
 Silk Market | 2026-2036
Silk Market Size, Share, and Industry Trends Forecast 2026-2036
Silk Market Intelligence
Venture capital investment into synthetic biology platforms is fragmenting the traditional sericulture-based supply landscape. This dynamic allows technology-focused firms like Spiber Inc. and Bolt Threads to compete on material performance against established producers. Meanwhile, large state-affiliated entities such as China National Silk Import & Export Corporation sustain market control through immense scale and integrated supply chains. Kraig Biocraft Laboratories differentiates by developing genetically engineered spider silk for high-strength technical applications.
Silk is a natural protein fiber, composed primarily of a fibroin core coated in sericin, which is produced by insect larvae like the silkworm Bombyx mori. Its unique combination of high tensile strength, excellent dye uptake, and characteristic luster makes it a premier material for luxury textiles and specialized biomedical applications. The apparel segment commands the largest share, while medical textiles represent a high-margin growth frontier due to silk's biocompatibility. Mulberry silk constitutes the bulk of commercial production, with wild silks like Tussar and Eri serving niche, high-value artisanal markets.
Quality and trade are shaped by national specifications like China's GB standards for raw silk and international labeling laws. The EU's REACH regulation restricts certain chemicals in dyeing and finishing, affecting market access for textile manufacturers. In the United States, the FDA evaluates the safety and biocompatibility of silk-based materials for medical devices. Producers must navigate this complex web of standards to secure access to diverse international end-use markets.
Market Dynamics
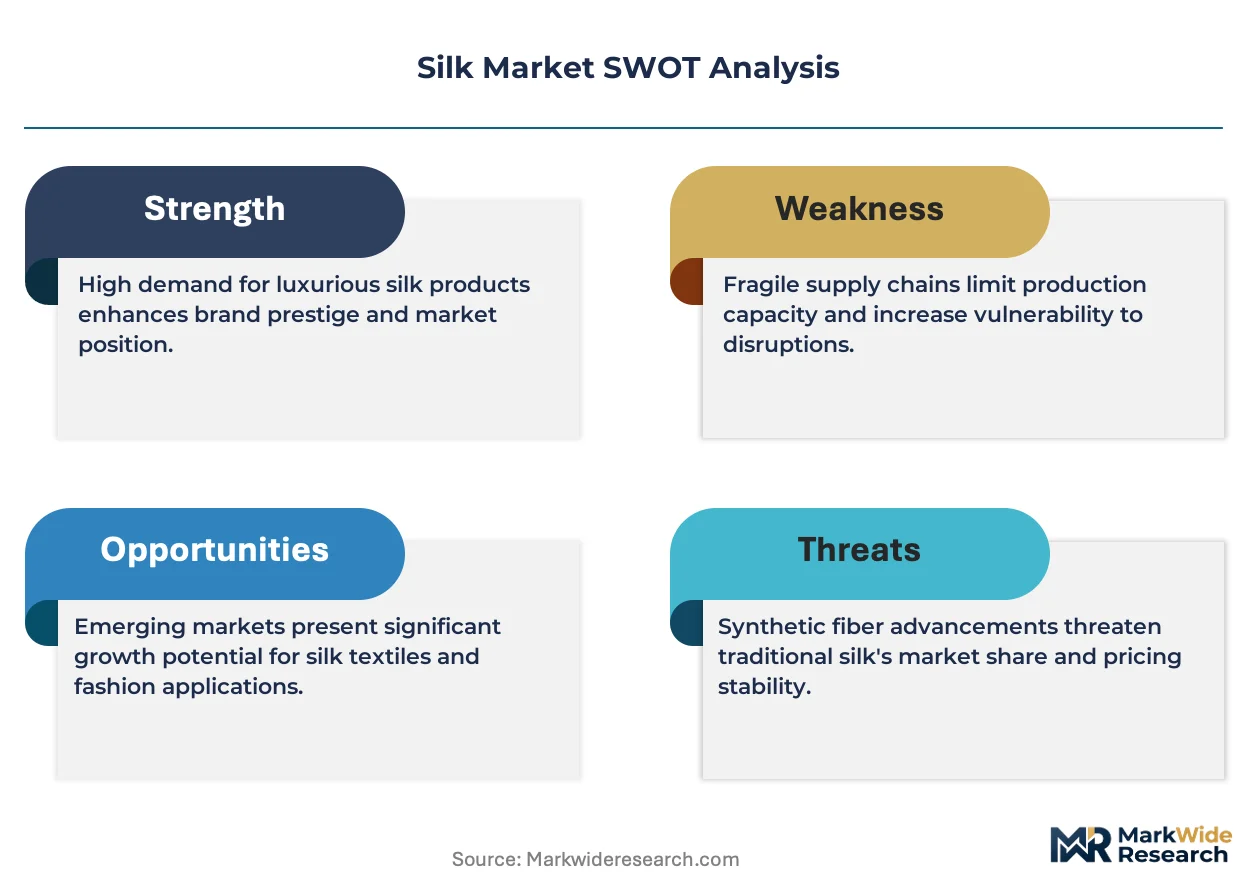
The central dynamic shaping the silk market is the competitive friction between traditional, agriculture-based sericulture and emerging biosynthetic production platforms. This tension creates a bifurcated landscape where material performance and supply chain technology, not just origin, define value.
Growth Catalysts
- Medical Sector Adoption:The inherent biocompatibility and degradability of silk fibroin propel its use in high-value medical applications, including dissolvable sutures, drug delivery systems, and scaffolds for tissue engineering.
- Luxury Goods Consumption:Sustained demand for premium apparel and home textiles in fashion-centric economies, particularly China and India, supports volume and value growth in the high-end mulberry silk segment.
- Biosynthetic Innovation:Advances in fermentation and genetic engineering are creating novel silk variants with enhanced properties like superior strength or elasticity, opening new markets in technical textiles and performance wear.
Market Restraints
- Input Cost Volatility:The sericulture industry's dependence on mulberry cultivation makes raw silk prices susceptible to agricultural risks, including climate change, disease, and land-use competition, creating price instability.
- Substitution from Synthetics:Lower-cost synthetic fibers such as polyester, nylon, and rayon present a significant substitution threat in mass-market apparel, competing directly on price and functional attributes like easy care.
- Regulatory Compliance Burden:Stringent chemical regulations, notably the EU's REACH framework, impose significant compliance costs and market access hurdles for textile dyers and finishers, particularly for smaller producers.
Strategic Opportunities
- Non-Mulberry Silk Promotion:Marketing wild silks like Tussah and Eri based on their unique textures, natural colors, and sustainable, forest-based production narratives can capture niche premium and eco-conscious consumer segments.
- Smart Textile Integration:The development of conductive silk fibers presents an opportunity to create integrated e-textiles for health monitoring, wearable electronics, and other smart fabric applications.
- Circular Economy Models:Establishing scalable processes for recycling silk waste and post-consumer textiles into new fibers or other materials aligns with sustainability mandates and offers a new value stream.
Industry Challenges
- Quality Standardization Gaps:While mulberry silk has established grading systems like China's GB standards, wild and artisanal silks lack consistent international quality standards, hindering their trade and broader market acceptance.
- Intellectual Property Complexity:The landscape for biosynthetic and genetically engineered silks is crowded with patents, creating significant licensing hurdles and potential litigation risks for firms entering the space.
- Supply Chain Traceability:Verifying the authenticity, origin, and ethical production standards of raw silk across a fragmented global supply chain is a major operational challenge for brands making sustainability claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silk Market |
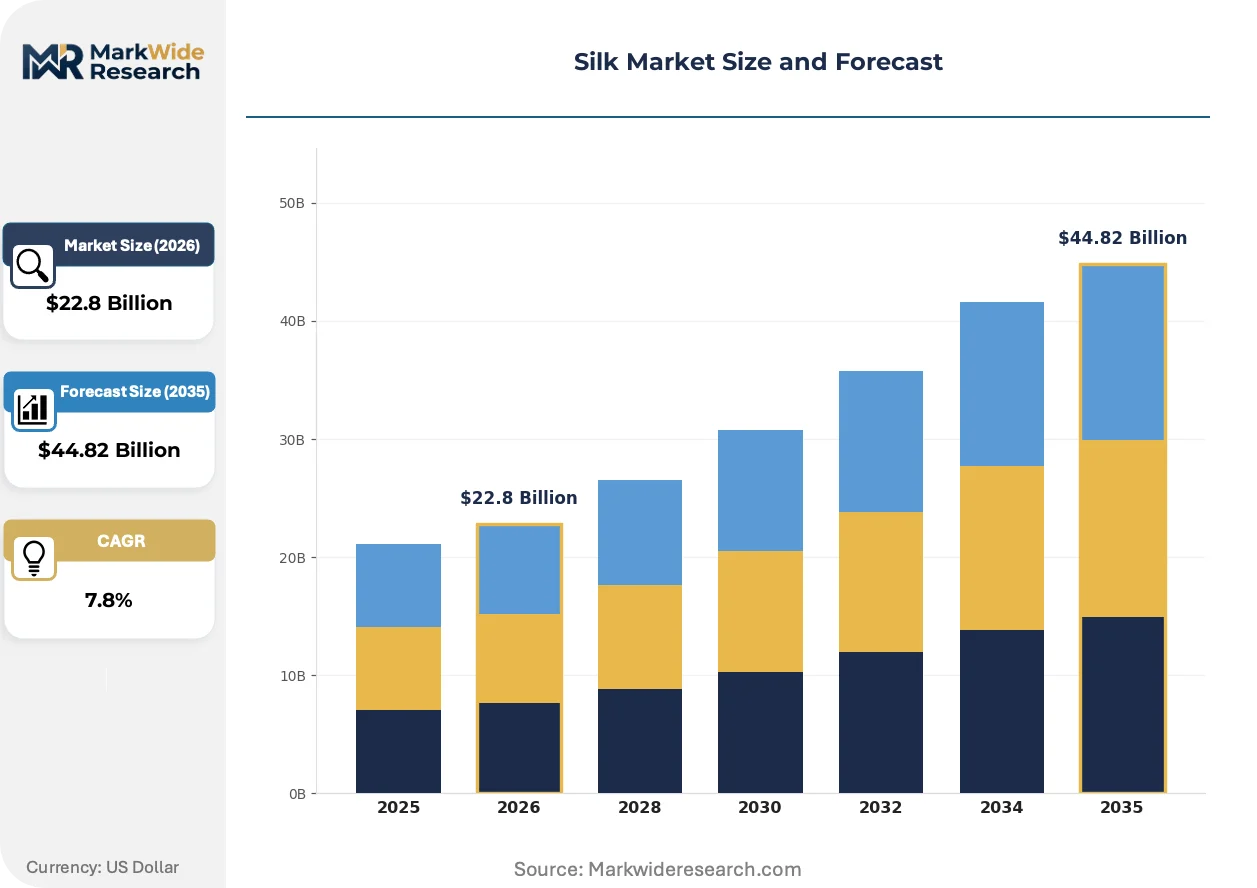
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $44.82 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mulberry Silk, Tussar Silk, Eri Silk, Muga Silk, Wild Silk Application: Apparel, Home Furnishings, Accessories, Industrial Textiles, Medical Textiles End User: Fashion Designers, Textile Manufacturers, Luxury Brands, Upholstery Companies Packaging Type: Reel Packaging, Box Packaging, Roll Packaging, Bulk Packaging |
| Companies Covered | Guangxi Huahong Silk Co. Ltd., Bolt Threads, Anhui Silk Co. Ltd., Kraig Biocraft Laboratories, Spiber Inc., China National Silk Import & Export Corporation, Jiangsu Soho International Group, Shengkun Silk Manufacturing Co. Ltd., Zhejiang Jiaxin Silk Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silk Market Strategic Shifts & Innovations
Material science and digital traceability are converging to redefine silk's value proposition. This shift moves the focus from purely aesthetic qualities to verifiable performance metrics and transparent, ethical sourcing narratives, influencing both production technology and consumer preference.
Technology and Product Evolution
Biosynthetic silk production, utilizing engineered microbes in fermentation processes, allows for the creation of fibers with tailored properties. Technical textile and performance sportswear manufacturers are among the earliest adopters, seeking materials with specific strength-to-weight ratios or elasticity. This technology is rendering obsolete the fixed material properties and agricultural dependencies of traditional sericulture for advanced industrial applications.
Regulatory and Policy Shift
The European Union's Corporate Sustainability Reporting Directive (CSRD) is a significant policy driver. It compels large companies to disclose detailed environmental and social impacts throughout their supply chains, including raw material sourcing. Luxury apparel and home furnishing brands are most directly affected, accelerating their investment in supply chain mapping and verification technologies to substantiate the origin and production methods of their silk.
Demand-Side and Behavioral Shift
Consumer purchasing criteria in luxury segments are evolving from a focus on brand and aesthetics to a demand for radical transparency. This behavioral change disrupts opaque, multi-tiered sourcing models by favoring suppliers who can provide verifiable proof of origin, often via QR codes or blockchain-based platforms. This trend is most pronounced in the North American and European markets for high-value goods like bridal gowns and premium textiles.
Silk Market Segmentation
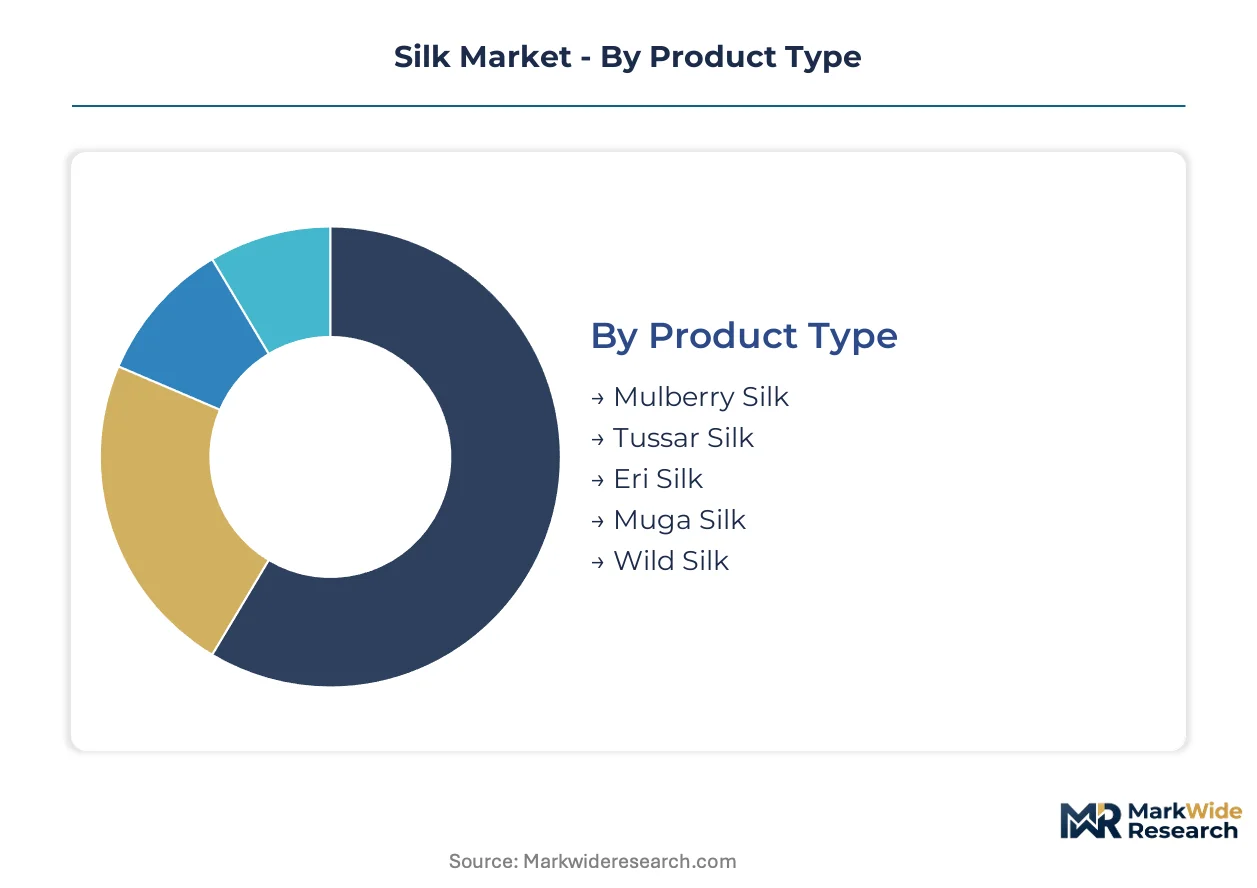
The silk market segments reflect the diverse origins, processing requirements, and end-use applications of this versatile natural fiber. Understanding these distinctions is crucial for identifying specific market opportunities and navigating the complex supply chains for both traditional and advanced silk materials.
Product Type:
The product type of silk significantly influences the intensity of required after-sales support, particularly regarding specialized care instructions and authenticity verification for high-value textiles.
- Mulberry Silk:This cultivated silk, produced by Bombyx mori silkworms fed exclusively on mulberry leaves, forms the backbone of commercial silk production due known for its smooth texture and uniform fibers. Demand concentrates in luxury apparel and high-end home furnishings across China and India due to its aesthetic appeal and dye uptake.
- Tussar Silk:A wild silk produced by Antheraea moths, Tussar silk is characterized by its rich texture and natural golden hue, offering a distinct aesthetic. Its demand is concentrating in artisanal fashion and sustainable textile markets in Europe and North America, driven by consumer preference for unique, natural fibers.
- Eri Silk:Known as peace silk, Eri is produced by Samia ricini and is harvested after the moth emerges, making it popular in cruelty-free textile segments.
- Muga Silk:This rare wild silk from Assam, India, boasts a natural golden sheen and exceptional durability, catering to niche, high-value traditional garments.
- Wild Silk:Encompasses various non-mulberry silks, offering unique textures and properties, often sourced for specialized textile applications and artisanal crafts.
Mulberry Silk holds the largest share; momentum sits with biosynthetic innovations and specialty wild silks.
Application:
Applications for silk fibers vary widely in their potential margin contributions, driven by processing complexity and end-product value.
- Apparel:Silk is a premier material for clothing, including dresses, shirts, scarves, and lingerie, valued for its luxurious feel, drape, and breathability. This segment generates substantial volume across fashion hubs in Milan, Paris, and New York, driven by consistent consumer demand for premium garments.
- Medical Textiles:Silk fibroin's biocompatibility and biodegradability make it ideal for surgical sutures, tissue engineering scaffolds, and drug delivery systems. Demand concentrates in advanced medical device manufacturing in the United States and Germany, propelled by research into regenerative medicine.
- Home Furnishings:Used in bedding, upholstery, curtains, and decorative items, silk adds elegance and comfort to interior spaces.
- Accessories:Scarves, ties, handbags, and jewelry often incorporate silk for its aesthetic appeal and soft texture.
- Industrial Textiles:Specialized silk fibers find use in niche industrial applications requiring high strength-to-weight ratios or specific electrical properties.
Apparel consistently generates the highest volume, while medical textiles are gaining share fastest due to specialized demand.
End User:
End-user segments exhibit distinct procurement patterns, reflecting their varying scale and quality requirements from the supply chain.
- Fashion Designers:These users source silk for creating high-end garments and collections, prioritizing unique textures, colors, and ethical sourcing narratives. Their demand is often for smaller, specialized batches of silk from various origins.
- Textile Manufacturers:This segment processes raw silk into fabrics and finished goods, requiring consistent quality and large-volume supply for mass production. Procurement patterns focus on cost-efficiency and reliable supply chains from major producing countries like China.
- Luxury Brands:These entities demand premium, often traceable, silk for their exclusive product lines, emphasizing brand heritage and superior material quality.
- Upholstery Companies:These companies utilize silk for high-end furniture and interior design projects, valuing durability and aesthetic appeal.
Textile manufacturers represent the largest volume purchasers, with luxury brands commanding premium sourcing.
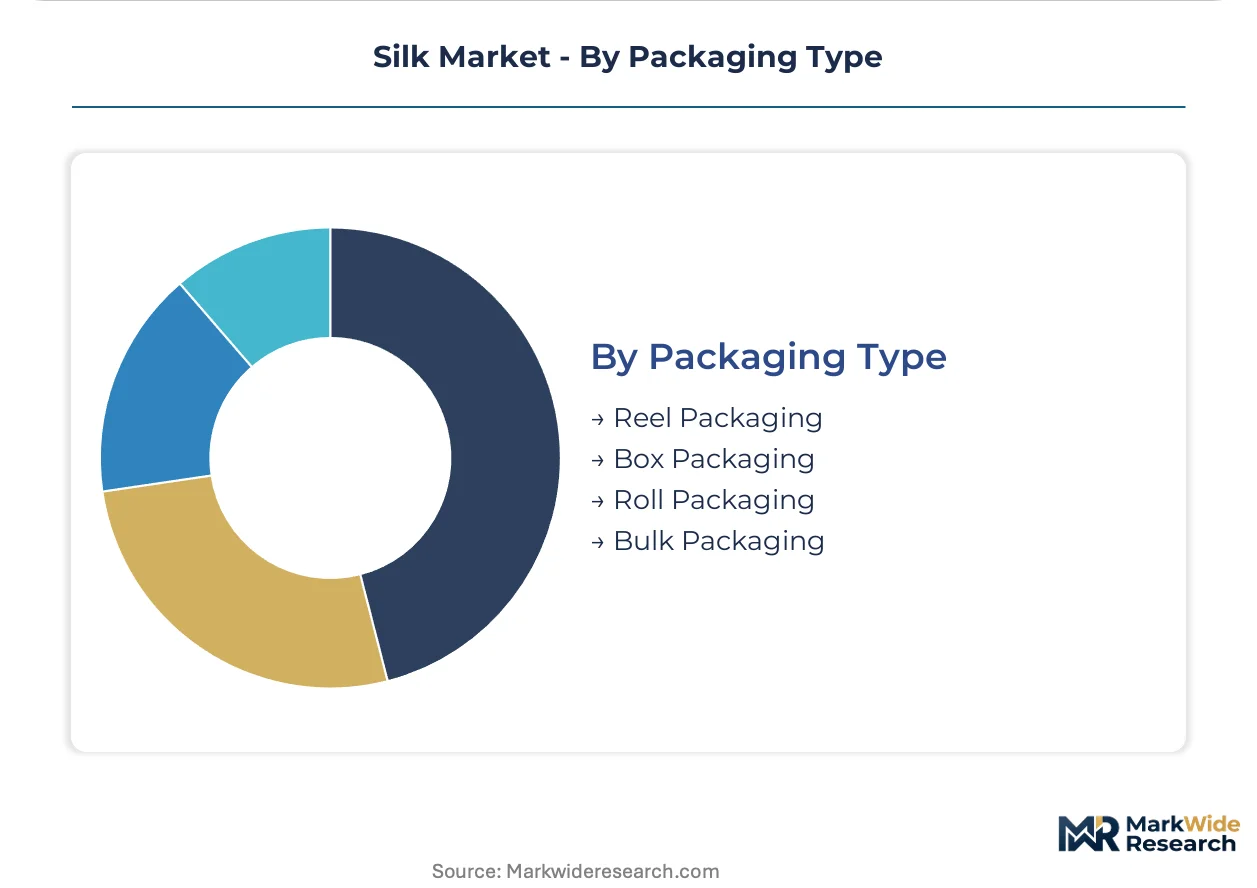
Packaging Type:
The packaging type for silk raw materials is primarily dictated by volume requirements and downstream processing needs.
- Reel Packaging:Raw silk is often wound onto reels after reeling from cocoons, preserving its continuous filament structure and preventing tangling. This packaging is standard for high-quality reeled silk destined for weaving and knitting.
- Box Packaging:Processed silk, such as spun silk yarn or silk waste, may be packed into boxes for protection during transport and storage. This method supports smaller quantities or specialty silk products.
- Roll Packaging:Finished silk fabrics are typically rolled onto tubes to prevent creases and maintain their integrity during shipping to apparel manufacturers and retailers.
- Bulk Packaging:Large quantities of raw silk, silk waste, or lower-grade silk are often transported in bulk containers or bales for industrial processing or further refinement.
Bulk packaging facilitates large-scale industrial use, with reel packaging supporting precision textile production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the silk market exhibits a significant asymmetry. Major producing nations like China often dictate raw material costs, while luxury consumption hubs in Europe command premium prices for finished goods. This dynamic creates varied opportunities and challenges across global regions.
China
China dominates global silk production and consumption, driven by its vast domestic luxury apparel and home furnishing demand. The nation's GB standards for raw silk uphold quality, influencing international trade. Zhejiang and Jiangsu provinces host major silk textile manufacturing clusters.
India
India's silk market thrives on robust domestic demand for traditional garments and premium apparel. Government initiatives like the PLI scheme support textile processing. Karnataka remains a primary hub for mulberry silk cultivation, while Assam specializes in unique Muga and Eri silks.
United States
The United States exhibits strong demand for silk in high-value medical textiles and luxury fashion. The FDA evaluates the safety and biocompatibility of silk-based medical device materials. Biotech clusters in Boston and the San Francisco Bay Area drive innovation in biosynthetic silk.
Germany
Germany presents significant demand for silk in advanced medical devices and high-end apparel. The EU's REACH regulation impacts chemical use in textile dyeing. Southern Germany, with its strong medical device industry, hosts research centers focused on silk fibroin applications.
France
France remains a global epicenter for luxury fashion and haute couture, driving premium silk consumption. The EU's Corporate Sustainability Reporting Directive influences supply chain transparency. Lyon maintains its historical significance as a silk weaving center, and Paris houses numerous luxury fashion houses.
Silk Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing raw materials and intermediate products. The silk market exhibits a bifurcated structure, split between traditional sericulture and innovative biosynthetic production. Key archetypes include large state-backed entities focused on scale, technology-focused firms pioneering novel silk variants, and artisanal producers targeting niche luxury segments. Dominant competitive moves involve strategic partnerships for technology transfer and capacity expansion in emerging production methods.
Specialists in advanced material science, such as Bolt Threads and Spiber Inc., exemplify the technology-focused firms driving biosynthetic silk innovation. These companies anchor the high-performance segment, developing novel material properties previously unavailable from traditional sources. Meanwhile, China National Silk Import & Export Corporation, a large state-affiliated entity, represents the established producers maintaining market control through immense scale and integrated supply chains. These players collectively shape the competitive dynamics across both traditional and emerging silk markets.
| Leading Market Players |
|---|
| Guangxi Huahong Silk Co. Ltd. |
| Bolt Threads |
| Anhui Silk Co. Ltd. |
| Kraig Biocraft Laboratories |
| Spiber Inc. |
| China National Silk Import & Export Corporation |
| Jiangsu Soho International Group |
| Shengkun Silk Manufacturing Co. Ltd. |
| Zhejiang Jiaxin Silk Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Undercapacity in specialized biosynthetic silk production drives supplier behavior and pricing posture for advanced applications. This limited supply enables technology-focused firms to command premium pricing for novel material properties, influencing downstream product development.
Pricing Analysis
Configured-to-order pricing for specialized silk variants commands a premium over standard commodity pricing. The dominant pricing structure is a hybrid of contract-based long-term offtake for large textile manufacturers and per-unit transactional pricing for luxury brands and medical device firms. Price differentiation drivers include quality grade, often aligned with China's GB standards, and authenticity verification for wild silks. Pricing softness stems from the substitution threat posed by lower-cost synthetic fibers in mass-market apparel. Mass-market apparel manufacturers are most price-sensitive, while medical device companies exhibit lower price sensitivity due to performance requirements.
Supply Chain Analysis
Contract-manufacturing concentration for traditional silk production resides heavily in China and India, which dominate raw silk output. The supply chain draws from primary inputs like mulberry leaves for sericulture and genetically engineered microbes for biosynthetic silks. A structural risk is commodity price volatility in mulberry cocoons due to agricultural risks. Distribution runs through multi-tiered networks for traditional textiles, often involving brokers and wholesalers, while specialized biosynthetic silks frequently use more direct channels to end-use manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents an early-cycle expansion story, primarily justified by the accelerating adoption of silk fibroin in high-value medical textiles.
For Market Incumbents: Entrench existing market share by investing in sustainable sericulture practices and promoting non-mulberry silks' unique attributes. Diversify product portfolios to mitigate the competitive threat from advanced biosynthetic silks. Reinforce integrated supply chains through digital traceability solutions to meet increasing transparency demands from regulators like the EU's CSRD. Emphasize quality standardization for traditional silks to maintain market trust.
For New Entrants and Emerging Players: Build out capabilities in advanced material science, focusing on novel silk variants with enhanced properties like superior strength or elasticity. Target white-space opportunities in smart textiles and performance wear, particularly in North American and European markets. A compelling go-to-market angle involves verifiable sustainability claims and performance data, appealing to eco-conscious consumers and technical textile manufacturers. Leverage intellectual property in genetic engineering to create differentiated products.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among firms integrating silk-based biomaterials into medical devices or specialized technical applications. The long-term viability over the next 5-10 years favors firms with strong intellectual property portfolios in biosynthetic silk production and advanced processing technologies. Target acquisition archetypes include technology-focused firms like Spiber Inc. or Kraig Biocraft Laboratories. The signal to watch is the rate of FDA approvals for silk-based medical devices, indicating broader market acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Biosynthetic Capacity Expansion | Increases supply of novel silk variants for technical textiles and medical applications. |
| Supply Chain Traceability Investment | Ensures compliance with EU CSRD and meets consumer demand for ethical sourcing. |
| Non-Mulberry Silk Branding | Captures niche premium and eco-conscious consumer segments in Europe and North America. |
| R&D in Smart Textile Integration | Unlocks new applications for conductive silk fibers in health monitoring and wearable electronics. |
| Strategic Partnerships for Medical Devices | Accelerates market penetration of silk fibroin in high-value surgical and tissue engineering uses. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary data sources anchors the qualitative findings. This involved discussions with textile manufacturers, fashion designers, medical device engineers, and sericulture farmers. Secondary validation drew from national silk standards like China's GB, EU REACH guidelines, FDA evaluations, and trade association reports. The approach employed bottom-up and top-down triangulation to ensure data accuracy.
The calibration approach integrated historical data with projected market shifts across the analysis window. Segmentation dimensions modeled included product type, application, end-user, packaging type, and regional production dynamics. Compound annual growth rates were derived from historical trends and anticipated shifts in consumption patterns and technological adoption. Luxury goods consumption trends and biosynthetic production capacity served as key industry-specific forecast inputs.
Practitioners should monitor climate change impacts on sericulture and rapid advancements in synthetic biology for early signals. Forecasts reflect assumptions regarding regulatory stability and consumer preferences. Quarterly review of raw material price volatility and new product introductions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Global Rattan Products Market
Natural Fibers
Acoustic Cotton Market
Natural Fibers
Global Cellulosic Man-Made Fibers Market
Natural Fibers
Organic Cotton Market
Natural Fibers
Down and Feather Market
Natural Fibers
Natural Cotton Extract Market
Natural Fibers
Global Alpaca Fiber Market
Natural Fibers
North America Lyocell Fiber Market
Natural Fibers
Lignocellulosic Fibers Market
Natural Fibers
Eco Fibers Market
Natural Fibers
Wood-Based Fibers Market
Natural Fibers
Apple Fiber Market
Natural Fibers
Sugarcane Fiber Market
Natural Fibers
Natural Fibers Market
Natural Fibers
Cashmere Clothing Market
Natural Fibers
Gum Fiber Market