
 Modal Fiber Market | 2026-2036
Modal Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Modal Fiber Market Intelligence
Direct-to-brand fiber supply agreements is tilting toward vertically integrated producers with captive pulp sources. Lenzing AG leverages its TENCEL Modal trademark to command premium positioning in European luxury apparel. Aditya Birla Group anchors South Asian supply through Grasim Industries Limited's integrated viscose and modal complexes in India. Sateri competes on scale from its Chinese facilities, while Toray Industries extends its technical fiber expertise into high-performance modal blends for Japanese athletic wear brands.
Modal fiber is a regenerated cellulose textile produced through the viscose process using beechwood or other hardwood pulp, yielding filaments with higher wet tenacity and softer hand feel than standard viscose rayon. The manufacturing employs a multi-step cellulose xanthate route with controlled stretch orientation to achieve tenacities exceeding 3.5 cN/dtex in wet conditions, primarily serving premium apparel and home textile applications where drape and moisture absorption matter. Apparel applications lead volume absorption, while athletic wear represents the fastest-expanding end-use pool as moisture-management specifications harden. Staple fiber dominates form-based shipments, though lyocell blends capture widening interest from spinners seeking to reduce water intensity in downstream processing.
REACH in Europe and China's GB 18401 national textile safety standard impose escalating chemical residue limits on modal fiber imports, forcing producers to certify APEO-free and low-sulfur processing. The EU Green Deal's textile strategy accelerates pressure for fiber-level traceability and recycled content claims, while India's BIS certification requirements for textile imports create additional compliance gates for cross-border suppliers. Stakeholders must monitor how pulp cost volatility and evolving biodegradability certifications reshape sourcing economics across integrated and merchant fiber producers.
Market Dynamics
Integrated pulp-to-fiber operations in China's Zhejiang and Shandong provinces are compressing cost structures and forcing merchant producers to secure captive beechwood supplies or exit premium segments entirely.
Growth Catalysts
- EU Green Deal textile strategy:Mandates for fiber-level traceability and recycled content claims are pulling modal fiber into circular supply chains ahead of synthetic alternatives.
- Athletic wear moisture specifications:Performance brands are hardening wet-tenacity requirements that modal's 3.5 cN/dtex specification satisfies more reliably than standard viscose.
- REACH chemical disclosure tightening:APEO-free and low-sulfur processing certifications are creating compliance moats for producers who invested early in closed-loop chemistry.
Market Restraints
- Beechwood pulp cost volatility:Hardwood fiber supply concentrates in European and North American temperate forests, exposing margin structures to weather-driven harvest disruptions.
- Lyocell substitution pressure:Lower-water-intensity lyocell processes are capturing spinner interest in segments where modal previously held default position.
- India BIS certification gates:Cross-border suppliers face additional testing timelines and documentation burdens for textile imports into South Asian markets.
Strategic Opportunities
- GB 18401 compliance arbitrage:China's escalating national textile safety standard creates first-mover advantage for producers with certified low-residue processing infrastructure.
- Lyocell-modal blend innovation:Spinners seeking water reduction in downstream processing are opening formulation white space between pure fiber categories.
- Home textile pivot:Drape and moisture-absorption specifications in premium bedding and bath segments remain underpenetrated relative to apparel saturation.
Industry Challenges
- Cellulose xanthate process expertise:Controlled stretch orientation requires specialized chemical engineering talent that aging workforces in traditional viscose regions struggle to replenish.
- Biodegradability certification complexity:Competing industrial and marine biodegradability standards create testing duplication costs for producers seeking multi-jurisdiction product claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modal Fiber Market |
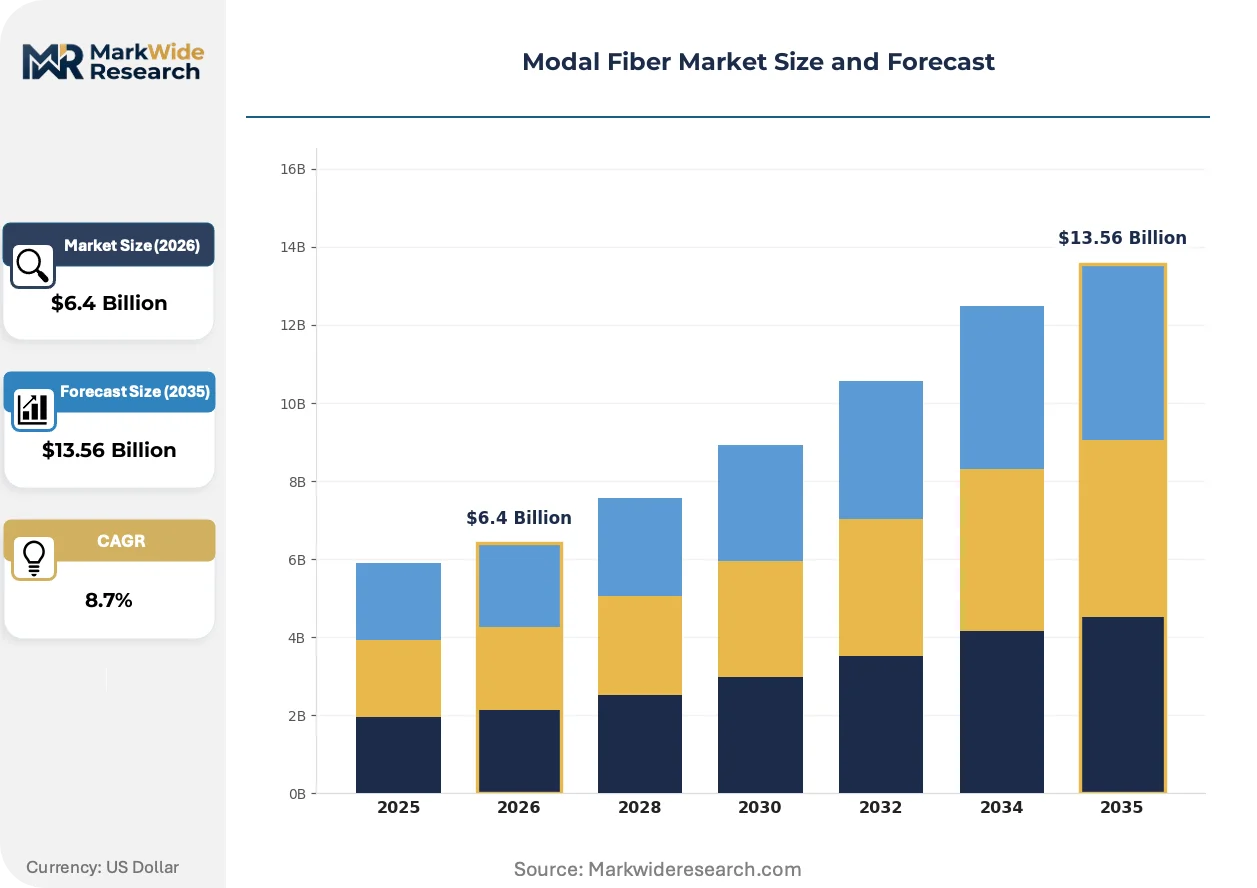
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $13.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textiles, Home Furnishings, Apparel, Non-Wovens End Use: Fashion, Athletic Wear, Underwear, Home Decor Form: Filament, Staple Fiber, Lyocell Blends, Yarn Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Zhejiang Fulida Holding Co., Ltd., Nanollose, Lenzing AG, Aditya Birla Group, Toray Industries, Sateri, Asia Pacific Rayon Limited, China Bambro Textile, Grasim Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modal Fiber Market Strategic Shifts & Innovations
Digital traceability infrastructure and closed-loop chemistry advances are restructuring how fiber provenance is verified and valued across premium supply chains.
Blockchain-based fiber provenance tracking is virtualizing the chain-of-custody documentation that previously required paper certificates and third-party audits. Luxury apparel houses in Milan and Paris are mandating lot-level digital passports for modal inputs. This technology is virtualizing the role of traditional textile certification bodies by embedding verification directly into supply chain software.
REACH Annex XVII restrictions on N-methylmorpholine-N-oxide residues are tightening testing protocols for European market access. The regulation forces producers to retool solvent recovery systems or risk import detention at Rotterdam and Hamburg ports. German technical textile spinners are responding by consolidating supplier lists to entities with demonstrated ECHA compliance histories.
Direct-to-brand supply contracting is displacing merchant fiber trading in premium segments. Athletic wear houses in Japan and South Korea are negotiating multi-year offtake agreements with named producers rather than spot-market purchases. This pattern concentrates procurement leverage with vertically integrated suppliers who control pulp origination.
Modal Fiber Market Segmentation
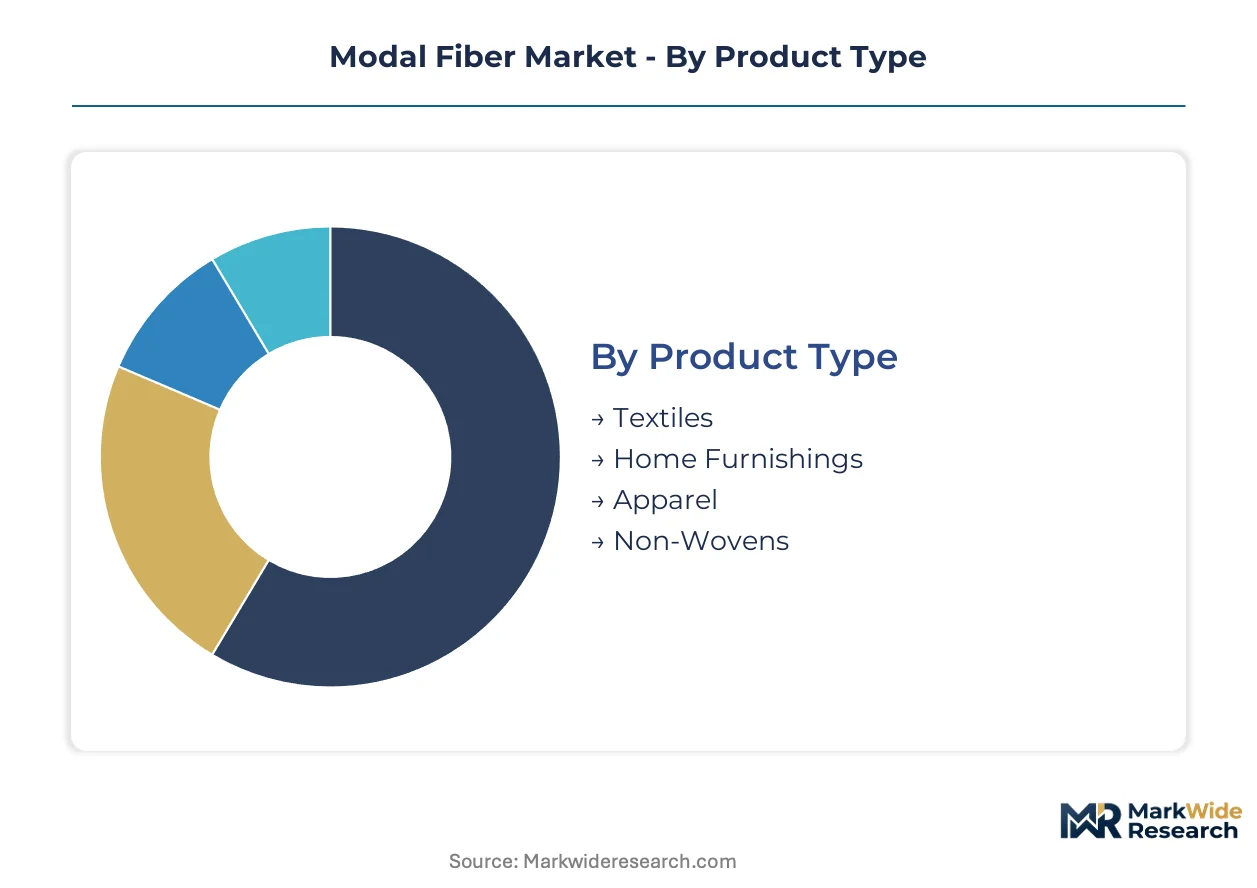
Modal fiber demand fragments across four distinct segmentation axes, each revealing how material specifications and channel economics reshape procurement patterns. Product type and end-use segmentation expose where wet-tenacity premiums command pricing power, while form and distribution channel splits illuminate downstream processing preferences and brand access strategies.
Product Type:
Maturity varies sharply across applications, with established apparel categories defending volume against emerging technical textile formats.
- Textiles:Broad woven and knitted fabric applications span dress shirts, blouses, and lightweight suiting where modal's 50% higher wet strength than standard viscose justifies fiber premiums. Mills in Zhejiang province concentrate output for European luxury houses requiring REACH-certified APEO-free processing.
- Apparel:Cut-and-sew garment production absorbs the largest fiber volumes, particularly in women's casual wear where drape and moisture absorption drive specification. Athletic wear brands in Japan and South Korea are hardening wet-tenacity requirements that modal's 3.5 cN/dtex specification satisfies more reliably than cotton blends.
- Home Furnishings:Premium bedding and bath segments exploit superior moisture management in sheet sets and towel collections. Italian and German retailers specify certified low-sulfur processing for skin-contact applications.
- Non-Wovens:Hygiene and medical wipe applications leverage modal's biodegradability credentials against petroleum-based alternatives. German technical textile producers consolidate supplier lists to entities with demonstrated ECHA compliance histories.
Apparel retains volume leadership; athletic wear within that category holds the steepest expansion curve.
End Use:
Application economics separate premium moisture-management specifications from commodity replacement markets.
- Athletic Wear:Performance brands specify modal for base layers and training apparel where sweat-wicking and shape retention under repeated washing justify fiber cost premiums. Japanese athletic wear houses negotiate multi-year offtake agreements with named producers rather than spot-market purchases.
- Underwear:Intimate apparel brands exploit modal's softer hand feel and reduced pilling versus cotton for premium lingerie and loungewear lines. French and Italian luxury houses mandate lot-level digital passports for fiber inputs.
- Fashion:Ready-to-wear collections incorporate modal for fluid drape in dresses and separates targeting mid-market positioning. Chinese fast-fashion retailers source through wholesale channels with less stringent provenance documentation.
- Home Decor:Curtain and upholstery applications remain underpenetrated relative to apparel saturation, though premium residential markets in Germany and Switzerland specify modal for natural-fiber content claims.
Underwear commands the highest fiber premiums per kilogram; athletic wear is gaining share fastest among end-use categories.
Form:
Processing requirements and water intensity differentiate fiber formats competing for spinner attention.
- Staple Fiber:Short-cut fibers for cotton-system spinning dominate shipment volumes, serving ring-spun and open-end yarn production across apparel and home textile mills. Integrated pulp-to-fiber operations in Shandong province compress cost structures for this commodity-grade output.
- Lyocell Blends:Spinner formulations combining modal with lower-water-intensity lyocell capture widening interest from processors seeking to reduce effluent treatment burdens. German technical textile spinners are consolidating supplier lists to entities with demonstrated closed-loop chemistry capabilities.
- Filament:Continuous-fiber forms serve warp-knitting and weaving applications requiring strength with minimal twist. Italian hosiery producers specify filament modal for sheer hosiery and seamless garment production.
- Yarn:Pre-spun packaged yarns target smaller cut-and-sew operations lacking in-house spinning capacity. Indian BIS certification requirements for textile imports create additional compliance gates for cross-border yarn suppliers.
Staple fiber retains volume leadership; lyocell blends hold the steepest expansion curve.
Distribution Channel:
Channel concentration reflects how brand scale and certification requirements filter fiber access.
- Wholesale:Merchant fiber trading through distributors and agents serves mid-tier mills lacking direct producer relationships. This channel is losing share as athletic wear houses consolidate procurement leverage with vertically integrated suppliers.
- Specialty Stores:Curated fiber selections for boutique spinners and artisan weavers emphasize certified sustainable sourcing with full provenance documentation. Swiss and Austrian producers leverage specialty channel positioning for premium pricing.
- Online Retail:Digital platforms for small-lot fiber procurement serve independent designers and startup apparel brands. Blockchain-based fiber provenance tracking is virtualizing chain-of-custody documentation previously requiring paper certificates.
- Supermarkets:Mass-market retail channels for consumer-facing textile products carry limited modal content, primarily in private-label bedding and basic apparel where price positioning restricts fiber specification.
Wholesale retains volume leadership; online retail holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites European modal fiber import flows, while Shanghai Yangshan深水港 anchors Asia-Pacific pulp-to-fiber logistics. Integrated cellulose processing clusters in Zhejiang and Shandong provinces feed global supply chains through these maritime gateways.
China
Integrated pulp-to-fiber operations in Zhejiang and Shandong provinces compress production economics for staple fiber output. GB 18401 national textile safety standards impose escalating chemical residue limits on domestic producers. Sateri and Asia Pacific Rayon Limited operate captive facilities near Ningbo and Rizhao, leveraging backward integration into dissolving pulp supply.
Germany
Technical textile spinners in Baden-Württemberg consolidate supplier lists to entities with demonstrated ECHA compliance histories. REACH Annex XVII restrictions on N-methylmorpholine-N-oxide residues tighten testing protocols for fiber imports. The Rhine-Ruhr industrial corridor hosts specialized chemical engineering talent for cellulose xanthate process optimization.
India
Grasim Industries Limited anchors South Asian supply through integrated viscose and modal complexes in Gujarat and Maharashtra. BIS certification requirements for textile imports create additional compliance gates for cross-border suppliers. The Mumbai-Pune industrial belt concentrates downstream spinning capacity for premium apparel exports.
Japan
Athletic wear houses in Osaka and Tokyo negotiate multi-year offtake agreements with named producers rather than spot-market purchases. METI industrial standards guide moisture-management specifications for performance apparel. Toray Industries extends technical fiber expertise into high-performance modal blends from Nagoya-area facilities.
Austria
Lenzing AG leverages its TENCEL Modal trademark to command premium positioning in European luxury apparel. The EU Green Deal textile strategy mandates fiber-level traceability that Austrian producers embed through blockchain-based provenance systems. Upper Styria's forest-products industrial cluster supports captive beechwood pulp sourcing for regenerated cellulose output.
Modal Fiber Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in pulp supply and downstream in technical spinning. The vendor base organizes around three strategic archetypes: vertically integrated forest-products conglomerates with captive pulp sources, specialty chemical engineers focused on closed-loop solvent recovery, and scale-driven Asian producers competing on throughput. Consolidation pressures favor backward integration into hardwood fiber supply, while regulatory compliance investments create moats for early movers in APEO-free processing.
Within the integrated pulp-to-fiber tier, Lenzing AG and Grasim Industries Limited exemplify the captive-resource archetype, leveraging forest-products heritage into premium fiber positioning. Sateri anchors the scale-driven segment, representing Chinese producers competing through Zhejiang and Shandong province concentration. Among technology-forward specialists, Toray Industries occupies a position bridging technical textile expertise with athletic wear application development.
| Leading Market Players |
|---|
| Zhejiang Fulida Holding Co., Ltd. |
| Nanollose |
| Lenzing AG |
| Aditya Birla Group |
| Toray Industries |
| Sateri |
| Asia Pacific Rayon Limited |
| China Bambro Textile |
| Grasim Industries Limited |
| Others |
Cost & Logistics Intelligence
Zhejiang province's integrated pulp-to-fiber clusters concentrate capacity that shapes downstream pricing power for premium modal grades. Merchant producers without captive beechwood supply face margin compression as integrated operators leverage upstream control over dissolving pulp origination.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified APEO-free fiber from commodity-grade output. Price differentiation rests on certification tier and volume scale, with luxury apparel houses paying premiums for lot-level traceability. Pricing pressure stems from lyocell substitution in moisture-management applications where spinners seek lower water intensity. Athletic wear brands show least price sensitivity due to hardening wet-tenacity specifications, while fast-fashion retailers drive commoditization in undifferentiated staple fiber.
Supply Chain Analysis
Extended payment terms from integrated Chinese producers are restructuring working capital requirements for European spinners. Geographic supply concentration centers on China, India, and Austria, with raw material dependencies on European and North American temperate hardwood forests. Supply chain risk hinges on weather-driven harvest disruptions in beechwood pulp sourcing. Distribution runs through direct-to-brand contracting displacing merchant fiber trading in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modal fiber markets reward service-attach strategies where certified processing and digital provenance systems expand faster than base fiber commoditization. Recurring revenue from compliance documentation and blockchain-based chain-of-custody verification outpaces hardware margins in premium tiers.
For Market Incumbents: Insulate premium positioning by deepening captive beechwood supply through forestry concessions in European temperate zones. Accelerate APEO-free and low-sulfur processing certification to exploit REACH compliance moats. Consolidate procurement leverage with athletic wear houses through multi-year offtake structures that lock in volume.
For New Entrants and Emerging Players: Build out lyocell-modal blend capabilities to capture spinner interest in water-reduction formulations. Target home furnishings segments in German and Swiss premium residential markets where drape specifications remain underpenetrated. Lead with certified sustainable sourcing credentials to access specialty store channels demanding full provenance documentation.
For Investors and Strategic Acquirers: Long-term, this sits as a compliance-infrastructure play because regulatory tightening across REACH, GB 18401, and BIS certification creates durable competitive moats for early movers. Acquisition focus centers on integrated producers with demonstrated ECHA compliance histories and closed-loop chemistry capabilities. Monitor lyocell process cost curves as inflection signal for substitution pressure timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hardwood Forestry | Captive beechwood supply from Upper Styria or European temperate forests secures pulp cost stability. |
| Closed-Loop Chemistry Certification | APEO-free processing investment satisfies REACH Annex XVII and GB 18401 residue limits simultaneously. |
| Digital Provenance Infrastructure | Blockchain-based fiber passports embed verification directly into supply chain software for Milan and Paris luxury houses. |
| Lyocell-Modal Blend Development | Formulation innovation addresses spinner demand for water-intensity reduction in downstream processing. |
| Direct-to-Brand Supply Contracting | Multi-year offtake agreements with Japanese athletic wear houses displace spot-market merchant trading. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with fiber producers, textile mill procurement directors, and athletic wear supply chain managers; and secondary validation through customs trade records, ECHA registration databases, and SEC filings from listed forest-products conglomerates. Bottom-up fiber shipment estimates triangulated against top-down apparel production data across the analysis window.
Forecast inputs span product type, end-use application, fiber form, and distribution channel segmentation. CAGRs derive from elasticity-adjusted demand modeling incorporating pulp cost volatility and regulatory compliance investment cycles. Industry-specific inputs include wet-tenacity specification hardening in athletic wear and biodegradability certification complexity across competing standards.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by scale-driven Chinese producers or rapid lyocell cost reduction would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Cashmere Clothing Market
Natural Fibers
Cellulose Market
Natural Fibers
North America Cotton Market
Natural Fibers
Abaca Fiber Market
Natural Fibers
North America Lyocell Fiber Market
Natural Fibers
Silk Fabric Market
Natural Fibers
Green Fibers Market
Natural Fibers
Asia-Pacific Alpaca Fiber Market
Natural Fibers
Thailand Textile Market
Natural Fibers
Natural Cotton Extract Market
Natural Fibers
Acoustic Cotton Market
Natural Fibers
Woolen Textiles Market
Natural Fibers
Natural Fibers Market
Natural Fibers
Acacia Fiber Powder Market
Natural Fibers
Organic Cotton Market
Natural Fibers
Global Rattan Products Market