

Bamboo Fiber Tableware and Kitchenware Market Size, Share, and Industry Trends Forecast 2026-2036
Bamboo Fiber Tableware and Kitchenware Market Insights
Food-grade certification tiers are rotating toward commercial compostability standards as the baseline for market entry. Bambu leverages its direct farm partnerships to secure raw material traceability. EcoSouLife anchors its position through Australian retail channel control. Huhtamaki competes via manufacturing scale across European converting facilities.
Bamboo fiber tableware and kitchenware denotes molded articles manufactured from pulverized bamboo cellulose bound with cornstarch, PLA, or rice husk composites, typically processed through heat-compression molding at temperatures between 120°C and 180°C to achieve structural rigidity for single-use and limited-reuse food service applications. The material composition segment stratifies around bamboo-cornstarch blends occupying the volume core due to cost parity with conventional plastics, while bamboo-PLA formulations command premium placement in certified composting infrastructure markets. The end use segment shows catering services and food trucks outpacing household adoption because commercial operators face direct regulatory pressure and waste disposal cost exposure.
The EU Single-Use Plastics Directive and EFSA food contact material standards constrain melamine-containing formulations while accelerating pure bamboo fiber and PLA-blend approvals. REACH chemical compliance and Germany's national packaging ordinance create tiered market access where certified compostable products gain preferential shelf placement. Stakeholders must monitor evolving composting infrastructure certification reciprocity between national schemes.
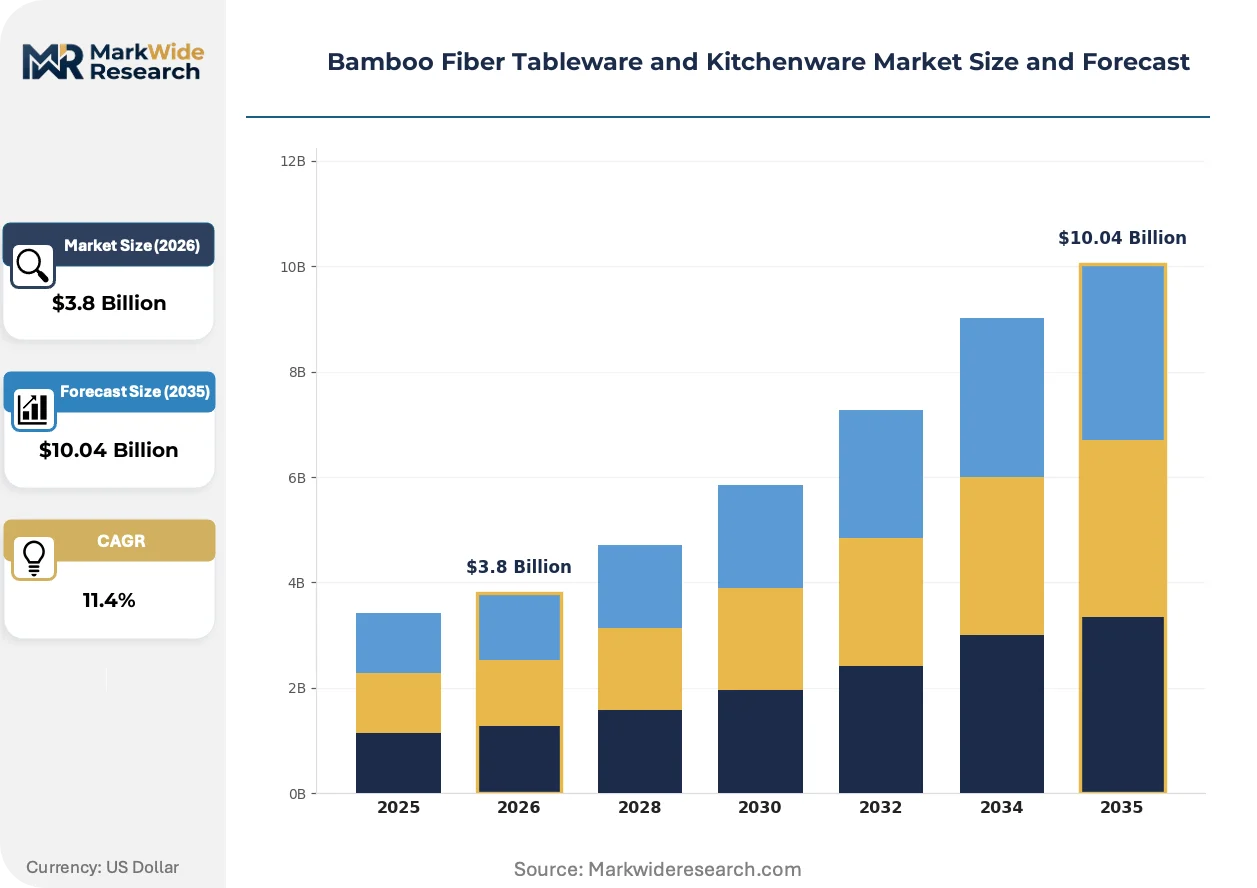
Market Dynamics
The EU Single-Use Plastics Directive is compressing demand for petroleum-based disposables while redirecting procurement budgets toward certified compostable alternatives, forcing converters to requalify their raw material slate.
Growth Catalysts
- Commercial compostability mandates:Germany's national packaging ordinance grants preferential shelf placement to certified compostable serveware, accelerating foodservice operator adoption.
- Bamboo-cornstarch cost parity:Heat-compression molding at 120°C to 180°C achieves unit economics matching conventional plastics for high-volume catering contracts.
- EFSA food contact approvals:Pure bamboo fiber and PLA-blend formulations gain regulatory clearance previously blocked to melamine-containing competitors.
Market Restraints
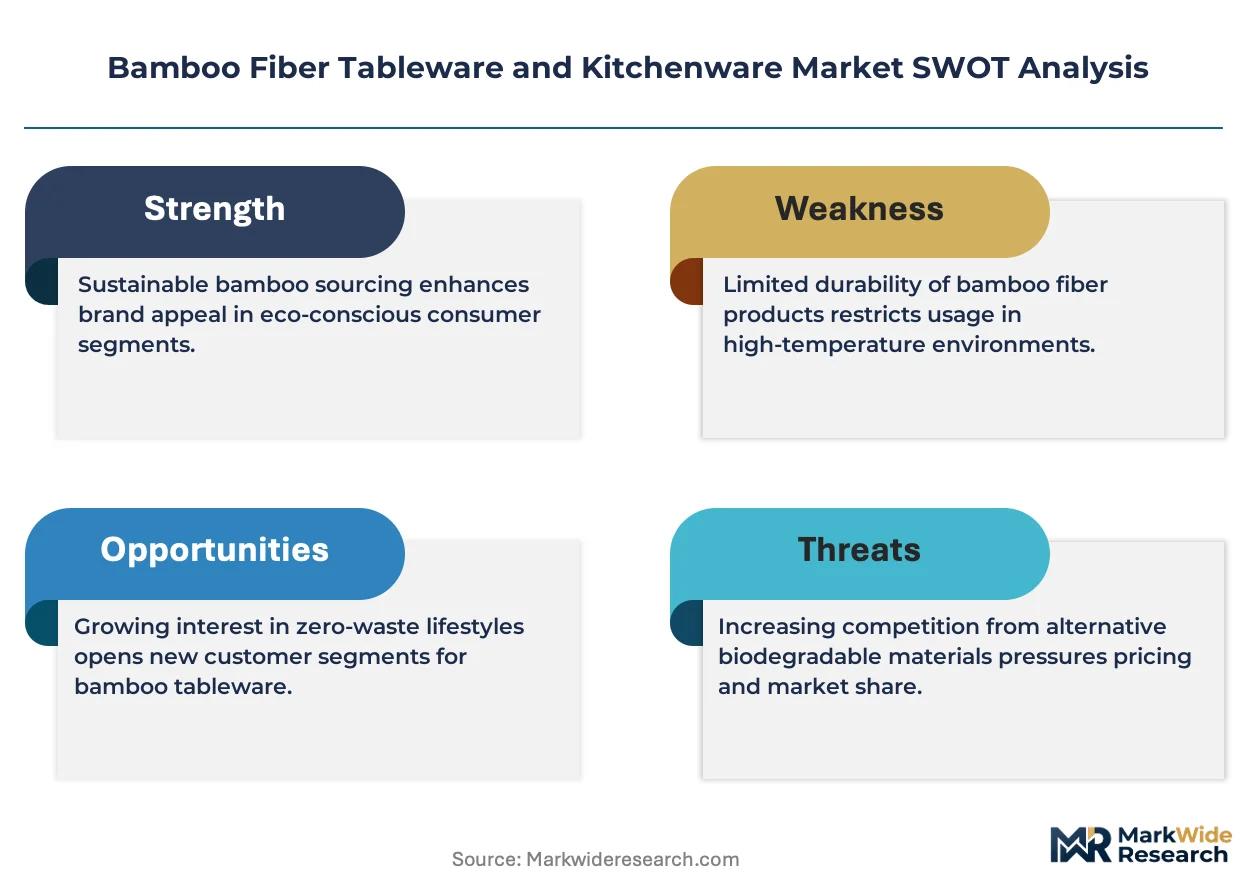
- Input cost volatility:Cornstarch pricing fluctuates with agricultural commodity cycles, squeezing margin on volume-core bamboo-cornstarch blends.
- Composting infrastructure gaps:Industrial composting facility density concentrates in Germany, France, and the Netherlands, leaving peripheral markets without end-of-life pathway assurance.
- Technical performance ceilings:Heat resistance above 100°C degrades structural integrity, excluding bamboo fiber from high-temperature food service applications.
Strategic Opportunities
- Australian retail channel control:Direct-to-supermarket distribution bypasses fragmented wholesaler networks, capturing household segment margin.
- Food truck regulatory exposure:Mobile food operators face municipal waste disposal levies that compostable serveware eliminates, creating pull-through demand.
- REACH chemical compliance tiering:Premium positioning accrues to melamine-free formulations that satisfy EFSA and REACH dual certification.
Industry Challenges
- Certification timeline compression:National composting scheme reciprocity remains unharmonized, forcing redundant testing for multi-country foodservice contracts.
- Heat-compression equipment capex:Mold fabrication and press installation require capital deployment ahead of volume commitments from risk-averse catering procurement.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bamboo Fiber Tableware and Kitchenware Market Trends and Innovations
Material science advances and regulatory chemistry constraints are jointly redefining acceptable formulation boundaries. Processors now compete on certification depth rather than price alone.
Heat-compression molding with rice husk composites is decomposing the traditional cost barrier between bamboo fiber and petroleum-based serveware. European converting facilities are retooling press lines to accommodate 150°C processing windows. The technology is decomposing incumbent plastic market share in German and Dutch catering supply chains.
REACH chemical compliance and EFSA food contact standards are constraining melamine-containing formulations while accelerating pure bamboo fiber approvals. Industrial consequence flows through to raw material procurement, where traceability documentation now gates supplier qualification. German packaging ordinance enforcement targets foodservice distributors with preferential procurement rules for certified compostable inventory.
Certification-driven preference shifts now dominate foodservice procurement evaluation. Catering operators and institutional buyers are displacing price-primary sourcing with compostability-standard compliance as the threshold qualification. French and Dutch municipal catering contracts embed industrial compostability certification as mandatory bid requirement.
Bamboo Fiber Tableware and Kitchenware Market Segmentation
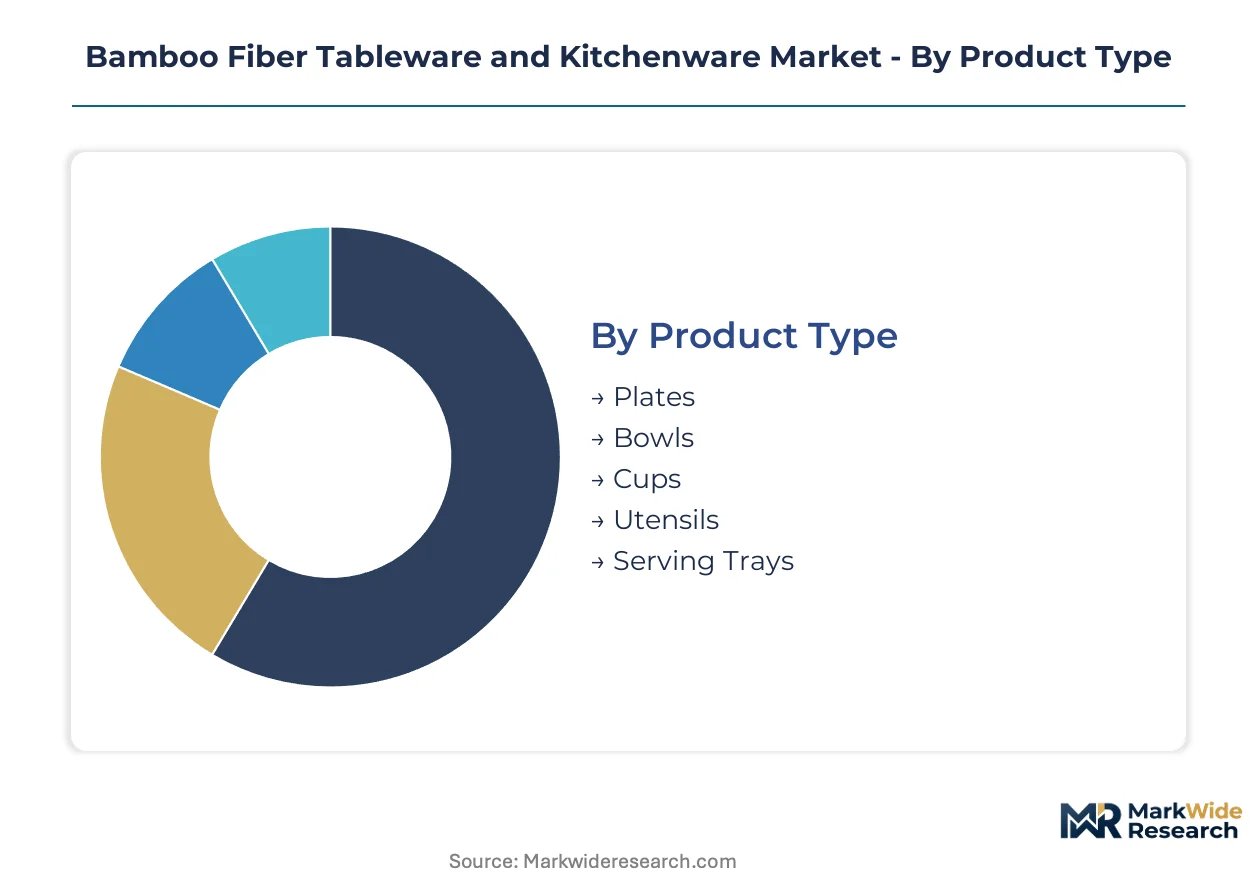
Segmentation in bamboo fiber tableware reveals how material composition and end-use requirements channel products through distinct procurement pathways. Foodservice operators prioritize certified compostable formulations, while household buyers respond to retail availability and price positioning. Understanding these segment-channel linkages exposes where margin concentrates and where volume scales.
Product Type:
Plates and bowls flow predominantly through foodservice wholesale channels, while cups and utensils reach household buyers via supermarket and online retail. Serving trays occupy a specialized catering procurement track with distinct volume economics.
- Plates:Molded cellulose structures with 180°C heat-compression rigidity serve high-volume catering contracts. German and French institutional buyers specify industrial compostability certification as mandatory bid threshold.
- Bowls:Deep-drawn formations with reinforced rim structures target soup and grain service applications. Demand concentrates in Netherlands cafe chains facing municipal waste disposal levies.
- Cups:Tapered wall designs with PLA-laminated interiors for liquid containment. Australian supermarkets stock these as household entry points.
- Utensils:Injection-molded cutlery sets with cornstarch binding for cost parity. Food trucks procure these through direct manufacturer relationships.
- Serving Trays:Large-format platters with rice husk composite reinforcement for structural load. Hotel banquet departments specify these for premium presentation tiers.
By volume, Plates leads. By growth pace, Cups is ahead.
Material Composition:
Cost tiering separates certified compostable formulations from legacy blends, with price positioning determining channel access and customer segment penetration.
- Pure Bamboo Fiber:Unblended cellulose with EFSA food contact approval and REACH chemical compliance. German packaging ordinance grants preferential shelf placement, accelerating foodservice adoption.
- Bamboo & Cornstarch Blend:Heat-compression molded at 120°C to 150°C achieving unit economics matching conventional plastics. Volume-core positioning in high-turnover catering supply chains.
- Bamboo & Melamine:Legacy formulation facing regulatory compression under EU chemical standards. Declining channel access as EFSA restrictions tighten.
- Bamboo & Rice Husk:Agricultural waste composite with reduced raw material cost exposure. Emerging tier for price-sensitive household segments.
- Bamboo & PLA:Biopolymer blend commanding premium in certified composting infrastructure markets. French municipal catering contracts embed this as mandatory specification.
Pure Bamboo Fiber captures the premium tier. Bamboo & Cornstarch Blend dominates volume throughput.
End Use:
Application-specific performance requirements and regulatory exposure create divergent procurement patterns across customer types.
- Household:Retail-dependent segment with Australian supermarket channel control capturing margin. EcoSouLife anchors position through direct-to-supermarket distribution bypassing fragmented wholesaler networks.
- Hotels:Banquet and room service applications with presentation-tier requirements. Premium positioning accrues to melamine-free formulations.
- Cafes:Front-of-house serveware with visible sustainability signaling. Netherlands and Germany lead adoption within European cluster.
- Catering Services:High-volume procurement with compostability-standard compliance as threshold qualification. Industrial composting facility density concentrates supplier selection.
- Food Trucks:Mobile operators facing municipal waste disposal levies that compostable serveware eliminates. Direct manufacturer sales channel dominates.
Catering Services generates highest volume velocity. Food Trucks is expanding most quickly.
Distribution Channel:
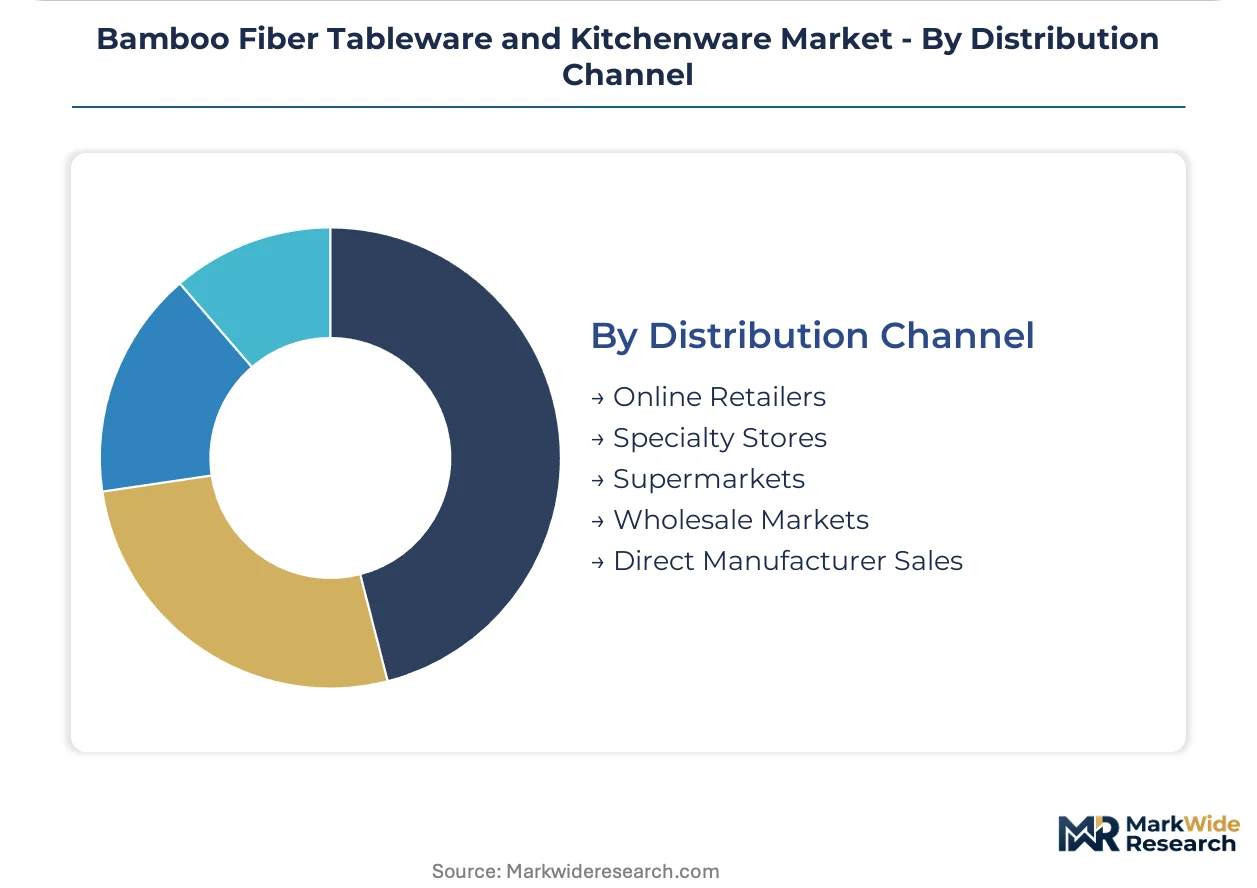
Channel control determines margin capture, with direct relationships displacing intermediary layers in high-volume segments.
- Online Retailers:Household segment access with subscription and bulk-purchase mechanics. Platform algorithms favor certified compostable product listings.
- Specialty Stores:Curated sustainability positioning with educational staff interaction. Premium pricing tolerance for EFSA-compliant formulations.
- Supermarkets:Mass-market household penetration with shelf placement fees determining visibility. Australian retail channel control demonstrates margin capture potential.
- Wholesale Markets:Foodservice volume aggregation with price-primary sourcing legacy. Compostability certification is displacing pure price comparison.
- Direct Manufacturer Sales:Catering and food truck procurement with volume commitment preceding capital deployment. Bambu leverages farm partnerships for traceability documentation.
Wholesale Markets still handles largest throughput. Direct Manufacturer Sales is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers dominate bamboo fiber tableware exports to European foodservice distributors, with containerized shipments routing through Rotterdam and Hamburg to reach continental buyers. Australian retail chains source directly from Southeast Asian converting facilities, bypassing traditional importer intermediaries.
Germany
Industrial composting infrastructure density in Bavaria and North Rhine-Westphalia enables end-of-life pathway assurance for catering procurement. The national packaging ordinance grants preferential shelf placement to certified compostable serveware, accelerating foodservice operator adoption. Berlin-Brandenburg hosts converting facilities retooling press lines for 150°C rice husk composite processing.
France
Municipal catering contracts in Île-de-France embed industrial compostability certification as mandatory bid requirement, displacing price-primary sourcing. EFSA food contact standards constrain melamine-containing formulations while accelerating pure bamboo fiber approvals. Lyon-based cafe chains drive front-of-house serveware adoption with visible sustainability signaling.
Netherlands
Amsterdam-Rotterdam corridor cafe operators face municipal waste disposal levies that compostable serveware eliminates, creating pull-through demand. REACH chemical compliance tiering rewards melamine-free formulations with premium positioning. Dutch food trucks procure direct from manufacturers to bypass fragmented wholesaler networks.
Australia
Supermarket channel control in New South Wales and Victoria captures household segment margin through direct-to-retail distribution. TGA food contact guidelines align with EFSA standards, smoothing import qualification for Southeast Asian converters. Melbourne-based specialty stores curate sustainability positioning with educational staff interaction.
United States
Food truck regulatory exposure in California and Texas creates demand for compostable serveware that eliminates municipal waste disposal levies. FDA food contact material standards intersect with state-level plastic bans in driving procurement shifts. Pacific Northwest institutional buyers specify certified compostable inventory for banquet and catering contracts.
Bamboo Fiber Tableware and Kitchenware Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and raw material traceability. The vendor base stratifies around manufacturing scale, farm partnership control, and retail channel ownership rather than pure price competition. Three archetypes dominate: integrated converters with captive raw material sourcing, brand houses with supermarket distribution lock, and contract manufacturers serving private-label programs. Capacity expansion and certification reciprocity partnerships constitute the dominant competitive moves as procurement shifts toward mandatory compostability compliance.
Within the farm-partnership archetype, Bambu exemplifies upstream control through direct agricultural relationships that gate supplier qualification with traceability documentation. EcoSouLife anchors the retail-channel tier, occupying a position built on Australian supermarket distribution that bypasses fragmented wholesaler networks. Huhtamaki sits within the scale-driven segment, representing manufacturing breadth across European converting facilities with press-line retooling capabilities for rice husk composite processing.
| Leading Market Players |
|---|
| Bambu |
| EcoSouLife |
| Ekobo |
| World Centric |
| BioPak |
| Vegware |
| Huhtamaki |
| Bamboo India |
| Natural Home Brands |
| Others |
Pricing and Supply Chain Analysis
Heat-compression press utilization rates above 75% in Zhejiang and Fujian provinces compress unit costs for bamboo-cornstarch blends to parity with conventional plastics. This scale threshold concentrates supply-side pricing power among converters operating multiple 150°C processing lines, while marginal players face margin erosion from cornstarch commodity volatility.
Pricing Analysis
Prior-generation melamine-containing formulations trade at legacy discounts against current-generation pure bamboo fiber and PLA-blend tiers, while next-generation rice husk composites command modest premiums in certified composting markets. Contract-based long-term offtake dominates foodservice procurement, with price differentiation driven by EFSA certification tier and volume scale. Pricing pressure stems from cornstarch agricultural commodity cycles squeezing margin on high-turnover catering contracts. Food trucks exhibit highest price sensitivity due to thin operating margins, while hotel banquet departments show lowest sensitivity given presentation-tier requirements.
Supply Chain Analysis
Strategic stockpiling of cornstarch and PLA resin prevails among European converters buffering against agricultural commodity volatility, while just-in-time raw material flows characterize Southeast Asian export facilities. Supply concentrates in China, Vietnam, and Indonesia for molded cellulose processing, with Germany and the Netherlands hosting downstream converting and certification activities. Raw material dependencies center on bamboo pulp, cornstarch binders, and PLA biopolymer feedstocks. Single-source vulnerability runs through concentrated PLA resin supply from select fermentation facilities. Distribution runs through Rotterdam and Hamburg container terminals for European foodservice channels, with Australian supermarket chains sourcing direct from Southeast Asian manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across national composting certification schemes creates niche entry points for specialists mastering reciprocity documentation. Catering procurement shifts toward mandatory industrial compostability compliance reward players with testing laboratory relationships and multi-country approval track records.
For Market Incumbents: Shield market position through backward integration into bamboo farm partnerships that gate traceability documentation for EFSA qualification. Add heat-compression capacity in Bavaria and North Rhine-Westphalia to capture German packaging ordinance preferential placement. Certification investment in dual REACH and EFSA compliance creates switching costs against melamine-legacy competitors facing regulatory compression. For New Entrants and Emerging Players: Anchor in Australian household segments where supermarket channel control bypasses fragmented wholesaler networks and captures retail margin. Target food truck operators in California and Texas facing municipal waste disposal levies, where direct manufacturer sales relationships eliminate intermediary layers. Lead with compostability certification as mandatory bid qualification for municipal catering contracts. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among farm-partnership converters with multi-year catering supply agreements and traceability-locked raw material flows. Five-to-ten year viability hinges on industrial composting infrastructure buildout pace across peripheral European markets. Acquisition targets with existing TGA alignment for Australian import qualification offer geographic expansion optionality. Watch for national composting scheme reciprocity harmonization as inflection signal for multi-country contract scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Depth Investment | EFSA and REACH dual compliance unlocks German packaging ordinance preferential shelf placement. |
| Farm Partnership Integration | Direct agricultural relationships gate supplier qualification with bamboo traceability documentation. |
| Retail Channel Control | Australian supermarket direct distribution bypasses fragmented wholesaler networks and captures household margin. |
| Heat-Compression Capacity Expansion | 150°C rice husk composite processing lines decompose cost barriers against petroleum-based serveware. |
| Composting Infrastructure Partnership | Industrial composting facility density in Germany, France, and Netherlands determines end-of-life pathway assurance. |
Research Methodology
A spread of perspectives from converting facility operations managers, foodservice procurement directors, composting infrastructure operators, and retail category buyers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through EFSA food contact material filings, German packaging ordinance enforcement records, Australian TGA import qualification databases, and customs trade flow data. Bottom-up segment sizing triangulated against top-down market envelope checks.
Segmentation dimensions modeled span material composition tier, end-use application, and distribution channel structure across the projection horizon. CAGRs derived from volume trajectory analysis incorporating heat-compression capacity expansion timelines and regulatory enforcement phase-in schedules. Forecast inputs include cornstarch commodity price cycles and industrial composting facility density projections.
Decision-makers should treat outputs as directional under sustained EFSA enforcement trajectory and composting infrastructure buildout assumptions; material deviation would warrant model refresh. Revision becomes warranted when national composting scheme reciprocity harmonization crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.