
 Global Cotton Market | 2026-2036
Global Cotton Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cotton Market Analysis
Multi-source procurement from ginners and cooperatives is repositioning how spinners manage fiber quality and price volatility. Cargill leverages its global logistics network to connect Brazilian and Australian origins with Asian mills. Allenberg Cotton Company anchors its competitiveness in risk-management tools and origin diversification. Louis Dreyfus Company competes through integrated origination across multiple hemispheres.
Cotton is a natural cellulosic seed fiber composed of nearly pure cellulose, typically measuring 10 to 40 millimeters in staple length depending on cultivar, and is ginned to separate lint from seed before bale formation for textile manufacturing. Its primary commercial purpose is to provide spinnable fiber for yarn and fabric production across apparel, home furnishings, and technical textiles. Upland Cotton occupies the dominant volume position due to its higher yield and broader geographic adaptability, while Organic Cotton commands premium positioning as sustainability criteria tighten across European and North American buyer specifications. Conventional Cotton retains cost advantages in price-sensitive mass-market segments, though margin pools are shifting toward traceable and certified origins.
The USDA implements grading standards through its Agricultural Marketing Service, classifying cotton by staple length, micronaire, and color to establish universal trading terms. The EU Green Deal and associated due diligence frameworks are reshaping import requirements for agricultural commodities entering European ports. India's Textiles Ministry and Cotton Corporation of India influence domestic availability through minimum support price operations and buffer stock management. Stakeholders must monitor how regulatory divergence between sustainability-focused import markets and production-oriented export policies reshapes origin premiums and contract structures.
Market Dynamics
EU Green Deal due diligence requirements are forcing cotton traders to reconstruct supply chain documentation and origin verification systems. Procurement departments now treat fiber traceability as a contractual prerequisite rather than a marketing attribute.
Growth Catalysts
- EU Green Deal Due Diligence:Mandatory supply chain disclosure for agricultural imports entering European ports is pulling certified organic and traceable cotton volumes into premium contract structures.
- Textile Mill Capacity Expansion in India:Domestic spinners are scaling operations to serve both local garment manufacturing and export yarn demand, tightening regional fiber offtake.
- Mechanical Harvesting Diffusion:Stripper and spindle picker adoption across Brazilian cerrado and Australian riverina is compressing per-bale labor costs and flattening seasonal supply curves.
Market Restraints
- Input Cost Volatility:Synthetic fertilizer and diesel price swings transmit directly into ginning economics, squeezing margin predictability for origin operators.
- Supply Concentration Risk:Brazilian export availability hinges on Santos port logistics and seasonal rainfall patterns in Mato Grosso.
- Regulatory Friction:India's Cotton Corporation of India buffer stock interventions periodically distort spot pricing transparency for international buyers.
Strategic Opportunities
- Underpenetrated Geography:West African origins in Burkina Faso and Mali offer compliant fiber for EU preferential tariff access under Everything But Arms provisions.
- Regulatory Tailwind:India's PLI scheme for textile manufacturing is incentivizing integrated fiber-to-fabric investments that stabilize long-term cotton offtake.
- Technology Convergence:Blockchain traceability platforms merged with satellite-based farm monitoring are collapsing verification costs for organic certification claims.
Industry Challenges
- Agronomic Skill Gap:Integrated pest management expertise for bollworm resistance management is scarce among smallholder extension services.
- Certification Timeline Compression:Organic transition periods and residue testing protocols delay premium market access for converting farms.
- Legacy Gin Infrastructure:Aging roller gin capacity in traditional origins limits high-grade fiber output expansion despite seed variety improvements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cotton Market |
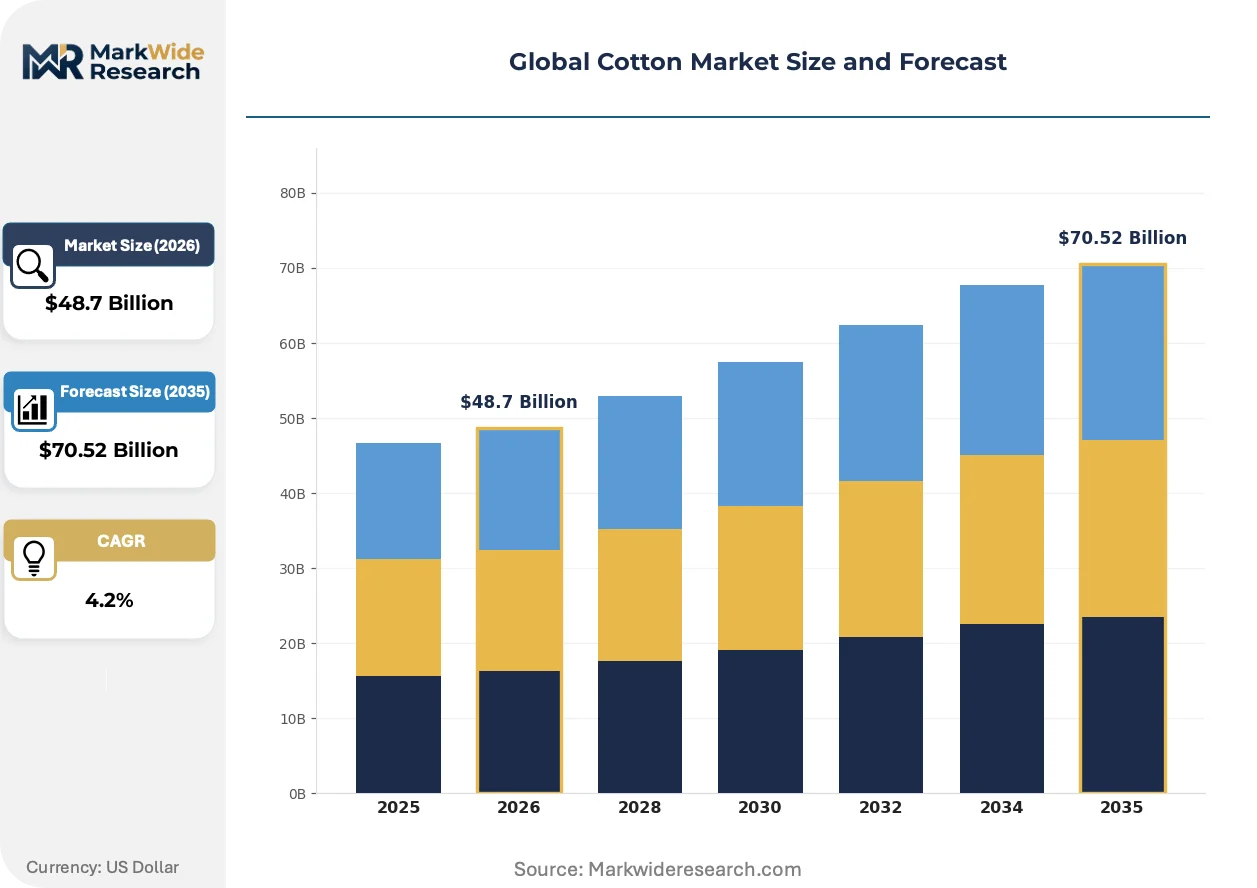
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $70.52 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Cotton, Conventional Cotton, Pima Cotton, Upland Cotton End Use: Apparel, Home Textiles, Industrial Products, Medical Supplies Distribution Channel: Online Retail, Wholesale, Direct Sales, Exports Processing Technology: Spinning, Weaving, Knitting, Finishing |
| Companies Covered | Allenberg Cotton Company, Cargill, Olam International, Louis Dreyfus Company, Plexus Cotton Ltd, Calcot Ltd, Staplcotn, Dunavant Enterprises, ECOM Agroindustrial Corp Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cotton Market Emerging Trajectories
Digital traceability infrastructure is displacing paper-based chain-of-custody documentation across cotton procurement workflows. This shift is compressing verification timelines and enabling real-time compliance auditing.
Sensor-based moisture detection and automated bale tagging is electrifying ginning operations from field to warehouse. Mid-sized cooperatives in Australia and Brazil are adopting these systems fastest. The technology is compressing quality disputes and accelerating payment settlement cycles for growers.
REACH chemical restrictions and the EU Green Deal's deforestation-free supply chain mandates are reshaping import documentation burdens. Textile brands sourcing for European retail must now demonstrate geolocation-verified farm origins. Apparel manufacturers are responding by consolidating supplier bases to reduce audit complexity.
Direct contracting between spinners and ginner cooperatives is fragmenting traditional merchant intermediation. Large South Asian mills now negotiate multi-origin supply agreements covering Brazilian, Australian, and West African volumes simultaneously. This pattern is most visible in Tamil Nadu and Gujarat, where integrated textile clusters source fiber across three hemispheres.
Global Cotton Market Segmentation
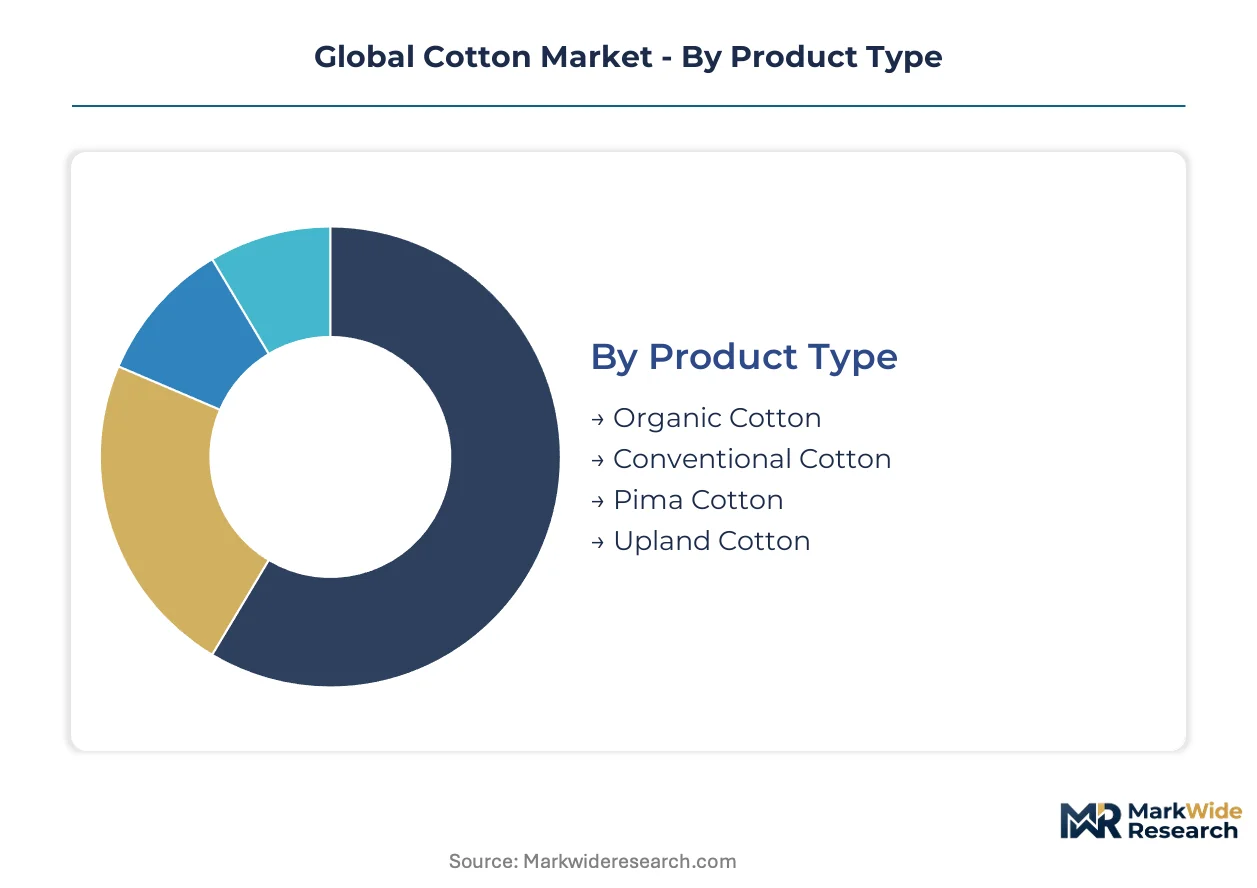
Cotton procurement stratifies across fiber grades, end-use applications, and channel structures that determine margin capture and compliance burden. Spinners and brands configure sourcing portfolios around these segment boundaries to balance cost, quality, and traceability requirements.
Product Type:
Standardization dominates at the commodity base while premium tiers demand intensive farm-level documentation and certification protocols.
- Upland Cotton:Higher-yield cultivar with staple length ranging 25-32 millimeters, ginned predominantly by saw-type machinery for mass-market yarn production. Indian textile mills in Tamil Nadu and Gujarat absorb the largest volumes, driven by PLI scheme incentives for integrated fiber-to-fabric investments.
- Organic Cotton:Cultivated without synthetic pesticides or fertilizers under third-party certification, commanding price premiums of 15-30 percent above conventional grades. EU Green Deal due diligence mandates are pulling certified volumes into premium contract structures for European apparel brands.
- Conventional Cotton:Standard agricultural practice with permitted synthetic inputs, retaining cost advantages in price-sensitive mass-market segments.
- Pima Cotton:Extra-long staple variety exceeding 35 millimeters, prized for fine-count yarn applications in luxury apparel.
Most installed capacity flows through Upland Cotton. Expansion is steepest in Organic Cotton.
End Use:
Application-driven specifications create divergent fiber quality requirements and certification intensity across downstream segments.
- Apparel:Dominant consumption channel spanning fast fashion through luxury tiers, with sustainability criteria tightening most aggressively in European and North American buyer specifications. REACH chemical restrictions and deforestation-free mandates are reshaping sourcing documentation burdens for brands serving EU retail.
- Home Textiles:Bedding, towel, and furnishing applications demanding durable, absorbent fiber characteristics with lower fineness requirements than apparel.
- Industrial Products:Technical applications including cordage, filters, and nonwoven reinforcements where tensile strength supersedes aesthetic properties.
- Medical Supplies:Surgical gauze, bandages, and hygiene products requiring pharmaceutical-grade purity and sterilization compatibility.
Volume concentration sits with Apparel. Margin expansion is most pronounced in Medical Supplies.
Distribution Channel:
Channel selection determines price transparency, working capital cycles, and supply chain visibility for fiber procurement.
- Wholesale:Traditional merchant intermediation through cotton exchanges and dealer networks, providing liquidity and price discovery for standardized grades.
- Direct Sales:Contracting between spinners and ginner cooperatives, fragmenting traditional merchant roles as large South Asian mills negotiate multi-origin supply agreements.
- Exports:Cross-border shipment from origin markets to consuming regions, concentrated through Santos port for Brazilian supply and Fremantle for Australian origins.
- Online Retail:Emerging digital platforms for spot transactions and forward contracting, particularly for certified and traceable grades.
Transaction volume concentrates in Wholesale. Digital infrastructure investment is accelerating fastest in Direct Sales.
Processing Technology:
Technology selection locks in fiber preparation methods that constrain downstream quality ceilings and production economics.
- Spinning:Ring spinning and open-end rotor systems converting lint into yarn, with compact spinning technology reducing hairiness for premium apparel applications.
- Weaving:Interlacing warp and weft threads on air-jet and rapier looms for structured fabrics in shirting and denim.
- Knitting:Loop formation for stretchable fabrics in T-shirts and intimate apparel, with circular knitting dominating mass production.
- Finishing:Chemical and mechanical treatments including mercerization, sanforization, and softening that determine final fabric hand and performance.
Capital deployment concentrates in Spinning. Automation penetration is deepest in Finishing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tamil Nadu's textile belt commands the largest installed spinning capacity worldwide, absorbing upland cotton from multiple hemispheres. The EU Green Deal and India's PLI scheme are redirecting investment flows across producing and consuming regions.
India
Gujarat and Maharashtra mills scale capacity to serve garment export demand and domestic apparel consumption. The Cotton Corporation of India maintains buffer stock operations that periodically influence spot pricing transparency. Tamil Nadu's integrated clusters source Brazilian, Australian, and West African fiber simultaneously through direct ginner contracts.
China
Xinjiang-origin fiber faces documentation barriers for EU and US apparel supply chains, redirecting procurement toward Brazilian and Australian alternatives. The country's national agricultural regulator enforces quality grading protocols aligned with international trading standards. Yangtze River Delta spinning mills absorb premium long-staple imports for high-count yarn production.
United States
Texas High Plains and Mississippi Delta gins supply extra-long staple Pima and high-grade upland varieties to Asian spinners. USDA grading standards through the Agricultural Marketing Service establish universal trading terms for fiber classification. California's San Joaquin Valley maintains specialized acreage for luxury apparel segment supply.
Brazil
Mato Grosso and Bahia expansion drives export volume growth into Asian mill procurement portfolios. Seasonal rainfall patterns and Santos port logistics create periodic supply concentration risks for international buyers. The cerrado region's mechanical harvesting adoption compresses per-bale labor costs below manual-picking origins.
Australia
New South Wales and Queensland riverina districts supply contamination-free fiber prized for premium yarn applications. Satellite-based farm monitoring and blockchain traceability platforms enable rapid organic certification verification. Fremantle and Brisbane port infrastructure channels bales directly to South Asian spinning operations.
Global Cotton Market Vendor Landscape
Global majors compete with regional champions across origination networks and risk-management capabilities. The merchant tier concentrates around integrated traders with multi-hemisphere procurement infrastructure. Three archetypes dominate: integrated agricultural conglomerates with captive logistics, specialized cotton merchants with deep origin relationships, and cooperative marketing associations representing pooled grower output. Competitive moves center on origin diversification and digital traceability platform deployment.
Among integrated agricultural traders, Cargill exemplifies the logistics-anchored archetype through its Brazilian and Australian origin connections with Asian mills. Allenberg Cotton Company occupies a position within the risk-management specialist tier, while Louis Dreyfus Company represents the multi-hemisphere origination model. These three entities anchor the competitive structure through differentiated approaches to fiber procurement, quality assurance, and supply chain documentation.
| Leading Market Players |
|---|
| Allenberg Cotton Company |
| Cargill |
| Olam International |
| Louis Dreyfus Company |
| Plexus Cotton Ltd |
| Calcot Ltd |
| Staplcotn |
| Dunavant Enterprises |
| ECOM Agroindustrial Corp Ltd |
| Others |
Supply Flow & Price Mechanics
Family-owned ginning cooperatives across West Africa and South Asia anchor supply discipline through patient capital deployment and multi-generational farmer relationships. Their financing patterns buffer spot market volatility while sustaining premium contract premiums for traceable origins.
Pricing Analysis
Input-cost pass-through from synthetic fertilizer and diesel price swings compresses ginning margins and transmits into bale pricing within one to two quarters. Contract-based long-term offtake dominates procurement between spinners and major origins, with price differentiation driven by certification level (EU Green Deal compliance, organic third-party verification) and staple length grade. Pricing pressure stems from India's Cotton Corporation of India buffer stock interventions that periodically distort spot transparency. Mass-market conventional grades exhibit highest price sensitivity, while medical-grade and extra-long staple varieties retain inelastic demand curves.
Supply Chain Analysis
Certification gating through EU Green Deal due diligence mandates and USDA Agricultural Marketing Service grading standards filters supplier eligibility for premium contract tiers. Geographic supply concentrates in Brazil, India, and Australia, with raw material dependencies on glyphosate-resistant seed varieties, synthetic nitrogen fertilizers, and diesel-powered mechanical harvesting equipment. Single-source vulnerability runs through Santos port logistics for Brazilian export availability. Distribution runs through direct spinner-ginner contracting that fragments traditional merchant intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Cotton Market functions as a stable compounder, with EU regulatory mandates driving steady premiumization of certified and traceable fiber tiers.
For Market Incumbents: Extend digital traceability infrastructure investments to collapse verification costs for organic certification claims and reinforce contract stickiness with EU apparel brands. Counter mechanical harvesting diffusion in Brazil and Australia by deepening origin relationships with West African cooperatives that offer Everything But Arms tariff preference. Buffer stock intervention risk in India demands diversified procurement across three hemispheres minimum. For New Entrants and Emerging Players: EU Green Deal due diligence requirements in Europe open a window for blockchain-integrated traceability platforms that merge satellite farm monitoring with automated bale tagging. West African origins in Burkina Faso and Mali represent the most penetrable geography given compliant fiber access and underdeveloped merchant competition. A go-to-market angle anchored in pharmaceutical-grade purity certification for medical supplies bypasses saturated apparel procurement channels. For Investors and Strategic Acquirers: Valuations sit cheapest among regional ginning cooperatives with captive farmer networks and underinvested digital infrastructure. Long-term viability centers on fiber traceability as a contractual prerequisite rather than marketing attribute across the next decade. Acquisition targets should display integrated origination across multiple hemispheres with existing EU brand relationships. Watch for inflection when India's PLI scheme for textile manufacturing triggers integrated fiber-to-fabric capacity announcements in Gujarat and Tamil Nadu.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Platform Deployment | Merges satellite farm monitoring with automated bale tagging to compress EU Green Deal compliance verification timelines. |
| Multi-Hemisphere Origin Diversification | Contracts spanning Brazilian, Australian, and West African volumes reduce India's Cotton Corporation of India intervention exposure. |
| Mechanical Harvesting Scale-Up | Stripper and spindle picker adoption across Mato Grosso and Queensland riverina compresses per-bale labor costs below manual-picking origins. |
| Organic Certification Transition Programs | Third-party verification investment captures 15-30 percent price premiums as REACH chemical restrictions tighten. |
| Direct Spinner-Ginner Contracting | Tamil Nadu and Gujarat mills fragment traditional merchant intermediation through multi-origin supply agreements. |
Methodological Framework
Coverage spans South Asia, South America, and Oceania, with primary inputs from each region combining structured interviews with ginning cooperative managers, textile mill procurement directors, and agricultural extension officers alongside secondary validation. USDA Agricultural Marketing Service grading databases, EU customs import records, and Cotton Corporation of India buffer stock disclosures anchor quantitative triangulation. Bottom-up bale volume estimates from origin gins reconcile against top-down apparel consumption models.
Granularity-level modeling disaggregates volume and value across the analysis window by fiber grade (Upland, Organic, Pima), end-use application (Apparel, Home Textiles, Medical Supplies), and distribution channel (Wholesale, Direct Sales, Exports). CAGRs derive from regression analysis against textile mill capacity expansion rates and EU regulatory compliance cost curves. Industry-specific forecast inputs include monsoonal rainfall patterns in Maharashtra and Santos port throughput capacity utilization.
Revisions become necessary when EU Green Deal due diligence implementation timelines accelerate or when India's PLI scheme disbursement triggers unexpected integrated fiber-to-fabric investment surges. Forecasts reflect assumptions around mechanical harvesting adoption rates and organic transition period completion. A model refresh is warranted upon material change in EU REACH chemical restriction scope or Cotton Corporation of India buffer stock operating procedures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Hessian Sacks Market
Natural Fibers
Natural Fibers Market
Natural Fibers
Cashmere Clothing Market
Natural Fibers
Bamboo Fibers Market
Natural Fibers
Jute Bags Market
Natural Fibers
Cellulose Market
Natural Fibers
Indonesia Textiles Market
Natural Fibers
Spent Coffee Grounds Fiber Market
Natural Fibers
Eco Fibers Market
Natural Fibers
Silk Market
Natural Fibers
Jute Market
Natural Fibers
Global Hemp Fiber Market
Natural Fibers
Natural Fiber Reinforced Composites Market
Natural Fibers
Natural Fiber Composite (NFC) Market
Natural Fibers
Abaca Fiber Market
Natural Fibers
Silk Textiles Market