
 Green Fibers Market | 2026-2036
Green Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Green Fibers Market Analysis
The EU Green Deal is recalibrating procurement standards across European textile supply chains, forcing fiber producers to certify biodegradability and renewable content. Lenzing AG leverages its Tencel production platform to dominate wood-based cellulosic fiber supply. Aditya Birla Group anchors South Asian viscose output through Grasim Industries' integrated pulp-to-fiber operations. DuPont de Nemours specializes in bio-based polymer fibers that compete with petroleum-derived alternatives in automotive and industrial applications.
Green fibers encompass plant-derived and regenerated cellulosic materials engineered to replace conventional synthetic and resource-intensive natural fibers, typically processed through mechanical retting, chemical dissolution, or enzymatic treatment to achieve specified tenacities between 15 and 40 cN/tex for yarn applications. Their primary commercial purpose centers on reducing Scope 3 emissions for downstream manufacturers while meeting performance thresholds for woven and nonwoven end products. Organic cotton and hemp command premium positioning in apparel supply chains where brand sustainability commitments create protected margin pools. Bamboo fiber adoption is accelerating fastest in nonwoven hygiene applications due to its inherent antimicrobial properties and rapid biomass regeneration cycles.
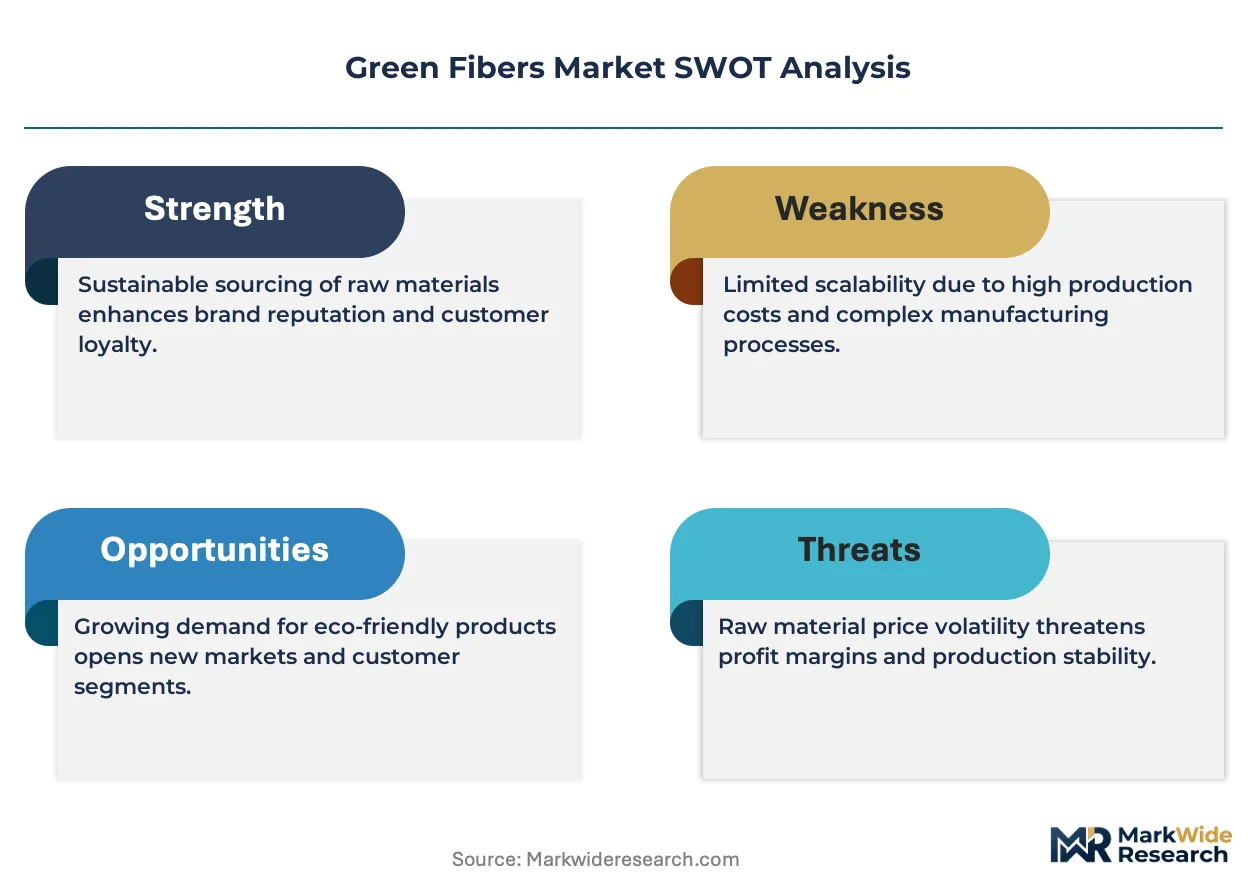
REACH chemical registration requirements in Europe restrict certain viscose processing chemicals, while the EU's Ecodesign for Sustainable Products Regulation establishes mandatory recycled and recyclable content thresholds for textiles placed on the European market. The EPA's emerging bio-preferred program procurement standards in the United States create federal purchasing pull for certified biobased fibers. Stakeholders must monitor how divergent regional certification schemes for biodegradability and renewable content reshape market access conditions and supplier qualification timelines.
Market Dynamics
The EU Green Deal's Ecodesign for Sustainable Products Regulation is forcing fiber producers to reconfigure entire production systems around certified biodegradability and renewable content thresholds. This mandate is compressing supplier qualification timelines while creating protected margin pools for early certifiers.
Growth Catalysts
- EU Green Deal textile mandates:Mandatory recycled and recyclable content thresholds for textiles placed on the European market are accelerating fiber substitution timelines across apparel supply chains.
- Automotive lightweighting demand:Bio-based polymer fibers are displacing petroleum-derived alternatives in vehicle interior applications as OEMs target Scope 3 emission reductions.
- Stuttgart technical textile cluster:Germany's concentrated R&D infrastructure around high-performance nonwovens is pulling specialized hemp and flax fiber development.
Market Restraints
- REACH chemical restrictions:ECHA registration requirements for carbon disulfide and other viscose processing chemicals are constraining European regenerated cellulosic capacity expansion.
- Pulp supply concentration:Wood-based cellulosic fiber producers remain dependent on Southeast Asian dissolving pulp imports, creating raw material vulnerability.
- Performance gaps in technical applications:Natural fiber tenacities plateau below 40 cN/tex, limiting penetration into high-strength industrial yarns and tire cord.
Strategic Opportunities
- Nonwoven hygiene pivot:Bamboo fiber's inherent antimicrobial properties and rapid biomass regeneration cycles are opening dedicated supply contracts in diaper and feminine hygiene segments.
- US federal procurement pull:EPA bio-preferred program standards are creating mandated purchasing volume for certified biobased fibers across federal agencies.
- Enzymatic retting convergence:Integration of enzyme treatment with mechanical processing is reducing water intensity and expanding temperate-region hemp cultivation.
Industry Challenges
- Biodegradability certification complexity:Divergent national schemes for compostability testing and marine biodegradability are extending product qualification timelines by 12-18 months.
- Retting workforce scarcity:Mechanical and enzymatic fiber extraction requires specialized agronomic and process engineering skills that agricultural regions lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Fibers Market |
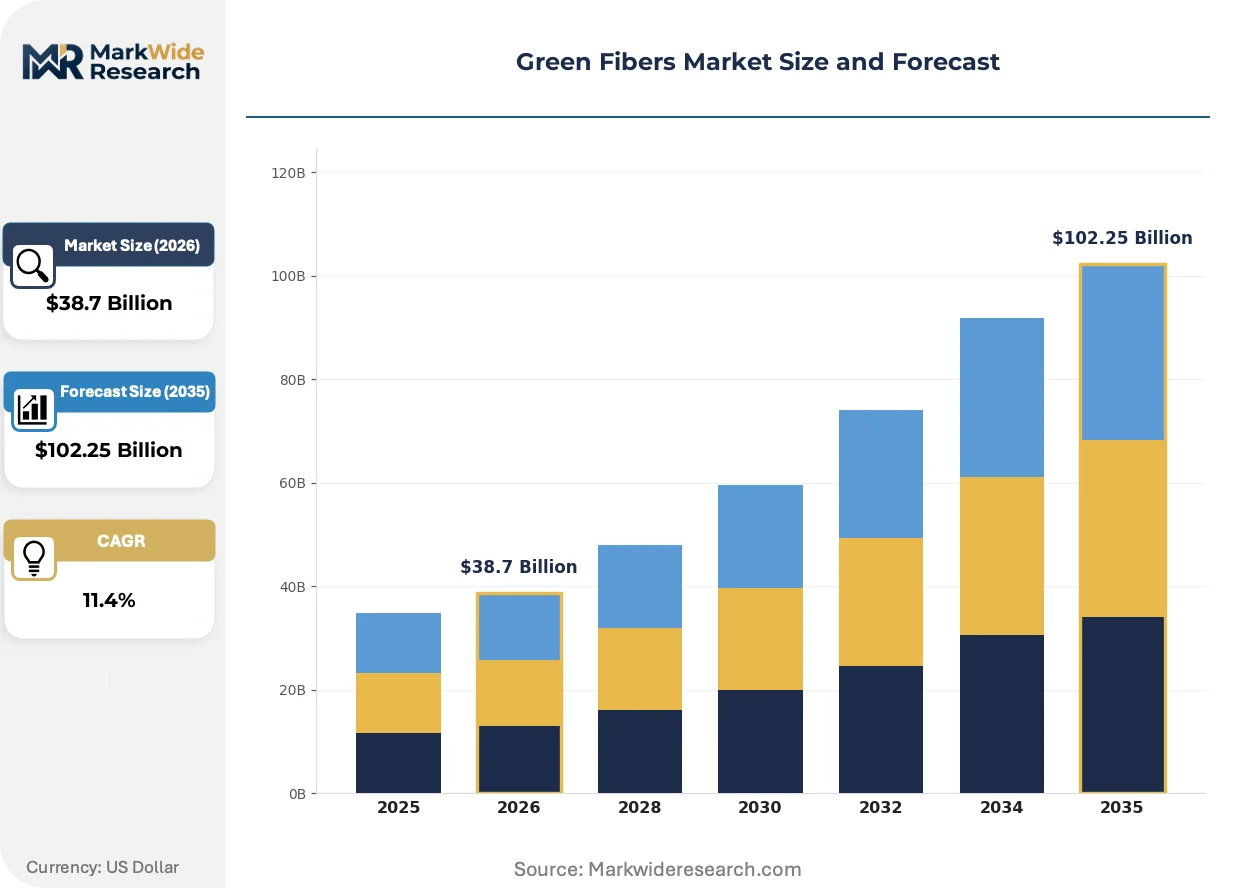
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hemp, Bamboo, Organic Cotton, Linen End Use Industry: Textiles, Automotive, Composites, Construction Form: Yarn, Fabric, Composite Material, Nonwoven Feature: Biodegradable, Renewable, Lightweight, Insulating |
| Companies Covered | Lenzing AG, Aditya Birla Group (Grasim Industries), DuPont de Nemours, BASF SE, Toray Industries, Eastman Chemical Company, Unifi Inc., Renewcell, Mitsubishi Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Fibers Market Emerging Trajectories
Processing technology convergence is collapsing the traditional separation between textile-grade natural fibers and technical nonwoven inputs. This shift is compressing equipment amortization cycles while opening new specification tiers.
Enzymatic fiber extraction is rewriting the economics of bast crop processing. The technology replaces water-intensive retting with targeted biocatalytic separation, enabling European and North American hemp producers to compete with Asian supply. Apparel brands with science-based targets are fast-tracking adoption to secure certified fiber volumes ahead of competitor procurement cycles.
REACH chemical registration requirements are restructuring European viscose supply chains. ECHA restrictions on carbon disulfide emissions are forcing producers to invest in closed-loop solvent recovery or pivot to alternative dissolution chemistries. Wood-based cellulosic fiber manufacturers serving EU apparel markets are consolidating around Tencel-type lyocell processes that bypass traditional viscose chemistry entirely.
Brand sustainability commitments are hardening into procurement specifications with penalty clauses. Major apparel retailers now require fiber suppliers to provide lot-level biodegradability certification and Scope 3 emission calculations. This specification tightening is most visible in German technical textile clusters, where automotive and industrial buyers are integrating fiber certification into supplier scorecards with quarterly compliance audits.
Green Fibers Market Segmentation
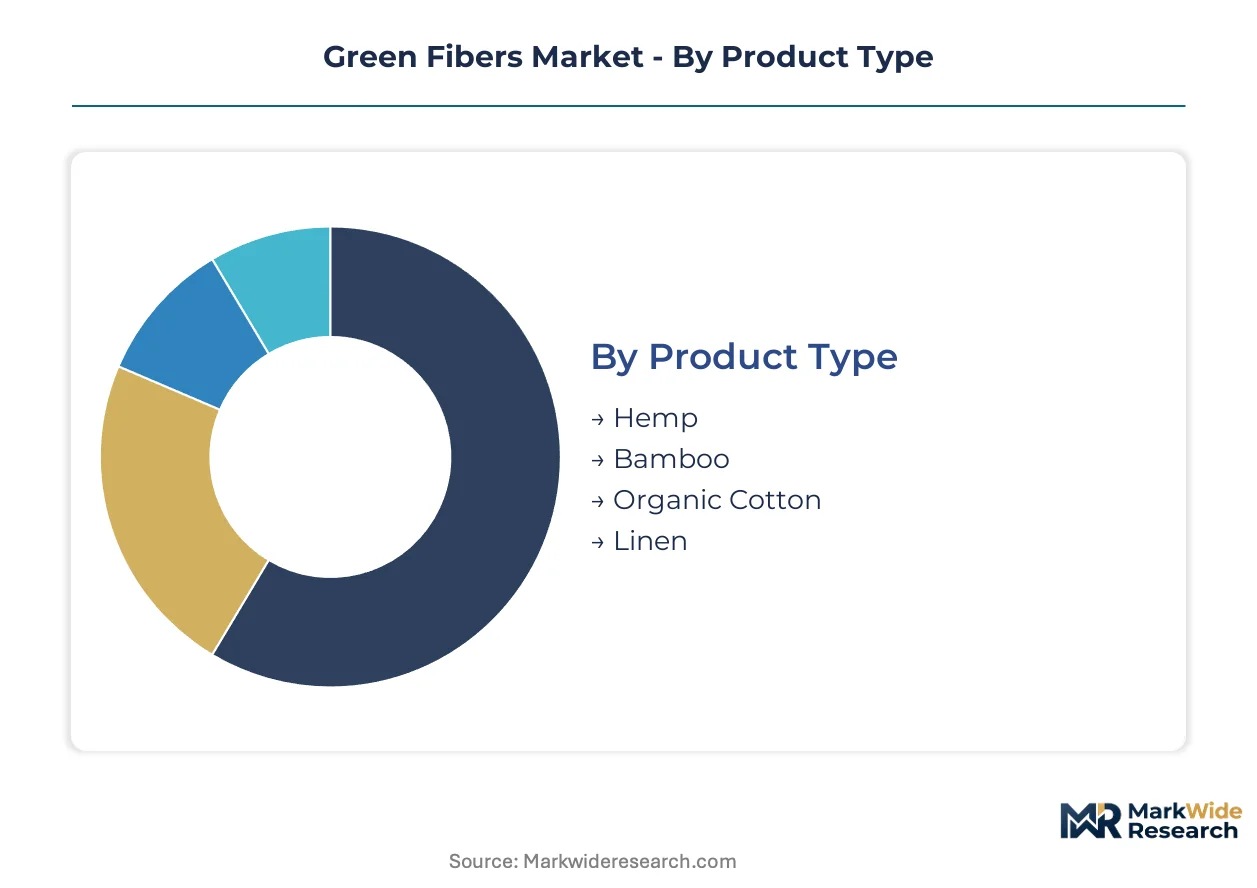
Green fiber suppliers configure production assets around distinct specification tiers that command divergent margin structures. Each segmentation dimension—product chemistry, end-use performance requirements, physical form, and certified features—creates separate qualification barriers and procurement contract terms.
Product Type:
Supply concentration in certified organic cotton and wood-based cellulosics is reshaping how fiber producers allocate retting and dissolution capacity across crop types.
- Organic Cotton:Grown without synthetic pesticides or fertilizers under third-party certification schemes, this fiber delivers the soft hand feel and dye affinity that apparel brands require for direct-to-skin applications. Demand concentrates in German technical textile clusters where automotive interior suppliers specify certified organic content for Scope 3 reporting.
- Hemp:Bast fibers extracted from Cannabis sativa stalks through water retting or enzymatic processing achieve tenacities between 30 and 40 cN/tex, positioning them as structural reinforcement candidates. Stuttgart-area nonwoven manufacturers are pulling specialized hemp fiber development for high-performance geotextile applications.
- Bamboo:Regenerated cellulosic fiber derived from fast-growing Moso bamboo pulp delivers inherent antimicrobial properties through bamboo kun biochemistry. European hygiene product manufacturers specify bamboo for diaper top sheets and feminine care substrates.
- Linen:Flax fibers from Linum usitatissimum stems processed through dew retting produce the crisp hand and high thermal conductivity valued in summer apparel and bedding. Belgian and French agricultural cooperatives dominate EU linen fiber supply through heritage cultivation regions.
Today's leader: Organic Cotton. Tomorrow's challenger: Hemp.
End Use Industry:
Application-specific performance thresholds create divergent certification requirements and supplier qualification timelines across downstream sectors.
- Textiles:Apparel and home textile manufacturers specify fiber tenacities, elongation rates, and dye uptake curves that determine weaving efficiency and finished fabric durability. EU Green Deal Ecodesign mandates are accelerating substitution away from conventional cotton and polyester blends.
- Automotive:OEM interior trim specifications require flame resistance, low VOC emissions, and acoustic dampening performance that natural fibers achieve at lower densities than petroleum-derived alternatives. German manufacturers integrate fiber certification into supplier scorecards with quarterly compliance audits.
- Composites:Fiber-reinforced polymer matrix applications demand consistent aspect ratios and surface chemistry for resin wet-out, with hemp and flax fibers displacing glass fiber in non-structural automotive panels.
- Construction:Geotextiles, insulation batts, and fiber-cement reinforcement applications prioritize biodegradability in temporary erosion control and thermal performance in building envelopes.
Textiles commands current volume. Automotive offers the steepest expansion trajectory as lightweighting mandates harden.
Form:
Physical processing stages determine which fiber producers capture value and which remain raw material suppliers to integrated textile manufacturers.
- Yarn:Twisted staple fiber assemblies produced through ring, rotor, or air-jet spinning achieve specified count and strength for weaving or knitting operations. Italian and Portuguese spinning mills specialize in fine-count hemp and linen yarns for premium apparel.
- Fabric:Woven or knitted structures from greige or finished yarn create the substrate for garment cutting or industrial product fabrication. REACH chemical restrictions on processing aids are restructuring European fabric finishing supply chains.
- Composite Material:Fiber mats, rovings, or prepregs impregnated with thermoset or thermoplastic matrices serve structural and semi-structural applications in transportation and construction.
- Nonwoven:Entangled fiber webs produced through mechanical, thermal, or chemical bonding create disposable hygiene products, filtration media, and geotextiles without yarn intermediate stages.
Nonwoven captures processing margin. Yarn remains the most defensible position for established European fiber houses.
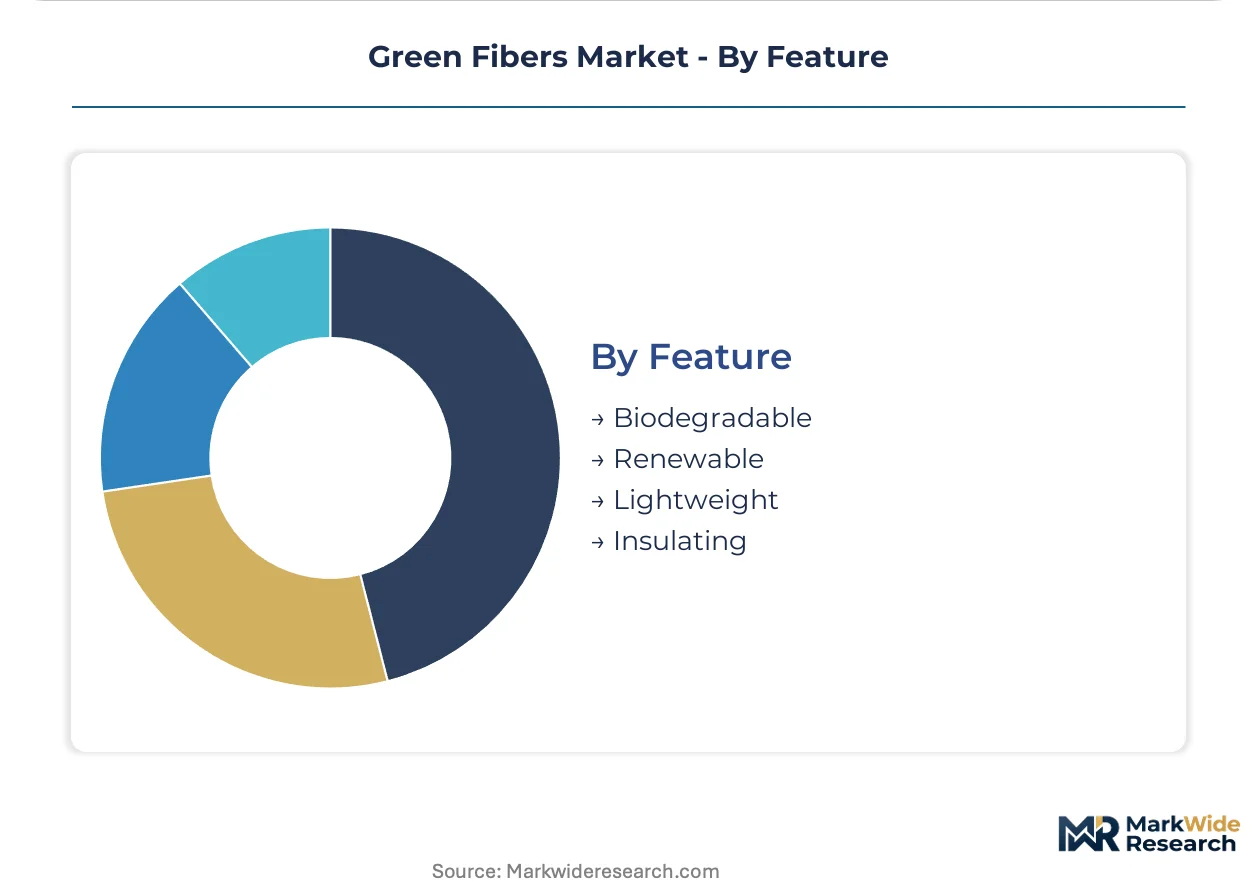
Feature:
Certified functional attributes now determine market access conditions and price realization levels more than base fiber chemistry.
- Biodegradable:Compostability certification under EN 13432 or ASTM D6400 standards enables disposal routes that avoid landfill fees and align with brand circularity commitments. Divergent national testing protocols extend qualification timelines.
- Renewable:Bio-based content verification through carbon-14 analysis or mass balance accounting satisfies EU Ecodesign thresholds and US EPA bio-preferred procurement standards.
- Lightweight:Specific strength ratios that exceed conventional materials enable mass reduction in transportation applications where every gram affects fuel efficiency calculations.
- Insulating:Thermal and acoustic dampening properties position bast fibers as substitutes for synthetic insulation in building envelopes and automotive NVH packages.
Biodegradable certification opens EU market access. Lightweight specifications unlock automotive pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European textile manufacturing heritage traces through Belgian flax cultivation and Italian spinning traditions, establishing quality benchmarks that contemporary green fiber producers now adapt for sustainability certification. Asian supply chains scaled wood-based cellulosic production from Japanese viscose engineering and Indian integrated pulp operations. North American demand formation centers on federal procurement standards and automotive lightweighting mandates.
Germany
Automotive OEMs specify certified organic fiber content for interior trim Scope 3 reporting, while technical textile manufacturers around Stuttgart pull specialized hemp development for geotextile applications. The EU Green Deal's Ecodesign for Sustainable Products Regulation mandates recycled content thresholds for all textiles placed on the German market. The Stuttgart technical textile cluster concentrates R&D infrastructure for high-performance nonwoven development.
United States
Federal agency procurement creates mandated purchasing volume for certified biobased fibers through EPA bio-preferred program standards. The USDA administers certification protocols for organic cotton and hemp cultivation that qualify producers for federal supply contracts. Automotive manufacturers in Michigan and the Southeast integrate natural fiber composites into vehicle interior panels.
China
Dual carbon goals drive substitution of petroleum-derived synthetics with bamboo-based cellulosic fibers in domestic textile manufacturing. The Ministry of Ecology and Environment encloses carbon intensity benchmarks for viscose production facilities in the Yangtze River Delta. Zhejiang and Jiangsu provinces concentrate regenerated cellulosic fiber capacity serving both domestic apparel and export markets.
India
Apparel export houses scale organic cotton procurement to meet EU retailer sustainability specifications and avoid Ecodesign compliance penalties. The Bureau of Indian Standards operates certification schemes for textile biodegradability that align with EN 13432 testing protocols. Gujarat and Maharashtra host integrated ginning and spinning operations that process certified organic cotton for European brand supply chains.
Belgium
Heritage flax cultivation cooperatives supply premium linen fiber to luxury apparel and home textile manufacturers demanding traceable agricultural provenance. REACH chemical registration requirements administered by ECHA restrict certain retting processing aids used in traditional fiber extraction. The Flanders region maintains specialized dew retting infrastructure that produces textile-grade flax with specified thermal conductivity properties.
Green Fibers Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tier and end-use specification complexity. The vendor base organizes into three distinct strata: integrated pulp-to-fiber conglomerates with captive raw material supply, specialized regenerated cellulosic producers with closed-loop chemistry platforms, and regional natural fiber processors with heritage agricultural relationships. Strategic moves concentrate on backward integration into dissolving pulp supply and technology licensing for enzymatic retting processes.
Among European integrated producers, Lenzing AG occupies a position exemplifying wood-based cellulosic specialization through lyocell platform dominance. Aditya Birla Group anchors the South Asian tier through Grasim Industries' pulp-to-fiber vertical structure. DuPont de Nemours sits within the bio-based polymer segment, representing petrochemical alternative development for automotive and industrial applications.
| Leading Market Players |
|---|
| Lenzing AG |
| Aditya Birla Group (Grasim Industries) |
| DuPont de Nemours |
| BASF SE |
| Toray Industries |
| Eastman Chemical Company |
| Unifi Inc. |
| Renewcell |
| Mitsubishi Chemical Corporation |
| Others |
Supply Flow & Price Mechanics
Specialized enzymatic retting technicians concentrated in Belgium's Flanders region and Italy's Biella district command wage premiums that widen pricing spreads between premium-certified and commodity-grade bast fibers. Labor-cost differentials between heritage European processing clusters and emerging Asian mechanical-retting operations feed directly into three-tier pricing stratification across organic cotton, hemp, and linen grades.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs green fiber transactions, with certification grade under EU Ecodesign standards and volume scale driving price differentiation between tiers. Cost compression in standard-grade viscose alternatives is intensifying because REACH chemical compliance adds processing overhead that mechanical-retting competitors avoid. Automotive OEMs show least price sensitivity due to Scope 3 reporting mandates, while mass-market apparel brands face acute margin pressure from fiber substitution timelines.
Supply Chain Analysis
Single-source vulnerability sits with Southeast Asian dissolving pulp suppliers that feed European lyocell and viscose production. Raw material flows draw from Austrian and Czech wood pulp operations, Indian organic cotton ginning clusters, and Chinese bamboo viscose facilities. Tariff exposure on processed cellulosic imports from China threatens margin structures for EU-based weavers. Distribution runs through integrated textile houses in Portugal and Turkey that control yarn-to-fabric conversion capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU regulatory compliance premiums and Asian production cost advantages, with carbon border adjustments widening the effective cost differential between certified European supply and conventional Asian alternatives.
For Market Incumbents: Anticipate accelerated consolidation around closed-loop lyocell chemistry as REACH restrictions on carbon disulfide harden. Incumbents should prioritize backward integration into dissolving pulp supply to defend margin structures against Asian viscose competitors. Certification investment in EN 13432 biodegradability standards creates switching costs that protect contract renewal rates with German automotive OEMs. For New Entrants and Emerging Players: The 40-60% price-point gap between premium-certified organic fibers and economy-grade conventional cotton creates entry space for mid-tier enzymatic retting specialists. Nonwoven hygiene applications in North America offer the most penetrable white space due to EPA bio-preferred procurement mandates. A go-to-market angle anchored on lot-level Scope 3 emission calculations attracts apparel brands with science-based targets. For Investors and Strategic Acquirers: Apparel conglomerates with net-zero commitments are the most active acquirer in this space, seeking captive fiber supply for supply chain decarbonization. Targets with integrated pulp-to-fiber assets in temperate climates offer long-term viability through the energy-transition window. The signal to watch is EU Ecodesign enforcement intensity against non-compliant textile imports.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Retting Scale-Up | Reduces water intensity and enables European hemp cultivation competitive with Asian supply. |
| Backward Integration into Dissolving Pulp | Captures margin from Southeast Asian pulp suppliers and insulates against tariff exposure. |
| EU Ecodesign Certification Investment | Unlocks protected margin pools in German automotive interior specifications. |
| Nonwoven Hygiene Supply Contracts | Secures dedicated offtake from EPA bio-preferred federal procurement programs. |
| Closed-Loop Lyocell Chemistry Licensing | Technology transfer generates royalty streams while bypassing REACH carbon disulfide restrictions. |
Methodological Framework
Multiple input streams — fiber procurement directors at apparel brands, enzymatic retting process engineers, ECHA regulatory affairs specialists, and dissolving pulp traders — were reconciled against secondary validation from EU Ecodesign implementation guidance, REACH chemical restriction notices, and EPA bio-preferred program standards. Bottom-up volume estimates from ginning and spinning operations were triangulated with top-down demand projections from automotive OEM sustainability reports.
Historical capacity expansion patterns were cross-referenced against expert panel assessments of enzymatic technology adoption curves across the analysis window. Segmentation modeling incorporated fiber chemistry type, end-use performance tier, physical processing form, and certified attribute dimensions. CAGRs were derived from regression analysis of substitution elasticity against synthetic fiber pricing, with automotive lightweighting mandates and EU textile Ecodesign thresholds as primary demand-shaping inputs.
The model assumes a particular technology adoption path; alternative pathways for enzymatic retting commercialization would alter the outlook if water-scarcity pressures accelerate faster than projected. Forecasts reflect assumptions about EU enforcement consistency and carbon border adjustment implementation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Cellulose Acetate Fiber Market
Natural Fibers
Cellulose Fiber Market
Natural Fibers
North America Alpaca Fiber Market
Natural Fibers
Indonesia Textiles Market
Natural Fibers
Wood-Based Fibers Market
Natural Fibers
North America Textile Market
Natural Fibers
Fenugreek Fiber Market
Natural Fibers
Down and Feather Market
Natural Fibers
Lignocellulosic Fibers Market
Natural Fibers
Silk Textiles Market
Natural Fibers
Textile Staples Market
Natural Fibers
Jute Market
Natural Fibers
Natural Fiber Composite (NFC) Market
Natural Fibers
Silk Fabric Market
Natural Fibers
Thailand Textile Market
Natural Fibers
Global Cellulosic Man-Made Fibers Market