
 Gum Fiber Market | 2026-2036
Gum Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Gum Fiber Market Analysis
Food and beverage formulators is unwinding reliance on synthetic hydrocolloids toward plant-derived alternatives. Nexira leverages its botanical extraction heritage to anchor European supply chains for acacia-derived fibers. Cargill sustains broad agricultural sourcing networks that compete across guar and xanthan gum categories. Ingredion Incorporated specializes in clean-label texturizing systems that differentiate its portfolio from commodity gum suppliers.
Gum fiber comprises high-molecular-weight polysaccharides extracted from plant seeds, tree exudates, or microbial fermentation, typically functioning as hydrocolloids that hydrate in water to modify viscosity, gelation, and suspension properties. Guar gum dominates volume flows due to its cost position in hydraulic fracturing and food applications, while xanthan gum commands premium positioning in gluten-free bakery and pharmaceutical suspensions where temperature-stable rheology justifies higher formulation value.
FDA dietary fiber qualification criteria and EFSA health claim frameworks govern how suppliers position soluble fiber content in nutritional labeling across the United States and Europe. India's FSSAI and BIS standards regulate guar gum purity grades for domestic food and export markets, directly shaping processor certification requirements in Rajasthan processing zones. Stakeholders must monitor evolving regulator definitions of dietary fiber as these classifications determine which gum fractions qualify for functional health claims in finished products.
Market Dynamics
Clean-label reformulation mandates from major retailers are forcing hydrocolloid suppliers to requalify gum fiber grades for simplified ingredient statements, compressing certification timelines and fragmenting procurement specifications across North American and European food manufacturing networks.
Growth Catalysts
- FDA Dietary Fiber Definition:The FDA's expanded definition of dietary fiber under 21 CFR 101.9 is enabling guar gum and acacia gum suppliers to pursue qualified health claims in US nutritional bars and beverages.
- Hydraulic Fracturing Demand:Oilfield service operators in Texas and North Dakota continue specifying high-viscosity guar gum for shale stimulation fluids, sustaining volume throughput for Rajasthan processing clusters.
- Gluten-Free Bakery Expansion:Xanthan gum functionality in dough rheology is accelerating adoption by European and North American gluten-free bread formulators seeking temperature-stable viscosity profiles.
Market Restraints
- Monsoon-Dependent Guar Seed Supply:Annual rainfall variability across Rajasthan and Gujarat directly constrains raw material availability for global guar gum processors.
- Fermentation Capacity Concentration:Xanthan gum production remains concentrated among microbial fermentation specialists with limited geographic diversification, creating supply vulnerability.
- Cellulose Gum Substitution:Purified cellulose derivatives from wood pulp processing are capturing share in cost-sensitive sauce and dressing applications where gel strength requirements are moderate.
Strategic Opportunities
- Brazilian Savanna Acacia:Underdeveloped harvesting infrastructure in Brazil's Cerrado biome offers white-space expansion for acacia gum suppliers seeking supply chain diversification beyond Sudan and Senegal.
- Personal Care Texturizers:Cosmetic formulators in South Korea and Japan are specifying gum fibers for natural-origin rheology modifiers in K-beauty skincare emulsions.
- EU Green Deal Biomass Incentives:The EU Green Deal's sustainable sourcing criteria are creating preferential market access for FSC-certified acacia gum versus synthetic hydrocolloid alternatives.
Industry Challenges
- Dual-Grade Certification Burden:Processors serving both food and oilfield markets must maintain separate FSSAI purity certifications and API friction-fluid specifications, duplicating quality management overhead.
- Specialized Extraction Talent Scarcity:Rajasthan's guar gum processing zones face shortages of chemical engineers capable of optimizing solvent recovery systems for food-grade gum splits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gum Fiber Market |
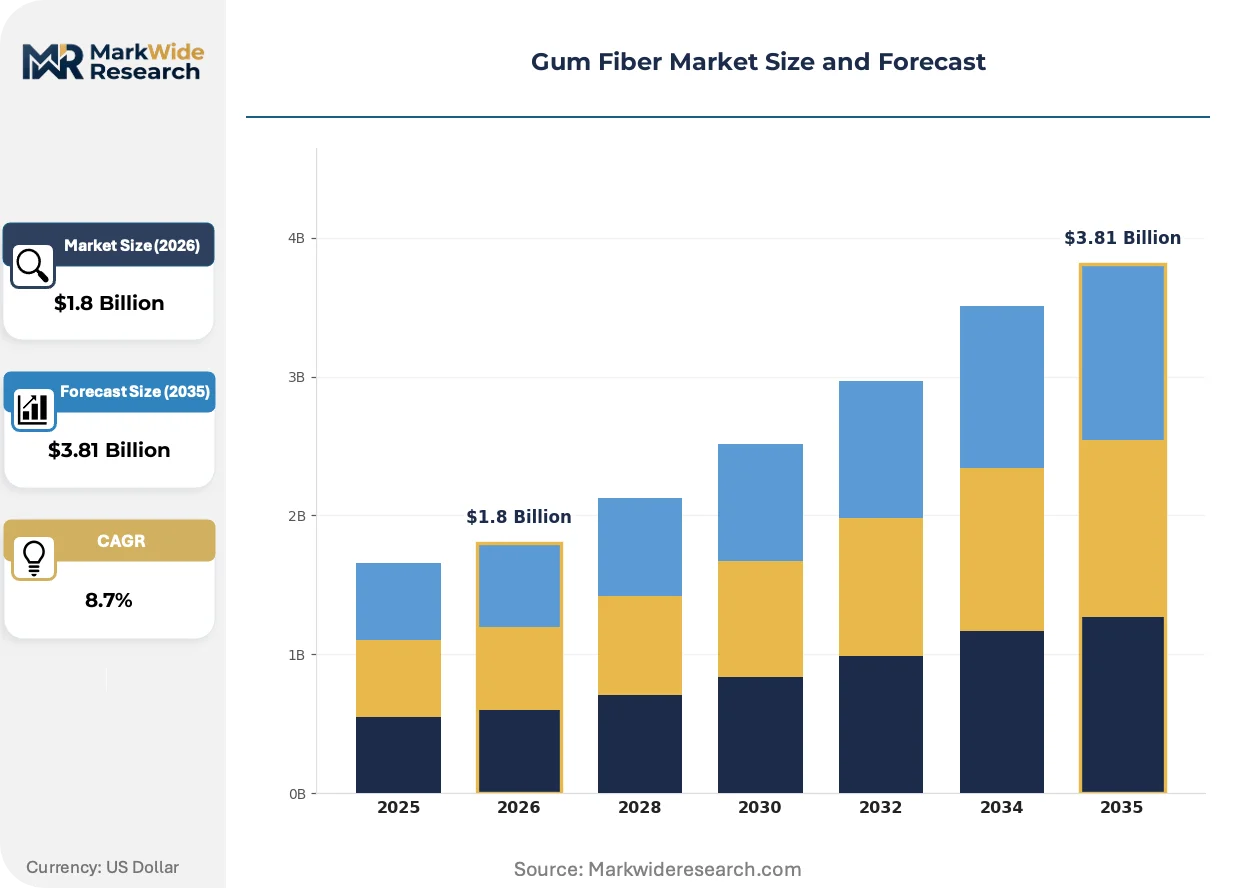
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Guar Gum, Xanthan Gum, Locust Bean Gum, Gum Arabic End Use Industry: Food & Beverage, Pharmaceuticals, Cosmetics, Textiles Formulation Type: Powder, Liquid, Granules, Paste Distribution Channel: Online, Retail, Distributors, Wholesalers |
| Companies Covered | AEP Colloids, Nexira, Cargill, Ingredion Incorporated, BASF SE, DuPont de Nemours, Neelkanth Polymers, Nutriroma, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gum Fiber Market Emerging Trajectories
Biotechnology-enabled fermentation processes and precision agriculture data systems are converging to reshape how gum fiber suppliers manage yield variability and functional consistency across geographically dispersed raw material sourcing networks.
Precision fermentation-derived hydrocolloids are supplanting conventionally extracted seed gums in select high-margin pharmaceutical suspension applications. Biotech startups in California and the Netherlands are scaling microbial cellulose and fermentation-based alternatives that match guar gum viscosity profiles. This technology is supplanting traditional supply chain dependencies on monsoon-sensitive agricultural regions while commanding 40-60% price premiums in parenteral drug formulations.
EFSA's 2021 updated guidance on health claims substantiation for soluble fiber is tightening clinical evidence requirements for gum fiber suppliers seeking Article 13.1 and 13.5 claims. The regulation now demands randomized controlled trials demonstrating physiological benefit to gut function or blood glucose regulation. European hydrocolloid marketers are responding by commissioning prospective studies on acacia gum prebiotic effects to defend existing claim positions.
Direct-procurement relationships between food manufacturers and Rajasthan processing cooperatives are shortening traditional trader-mediated supply chains. Large North American bakery and dairy conglomerates are establishing volume commitments with Gujarat-based guar gum refiners, bypassing European distributor markups. This disintermediation is most visible in contract structures for organic-certified gum grades where traceability documentation requirements exceed standard commercial specifications.
Gum Fiber Market Segmentation
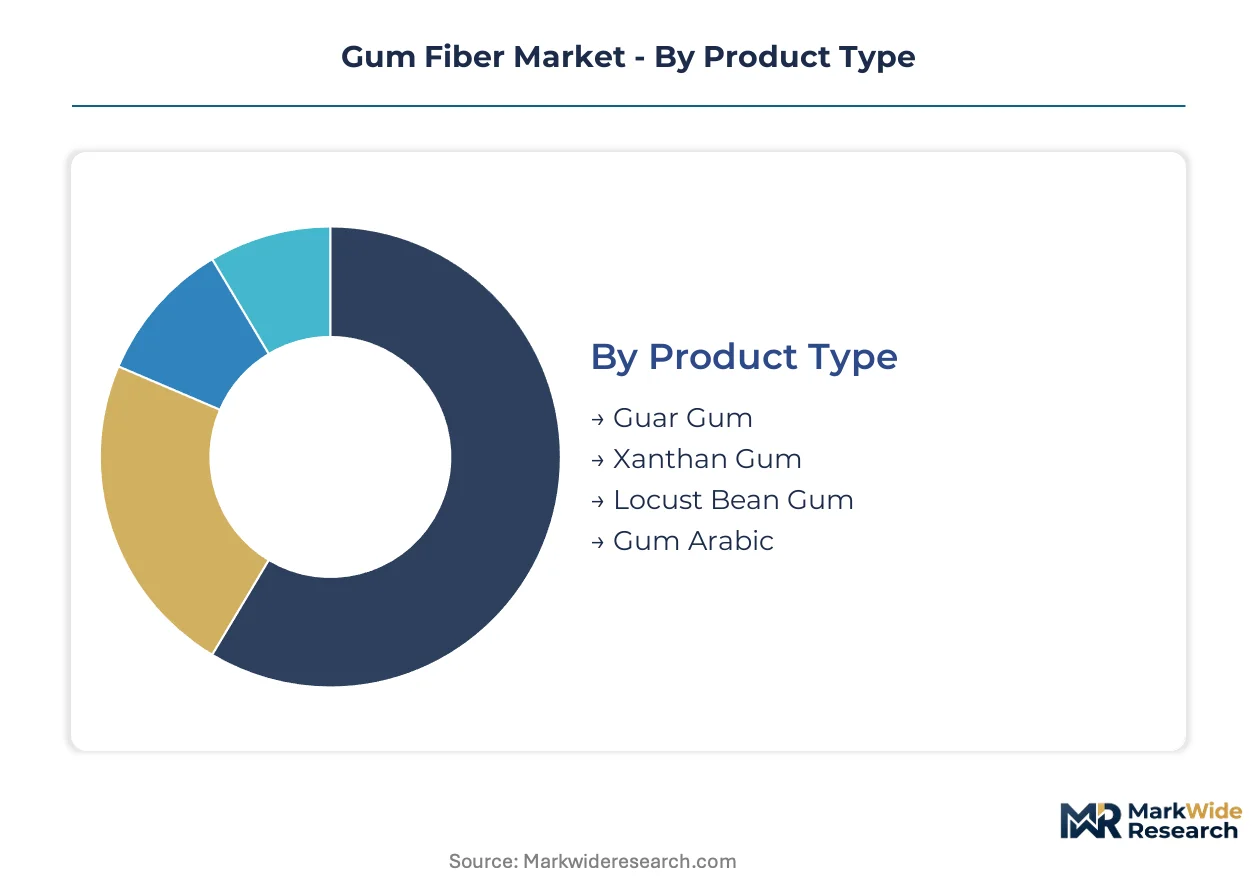
Gum fiber procurement patterns diverge sharply across product chemistry, end-use performance requirements, and formulation handling constraints. Suppliers must align extraction grades with distinct regulatory thresholds governing food safety, pharmaceutical purity, and industrial viscosity specifications.
Product Type:
Locust bean gum and gum arabic face intensifying displacement pressure from fermentation-derived alternatives and modified cellulose in cost-sensitive applications.
- Guar Gum:Galactomannan polysaccharide from Cyamopsis tetragonoloba seeds with exceptional cold-water hydration rates. Hydraulic fracturing operators in Texas specify high-viscosity grades for shale stimulation fluids, while FSSAI-regulated food processors in Rajasthan demand split-grade purity for domestic nutritional labeling.
- Xanthan Gum:Extracellular polysaccharide from Xanthomonas campestris fermentation delivering temperature-stable pseudoplasticity. Gluten-free bakery formulators in Germany and France specify this grade for dough rheology where freeze-thaw stability justifies premium positioning over seed-derived alternatives.
- Locust Bean Gum:Carob seed extract with synergistic gelation properties when combined with carrageenan or xanthan in dairy applications.
- Gum Arabic:Acacia senegal exudate prized for low-viscosity emulsification in beverage flavor encapsulation and confectionery glazing.
Guar gum retains volume leadership; xanthan gum holds the steepest expansion curve.
End Use Industry:
Cost tier stratification separates commodity-grade supply for industrial applications from certified pharmaceutical and food-grade extraction protocols.
- Food & Beverage:Clean-label reformulation mandates from major retailers are compressing certification timelines for hydrocolloid suppliers serving nutritional bar, dairy alternative, and reduced-sugar beverage categories across FDA and EFSA jurisdictions.
- Pharmaceuticals:USP-NF and EP compliance requirements for suspending agents and controlled-release matrices command 40-60% price premiums over food-grade equivalents due to endotoxin and microbial specification stringency.
- Cosmetics:K-beauty formulators in South Korea specify natural-origin gum fibers for skincare emulsion stability, displacing synthetic carbomer and acrylate alternatives.
- Textiles:Sizing and printing applications in India's Surat and Tirupur clusters consume lower-purity guar derivatives where color fastness rather than food safety governs procurement.
Food and beverage commands procurement volume; pharmaceuticals deliver the widest margin dispersion.
Formulation Type:
Application-driven handling requirements determine whether processors invest in instantized powder technologies or liquid dispersion systems.
- Powder:Standard milled grades dominate bulk industrial procurement, though agglomerated instant variants command premiums in automated bakery mixing operations where dust control and hydration speed reduce processing downtime.
- Liquid:Pre-hydrated suspensions eliminate dissolution equipment requirements for mid-scale sauce manufacturers and ready-to-drink beverage co-packers with limited shear-mixing capacity.
- Granules:Intermediate particle size for controlled-release pharmaceutical tablets and veterinary feed premixes where uniform distribution prevents ingredient segregation.
- Paste:High-solids concentrates for textile sizing operations and oilfield friction-reducer applications requiring immediate viscosity development without hydration lag.
Powder formulations retain volume leadership; liquid dispersions are climbing the fastest in convenience-driven food manufacturing.
Distribution Channel:
Customer scale and certification documentation intensity separate direct procurement relationships from trader-mediated supply chains.
- Distributors:Technical specialists like Brenntag and Univar Solutions maintain regional warehousing for just-in-time delivery to mid-scale food processors requiring lot traceability and COA documentation.
- Wholesalers:Volume aggregation for industrial textile and oilfield applications where specification uniformity matters less than price per metric ton and freight consolidation.
- Online:E-procurement platforms serving small-scale cosmetics startups and research institutions with sample quantities and rapid fulfillment.
- Retail:Consumer-packaged gum fiber for home brewing, gluten-free baking enthusiasts, and specialty food hobbyists through Amazon and specialty ingredient storefronts.
Distributors retain volume leadership; online channels are gaining share fastest among specialty and startup formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rajasthan processing clusters export refined guar gum derivatives to North American oilfield operators and European food manufacturers, establishing India as the dominant supply corridor for global hydrocolloid flows.
United States
Texas shale operators consume high-viscosity guar gum grades for hydraulic fracturing fluids, while FDA's 21 CFR 101.9 dietary fiber definition enables qualified health claims in nutritional bars. Houston and Midland oilfield service hubs coordinate just-in-time procurement from Indian refiners.
Germany
Gluten-free bakery formulators in Bavaria and North Rhine-Westphalia specify xanthan gum for dough rheology stability. EFSA's tightened Article 13.1 health claim substantiation demands randomized controlled trials for prebiotic positioning. Hamburg distributors maintain regional warehousing for just-in-time delivery to mid-scale processors.
India
Rajasthan and Gujarat processing zones supply global hydrocolloid demand amid monsoon-dependent seed availability. FSSAI purity certifications and BIS standards govern split-grade extraction for domestic food and export markets. Jodhpur and Bikaner refiners face chemical engineer shortages for solvent recovery optimization.
Brazil
Underdeveloped acacia harvesting infrastructure in the Cerrado biome offers supply diversification beyond Sudan and Senegal. ANVISA regulates food-grade gum imports while domestic cosmetics formulators specify natural-origin texturizers. São Paulo distributors aggregate volume for South American manufacturing networks.
China
SAMR oversees food additive safety assessments for imported gum fibers while domestic processors expand microbial fermentation capacity. Yangtze River Delta pharmaceutical manufacturers demand USP-NF compliant suspending agents for parenteral formulations. Shanghai technical distributors bridge specification gaps between Indian suppliers and domestic formulators.
Gum Fiber Market Vendor Landscape
Player mix skews toward agricultural processors with botanical extraction heritage and fermentation specialists with microbial production platforms. Market structure fragments across seed-gum refiners, exudate harvesters, and biotech-enabled alternatives. Strategic archetypes include Rajasthan-based guar processors, European acacia distributors, and fermentation-derived hydrocolloid innovators. Dominant competitive moves encompass direct-procurement relationships with food manufacturers and precision fermentation scale-up for pharmaceutical-grade substitutes.
Within the agricultural processing tier, Nexira exemplifies European acacia supply chain anchoring through French botanical extraction heritage, while Cargill occupies a diversified position spanning guar and xanthan categories through broad agricultural sourcing networks. Ingredion Incorporated represents the clean-label texturizing systems specialization that differentiates portfolio positioning from commodity gum suppliers.
| Leading Market Players |
|---|
| AEP Colloids |
| Nexira |
| Cargill |
| Ingredion Incorporated |
| BASF SE |
| DuPont de Nemours |
| Neelkanth Polymers |
| Nutriroma |
| Kerry Group |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Rajasthan guar gum refiners shapes both regional supply concentration and price floors for global hydrocolloid procurement. Oilfield service operators in Texas negotiate long-term offtake contracts that buffer processing clusters against monsoon-driven seed volatility, while food-grade certification tiers segment pricing power across FSSAI-regulated and API-specified grades.
Pricing Analysis
Conventional seed-extraction technology commands commodity pricing against precision fermentation alternatives capturing 40-60% premiums in pharmaceutical suspensions. Three-tier pricing structure across premium, standard, and economy levels separates USP-NF compliant pharmaceutical grades from FSSAI-certified food splits and industrial oilfield specifications. Cost compression in standard food-grade tiers is intensifying because cellulose gum substitution pressures guar derivatives in sauce applications. Mid-scale dairy and bakery manufacturers exhibit highest price sensitivity, while parenteral drug formulators show minimal elasticity due to endotoxin specification stringency.
Supply Chain Analysis
Container availability on the Mundra-Houston trade lane directly constrains just-in-time delivery schedules for Texas shale operators. Raw material sourcing centers on India, Sudan, and Senegal for acacia and guar exudates, with microbial fermentation capacity concentrated in China and the Netherlands. Solvent recovery systems for food-grade gum splits draw from specialized chemical engineering talent pools in Rajasthan processing zones. Single-source vulnerability pervades xanthan gum fermentation due to limited geographic diversification among Xanthomonas campestris specialists. Distribution runs through technical specialists like Brenntag and Univar Solutions maintaining regional warehousing for mid-scale processors requiring lot traceability documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized extraction expertise shortages in Rajasthan processing zones constrain capacity expansion timelines for food-grade certification upgrades. This capability gap separates incumbents with established solvent recovery optimization from entrants facing qualification bottlenecks.
For Market Incumbents: Compound backward integration into Rajasthan seed procurement cooperatives to secure monsoon-resistant supply volumes against fermentation-derived substitutes. Invest in dual-grade certification infrastructure serving both FSSAI food purity and API friction-fluid specifications to defend margin position against cellulose gum displacement in cost-sensitive dressing applications.
For New Entrants and Emerging Players: Anchor in Brazilian Cerrado acacia harvesting infrastructure development to bypass Sudanese supply concentration and capture EU Green Deal biomass incentives. Target South Korean K-beauty cosmetic formulators specifying natural-origin rheology modifiers, leveraging e-procurement platforms for rapid sample fulfillment and technical documentation support.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation-derived hydrocolloid specialists with pharmaceutical-grade endotoxin control capabilities over conventional seed-gum refiners exposed to agricultural volatility. Five-to-ten year viability hinges on clinical evidence substantiation for prebiotic health claims under EFSA Article 13.1 frameworks. The signal to monitor is randomized controlled trial publication timelines for acacia gum gut function benefits.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Procurement | Rajasthan cooperative partnerships reduce monsoon exposure for oilfield contract fulfillment. |
| Dual-Grade Certification Infrastructure | FSSAI and API specifications expand addressable market across food and industrial segments. |
| Precision Fermentation Scale-Up | Microbial cellulose alternatives command pharmaceutical premiums while bypassing agricultural risk. |
| Cerrado Harvesting Infrastructure Development | Brazilian acacia diversification unlocks EU Green Deal preferential access versus synthetic competitors. |
| Clinical Evidence Investment for Health Claims | EFSA-compliant randomized trials defend prebiotic positioning against tightened substantiation requirements. |
Methodological Framework
The analysis maps guar gum refining, xanthan gum fermentation, acacia harvesting, and cellulose gum processing segments, each validated through extraction plant managers, food manufacturer procurement leads, oilfield service chemical engineers, and pharmaceutical formulation scientists. Primary interview findings triangulate against FSSAI certification databases, FDA 21 CFR 101.9 dietary fiber guidance, EFSA health claim registers, and Rajasthan agricultural ministry seed production statistics. Bottom-up capacity modeling and top-down end-use demand aggregation cross-validate volume estimates.
Consistency checks against external benchmarks validated projection outputs across the analysis window. Segmentation dimensions include product chemistry, end-use industry performance requirements, formulation handling constraints, and distribution channel documentation intensity. CAGRs derive from installed capacity utilization trends, substitution elasticity estimates, and regulatory claim qualification timelines. Forecast inputs incorporate monsoon variability indices for Rajasthan seed yields and fermentation capacity expansion announcements.
Material uncertainties — monsoon failure severity, EFSA health claim revocation decisions, and precision fermentation yield breakthroughs — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory stability and agricultural productivity baselines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Apple Fiber Market
Natural Fibers
Woolen Textiles Market
Natural Fibers
Spent Coffee Grounds Fiber Market
Natural Fibers
Textile Staples Market
Natural Fibers
Cellulose Acetate Fiber Market
Natural Fibers
Fenugreek Fiber Market
Natural Fibers
Natural Fibers and Sisal Market
Natural Fibers
Modal Fiber Market
Natural Fibers
Thailand Textile Market
Natural Fibers
Lignocellulosic Fibers Market
Natural Fibers
Cashmere Clothing Market
Natural Fibers
Global Rattan Products Market
Natural Fibers
Silk Fabric Market
Natural Fibers
North America Cotton Market
Natural Fibers
Natural Fibers Market
Natural Fibers
Natural Fiber Composite (NFC) Market