
 Global Cellulosic Man-Made Fibers Market | 2026-2036
Global Cellulosic Man-Made Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cellulosic Man-Made Fibers Market Analysis
Fast-fashion retailers are collapsing their reliance on conventional viscose as sustainability audits intensify, while premium apparel brands gain procurement share. Lenzing AG leverages its Tencel lyocell platform to dominate closed-loop production in Europe. Sateri Holding Group anchors its position through integrated pulp-to-fiber operations across Southeast Asia. Aditya Birla Group sustains cost leadership via massive viscose scale in India and Indonesia.
Cellulosic man-made fibers derive from regenerated cellulose extracted primarily from wood pulp, processed through either the viscose xanthate route or the direct-dissolution NMMO method used for lyocell, yielding filaments with tenacities ranging from 2.0 to 4.5 g/denier for textile applications. These fibers serve as biodegradable alternatives to petroleum-based synthetics in woven and nonwoven applications where moisture management and drape matter. Viscose still occupies the largest volume share but faces margin compression from environmental compliance costs, whereas lyocell captures the fastest growth trajectory as brands prioritize solvent-recyclable supply chains. Modal fibers differentiate through superior softness in intimate apparel, concentrating margin pools in premium fashion segments.
The EU Green Deal and REACH chemical restrictions in Europe compel producers to eliminate carbon disulfide emissions from viscose manufacturing, while China's MEE enforces wastewater standards that raise entry barriers for smaller mills. India's BIS certification for textile safety and the PLI scheme for man-made fibers redirect investment toward technical nonwoven grades. Stakeholders must monitor regulatory divergence between Asian production hubs and European consumption markets when siting new capacity or qualifying suppliers.
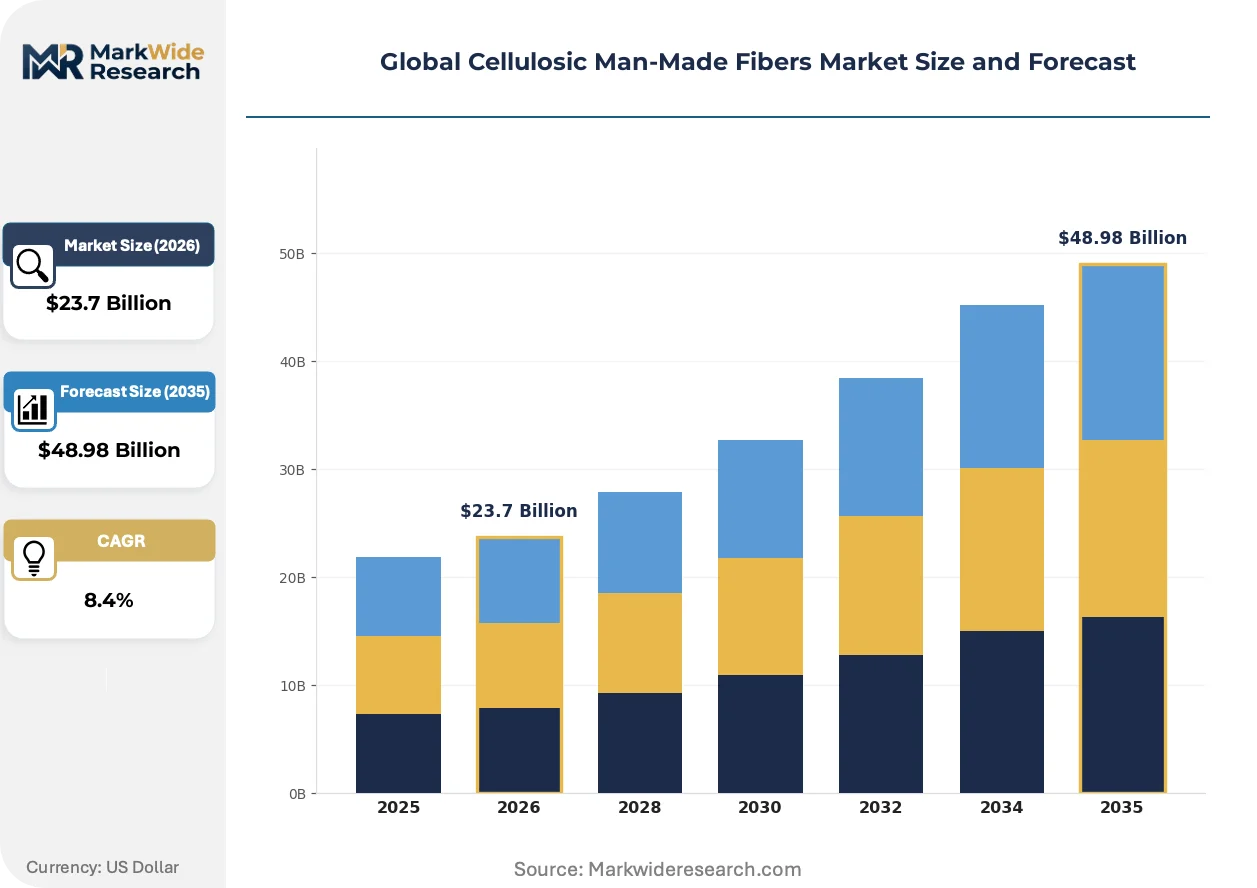
Market Dynamics
The EU Green Deal's chemical discharge mandates are forcing a production-method transition across the cellulosic fiber value chain, compressing conventional viscose margins while accelerating closed-loop lyocell capacity investments.
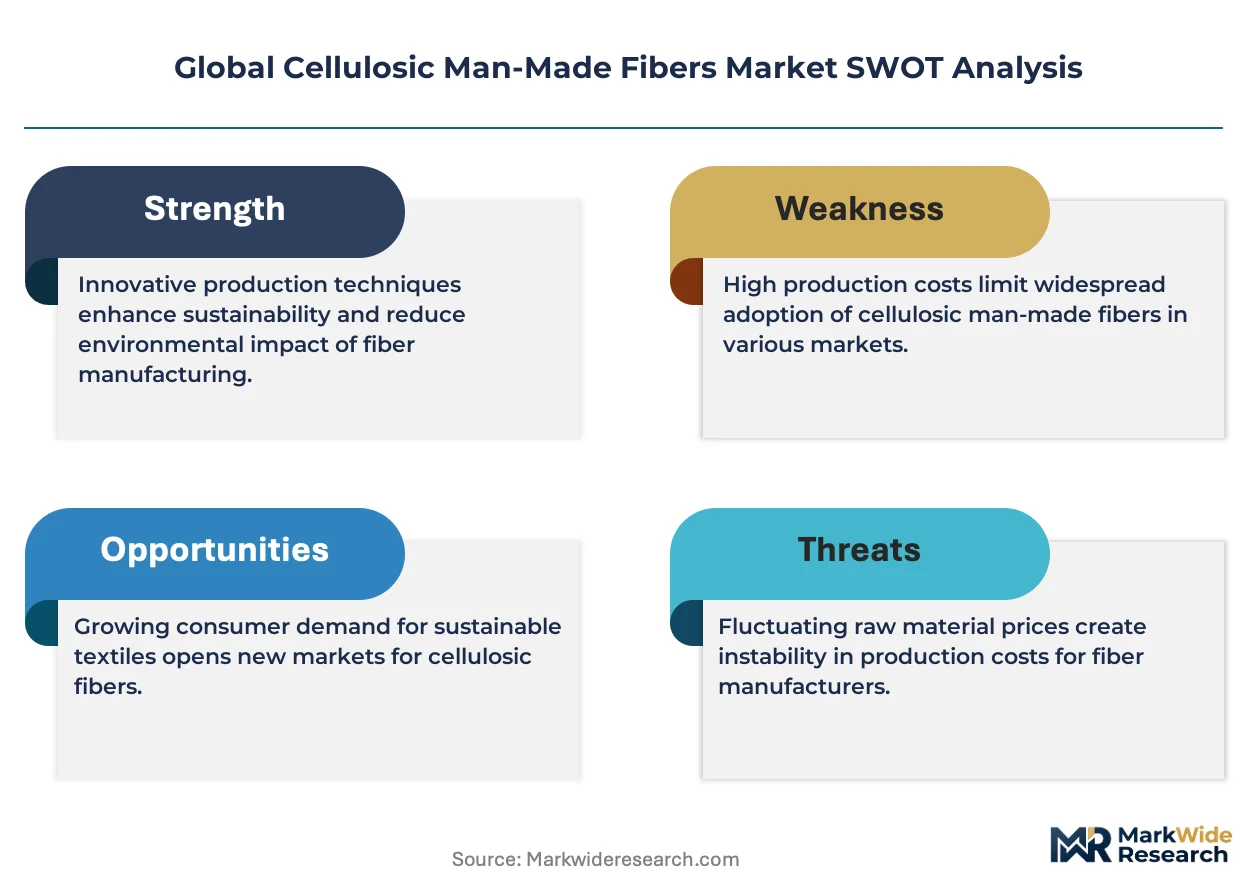
Growth Catalysts
- REACH chemical restrictions:European regulators now enforce carbon disulfide emission limits that disqualify conventional viscose from premium apparel supply chains.
- Intimate apparel softness specifications:Modal fiber demand concentrates in lingerie and loungewear segments where drape and hand-feel command price premiums.
- Integrated pulp-to-fiber operations:Southeast Asian production clusters capture cost advantages through captive dissolving pulp supply and captive energy generation.
Market Restraints
- Dissolving pulp price volatility:Hardwood pulp input costs swing with construction lumber cycles and paper-grade competition for wood chip supply.
- Single-region supply concentration:China, India, and Indonesia together host over seventy percent of new viscose and modal capacity additions.
- Mechanical recycling incompatibility:Cellulosic fibers degrade in standard textile shredding systems, blocking circular economy participation.
Strategic Opportunities
- India PLI scheme for man-made fibers:Production-linked incentives redirect capital toward technical nonwoven grades for medical and filtration applications.
- Agricultural residue feedstocks:Bamboo, wheat straw, and rice husk cellulose extraction opens sourcing beyond timber-dependent dissolving pulp.
- Direct-to-brand digital platforms:Fiber producers bypass trading houses to capture margin through mill-direct relationships with mid-sized apparel brands.
Industry Challenges
- NMMO solvent handling expertise:Lyocell production requires chemical engineers trained in amine oxide recovery systems, a scarce specialization outside Austria and China.
- Multi-standard certification timelines:Simultaneous pursuit of OEKO-TEX, FSC chain-of-custody, and EU Ecolabel approvals extends qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cellulosic Man-Made Fibers Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Viscose, Lyocell, Modal, Acetate Application: Textiles, Nonwovens, Automotive, Medical End User: Fashion, Interior Design, Home Textiles, Industrial Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Supermarkets |
| Companies Covered | Lenzing AG, Aditya Birla Group, Sateri Holding Group, Eastman Chemical Company, Kelheim Fibres GmbH, Daicel Corporation, Formosa Chemicals & Fibre Corporation, Fulida Group Holding Co., Ltd, Celanese Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cellulosic Man-Made Fibers Market Emerging Trajectories
Closed-loop solvent recovery systems and alternative cellulose feedstocks are restructuring competitive advantage in cellulosic fiber manufacturing. These developments compress the cost gap between conventional and sustainable production routes.
Direct-dissolution lyocell technology using N-methylmorpholine-N-oxide solvent is decomposing the historical cost premium of closed-loop manufacturing. Premium denim and activewear brands in Germany and Japan now specify lyocell blends at scale volumes previously reserved for commodity viscose. This solvent-recyclable route is decomposing the environmental compliance cost structure that burdened European viscose producers.
China's MEE wastewater discharge standards for chemical fiber manufacturing now mandate tertiary treatment for sulfate and zinc removal. Small and mid-sized viscose mills face consolidation pressure as compliance capex exceeds replacement economics. The Indonesian and Indian export-oriented sectors are responding with effluent recycling investments to maintain EU market access.
Apparel brand technical teams now embed fiber provenance requirements directly into purchase order terms rather than relying on supplier self-certification. Trading houses and commission agents lose influence as direct mill-brand relationships displace layered procurement. This pattern concentrates in European fast-fashion and premium outdoor segments where supply chain transparency carries consumer-facing value.
Global Cellulosic Man-Made Fibers Market Segmentation
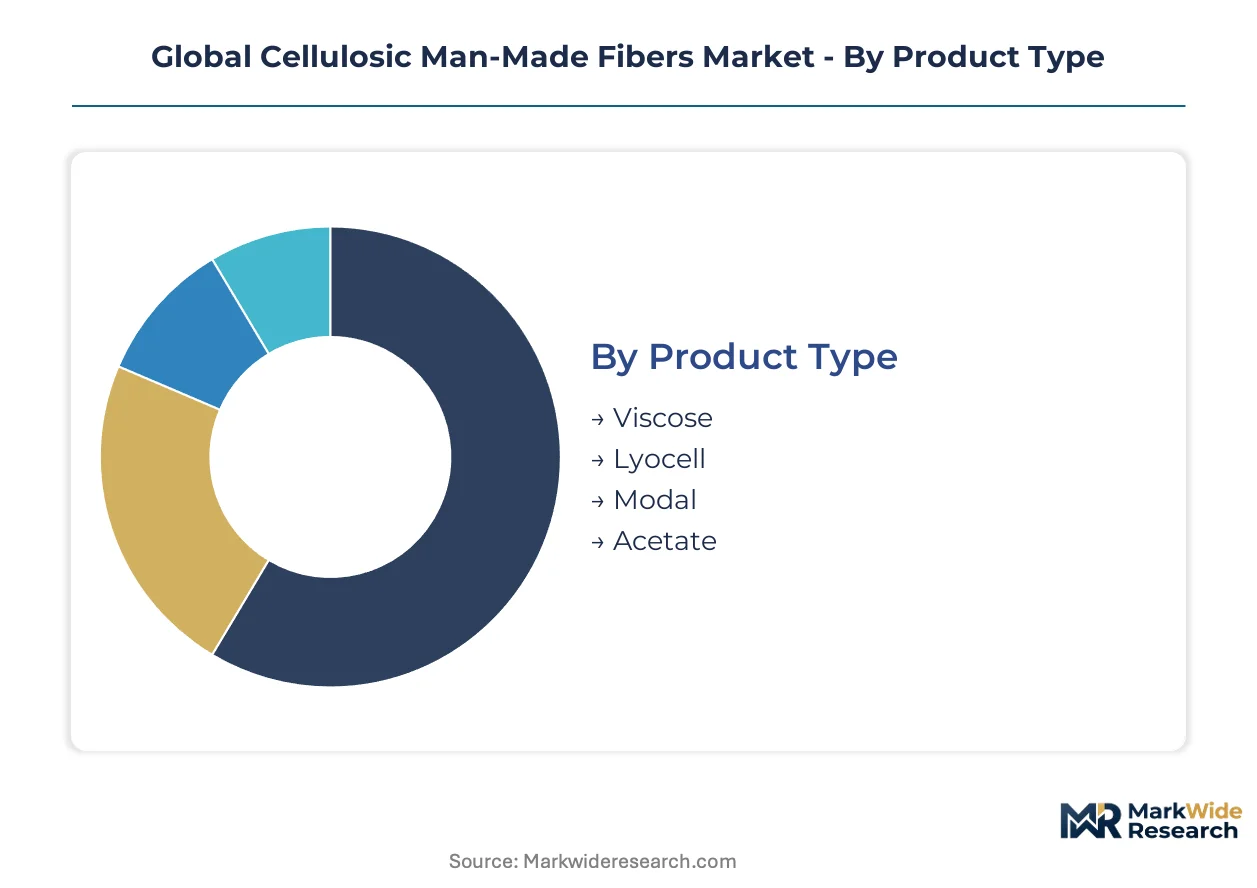
Segmentation in cellulosic fibers separates commodity-scale viscose from premium lyocell and modal grades, each commanding distinct compliance requirements and margin structures. Procurement teams route volume orders through integrated pulp-to-fiber producers while specialty grades move via direct mill-brand relationships.
Product Type:
Domestic consumption in India and Indonesia favors viscose for mass-market apparel, whereas European and Japanese brands drive export-led demand for lyocell and modal through sustainability-mandated supply chains.
- Viscose:Manufactured through the xanthate process using carbon disulfide, this fiber delivers tenacities of 2.0-2.5 g/denier for woven fashion fabrics. Indian and Indonesian mills supply bulk volumes to fast-fashion retailers facing REACH chemical restrictions in Europe. Margin compression from wastewater compliance costs is forcing consolidation among smaller Chinese producers.
- Lyocell:Direct-dissolution production with N-methylmorpholine-N-oxide solvent enables closed-loop solvent recovery exceeding 99%. German denim brands and Japanese activewear manufacturers specify lyocell blends at volumes previously reserved for commodity grades, capturing biodegradable positioning without petroleum-based synthetics.
- Modal:High-wet-modulus variant of viscose processed with modified spinning parameters for enhanced softness and dimensional stability. Lingerie and loungewear segments in France and Italy concentrate demand.
- Acetate:Cellulose acetate fiber produced through acetylation of wood pulp, limited to specialty linings and filtration media. Niche applications in luxury apparel and cigarette filters sustain small-scale production.
Viscose commands the established base. The steepest expansion runs through lyocell.
Application:
Cost tier separation distinguishes high-volume textile weaving from technical nonwoven grades commanding certification premiums in medical and filtration markets.
- Textiles:Woven and knitted fabrics for apparel and home furnishings represent the dominant consumption channel. Indian spinning mills blend viscose with cotton for cost-optimized shirting, while Austrian and Chinese lyocell producers serve premium European fashion houses with solvent-recyclable supply chains.
- Nonwovens:Spunlaid and hydroentangled structures for wipes, hygiene products, and technical filtration. India's PLI scheme for man-made fibers is redirecting capital toward medical-grade nonwoven capacity in Gujarat and Tamil Nadu.
- Automotive:Molded interior trim and seat fabrics requiring flame-retardant treatments. German OEM specifications favor lyocell for reduced volatile organic compound emissions.
- Medical:Surgical gowns, drapes, and wound dressings demanding biocompatibility certification. Sterilization compatibility limits viable fiber sources to controlled-process lyocell and modal grades.
Textiles anchor volume throughput. Medical applications are climbing the fastest.
End User:
Customer type stratification separates brand-driven fashion procurement from specification-bound industrial buyers with divergent transparency requirements.
- Fashion:Apparel brands from fast-fashion to luxury segments specifying fiber provenance in purchase order terms. Zara and H&M parent companies audit viscose suppliers for carbon disulfide emissions, while premium outdoor brands in Switzerland mandate FSC chain-of-custody documentation.
- Interior Design:Upholstery, wall coverings, and decorative textiles for commercial and residential spaces. Flame-retardant regulations in UK and French building codes constrain fiber selection.
- Home Textiles:Bedding, towels, and kitchen textiles where moisture absorption and drape drive preference. Modal dominates premium bed linen segments in Nordic markets.
- Industrial:Conveyor belts, hoses, and reinforcement materials requiring high tenacity. Technical specifications favor acetate and high-strength viscose variants.
Fashion directs procurement innovation. Interior design is gaining share fastest.
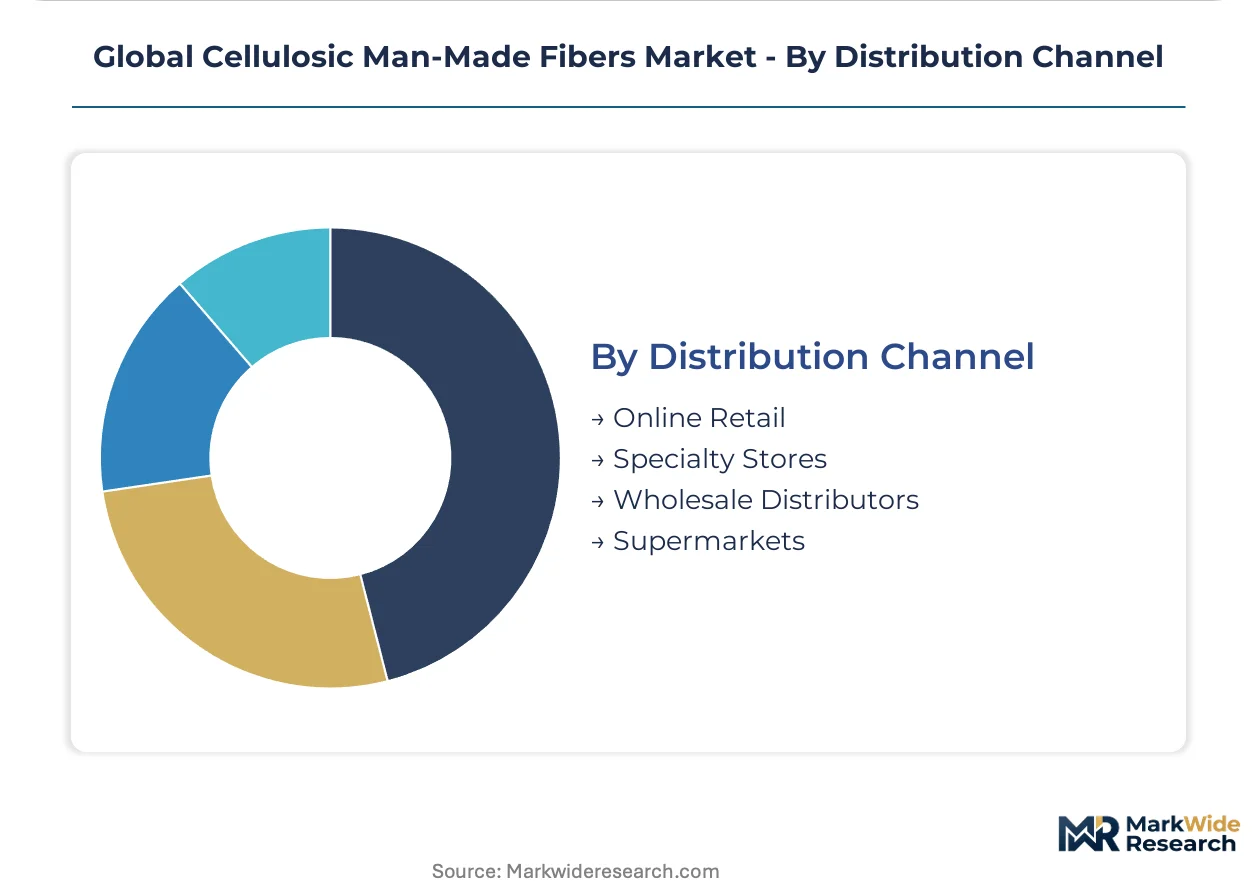
Distribution Channel:
Supply concentration patterns show integrated producers bypassing traditional trading houses to capture margin through direct relationships.
- Online Retail:Direct-to-brand digital platforms enabling fiber producers to sell spun yarn and finished fabric without commission agents. Lenzing's e-brand portal connects Tencel lyocell directly to mid-sized apparel manufacturers.
- Specialty Stores:Regional yarn distributors serving small-batch weavers and knitters in Italy's Como silk district and Japan's Bishu wool region.
- Wholesale Distributors:Trading houses historically dominating volume procurement from Chinese and Indonesian mills, now losing influence as brands enforce direct mill qualification.
- Supermarkets:Mass-market home textile retailers in UK and Germany sourcing private-label bedding and towels through consolidated viscose supply agreements.
Wholesale distributors retain legacy volume. Online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia exports viscose staple fiber to European fast-fashion supply chains under tightening EU Green Deal chemical discharge rules. China ships lyocell and modal grades to Japanese activewear brands seeking biodegradable alternatives to petroleum-based synthetics. India directs technical nonwoven output toward Middle Eastern medical textile markets.
China
MEE wastewater standards mandate tertiary treatment for sulfate and zinc removal from viscose production. The Yangtze River Delta hosts consolidation pressure on small and mid-sized mills where compliance capex exceeds replacement economics. Nantong and Hangzhou clusters concentrate closed-loop lyocell capacity expansion serving German denim specifications.
Indonesia
Export-oriented viscose producers supply EU apparel brands auditing for carbon disulfide emissions under REACH restrictions. The country's national environmental regulator enforces effluent recycling investments to maintain European market access. Purwakarta and Karawang industrial zones anchor integrated pulp-to-fiber operations with captive dissolving pulp supply.
India
BIS certification for textile safety and the PLI scheme for man-made fibers redirect capital toward technical nonwoven grades. Gujarat spinning mills blend viscose with cotton for cost-optimized shirting serving domestic mass-market apparel. Tamil Nadu medical textile clusters in Coimbatore and Tiruppur scale lyocell capacity for surgical gown exports.
Germany
EU Green Deal chemical discharge mandates disqualify conventional viscose from premium apparel supply chains. ECHA enforces carbon disulfide emission limits that compress margins for non-compliant imports. Saxony-Anhalt and Thuringia host lyocell research partnerships between fiber producers and technical universities advancing NMMO solvent recovery systems.
Austria
REACH compliance requirements position Austrian lyocell producers as qualified suppliers to Swiss and French premium outdoor brands. The country's national standards body coordinates FSC chain-of-custody certification for wood pulp feedstocks. Upper Austria industrial zones concentrate closed-loop production expertise in amine oxide recovery systems.
Global Cellulosic Man-Made Fibers Market Vendor Landscape
Listed leaders compete with private specialists across capital access and operational flexibility dimensions. The vendor base separates into three tiers: integrated pulp-to-fiber conglomerates with captive raw material supply, specialty lyocell producers commanding solvent-recovery technical expertise, and regional viscose mills competing on scale economies. Strategic moves concentrate on backward integration into dissolving pulp production and direct-to-brand digital platform development that bypasses traditional trading houses.
Within the integrated conglomerate tier, Lenzing AG and Aditya Birla Group exemplify divergent geographic positioning strategies. Lenzing occupies a position representing European closed-loop lyocell leadership through its Tencel platform. Aditya Birla Group anchors cost-driven viscose scale across Indian and Indonesian production clusters. Sateri Holding Group sits within the Southeast Asian specialist archetype, representing integrated operations from pulp through finished fiber.
| Leading Market Players |
|---|
| Lenzing AG |
| Aditya Birla Group |
| Sateri Holding Group |
| Eastman Chemical Company |
| Kelheim Fibres GmbH |
| Daicel Corporation |
| Formosa Chemicals & Fibre Corporation |
| Fulida Group Holding Co., Ltd |
| Celanese Corporation |
| Others |
Supply Flow & Price Mechanics
EU Green Deal chemical discharge mandates gate both supply qualification and price differentiation simultaneously, forcing producers to absorb compliance costs or exit premium apparel channels entirely. REACH carbon disulfide emission limits disqualify conventional viscose from European fast-fashion supply chains, compressing margins for non-compliant mills while lyocell producers capture certification premiums.
Pricing Analysis
Prior-generation viscose, current-generation modal, and next-generation lyocell technologies stratify across distinct price bands. Three-tier pricing structure across premium, standard, and economy levels reflects solvent-recovery certification status and FSC chain-of-custody documentation. Pricing pressure stems from China's MEE wastewater compliance capex burdening smaller mills. Fast-fashion retailers exhibit highest price sensitivity, while Swiss and French premium outdoor brands accept substantial premiums for closed-loop provenance.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes intermittently disrupt dissolving pulp inbound flows to Indonesian and Indian mill complexes. China, Indonesia, and India concentrate over seventy percent of new viscose and modal capacity additions. Production draws from hardwood pulp feedstocks, N-methylmorpholine-N-oxide solvent systems, and captive energy generation. Single-region supply concentration creates tariff exposure vulnerability. Distribution runs through direct-to-brand digital platforms displacing traditional trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs fiber procurement as Lenzing's Tencel e-brand portal demonstrates interoperability between mill qualification systems and brand technical specifications. Direct digital interfaces are displacing layered trading relationships.
For Market Incumbents: Shield European market position by accelerating NMMO solvent recovery capacity in Austria and Germany before REACH enforcement tightens. Deepen upstream control over dissolving pulp supply through captive forestry operations in Southeast Asia. Certification investment in simultaneous OEKO-TEX and EU Ecolabel approval extends qualification cycles but locks out commodity competitors.
For New Entrants and Emerging Players: Agricultural residue feedstock processing represents an underserved service layer where timber-dependent incumbents lack technical capability. Target medical-grade nonwoven segments in India under PLI scheme incentives with bamboo and wheat straw cellulose extraction. Go-to-market leverage rests on biocompatibility certification for surgical gown applications.
For Investors and Strategic Acquirers: Carve-out targets emerge from integrated pulp-to-paper conglomerates seeking to divest non-core fiber assets. Long-term viability favors producers with demonstrated amine oxide recovery expertise and FSC-certified feedstock access. Watch for consolidation signals when Chinese MEE enforcement triggers distressed capacity sales.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dissolving Pulp | Captive hardwood pulp supply insulates Sateri and Aditya Birla from construction lumber cycle volatility. |
| Closed-Loop Lyocell Capacity Expansion | Nantong and Hangzhou clusters capture German denim brand specifications through NMMO solvent recovery. |
| Direct-to-Brand Digital Platform Launch | Lenzing's Tencel portal eliminates commission agents and captures margin from mid-sized apparel manufacturers. |
| Agricultural Residue Feedstock Development | Bamboo and wheat straw cellulose extraction opens sourcing beyond timber-dependent supply chains. |
| Medical Nonwoven Certification Investment | Tamil Nadu lyocell capacity targets Middle Eastern surgical gown markets through biocompatibility approval. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the value chain, including fiber procurement managers at European fast-fashion retailers, plant engineers at Indonesian viscose mills, technical directors at lyocell research partnerships in Saxony-Anhalt, and sustainability auditors certifying FSC chain-of-custody. Secondary validation drew from EU ECHA enforcement disclosures, China MEE wastewater discharge filings, India PLI scheme administrative records, and customs trade data for dissolving pulp imports. Bottom-up capacity assessments and top-down consumption estimates were triangulated.
Across the analysis window, forecasts were constructed through segmented modeling of product type, application, end user, and distribution channel dimensions. CAGRs were derived from slope analysis of year-over-year progression curves. Industry-specific inputs included REACH compliance cost trajectories, MEE enforcement intensity indices, and PLI scheme capital redirection patterns.
Underlying assumptions cover sustained EU Green Deal enforcement, China MEE consolidation pressure, and India PLI scheme continuity, with deviation risk concentrated in regulatory divergence between Asian production hubs and European consumption markets. Practitioners should keep alternative scenarios live as chemical discharge standards and agricultural residue processing economics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Silk Mask Market
Natural Fibers
Cellulose Acetate Fiber Market
Natural Fibers
North America Lyocell Fiber Market
Natural Fibers
Global Hemp Fiber Market
Natural Fibers
Jute Bags Market
Natural Fibers
Down and Feather Market
Natural Fibers
Cellulose Fiber Market
Natural Fibers
Sugarcane Fiber Market
Natural Fibers
Abaca Fiber Market
Natural Fibers
Spent Coffee Grounds Fiber Market
Natural Fibers
Natural Cotton Extract Market
Natural Fibers
Woolen Textiles Market
Natural Fibers
Bamboo Fibers Market
Natural Fibers
Silk Fabric Market
Natural Fibers
Organic Cotton Market
Natural Fibers
Green Fibers Market