
 Natural Cotton Extract Market | 2026-2036
Natural Cotton Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Cotton Extract Market Foresight
Clean-label cosmetics manufacturers are collapsing legacy procurement patterns that favored petrochemical moisturizers, redirecting formulation budgets toward botanical alternatives with traceable supply chains. Plexus Cotton Ltd. leverages its Lancashire-based ginning heritage to secure premium linter streams for cosmetic-grade extraction. Arvind Limited anchors its position through captive cotton farming in Gujarat that feeds integrated refining operations serving pharmaceutical and textile clients. The Rajlakshmi Cotton Mills differentiates via Kolkata-based processing infrastructure purpose-built for organic-certified output.
Natural cotton extract denotes bioactive compounds—principally gossypol derivatives, flavonoids, and polysaccharides—recovered from cottonseed, linters, or burrs through solvent or supercritical CO₂ extraction, typically standardized to specified polyphenol content for industrial consistency. The material serves primarily as a functional ingredient in topical formulations, dietary supplements, and textile finishing baths where plant-derived performance replaces synthetic chemistry. Refined extract commands the dominant value share due to its compliance with pharmaceutical and premium cosmetic specifications that reject residual solvent thresholds. Liquid extract formats are gaining fastest in cosmetics manufacturing, where cold-process formulators prize pumpable, pre-dispersed inputs that eliminate powder-handling steps and shorten batch cycles.
REACH registration requirements in Europe govern residual solvent limits and impurity profiles for botanical extracts entering cosmetic and pharmaceutical channels, while USDA organic certification in North America constrains permitted extraction methods and agricultural input histories. India's BIS standards for herbal raw materials create a parallel compliance layer for domestic manufacturers and export-oriented refiners operating from Gujarat and Maharashtra. Stakeholders must monitor evolving purity thresholds across these jurisdictions to avoid batch rejection at customs or formulation disqualification from clean-label product lines.
Market Dynamics
Clean-label cosmetic formulators are collapsing legacy procurement patterns that favored petrochemical moisturizers, redirecting formulation budgets toward botanical alternatives with traceable supply chains. REACH compliance in Europe and USDA organic certification in North America are tightening purity thresholds for botanical inputs, compressing supplier qualification timelines and rewarding early certifiers.
Growth Catalysts
- REACH solvent limits:European ECHA enforcement of residual solvent thresholds disqualifies conventional extraction outputs, creating preferential demand for supercritical CO₂-refined cotton extract in pharmaceutical and premium cosmetic channels.
- India's integrated clusters:Gujarat and Tamil Nadu textile-cosmetic hubs process domestic cotton linters into export-grade extracts, reducing import dependency for global formulators seeking compliant botanical inputs.
- Cold-process cosmetics:Liquid extract formats eliminate powder-handling steps and shorten batch cycles, accelerating adoption among contract manufacturers serving clean-label beauty brands.
Market Restraints
- Gossypol toxicity thresholds:FDA and EMA limits on residual gossypol derivatives in topical and ingestible applications constrain extraction yields and increase refining costs for seed-derived outputs.
- Indian supply concentration:Overreliance on Gujarat and Maharashtra ginning infrastructure creates weather-linked volume volatility and quality inconsistency during monsoon-disrupted harvests.
- Synthetic emollient substitution:Petrochemical-derived squalane and dimethicone retain cost advantages in mass-market formulations, limiting cotton extract penetration below premium tier positioning.
Strategic Opportunities
- Brazilian organic cotton expansion:Cerrado and Northeast cultivation zones offer untapped linter supply for EU REACH-compliant extraction, diversifying sourcing beyond Indian dominance.
- Nutraceutical encapsulation:Microencapsulation of cotton-derived polysaccharides for controlled-release dietary supplements opens adjacent revenue streams beyond topical applications.
- USDA BioPreferred program:Federal procurement preferences for biobased textile finishing agents create mandated demand channels for cotton extract in institutional uniform and bedding supply chains.
Industry Challenges
- Supercritical CO₂ technician scarcity:Specialized equipment operation and maintenance expertise concentrates among legacy flavor and fragrance extraction firms, constraining capacity expansion for cotton-specific refiners.
- Organic certification timelines:Three-year transition periods for conventional cotton farms seeking USDA organic status delay qualified raw material availability and lock in supply bottlenecks.
- Cross-jurisdiction batch documentation:Reconciling REACH dossier requirements, BIS herbal standards, and FDA cosmetic ingredient listings multiplies compliance overhead for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Cotton Extract Market |
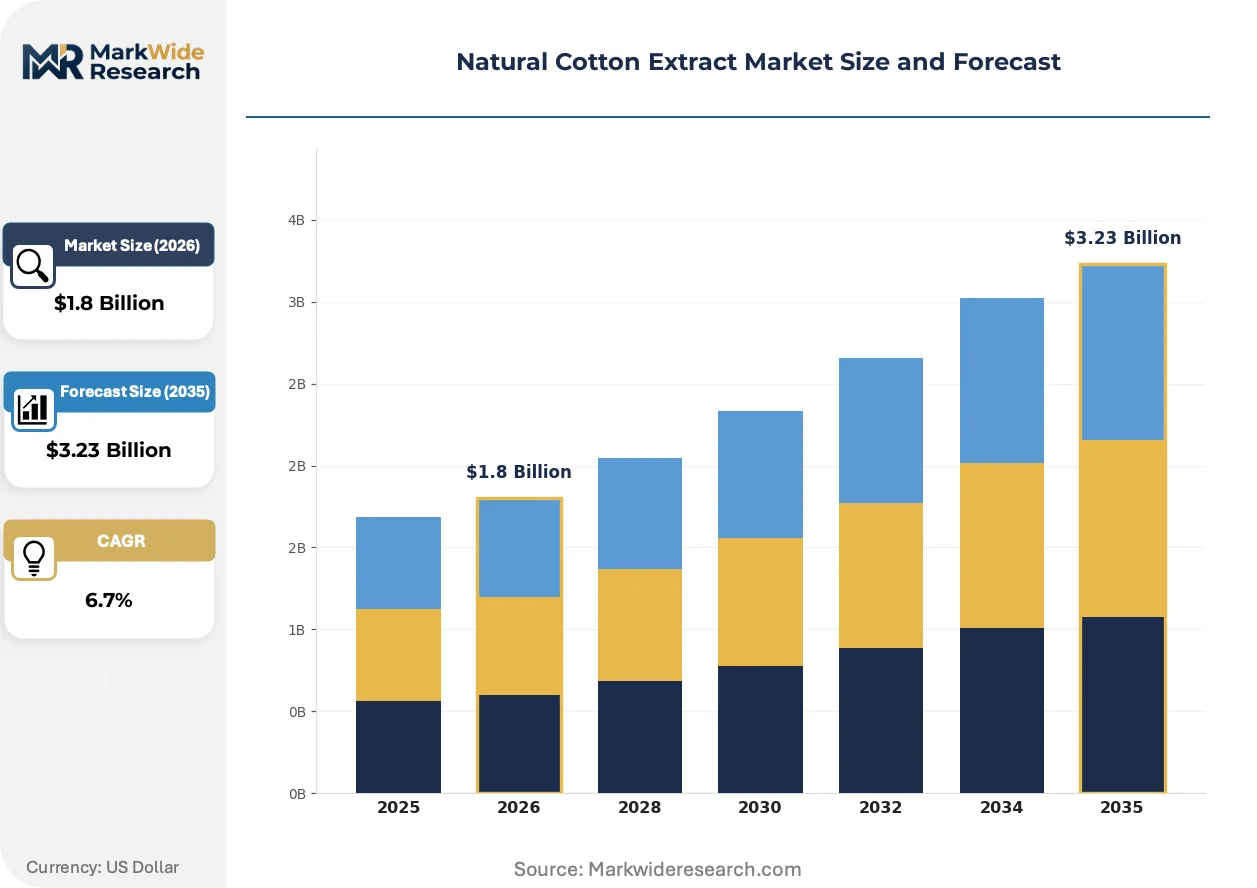
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Extract, Refined Extract, Powdered Extract, Liquid Extract Application: Cosmetics, Pharmaceuticals, Textiles, Food Additives End User: Manufacturers, Retailers, Wholesalers, Distributors Packaging Type: Bottles, Jars, Pouches, Bulk Containers |
| Companies Covered | KCC Beauty, Plexus Cotton Ltd., Botanicals Plus, Arvind Limited, The Rajlakshmi Cotton Mills, Carrubba Inc., Remei AG, Noble Ecotech, The Garden of Naturals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Cotton Extract Market Shifts & Advancements
Extraction technology and regulatory frameworks are actively reshaping competitive positioning in natural cotton extract supply chains. Three developments are compressing legacy process economics and reconfiguring buyer-supplier relationships across pharmaceutical, cosmetic, and textile end-uses.
Supercritical CO₂ extraction is bifurcating the refined extract segment into pharmaceutical-grade and cosmetic-grade supply tiers based on residual solvent thresholds. Premium cosmetic formulators in France and Switzerland are adopting this technology fastest, displacing hexane-based outputs from clean-label product lines. The structural consequence is compressing margins for conventional solvent refiners while rewarding capital-intensive supercritical operators with multi-year supply agreements.
EU CSRD disclosure requirements and the EU Green Deal's biobased content mandates are forcing cosmetic and textile manufacturers to document botanical input provenance. Industrial consequence includes mandatory supplier audits and blockchain-traceable batch records. Premium cosmetic brands with direct-to-consumer channels are most affected, responding by consolidating supplier bases to vertically integrated Indian and Turkish ginning-extraction operations.
Ingredient sourcing contracts are shortening from multi-year frameworks to 12-18 month agreements with price-reset clauses tied to cotton futures. Contract manufacturers serving indie beauty brands are most disrupted, replacing fixed-price annual orders with spot-market flexibility. This pattern is most visible in North American procurement, where clean-label startups prioritize supply security over cost predictability during cotton price volatility.
Natural Cotton Extract Market Segmentation
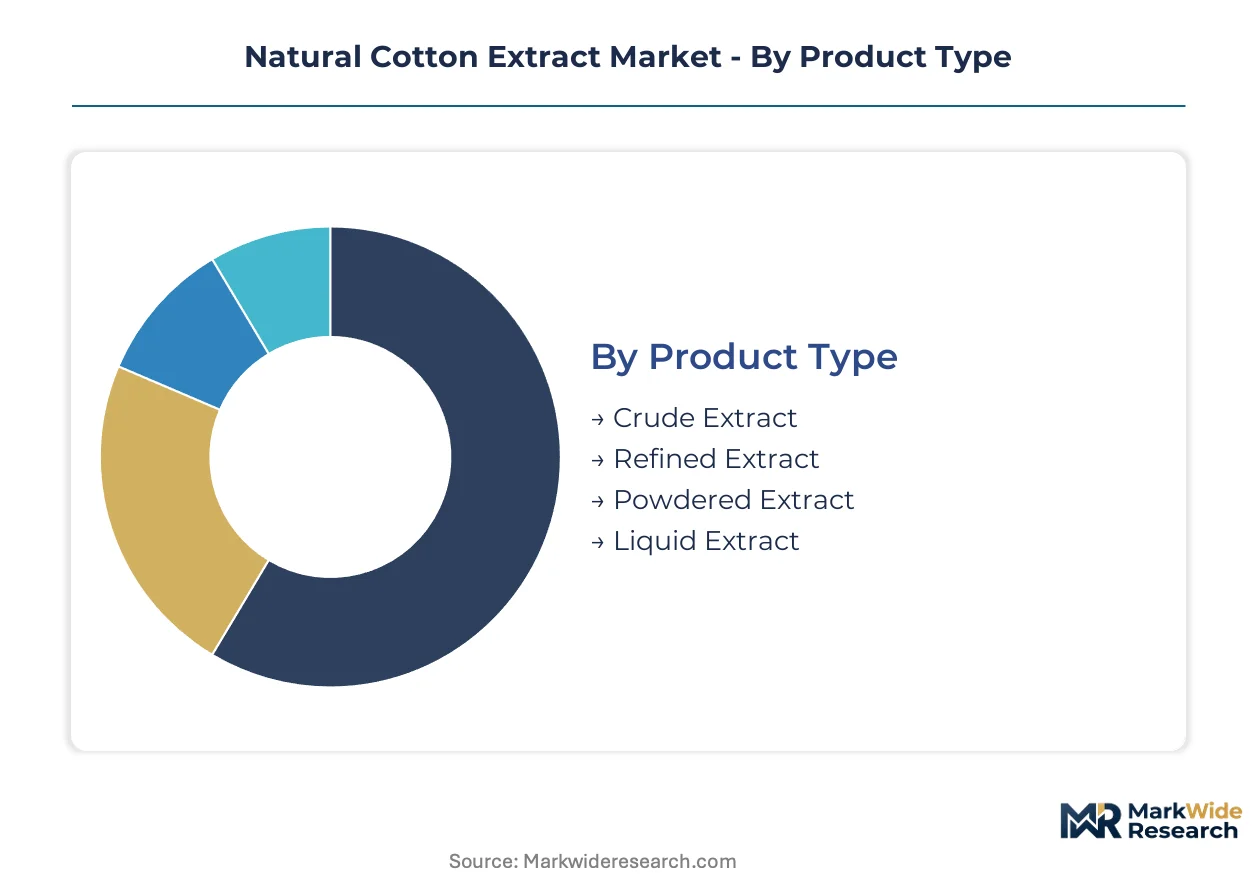
Segmentation in natural cotton extract markets tracks how extraction sophistication, regulatory compliance thresholds, and formulation convenience reshape procurement priorities across pharmaceutical, cosmetic, and industrial channels. Each dimension captures distinct margin structures and supplier qualification barriers.
Product Type:
Margin pools concentrate in extraction-purity tiers, where supercritical CO₂ processing commands pharmaceutical-grade premiums over conventional solvent outputs.
- Refined Extract:High-purity outputs standardized to specified polyphenol content and residual solvent limits below REACH thresholds. Pharmaceutical formulators in Switzerland and France source exclusively from supercritical CO₂ refiners to secure EMA-compliant dossiers for topical and ingestible applications.
- Liquid Extract:Pumpable, pre-dispersed formats eliminate powder-handling steps in cold-process cosmetics manufacturing. Contract manufacturers serving clean-label beauty brands in North America are rotating procurement toward liquid formats to shorten batch cycles and reduce clean-in-place downtime.
- Crude Extract:Unrefined outputs with higher gossypol content serve textile finishing baths where purity requirements remain less stringent than pharmaceutical channels.
- Powdered Extract:Spray-dried formats retain shelf stability for dietary supplement encapsulation, though handling complexity limits adoption in automated cosmetic production lines.
Refined extract holds installed capacity. Liquid extract is rotating up the share rankings.
Application:
Cost-to-compliance ratios diverge sharply across end-uses, with pharmaceutical and premium cosmetic channels absorbing extraction premiums that textile processors reject.
- Cosmetics:Clean-label formulators specify traceable botanical provenance and blockchain-documented batch records to satisfy EU CSRD disclosure requirements. Cold-process brands in France and Switzerland source liquid extracts exclusively, displacing synthetic emollients from premium moisturizer and serum formulations.
- Pharmaceuticals:EMA and FDA residual gossypol limits constrain seed-derived extraction yields, forcing refiners toward linter and burr feedstocks. Supercritical CO₂ processing is expanding fastest in this channel as hexane-based outputs face disqualification from new drug applications.
- Textiles:Biobased finishing agents for institutional uniform supply chains leverage USDA BioPreferred program preferences, though cost sensitivity limits cotton extract penetration below premium positioning.
- Food Additives:Microencapsulated cotton-derived polysaccharides for controlled-release dietary supplements remain nascent, constrained by FSSAI and FDA toxicity documentation requirements for novel food ingredients.
Cosmetics commands formulation premium capture. Pharmaceuticals is climbing the fastest on regulatory exclusion of conventional solvent extracts.
End User:
Procurement authority concentrates in direct manufacturers, while intermediaries face margin compression from shortened contract cycles and spot-market price volatility.
- Manufacturers:Integrated cosmetic and pharmaceutical producers with in-house formulation capabilities source directly from Indian and Turkish ginning-extraction operations, consolidating supplier bases to satisfy EU Green Deal provenance mandates.
- Distributors:Regional chemical distributors serving mid-tier cosmetic brands face inventory risk from cotton futures-linked pricing clauses that reset every 12-18 months.
- Wholesalers:Bulk handlers of crude extract for textile processors operate on volume-thin margins, vulnerable to monsoon-linked supply disruptions from Gujarat ginning infrastructure.
- Retailers:Direct-to-consumer clean-label brands with private-label extract lines represent emerging demand, though order scales remain below distributor minimums for refined outputs.
Manufacturers hold contract volume concentration. Distributors is gaining intermediary relevance as indie beauty brand procurement fragments.
Packaging Type:
Format selection tracks automation compatibility and contamination risk, with pharmaceutical channels demanding barrier properties that bulk textile shipments disregard.
- Bulk Containers:Stainless steel totes and drum liners for pharmaceutical-grade liquid extract minimize oxidative degradation during cold-chain transit from Indian refiners to European formulators.
- Bottles:Amber glass with nitrogen flushing preserves polyphenol stability for premium cosmetic serum applications, though unit costs exclude mass-market positioning.
- Jars:Wide-mouth formats suit powdered extract for dietary supplement blending operations, with desiccant integration mandatory for humidity-sensitive markets.
- Pouches:Flexible packaging for sample-scale cosmetic ingredient distribution enables formulation trials without drum-commitment inventory risk.
Bulk containers dominate pharmaceutical procurement. Bottles is ascending on premium cosmetic serum segment expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jawaharlal Nehru Port Trust in Maharashtra handles containerized exports of refined cotton extract to European pharmaceutical formulators, underwriting India's dominance in botanical ingredient trade lanes.
India
Gujarat's integrated textile-cosmetic clusters process domestic cotton linters into REACH-compliant extracts for Swiss and French pharmaceutical clients. FSSAI novel food ingredient documentation requirements constrain seed-derived polysaccharide launches in dietary supplements. Tamil Nadu ginning infrastructure around Coimbatore supplies captive refining operations serving export-oriented cosmetic manufacturers.
United States
USDA BioPreferred program mandates create institutional procurement channels for biobased textile finishing agents in federal uniform supply chains. FDA residual gossypol limits for topical applications force refiners toward linter and burr feedstocks rather than cottonseed. California-based clean-label cosmetic brands source liquid extract formats to eliminate powder-handling in cold-process manufacturing.
Switzerland
Swissmedic pharmaceutical-grade certification requirements drive demand for supercritical CO₂-refined extracts with documented batch provenance. EU CSRD disclosure mandates force cosmetic manufacturers to consolidate supplier bases to vertically integrated Indian operations. Geneva-headquartered fragrance houses specify blockchain-traceable cotton-derived inputs for premium serum formulations.
Germany
ECHA enforcement of REACH residual solvent thresholds disqualifies hexane-based extraction outputs from cosmetic and pharmaceutical channels. North Rhine-Westphalia chemical distributors face inventory risk from cotton futures-linked pricing clauses resetting every 12-18 months. Bavaria-based contract manufacturers serving indie beauty brands prioritize liquid extract formats to shorten batch cycle times.
Brazil
Cerrado and Northeast cultivation zones offer untapped organic linter supply for EU-compliant extraction, diversifying sourcing beyond Indian dominance. ANVISA toxicity documentation requirements for novel cosmetic ingredients delay market entry for seed-derived polysaccharide applications. São Paulo-based refiners develop supercritical CO₂ capacity to serve pharmaceutical export markets.
Natural Cotton Extract Market Competitive Landscape
Listed leaders compete with private specialists across extraction technology tiers, with publicly traded textile conglomerates facing off against family-owned ginning operations. Market structure concentrates around vertically integrated Indian players controlling linter supply from farm through refining. Three archetypes dominate: captive cotton farmers with in-house extraction, independent refiners purchasing lint on spot markets, and cosmetic ingredient distributors aggregating multi-origin supply. Competitive moves center on supercritical CO₂ capacity expansion and three-year organic certification transitions locking in qualified raw material streams.
Among UK-based operators, Plexus Cotton Ltd. exemplifies the heritage ginning specialist archetype leveraging Lancashire infrastructure for premium linter access. Indian conglomerates anchor the integrated producer tier, with Arvind Limited representing captive farming-to-refining models and The Rajlakshmi Cotton Mills occupying Kolkata-based organic-certified processing positions. These three entities illustrate geographic and structural differentiation strategies across the supplier base.
| Leading Market Players |
|---|
| KCC Beauty |
| Plexus Cotton Ltd. |
| Botanicals Plus |
| Arvind Limited |
| The Rajlakshmi Cotton Mills |
| Carrubba Inc. |
| Remei AG |
| Noble Ecotech |
| The Garden of Naturals |
| Others |
Supply & Pricing Matrix
REACH registration thresholds gate both supplier qualification timelines and price differentiation across European pharmaceutical and cosmetic procurement channels. Buyers purchasing supercritical CO₂-refined outputs absorb extraction premiums that conventional solvent refiners cannot command, while USDA organic certification creates parallel tiering in North American clean-label segments.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade supercritical CO₂ extracts from cosmetic-grade liquid formats and textile-bound crude outputs. Price differentiation rests on certification grade—REACH-compliant dossiers command premiums over BIS-standard herbal grades—and extraction method purity. Cost compression in conventional solvent tiers is intensifying because ECHA enforcement disqualifies hexane-based outputs from premium channels. Contract manufacturers serving mass-market cosmetic brands exhibit highest price sensitivity, while Swiss and French pharmaceutical formulators show least sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Jawaharlal Nehru Port Trust containerized exports underwrite India's dominance in refined extract trade lanes to European pharmaceutical clients. Raw material supply draws from Gujarat and Tamil Nadu ginning clusters, with Brazilian Cerrado zones emerging as alternative organic linter sources. Single-source vulnerability concentrates in monsoon-disrupted Maharashtra and Gujarat harvests. Distribution runs through vertically integrated Indian producers supplying direct to Swiss and French formulators, bypassing regional chemical distributors facing cotton futures-linked inventory risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where three-year organic certification timelines and supercritical CO₂ technician scarcity create switching-cost barriers for qualified suppliers.
For Market Incumbents: Shield margin position by accelerating captive organic cotton farming transitions in Gujarat and Maharashtra before competitor certification lock-in. Expand supercritical CO₂ capacity to capture pharmaceutical-grade premiums as EMA dossier requirements harden. Defensive consolidation should target Kolkata-based organic-certified processors to block new entrant access to FSSAI-compliant infrastructure. For New Entrants and Emerging Players: Cold-process cosmetics contract manufacturing gaps where incumbents under-serve indie beauty brands offer white-space entry. Target Brazilian Cerrado organic linter supply chains to bypass Indian concentration. Nutraceutical encapsulation for controlled-release dietary supplements presents the most penetrable application. Go-to-market angle: microencapsulation technology partnerships with São Paulo-based refiners building supercritical CO₂ capacity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across supercritical CO₂ extraction infrastructure as pharmaceutical-grade compliance requirements tighten. Long-term viability favors backward-integrated producers controlling linter supply from farm through refining. Acquisition target archetype: family-owned ginning operations in Tamil Nadu with untapped organic certification potential. Signal to watch: EMA regulatory guidance revisions on residual gossypol thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO₂ Capacity Expansion | ECHA REACH enforcement disqualifies hexane-based outputs from Swiss and French pharmaceutical channels. |
| Organic Certification Transition | Three-year USDA organic timelines lock in qualified raw material streams ahead of competitor qualification. |
| Backward Integration into Captive Farming | Gujarat and Maharashtra ginning infrastructure secures linter supply against monsoon-linked volatility. |
| Liquid Extract Format Development | Cold-process cosmetics manufacturers in California and France prioritize pumpable inputs to shorten batch cycles. |
| Brazilian Sourcing Diversification | Cerrado and Northeast cultivation zones reduce dependency on Indian supply concentration for EU-compliant extraction. |
Research Methodology
The analysis maps extraction technology tiers, regulatory compliance pathways, and end-use application segments, each validated through extraction plant managers, cosmetic formulation chemists, pharmaceutical regulatory affairs leads, and cotton ginning cooperative directors. Primary interviews with these stakeholders combined with secondary validation from ECHA registration databases, FSSAI novel food ingredient filings, USDA organic certification records, and Indian customs export data. Bottom-up capacity modeling and top-down demand triangulation cross-checked volume estimates across the analysis window.
Consistency checks against external benchmarks validated output robustness across the projection horizon. The analytical framework modeled extraction purity grades, application channels, geographic production clusters, and packaging format preferences. CAGRs derived from segment-level growth rate reconciliation with macro cotton lint production forecasts and clean-label cosmetics formulation trend indices. Industry-specific inputs included supercritical CO₂ equipment installation pipelines and EU CSRD disclosure implementation timelines.
Forecasts assume regulatory continuity in REACH, USDA organic, and BIS herbal standards regimes; material policy shifts would require re-modeling. Specific risk factors include EMA gossypol threshold revisions, Brazilian ANVISA novel ingredient pathway changes, and monsoon severity disrupting Gujarat ginning operations. Practitioners should keep alternative scenarios live as clean-label certification requirements and extraction technology cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Global Cotton Market
Natural Fibers
Bamboo Fibers Market
Natural Fibers
Acacia Fiber Powder Market
Natural Fibers
Silk Stocking Market
Natural Fibers
Gum Fiber Market
Natural Fibers
Sugarcane Fiber Market
Natural Fibers
Organic Cotton Market
Natural Fibers
Natural Fibers Market
Natural Fibers
North America Textile Market
Natural Fibers
Acoustic Cotton Market
Natural Fibers
Asia-Pacific Alpaca Fiber Market
Natural Fibers
Spent Coffee Grounds Fiber Market
Natural Fibers
Silk Mask Market
Natural Fibers
Natural Fiber Composite (NFC) Market
Natural Fibers
Cellulose Market
Natural Fibers
Modal Fiber Market