
 Hessian Sacks Market | 2026-2036
Hessian Sacks Market Size, Share, and Industry Trends Forecast 2026-2036
Hessian Sacks Market Foresight
The EU Green Deal's phased reduction of synthetic agricultural packaging is recalibrating procurement standards across European food importers. Gloster Limited leverages its integrated jute milling operations to sustain cost advantages in heavy-duty sack supply. J&HM Dickson Ltd. anchors its position through Scottish manufacturing heritage and specialized weaving equipment. Cheviot Company Limited differentiates via certified biodegradable product lines aligned with retailer sustainability mandates.
Hessian sacks are woven containers manufactured from jute or sisal fibers, typically constructed with 10-12 ounce per square yard fabric density and double-stitched seams for load-bearing applications in agricultural and industrial transport. The natural fiber material grade segment dominates volume due to compostability credentials and compatibility with organic certification requirements. Heavy-duty sacks command premium positioning in construction and mineral transport where tensile strength thresholds exceed 50 kilograms per bag. Lightweight bags represent the fastest-growing structural category, driven by retail produce packaging and e-commerce fulfillment applications requiring reduced dimensional weight.
BIS certification requirements in India govern jute product quality standards for domestic distribution and export eligibility, while REACH compliance in Europe restricts chemical treatments applied during fiber processing. The USDA's BioPreferred program creates procurement preference for biobased packaging in federal agricultural operations. Stakeholders must monitor evolving extended producer responsibility frameworks and fiber traceability mandates to anticipate compliance cost shifts and sourcing qualification barriers.
Market Dynamics
The EU Green Deal's phased single-use plastic restrictions are forcing agricultural commodity exporters to requalify their entire packaging supply chains around biodegradable fiber alternatives. This regulatory compression is accelerating procurement migration from polypropylene woven sacks toward jute-based substitutes, concentrating sourcing decisions in the hands of sustainability-certified importers.
Growth Catalysts
- EU Green Deal packaging mandates:The phased prohibition on synthetic agricultural sacks creates immediate substitution demand among European food importers sourcing from tropical commodity suppliers.
- Brazilian soybean exporters:Large-scale grain handlers are expanding biodegradable packaging procurement to maintain access to EU retail channels and organic certification premiums.
- Natural fiber compostability:Jute hessian's compatibility with organic waste streams eliminates disposal costs for municipal composting operations in German and French agricultural districts.
Market Restraints
- Jute fiber price volatility:Monsoon-dependent harvests in Bangladesh and West Bengal create input cost instability that squeezes converter margins during El Niño cycles.
- Supply concentration risk:Over 70% of raw jute processing capacity clusters within 200 kilometers of Kolkata, exposing buyers to regional logistics disruptions.
- Synthetic fiber substitution:Polypropylene woven sacks retain cost advantages in mineral transport and construction applications where biodegradability carries no procurement premium.
Strategic Opportunities
- Indian e-commerce fulfillment:Lightweight hessian mailers are penetrating last-mile delivery networks in Bangalore and Mumbai as plastic-free packaging mandates tighten.
- USDA BioPreferred program:Federal procurement preference for biobased packaging creates qualified supplier status for jute sack manufacturers serving US agricultural operations.
- Retail produce branding:European supermarket chains are specifying printed hessian for premium fruit and vegetable display packaging to signal sustainability credentials.
Industry Challenges
- REACH compliance timelines:European chemical registration requirements for fiber processing treatments extend qualification cycles by 12-18 months for new supplier entrants.
- Specialized weaving equipment scarcity:Heavy-duty sack production requires looms with 50-kilogram tensile capacity that face 24-month order backlogs from European machinery suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hessian Sacks Market |
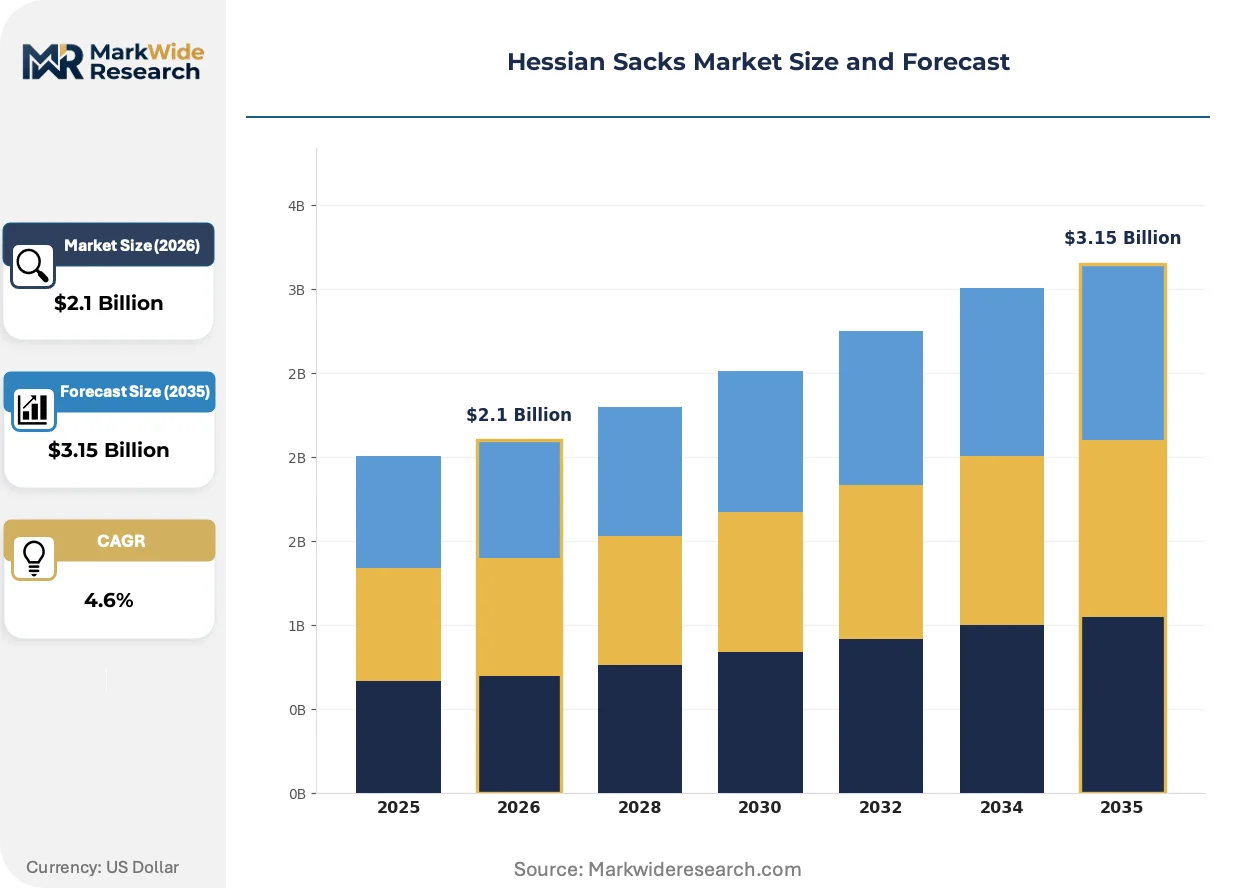
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Sacks, Custom Sizes, Lightweight Bags, Heavy-Duty Sacks End User: Agriculture, Retail, Construction, Industrial Material Grade: Natural Fiber, Biodegradable, Recycled, Synthetic Blend Distribution Channel: Online Retail, Wholesale, Direct Sales, Distributors |
| Companies Covered | Guangzhou Red Swan Textile Co., Ltd., J&HM Dickson Ltd., Jute Planet, LMC Global Private Limited, Bulk Bag Co. Limited, Premchand Jute & Industries Private Limited, Churiwal Technopack Private Limited, Gloster Limited, Cheviot Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hessian Sacks Market Shifts & Advancements
Digital traceability systems are penetrating natural fiber supply chains as buyers demand provenance verification for sustainability claims. This technological overlay is compressing the gap between plantation-level harvesting and retail packaging certification.
Plasma surface treatment technology is unifying fiber adhesion and print receptivity in a single processing step. Specialty chemical suppliers in Gujarat are retrofitting jute mills with atmospheric plasma systems that eliminate water-intensive sizing baths. European packaging converters are specifying plasma-treated hessian for high-resolution brand printing on coffee and cocoa sacks. This technology is unifying what previously required separate wet chemical and mechanical finishing stages.
REACH chemical registration in Europe is restricting boron-based fire retardants traditionally applied to jute fiber. The European Chemicals Agency's 2023 substance evaluation has classified certain boron compounds as reproductive toxicants, forcing sack manufacturers to reformulate with magnesium hydroxide alternatives. German agricultural distributors are demanding third-party certification of chemical-free processing for organic product lines.
Direct mill-to-retailer contracting is displacing traditional jute trader intermediaries in Bangladesh. Large European coffee roasters are establishing multi-year offtake agreements with integrated spinning and weaving operations in Khulna and Rajshahi. This channel compression eliminates margin stacking but requires buyers to assume quality assurance functions previously handled by trading houses. The pattern is most visible in specialty coffee supply chains where origin transparency commands price premiums.
Hessian Sacks Market Segmentation
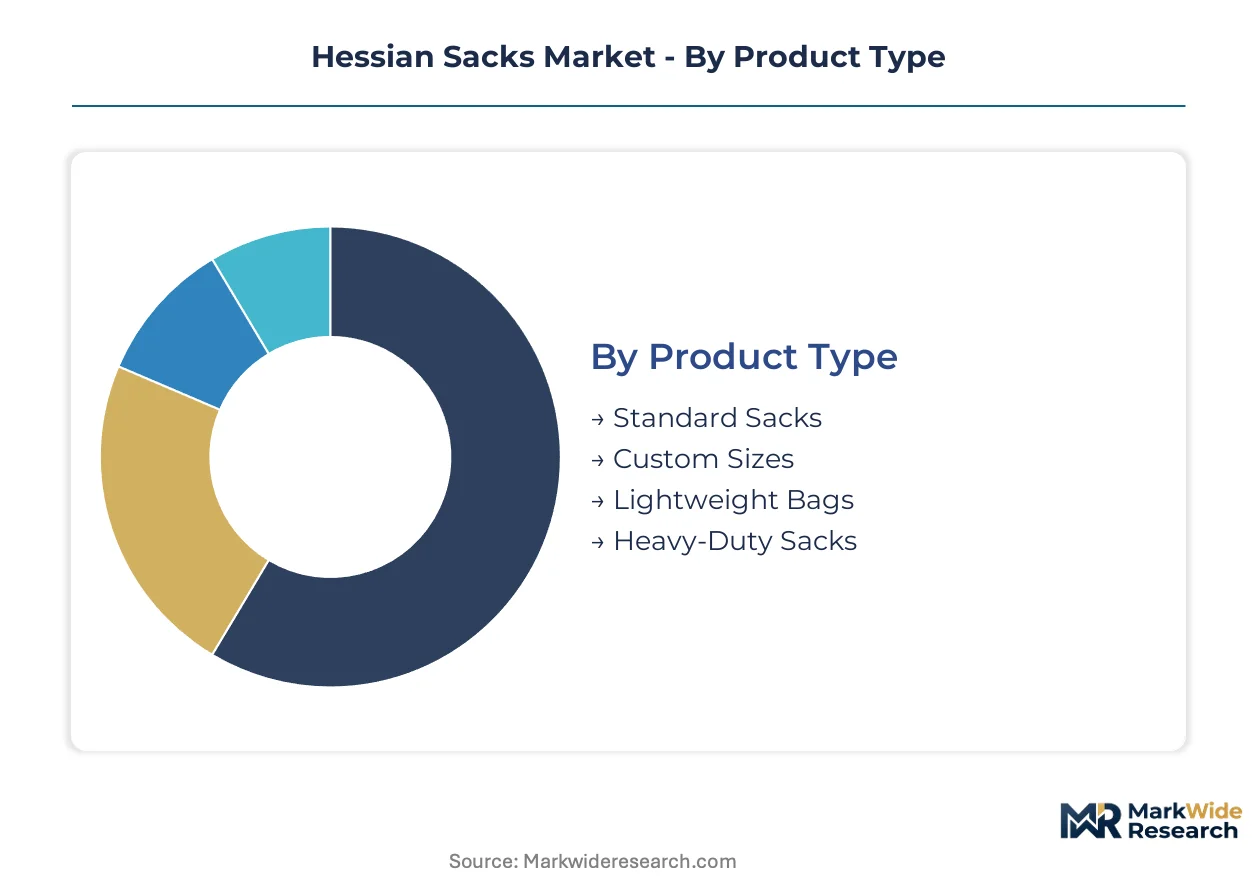
Segmentation in the Hessian Sacks Market reveals how procurement specifications diverge across regulatory environments and end-use durability requirements. Buyers requalify their packaging portfolios around compostability mandates and load-bearing thresholds that vary sharply by commodity type.
Product Type:
Upgrade cycles in agricultural packaging are accelerating as EU importers phase out polypropylene alternatives and Brazilian grain handlers seek organic certification compliance.
- Standard Sacks:These 10-12 ounce per square yard jute containers with double-stitched seams serve baseline agricultural transport needs. Demand concentrates among Indian spice exporters supplying European retail channels where BIS certification governs export eligibility.
- Heavy-Duty Sacks:Engineered with 50-kilogram tensile capacity and reinforced selvedge construction for mineral and construction material transport. Procurement clusters in German building supply distribution where REACH-compliant chemical treatments are mandatory for site usage approval.
- Custom Sizes:Dimensionally specified for specialty coffee and cocoa lot packaging with printed branding surfaces.
- Lightweight Bags:Reduced fabric density for retail produce display and e-commerce fulfillment applications.
Volume placements concentrate in Standard Sacks; the faster expansion belongs to Heavy-Duty Sacks.
End User:
Cost tier differentiation separates commodity handlers from premium brand owners who specify certified biodegradable packaging for sustainability signaling.
- Agriculture:The dominant consumption category spanning grain, pulse, and spice transport with organic certification requirements. Brazilian soybean exporters and Indian turmeric processors drive procurement volume as they requalify supply chains for EU Green Deal compliance.
- Retail:Premium fruit and vegetable display packaging with high-resolution surface printing for brand differentiation. French and German supermarket chains specify printed hessian for organic produce sections where visual sustainability cues command shelf price premiums.
- Construction:Sand, aggregate, and cement containment where synthetic fiber cost advantages persist.
- Industrial:Chemical and mineral transport requiring fire-retardant treatments now reformulated around magnesium hydroxide alternatives.
Margin capture is strongest in Retail; the steepest expansion trajectory runs through Agriculture.
Material Grade:
Application-specific certification requirements are fragmenting sourcing decisions across compostability verification and chemical treatment disclosure standards.
- Natural Fiber:Unbleached jute with full compostability credentials and organic waste stream compatibility. Demand clusters in German municipal composting districts where disposal cost elimination drives procurement preference.
- Biodegradable:Certified degradable treatments meeting EN 13432 standards for industrial composting. European food importers mandate this grade for private-label organic product lines.
- Recycled:Post-consumer jute fiber blends with reduced tensile consistency.
- Synthetic Blend:Polypropylene-jute composites retaining cost advantages in non-certified applications.
Procurement volume centers on Natural Fiber; the climbing demand curve tracks Biodegradable.
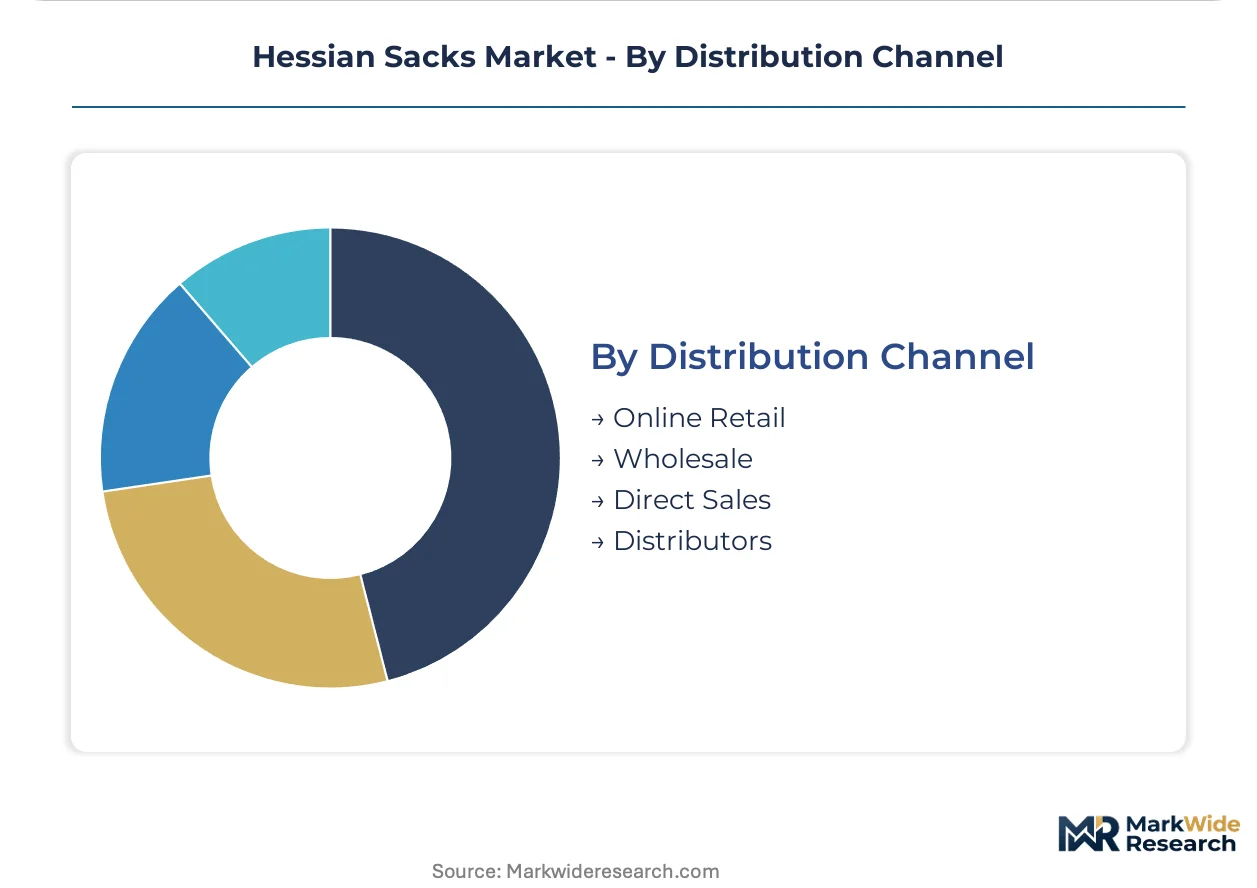
Distribution Channel:
Customer type fragmentation is compressing traditional trading margins as large buyers pursue direct mill relationships.
- Direct Sales:Multi-year offtake agreements between integrated Bangladeshi mills and European coffee roasters. Khulna and Rajshahi spinning operations now contract directly with specialty buyers seeking origin transparency documentation.
- Wholesale:Aggregated procurement through Kolkata-based trading houses serving mid-scale agricultural exporters. This channel retains relevance for Indian domestic distribution where BIS certification processing requires local intermediary expertise.
- Distributors:Regional stocking networks for construction and industrial supply.
- Online Retail:Small-lot procurement portals for craft and specialty packaging applications.
Channel volume aggregates in Wholesale; the fastest share gain belongs to Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kolkata and its surrounding 200-kilometer industrial belt concentrate over 70% of global raw jute processing capacity. This geographic dominance shapes procurement risk profiles and logistics cost structures for agricultural commodity exporters worldwide.
India
West Bengal's jute mills and BIS certification requirements govern domestic distribution and export eligibility for spice and grain handlers. The EU Green Deal's packaging mandates are accelerating procurement migration from polypropylene toward jute substitutes among turmeric processors. Manufacturing clusters in eastern India around Kolkata face monsoon-dependent fiber supply instability during El Niño cycles.
Bangladesh
Khulna and Rajshahi spinning operations are establishing multi-year offtake agreements with European coffee roasters seeking origin transparency. The country's national agricultural regulator oversees fiber quality standards for export eligibility. Direct mill-to-retailer contracting is displacing traditional trader intermediaries in specialty coffee supply chains.
Germany
German building supply distributors mandate REACH-compliant chemical treatments for heavy-duty sack site usage approval. The EU Green Deal's phased single-use plastic restrictions are recalibrating procurement standards across food importers sourcing tropical commodities. Municipal composting districts in agricultural regions eliminate disposal costs through natural fiber procurement preference.
Brazil
São Paulo-based grain handlers are expanding biodegradable packaging procurement to maintain EU retail channel access and organic certification premiums. The country's national agricultural regulator monitors export packaging compliance for soybean shipments. Large-scale commodity exporters face requalification pressures as European sustainability-certified importers consolidate sourcing decisions.
France
French supermarket chains specify printed hessian for organic produce sections where visual sustainability cues command shelf price premiums. ECHA's 2023 substance evaluation of boron-based fire retardants is forcing sack manufacturers toward magnesium hydroxide alternatives. Agricultural districts in northern France prioritize compostability credentials for municipal waste stream compatibility.
Hessian Sacks Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and sustainability-verification dimensions. The vendor base stratifies into integrated milling operations, specialized weaving equipment holders, and certified biodegradable product line specialists. Three archetypes dominate: vertically integrated fiber processors with captive raw material supply, heritage manufacturers leveraging specialized loom assets, and sustainability-focused converters aligned with retailer mandates. Competitive moves concentrate on direct mill-to-buyer contracting compression and plasma surface treatment technology licensing for print receptivity.
Among UK-based fabricators, J&HM Dickson Ltd. and Cheviot Company Limited occupy positions within specialized weaving and certified biodegradable tiers respectively. Gloster Limited anchors the integrated milling archetype with operations spanning fiber processing through finished sack production. These three entities exemplify how geographic manufacturing heritage and sustainability certification alignment determine margin capture in procurement decisions driven by EU Green Deal compliance and organic certification requirements.
| Leading Market Players |
|---|
| Guangzhou Red Swan Textile Co., Ltd. |
| J&HM Dickson Ltd. |
| Jute Planet |
| LMC Global Private Limited |
| Bulk Bag Co. Limited |
| Premchand Jute & Industries Private Limited |
| Churiwal Technopack Private Limited |
| Gloster Limited |
| Cheviot Company Limited |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between REACH-compliant heavy-duty sacks and standard agricultural containers manifests in divergent margin structures and procurement channel configurations. Premium positioning in German building supply distribution commands sustained markup power through specialized chemical treatment documentation, while commodity-grade standard sacks face compression through Kolkata trading house intermediation.
Pricing Analysis
Value-based pricing anchors on compostability credentials and organic certification compatibility that eliminate downstream disposal costs for European municipal buyers. Three-tier pricing structure across premium, standard, and economy levels reflects certification investment, tensile capacity thresholds, and geographic delivery complexity. Cost compression in standard-grade agricultural sacks is intensifying because monsoon-dependent fiber supply instability squeezes converter margins during El Niño cycles. Large-scale Brazilian grain handlers exhibit lowest price sensitivity due to organic certification premium capture, while Indian domestic spice traders face acute margin pressure from BIS compliance processing fees.
Supply Chain Analysis
Direct-to-retailer channels handle specialty coffee and cocoa demand from European roasters seeking origin transparency documentation. Raw jute processing draws from Bangladesh, India, and Nepal fiber harvests with captive spinning capacity concentrated in Khulna and Rajshahi. Supply chain risk centers on single-source vulnerability from Kolkata-clustered loom manufacturing facing 24-month equipment backlogs. Distribution runs through integrated mill operations, Kolkata-based trading houses, and regional construction supply networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around sustainability-verified suppliers as EU Green Deal compliance requirements eliminate uncertified competitors from European procurement portfolios.
For Market Incumbents: Deepen backward integration into captive fiber supply through multi-year offtake agreements with Bangladeshi plantation cooperatives. Invest in plasma surface treatment licensing to capture premium printing demand from European supermarket chains. Defensive positioning requires assuming quality assurance functions previously handled by trading intermediaries. For New Entrants and Emerging Players: The price-point gap between REACH-certified heavy-duty sacks and untreated standard containers creates white-space opportunity in mid-tier biodegradable certification. Target Indian e-commerce fulfillment networks in Bangalore and Mumbai where plastic-free packaging mandates tighten fastest. Go-to-market angle: lightweight mailer specialization with BIS certification processing expertise. For Investors and Strategic Acquirers: Re-rating potential sits with integrated jute milling operations given direct mill-to-retailer contracting displacement of trader intermediaries. Long-term viability favors archetypes with captive raw material supply and plasma treatment technology licensing. Signal to watch: European coffee roaster multi-year offtake agreement announcements indicating origin transparency premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Supply | Captive jute sourcing from Bangladeshi cooperatives insulates margin from monsoon volatility. |
| Plasma Surface Treatment Licensing | Eliminates water-intensive sizing baths while enabling high-resolution brand printing for retail clients. |
| REACH Compliance Certification Investment | Mandatory magnesium hydroxide fire-retardant reformulation opens German building supply distribution. |
| Direct Mill-to-Retailer Contracting | Channel compression with European coffee roasters captures origin transparency price premiums. |
| Lightweight Mailer Product Line Expansion | Penetrates Indian e-commerce last-mile networks facing plastic-free packaging regulatory pressure. |
Research Methodology
Independent corroboration across jute mill operations managers, European food importer procurement leads, and specialty coffee roaster supply chain directors underwrites the qualitative findings. Primary fieldwork combined structured interviews with Kolkata-based trading house principals and Bangladeshi spinning operation owners with secondary validation from BIS certification databases, EU Green Deal regulatory filings, and REACH chemical registration documentation. Bottom-up volume modeling triangulated against top-down agricultural commodity export flow analysis.
Comparable-period anchoring to historical jute fiber price cycles and El Niño impact patterns shaped the projection horizon calibration. Segmentation modeling spanned product type, material grade, end-use industry, and distribution channel dimensions across the analysis window. CAGRs were derived from demand elasticity coefficients tied to EU single-use plastic restriction phase-in schedules and Brazilian organic certification penetration curves.
Inputs from European coffee roaster sustainability officers were available through the study window; gaps in real-time monsoon harvest yield data introduce uncertainty bands around fiber cost assumptions. Forecasts reflect documented assumptions regarding REACH compliance timeline adherence and plasma treatment technology adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Acacia Fiber Powder Market
Natural Fibers
Cashmere Clothing Market
Natural Fibers
Thailand Textile Market
Natural Fibers
Silk Mask Market
Natural Fibers
Acoustic Cotton Market
Natural Fibers
Global Cellulosic Man-Made Fibers Market
Natural Fibers
Bamboo Fibers Market
Natural Fibers
Natural Fiber Reinforced Composites Market
Natural Fibers
Silk Fabric Market
Natural Fibers
Global Alpaca Fiber Market
Natural Fibers
Silk Stocking Market
Natural Fibers
Asia-Pacific Alpaca Fiber Market
Natural Fibers
Natural Fiber Composite (NFC) Market
Natural Fibers
Natural Fibers Market
Natural Fibers
Jute Bags Market
Natural Fibers
Eco Fibers Market