
 Indonesia Textiles Market | 2026-2036
Indonesia Textiles Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Textiles Market Foresight
Indonesia's national environmental regulations governing industrial wastewater discharge is pivoting textile producers toward closed-loop dyeing systems and chemical recovery investments. PT Sri Rejeki Isman Tbk leverages its vertically integrated operations from fiber to finished fabric to absorb compliance costs across multiple production stages. Indo-Rama Synthetics anchors its position through captive polyester chip production, insulating margin pools from raw material volatility. Sritex competes on military and institutional uniform contracts that require traceable supply chains and certified production facilities.
Indonesia textiles encompass natural and synthetic fiber materials processed through spinning, weaving, knitting, dyeing, printing, and finishing operations with thread counts ranging from coarse 20s to fine 80s for varied end-use performance. These materials serve as inputs for apparel manufacturing, interior furnishings, and technical industrial applications requiring specified tensile strength, colorfastness, and dimensional stability. Polyester fabric output leads volume rankings due to feedstock proximity and energy cost advantages in Java-based petrochemical corridors. Home furnishings demand accelerates fastest as Indonesian middle-income households upgrade upholstery and curtain purchases through retail and wholesale channels. Cotton spinning remains margin-constrained against imported fiber costs, pushing mills toward blended yarn formulations that reduce raw material exposure.
BIS-equivalent national standards and Ministry of Industry technical regulations enforce product safety, labeling accuracy, and environmental compliance for domestic market access and export eligibility. The Ministry of Environment and Forestry administers wastewater discharge permits that shape capital allocation decisions for dyeing and finishing investments across Central Java and West Java provinces. Stakeholders must monitor enforcement consistency and permit processing timelines to calibrate capacity expansion schedules against compliance readiness thresholds.
Market Dynamics
Ministry of Industry wastewater discharge standards are forcing Bandung and Solo dyeing clusters to reallocate capital toward closed-loop chemical recovery systems, compressing margins for non-integrated operators while rewarding mills with captive water treatment infrastructure.
Growth Catalysts
- EU-Japan export protocols:Japanese apparel buyers and EU textile importers demand traceable supply chains, pulling orders toward Indonesian mills with certified production facilities and documented chemical management systems.
- Polyester feedstock proximity:Java-based petrochemical corridors supply synthetic fiber inputs at energy cost advantages, anchoring volume production in integrated spinning-weaving-dyeing operations.
- Home furnishings retail expansion:Indonesian middle-income households upgrading upholstery and curtain purchases through wholesale and retail channels accelerate demand for finished fabric output.
Market Restraints
- Imported cotton fiber costs:Raw material exposure from international cotton markets constrains spinning margins, pushing mills toward blended yarn formulations with lower purity grades.
- Java manufacturing concentration:Production gravity in Central Java and West Java provinces creates geographic vulnerability to regional water scarcity events and localized permit processing delays.
- Technical substitution threat:Technical industrial applications requiring specified tensile strength and dimensional stability face competition from non-woven synthetic alternatives in automotive and filtration end-uses.
Strategic Opportunities
- Technical textile applications:Industrial end-uses requiring certified flame resistance and chemical protection specifications remain underpenetrated relative to apparel and home furnishings saturation.
- Ministry of Environment permit premiums:Early compliance with wastewater discharge standards creates positioning advantage for capacity expansion ahead of enforcement timeline bottlenecks.
- Digital printing convergence:Direct-to-fabric inkjet systems enable short-run customization for institutional uniform contracts requiring rapid color matching and minimal order minimums.
Industry Challenges
- Dyeing technician skill scarcity:Closed-loop system operation and chemical recovery process management require specialized training unavailable in standard textile vocational pipelines.
- Integrated facility capex intensity:Captive water treatment, energy recovery, and effluent monitoring infrastructure demands simultaneous capital deployment across multiple production stages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Textiles Market |
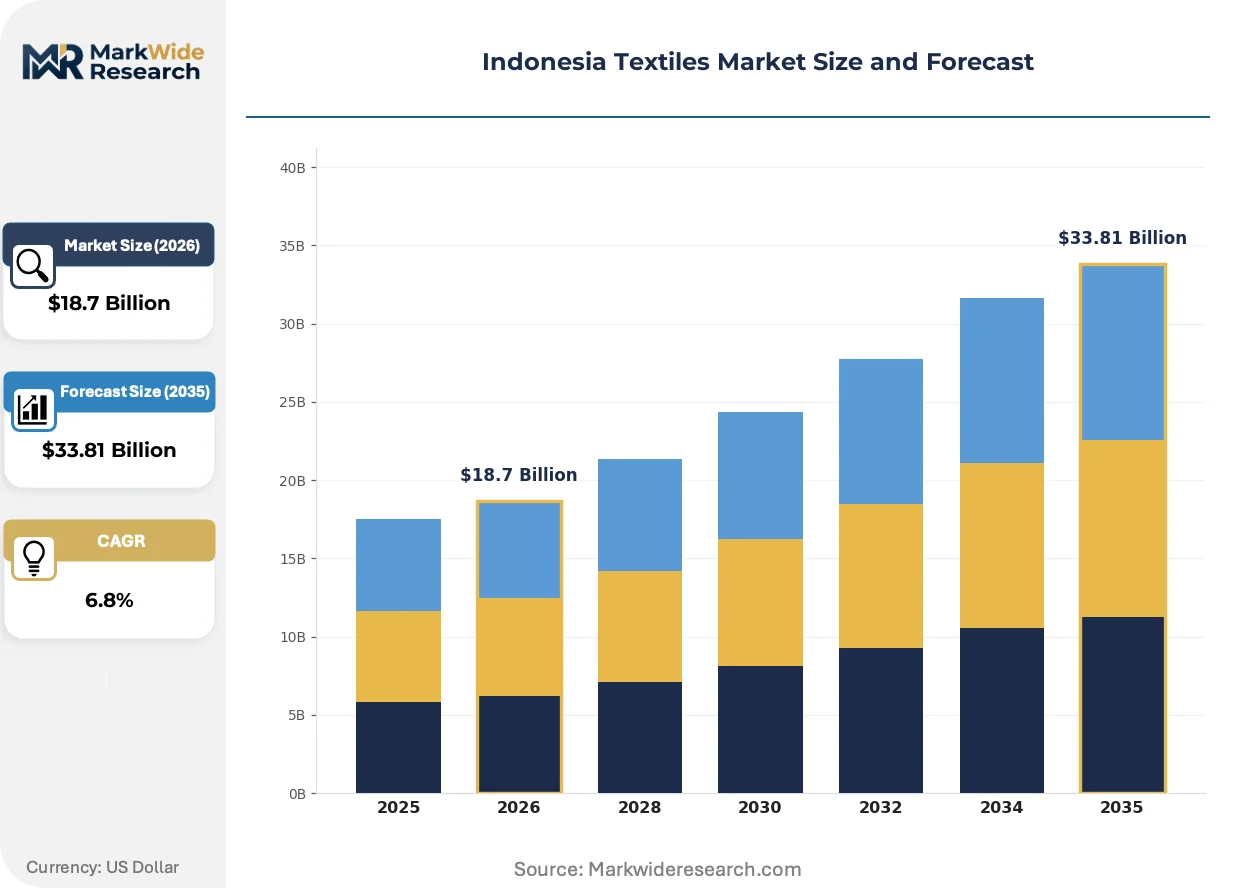
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cotton, Silk, Polyester, Wool End User: Apparel, Home Furnishings, Automotive, Industrial Distribution Channel: Online, Retail, Wholesale, Direct Sales Application: Fashion, Upholstery, Landscaping, Industrial Use |
| Companies Covered | PT Sri Rejeki Isman Tbk, Indo-Rama Synthetics, PT Asia Pacific Fibers Tbk, Sritex, Argo Pantes, Pan Brothers, PT Apac Inti Corpora, PT Kahatex, PT Panasia Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Textiles Market Shifts & Advancements
Digital production systems and environmental compliance architectures are restructuring competitive advantage in Indonesian textile manufacturing, separating integrated operators from fragmented processing houses.
Digital textile printing is converging with on-demand manufacturing workflows to compress sampling cycles from weeks to days. Japanese and EU export buyers are adopting these systems for initial order qualification and color approval. This convergence is collapsing minimum order thresholds and enabling micro-batch production for specialty uniform and interior furnishing contracts.
Ministry of Industry technical regulations enforcing BIS-equivalent national standards for product safety and labeling accuracy are tightening domestic market access requirements. Mills must maintain dual compliance frameworks for export eligibility and local distribution. Dyeing and finishing investments in Central Java face the steepest documentation burdens as permit processing timelines extend.
Certification-driven procurement now governs military and institutional uniform contracts, with traceable supply chains replacing price-only selection criteria. Government and corporate buyers audit fiber origin, chemical inputs, and facility labor conditions before contract award. This behavioral shift is most visible in Solo-based manufacturing clusters serving defense and public sector end-uses.
Indonesia Textiles Market Segmentation
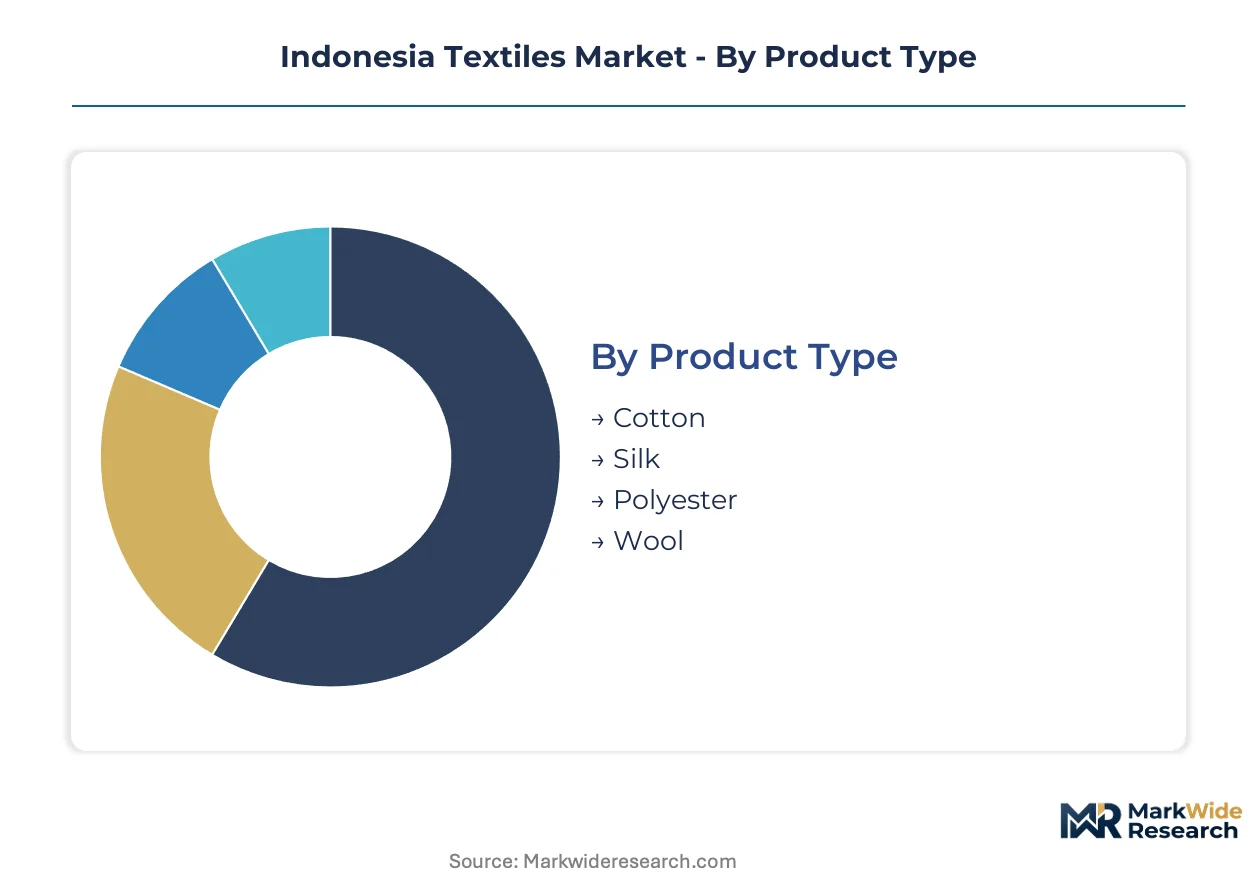
Indonesian textile producers configure product portfolios around fiber feedstock proximity and end-use certification requirements. Segment boundaries shift as integrated mills absorb dyeing compliance costs while fragmented processors retreat to undifferentiated commodity output.
Product Type:
Standalone fiber categories dominate volume rankings, while embedded fiber systems in blended yarns serve specialized performance requirements.
- Polyester:Synthetic polymer chains spun from purified terephthalic acid and ethylene glycol deliver crease resistance and dimensional stability. Java-based petrochemical corridors supply feedstock at energy cost advantages, anchoring volume production in Bandung and Solo integrated operations where captive chip production insulates margin pools from raw material volatility.
- Cotton:Cellulosic staple fibers harvested from Gossypium species provide breathability and moisture absorption prized in tropical climate apparel. Import dependency constrains spinning margins across Central Java mills, pushing formulation shifts toward lower-count blended yarns that reduce exposure to international fiber price swings.
- Silk:Protein filaments from Bombyx mori cocoons command premium positioning in ceremonial and luxury fashion segments.
- Wool:Keratin-based animal fibers serve niche cold-weather applications and institutional uniform specifications requiring natural flame resistance.
Volume placements concentrate in polyester; the faster expansion belongs to cotton as blended formulations penetrate mid-market apparel channels.
End User:
Cost tier stratification separates specification-driven institutional buyers from price-sensitive household purchasers.
- Apparel:Woven and knitted constructions cut and sewn into garments span thread counts from coarse 20s to fine 80s. Japanese and EU export protocols pull orders toward certified facilities with documented chemical management systems, compressing margins for non-compliant processors.
- Home Furnishings:Upholstery fabrics, curtain textiles, and decorative coverings serve Indonesian middle-income household upgrading cycles. Retail and wholesale channel expansion accelerates finished fabric demand through Java-based manufacturing clusters.
- Automotive:Technical specifications for seat coverings, headliners, and interior trim require specified tensile strength and abrasion resistance.
- Industrial:Filtration media, conveyor belting, and protective equipment applications face substitution pressure from non-woven synthetic alternatives.
Revenue concentration sits with apparel; home furnishings climb the fastest as domestic consumption upgrades.
Distribution Channel:
Customer type determines channel selection, with institutional buyers bypassing intermediaries while households fragment across touchpoints.
- Wholesale:Bulk transactions to garment manufacturers, furniture producers, and institutional contractors move through Solo and Bandung trading networks. Ministry of Industry technical regulations enforce BIS-equivalent documentation burdens that favor established channel relationships over spot market participation.
- Direct Sales:Military and institutional uniform contracts require traceable supply chains and certified production facilities. Government buyers audit fiber origin and labor conditions before award, locking out fragmented processors lacking documentation infrastructure.
- Retail:Branded fabric counters and home textile showrooms serve household purchasers upgrading upholstery selections.
- Online:Digital platforms enable short-run sampling for export qualification and color approval, collapsing minimum order thresholds.
Transaction value aggregates in wholesale; direct sales expand most quickly as certification requirements harden.
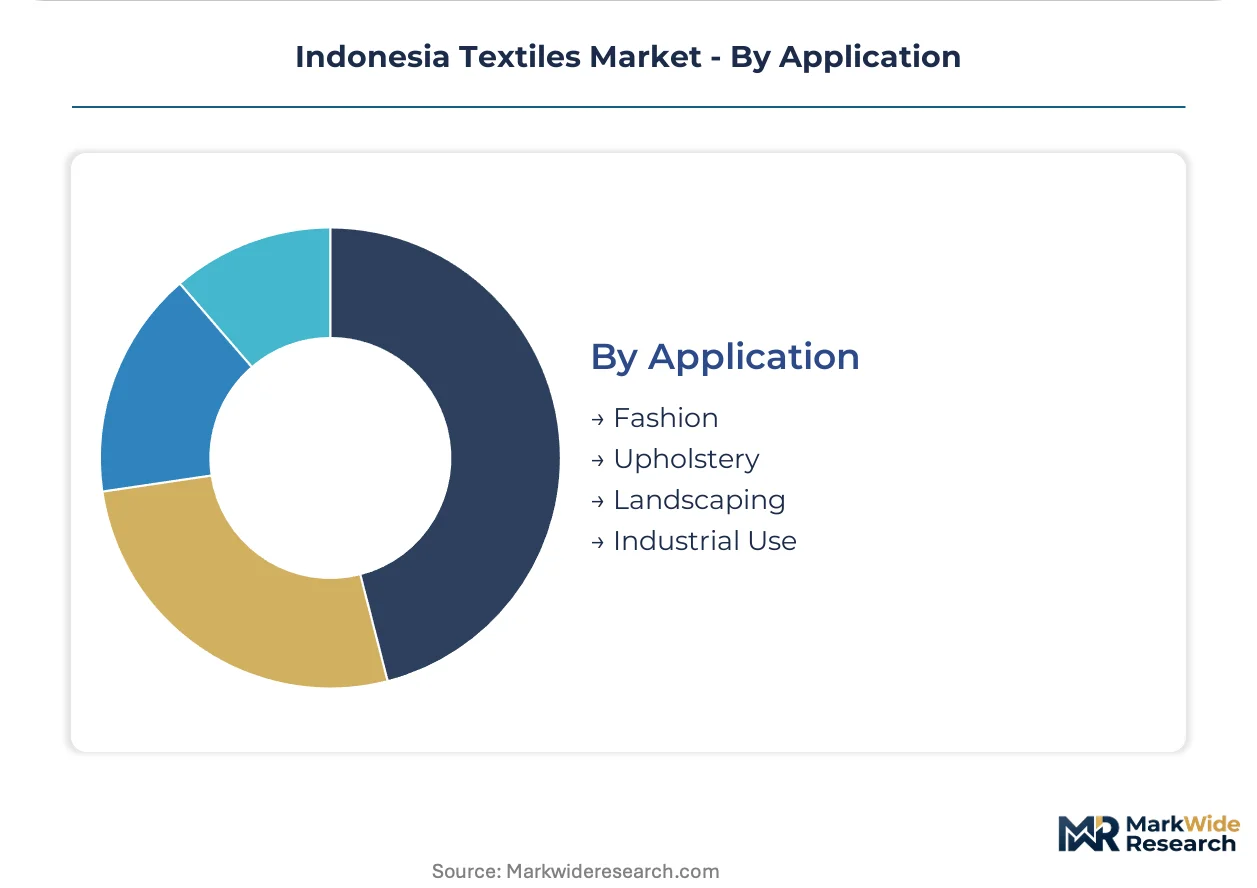
Application:
Maturity gradients separate saturated fashion segments from underpenetrated technical categories.
- Fashion:Seasonal garment production demands rapid color matching and minimal order minimums. Digital printing convergence enables micro-batch output for specialty contracts, compressing sampling cycles from weeks to days.
- Upholstery:Residential and commercial furniture covering specifications prioritize abrasion resistance and colorfastness. Indonesian middle-income household formation drives demand acceleration through retail channel expansion.
- Landscaping:Geotextiles, erosion control fabrics, and agricultural coverings serve infrastructure and cultivation applications.
- Industrial Use:Flame resistance and chemical protection specifications remain underpenetrated relative to apparel saturation, creating positioning space for mills investing in certified technical capabilities.
Shipment volumes concentrate in fashion; industrial use holds the steepest expansion trajectory as specification requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bandung and Solo anchor Indonesia's textile manufacturing gravity, with integrated spinning-weaving-dyeing operations concentrated in Java-based industrial corridors serving export buyers from Japan and the European Union.
West Java
Bandung's dyeing clusters face capital reallocation pressures under Ministry of Industry wastewater discharge standards. The Ministry of Environment and Forestry administers discharge permits that shape facility upgrade timelines. Captive water treatment infrastructure at integrated mills absorbs compliance costs while fragmented processors compress margins.
Central Java
Solo's manufacturing base specializes in military and institutional uniform contracts requiring traceable supply chains. BIS-equivalent national standards enforce product safety and labeling accuracy for domestic market access. Certification-driven procurement governs government and defense sector awards, locking out undocumented operators.
East Java
Surabaya corridor operations leverage port proximity for polyester feedstock imports and finished fabric exports. Ministry of Industry technical regulations tighten documentation burdens for dyeing investments. Petrochemical corridor linkages supply synthetic fiber inputs at energy cost advantages.
Banten
Tangerang industrial zones serve Jakarta-facing retail and wholesale distribution channels for home furnishings demand. Indonesian middle-income household upgrading cycles accelerate upholstery and curtain purchases through these manufacturing nodes. Permit processing timelines extend as environmental compliance documentation requirements intensify.
Indonesia Textiles Market Competitive Landscape
The competitive structure tilts toward vertically integrated conglomerates with captive fiber-to-fabric operations. Consolidation pressures favor mills absorbing wastewater treatment costs across multiple production stages. Three archetypes dominate: petrochemical-anchored synthetic producers, military-uniform specialists with certification infrastructure, and fragmented commodity processors retreating to undifferentiated output. Capacity expansion and compliance-driven facility upgrades constitute the dominant competitive moves.
Within the integrated conglomerate tier, PT Sri Rejeki Isman Tbk and Indo-Rama Synthetics occupy positions defined by upstream control over fiber inputs. Sritex represents the certification-specialist archetype, with its positioning governed by traceable supply chain requirements for institutional contracts. These three entities exemplify how environmental compliance investments and captive production infrastructure separate market leaders from margin-compressed commodity operators.
| Leading Market Players |
|---|
| PT Sri Rejeki Isman Tbk |
| Indo-Rama Synthetics |
| PT Asia Pacific Fibers Tbk |
| Sritex |
| Argo Pantes |
| Pan Brothers |
| PT Apac Inti Corpora |
| PT Kahatex |
| PT Panasia Group |
| Others |
Supply & Pricing Matrix
EU-Japan export buyers demanding traceable supply chains and certified chemical management systems are forcing Indonesian mills to absorb compliance premiums into contract pricing, compressing margins for non-integrated operators while rewarding facilities with captive water treatment and documented fiber origins.
Pricing Analysis
Certification-grade pricing anchors value-based contracts for military and institutional uniform procurement, where documented chemical inputs and labor audits command premiums over undifferentiated commodity output. Three-tier pricing structure across premium certification, standard compliance, and economy grades separates PT Sri Rejeki Isman Tbk and Sritex from fragmented processors. Pricing pressure stems from Ministry of Industry wastewater discharge standards forcing capital reallocation toward closed-loop dyeing systems. Household purchasers through retail channels exhibit highest price sensitivity, while defense sector buyers prioritize traceability over unit cost.
Supply Chain Analysis
Polyester chip supply rests on Java-based petrochemical corridors feeding Bandung and Solo integrated operations, while cotton fiber draws from import dependency through Surabaya port corridors. Purified terephthalic acid, ethylene glycol, and imported cotton lint constitute the dominant input base. Single-source vulnerability concentrates in synthetic feedstock corridors where energy cost advantages anchor volume production. Distribution runs through Solo and Bandung wholesale trading networks serving garment manufacturers and furniture producers, with direct sales channels capturing institutional uniform contracts requiring audit documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ministry of Environment wastewater discharge enforcement is accelerating consolidation, eliminating fragmented dyeing houses unable to fund captive treatment infrastructure while concentrating market share among integrated conglomerates with multi-stage compliance absorption capacity.
For Market Incumbents: Deepen backward integration into captive polyester chip production to insulate margin pools from feedstock volatility, mirroring Indo-Rama Synthetics' positioning. Expand water treatment capacity ahead of permit processing bottlenecks in Central Java. Certification infrastructure for military uniform contracts represents the priority defensive lever against emerging technical textile specialists. For New Entrants and Emerging Players: Ministry of Industry technical regulations enforcing BIS-equivalent national standards in Indonesia opens a window for digital printing specialists serving short-run institutional contracts with rapid color matching capabilities. Target home furnishings upholstery segments where domestic consumption upgrades outpace certified supply. Position through online sampling platforms collapsing minimum order thresholds for export qualification. For Investors and Strategic Acquirers: The window for entry favors vertically integrated mid-cap mills with dormant certification infrastructure and undervalued water treatment assets. Long-term viability hinges on compliance-ready capacity expansion ahead of enforcement timeline compression. Watch permit processing delays in West Java as the inflection signal for acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Dyeing System Deployment | Ministry of Environment permit premiums reward early compliance investments in Bandung clusters. |
| Captive Polyester Chip Production | Upstream control over synthetic feedstock insulates margins from petrochemical price swings. |
| Digital Printing Convergence | Direct-to-fabric inkjet systems enable micro-batch production for EU-Japan export qualification. |
| Certification Infrastructure Buildout | Traceable supply chains unlock military and institutional uniform contract awards. |
| Technical Textile Capability Investment | Flame resistance and chemical protection specifications remain underpenetrated relative to apparel saturation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews across textile mill operations directors, Ministry of Industry compliance officers, dyeing facility engineers, and export buyer procurement leads. Ministry of Environment permit databases, BIS-equivalent technical regulation documentation, and EU-Japan import certification requirements supplied validation benchmarks. Bottom-up capacity assessments across Bandung and Solo manufacturing clusters were reconciled with top-down trade flow analysis.
Data-stream reconciliation across production volume surveys, energy consumption benchmarks, and wastewater discharge permit records shaped the analytical framework. Segmentation modeling incorporated fiber type, end-use application, distribution channel, and regional regulatory cluster dimensions. CAGRs were derived from trend extrapolation of installed capacity, compliance investment cycles, and export order flow patterns. Polyester feedstock proximity advantages and cotton import dependency ratios served as industry-specific forecast inputs across the projection horizon.
The model assumes a particular technology adoption path for closed-loop dyeing systems; alternative pathways for chemical recovery processes would alter the outlook for margin compression timelines. Forecasts reflect assumptions around enforcement consistency for Ministry of Industry wastewater standards and permit processing velocity in West Java. Raw material volatility in international cotton markets and technical substitution from non-woven synthetics represent revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Natural Fiber Reinforced Composites Market
Natural Fibers
Silk Stocking Market
Natural Fibers
Silk Market
Natural Fibers
Fenugreek Fiber Market
Natural Fibers
Silk Fabric Market
Natural Fibers
North America Alpaca Fiber Market
Natural Fibers
Abaca Fiber Market
Natural Fibers
Natural Fiber Composite (NFC) Market
Natural Fibers
Textile Staples Market
Natural Fibers
Green Fibers Market
Natural Fibers
Sugarcane Fiber Market
Natural Fibers
North America Lyocell Fiber Market
Natural Fibers
Apple Fiber Market
Natural Fibers
Cellulose Acetate Fiber Market
Natural Fibers
Gum Fiber Market
Natural Fibers
Global Alpaca Fiber Market