
 Prism Coupler Market | 2026-2036
Prism Coupler Market Size, Share, and Industry Trends Forecast 2026-2036
Prism Coupler Market Analytics
The capital-intensity divergence between integrated photonics foundries and discrete component assemblers is reorganizing supplier hierarchies in prism coupler procurement. Thorlabs, Inc. leverages captive polishing and coating capabilities to sustain margin control across cylindrical and rectangular product lines. Edmund Optics Inc. competes through catalog breadth and same-day fulfillment infrastructure that anchors North American research laboratory demand. Schäfter+Kirchhoff differentiates via laser-based alignment systems bundled with precision coupler subassemblies.
A prism coupler is an optical device that couples electromagnetic radiation into or out of a waveguide structure through frustrated total internal reflection at a precisely controlled gap, typically requiring sub-micron positional accuracy and refractive index matching within 0.001. It serves primarily to characterize waveguide modes, measure refractive indices, and interface fiber systems with planar photonic circuits in telecommunications and sensor development. Cylindrical prism couplers dominate volume shipments for fiber optic testing applications where rotational symmetry simplifies alignment, while integrated photonics technology represents the fastest-expanding segment as silicon photonics foundries scale mode-converter deployment. Biomedical applications command premium positioning due to stringent surface quality and biocompatibility certification requirements that constrain supplier pools.
ISO 10110 surface imperfection standards and IEC 61300 fiber optic interconnect specifications govern dimensional tolerances and optical performance verification across manufacturing locations. The US FDA regulates prism couplers incorporated into Class II medical laser systems through 21 CFR 1040 performance standards, while REACH compliance documentation from ECHA shapes coating chemistry selection for European market access. Stakeholders must monitor foundry capacity allocation between datacom transceivers and test instrumentation as silicon photonics capital commitments reshape component availability timelines.
Market Dynamics
Silicon photonics foundries are reallocating capital from test instrumentation toward datacom transceiver production, compressing component availability timelines for prism coupler procurement while elevating captive sourcing strategies.
Growth Catalysts
- REACH substance restrictions:ECHA compliance mandates on optical coating materials are redirecting procurement toward certified German and Swiss substrate suppliers, tightening supplier qualification pools.
- Autonomous vehicle testing:Optical sensor deployment in LiDAR calibration and waveguide characterization programs is expanding instrument demand across automotive R&D facilities.
- Silicon photonics scaling:Mode-converter deployment in foundry process development is accelerating requirements for high-precision coupler subassemblies in pilot production lines.
Market Restraints
- Substrate cost volatility:Synthetic fused silica and calcium fluoride crystal supply concentration in Ukrainian and Chinese mining operations creates input price instability for coupler fabrication.
- Technical limitation:Sub-micron gap control requirements restrict throughput in high-volume manufacturing, capping economies of scale for rectangular prism geometries.
- Regulatory friction:US FDA 21 CFR 1040 laser system certification timelines extend 14-18 months for biomedical coupler applications, delaying revenue recognition.
Strategic Opportunities
- Underpenetrated biomedical segment:Biocompatibility-certified couplers for implantable photonic devices remain underserved, with only three qualified suppliers serving ISO 10993-compliant demand.
- Technology convergence:Integration of prism couplers with femtosecond laser micromachining systems enables single-step waveguide inscription and mode characterization.
- Regulatory tailwind:EU MDR Class IIb medical device traceability requirements are mandating optical test instrumentation upgrades in European contract manufacturing organizations.
Industry Challenges
- Specialized optomechanical talent scarcity:Precision alignment engineering expertise concentrates in Germany's Jena-Oberkochen corridor, constraining foundry expansion in other geographies.
- Certification timeline compression:IEC 61300 fiber optic interconnect testing protocols require 6-9 month validation cycles that conflict with silicon photonics foundry ramp schedules.
- IP licensing complexity:Frustrated total internal reflection gap control patents held by legacy research institutions create royalty stacking for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prism Coupler Market |
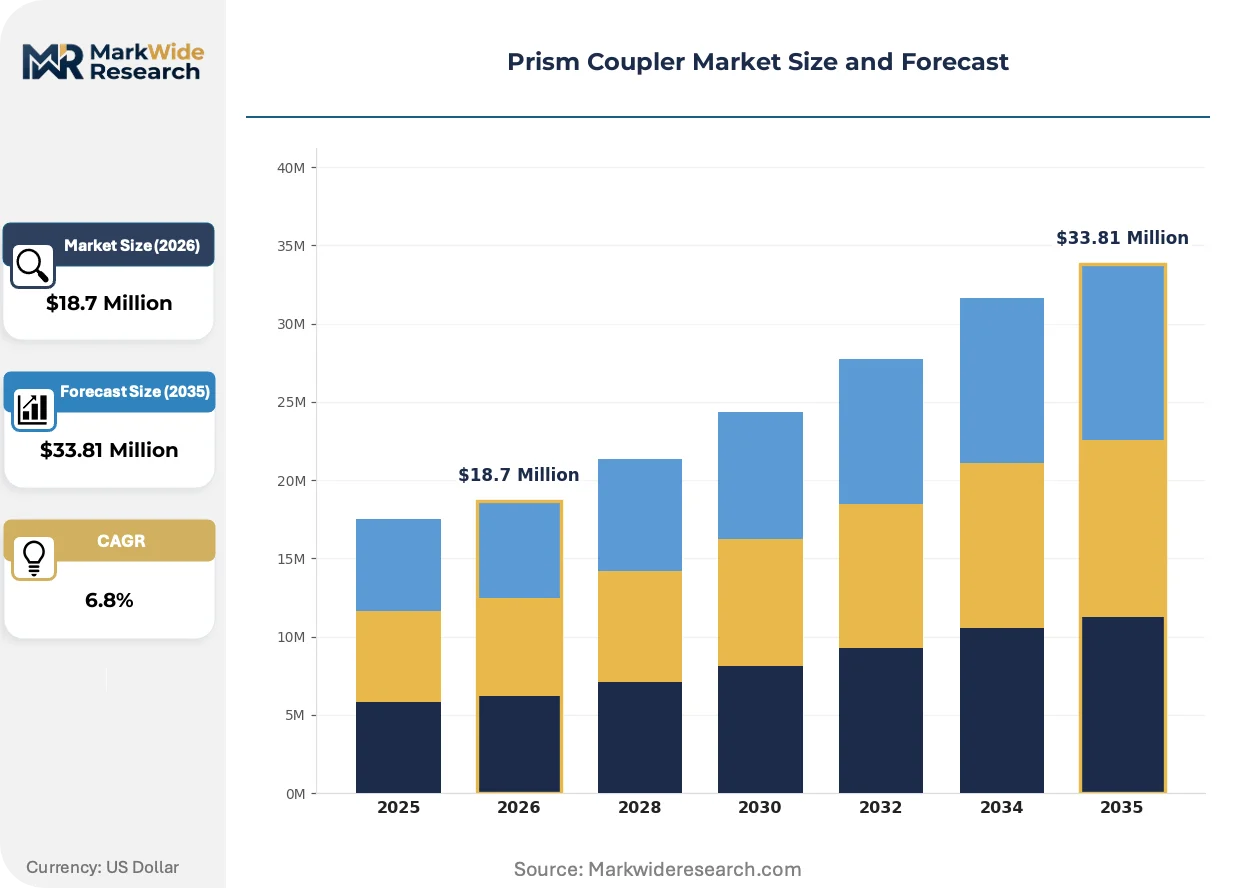
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $33.81 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cylindrical, Rectangular, Spherical, Aspheric Application: Telecommunications, Optical Sensors, Spectroscopy, Biomedical End User: Research Laboratories, Telecom Companies, Healthcare Providers, Educational Institutions Technology: Fiber Optic, Waveguide, Laser-based, Integrated Photonics |
| Companies Covered | Thorlabs, Inc., Newport Corporation, Edmund Optics Inc., OptoSigma Corporation, Horiba, Ltd., Melles Griot, Schäfter+Kirchhoff, Tempotec Optics, Standa Photonics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prism Coupler Market Evolving Landscape
Active alignment automation and coating chemistry substitution are compressing production timelines while expanding application scope beyond traditional telecommunications testing.
Free-space micro-optical benches with integrated prism couplers are supplanting fiber-pigtailed test fixtures in silicon photonics wafer-level probing. Foundry process development groups at IMEC and CEA-Leti are adopting these configurations for 300mm wafer mode mapping. This architecture is supplanting discrete component test stations by enabling parallel multi-channel characterization with sub-micron repeatability.
ECHA REACH Annex XIV authorization requirements for perfluorinated coating chemistries are compelling reformulation of anti-reflection layers. German precision optics suppliers are qualifying magnesium fluoride and silicon dioxide multilayer stacks as compliant alternatives. Biomedical coupler manufacturers face the steepest reformulation burden, as surface energy specifications for cell-culture compatibility conflict with traditional hydrophobic coatings.
Research laboratories are consolidating vendor relationships around same-day fulfillment capabilities rather than catalog breadth. North American university photonics groups now specify 24-hour delivery windows in procurement tenders, compressing distributor inventory positioning. This pattern is most pronounced in Boston-Cambridge and San Francisco Bay Area research clusters, where grant-funded projects operate on compressed experimental timelines.
Prism Coupler Market Segmentation
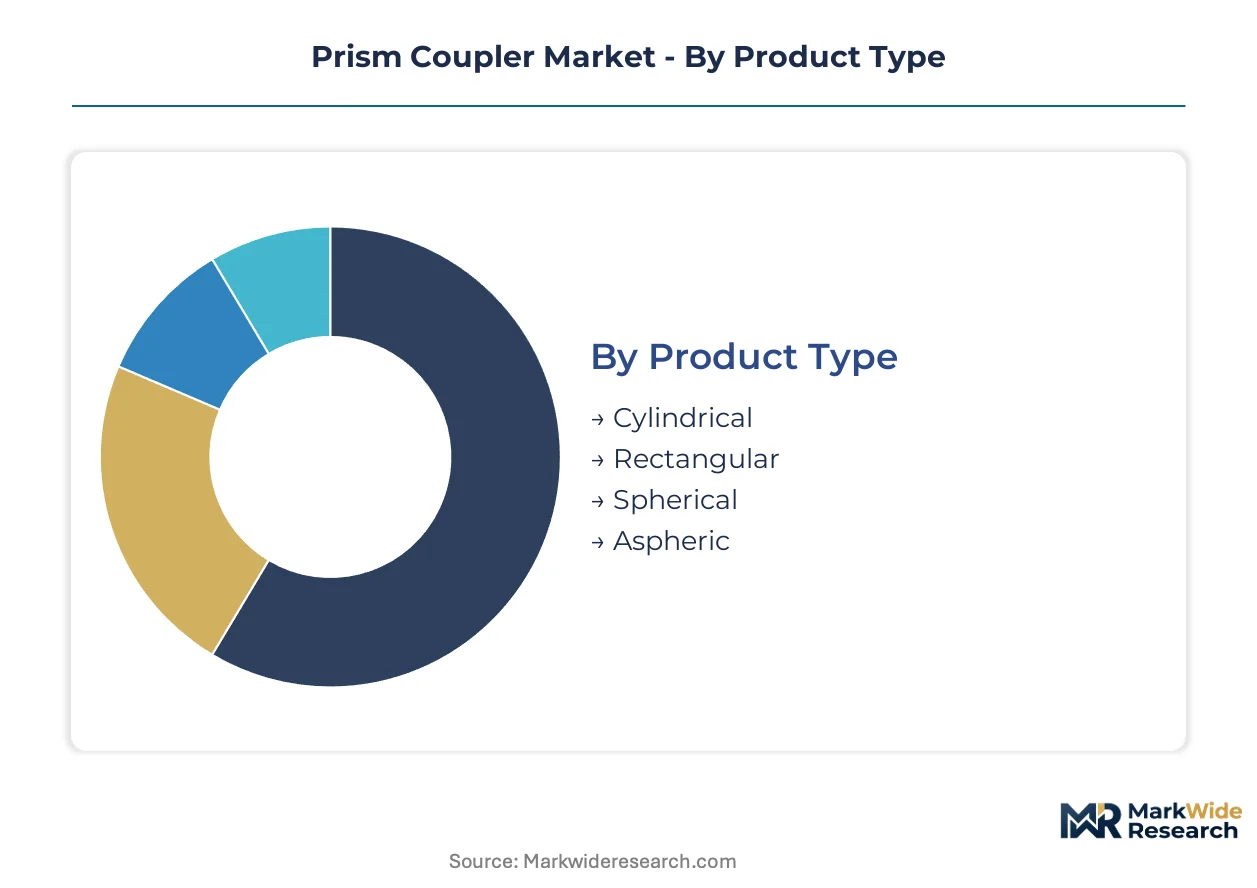
Prism coupler procurement patterns diverge sharply across product geometries and end-use certifications. Segment boundaries determine supplier qualification requirements, coating chemistry compliance, and alignment automation investments.
Product Type:
Cylindrical and rectangular geometries anchor domestic production in Germany's Jena-Oberkochen precision optics cluster, while spherical and aspheric variants rely on export-oriented Swiss and Japanese polishing houses.
- Cylindrical:Rotational symmetry simplifies fiber optic testing alignment procedures. Demand concentrates in North American telecom certification labs where IEC 61300 fiber interconnect validation drives volume procurement.
- Rectangular:Flat coupling surfaces enable planar photonic circuit interfacing with sub-micron gap control. Silicon photonics foundries in Belgium and the Netherlands specify these for 300mm wafer mode mapping stations.
- Spherical:Curved surface geometry suits free-space optical bench configurations. Swiss suppliers dominate precision polishing for this geometry.
- Aspheric:Non-spherical surface profiles correct wavefront aberrations in high-NA applications. Japanese glass-molding expertise anchors supply.
Cylindrical commands the established base. The steepest expansion runs through rectangular.
Application:
Cost tiers separate commodity telecommunications testing from premium biomedical certification, with spectroscopy and optical sensors occupying mid-range positioning.
- Telecommunications:Standardized fiber characterization protocols drive high-volume, lower-margin procurement. Datacom transceiver manufacturers in the United States and China represent the core demand pool.
- Biomedical:ISO 10993 biocompatibility and FDA 21 CFR 1040 laser system certification create steep supplier barriers. Implantable photonic device manufacturers pay 40-60% premiums for qualified couplers.
- Optical Sensors:LiDAR calibration and autonomous vehicle waveguide testing expand instrument demand. Automotive R&D facilities in Germany and California specify these for pilot production lines.
- Spectroscopy:Research-grade surface quality requirements align with university photonics group procurement. Same-day fulfillment capabilities determine vendor selection in Boston-Cambridge and Bay Area clusters.
Telecommunications commands the established base. The steepest expansion runs through biomedical.
End User:
Customer type determines volume scale and certification burden, with research laboratories prioritizing catalog breadth while healthcare providers enforce stringent traceability protocols.
- Research Laboratories:Grant-funded experimental timelines compress procurement cycles. North American university groups now mandate 24-hour delivery windows in tender specifications.
- Healthcare Providers:EU MDR Class IIb medical device traceability requirements mandate optical test instrumentation upgrades. European contract manufacturing organizations drive compliant coupler demand.
- Telecom Companies:Datacom transceiver production scales require mode-converter subassemblies in volume. Foundry capacity allocation tensions constrain component availability.
- Educational Institutions:Undergraduate photonics training programs prioritize cost-efficient cylindrical geometries. Budget constraints limit penetration of integrated photonics configurations.
Research laboratories command the established base. The steepest expansion runs through healthcare providers.
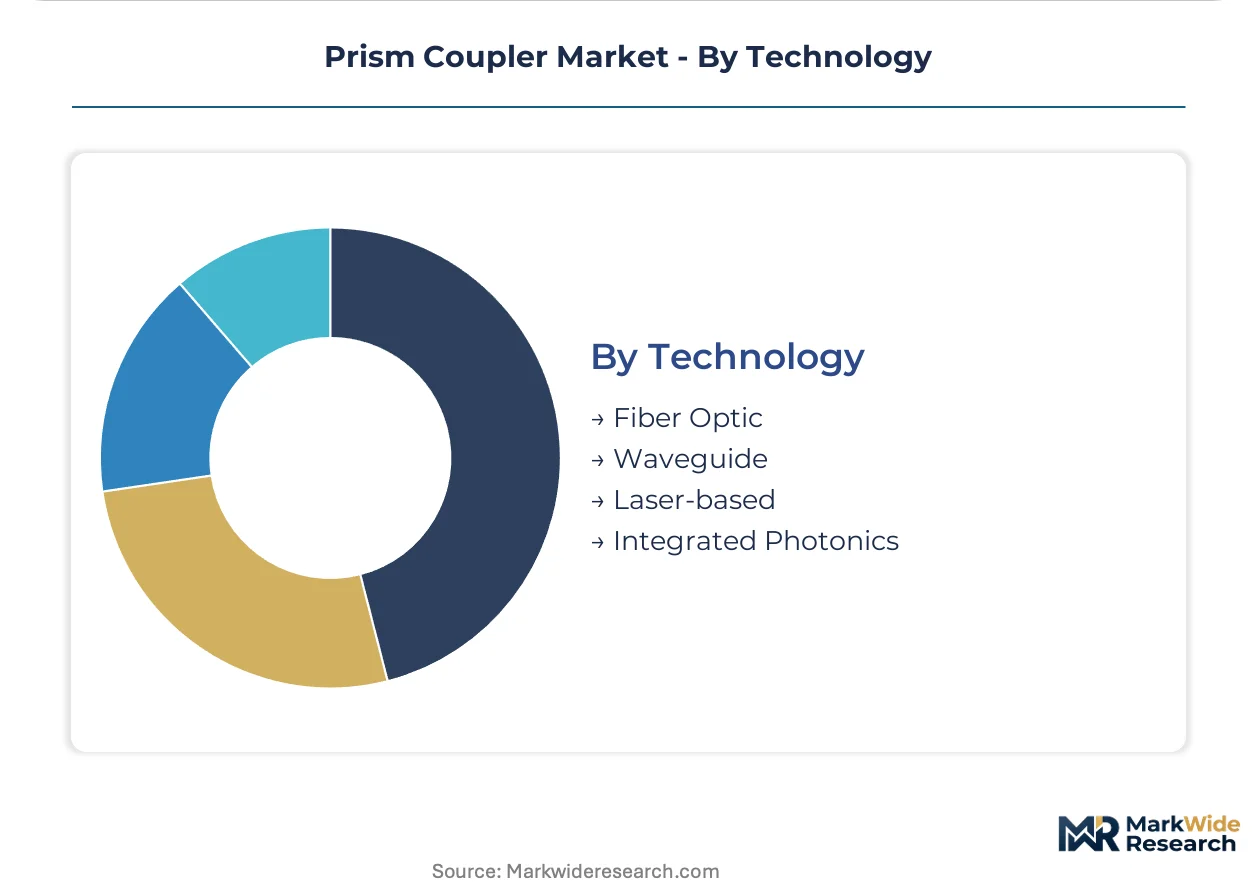
Technology:
Technology maturity separates legacy fiber optic installations from emerging integrated photonics architectures, with waveguide and laser-based systems occupying transitional positioning.
- Integrated Photonics:Silicon photonics foundry process development accelerates mode-converter deployment. IMEC and CEA-Leti pilot lines specify these for parallel multi-channel wafer probing.
- Fiber Optic:Established telecommunications infrastructure sustains cylindrical coupler demand. Legacy test stations in carrier networks resist architectural migration.
- Waveguide:Planar lightwave circuit characterization bridges fiber and photonic chip domains. Characterization laboratories in Germany and the United States anchor demand.
- Laser-based:Femtosecond micromachining integration enables single-step waveguide inscription. Equipment OEMs bundle alignment systems with precision coupler subassemblies.
Fiber optic commands the established base. The steepest expansion runs through integrated photonics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research laboratories in the United States exhibit the highest price elasticity, squeezing margins through 24-hour delivery mandates, while biomedical buyers in Germany absorb 40-60% premiums for ISO 10993-certified couplers without volume negotiation.
Germany
Precision optics demand concentrates in autonomous vehicle LiDAR calibration and silicon photonics foundry equipment. ECHA REACH Annex XIV authorization requirements redirect procurement toward certified substrate suppliers in Jena and Oberkochen. The Jena-Oberkochen corridor anchors production of cylindrical and rectangular geometries for fiber optic and planar photonic applications.
United States
Datacom transceiver manufacturers and university photonics groups drive divergent demand patterns. FDA 21 CFR 1040 laser system certification extends 14-18 month timelines for biomedical coupler applications. Boston-Cambridge and San Francisco Bay Area research clusters mandate same-day fulfillment windows in procurement specifications.
China
Synthetic fused silica supply concentration creates input cost volatility for domestic coupler fabrication. MIIT standards govern optical component performance verification for telecommunications infrastructure deployment. Yangtze River Delta precision optics houses scale cylindrical coupler output for fiber interconnect testing.
Japan
Aspheric prism coupler demand aligns with high-NA wavefront correction requirements in advanced imaging systems. METI industrial standards shape coating chemistry selection for export-oriented production. Glass-molding expertise in Nagoya and Osaka metropolitan areas anchors non-spherical surface profile supply.
Switzerland
Spherical geometry polishing for free-space optical benches sustains premium positioning in European research markets. Swissmedic medical device traceability requirements intersect with EU MDR Class IIb mandates for healthcare provider procurement. Zurich and Basel precision optics suppliers qualify magnesium fluoride multilayer stacks as REACH-compliant coating alternatives.
Prism Coupler Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in prism coupler supply. Captive polishing and coating capabilities distinguish the upper tier from assemblers dependent on external substrate sourcing. Three archetypes prevail: catalog-broad distributors anchoring North American research demand, precision alignment system bundlers serving foundry process development, and vertically integrated photonics component houses controlling margin through in-house fabrication. Competitive moves concentrate on strategic partnerships with silicon photonics foundries and geographic expansion into biomedical certification clusters.
Among integrated photonics specialists, Thorlabs, Inc. and Schäfter+Kirchhoff occupy positions that exemplify divergent bundling strategies. Catalog-scale distributors include Edmund Optics Inc. These three names represent the competitive spectrum from captive manufacturing to fulfillment infrastructure, with each archetype responding differently to foundry capacity allocation tensions and REACH compliance documentation burdens.
| Leading Market Players |
|---|
| Thorlabs, Inc. |
| Newport Corporation |
| Edmund Optics Inc. |
| OptoSigma Corporation |
| Horiba, Ltd. |
| Melles Griot |
| Schäfter+Kirchhoff |
| Tempotec Optics |
| Standa Photonics |
| Others |
Value Network & Pricing Analysis
Forty-five to sixty-day lead times for REACH-compliant substrate qualification concentrate pricing power among German and Swiss suppliers while compressing margins for assemblers dependent on external sourcing. This inventory dynamic couples with ECHA coating chemistry mandates to elevate input costs for biomedical-grade couplers against commoditized telecommunications variants.
Pricing Analysis
After-market calibration service contracts now generate lifetime value multiples exceeding hardware margins for precision alignment system bundlers. Three-tier pricing structure across ISO 10993-certified biomedical, IEC 61300-compliant telecommunications, and research-grade spectroscopy tiers anchors transaction structures. Cost compression in standard fiber optic testing intensifies as Chinese cylindrical coupler output scales, while German buyers absorb premium positioning without volume negotiation. Research laboratories in North America exhibit highest price elasticity through 24-hour delivery mandates.
Supply Chain Analysis
Sixty-day substrate qualification timelines tether inventory positioning to German and Ukrainian synthetic fused silica supply. Calcium fluoride crystal draws from Chinese mining operations and Japanese polishing houses, creating geographic concentration risk. REACH Annex XIV authorization restrictions on perfluorinated coatings constitute the dominant regulatory chokepoint. Distribution runs through catalog-scale distributors anchoring North American research demand and direct foundry relationships for silicon photonics mode-converter subassemblies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recurring revenue from alignment system calibration contracts and coating recertification services expands faster than hardware shipments, reframing this market as a service-attach opportunity rather than component transaction play.
For Market Incumbents: Shield margin position by deepening captive polishing capabilities in the Jena-Oberkochen corridor against Chinese cylindrical coupler cost compression. Prioritize ISO 10993 biocompatibility certification investment to capture 40-60% premium pricing in implantable photonic device supply, insulating against commoditization in fiber optic testing segments. For New Entrants and Emerging Players: Same-day fulfillment infrastructure gaps in North American research clusters offer white-space entry through 24-hour delivery capability builds. Target Boston-Cambridge and San Francisco Bay Area university photonics groups with consolidated vendor relationships. Lead with spectroscopy-grade surface quality positioning to bypass telecommunications margin compression. For Investors and Strategic Acquirers: Long-term, this sits as a precision optomechanical capability play because silicon photonics foundry scaling creates durable demand for sub-micron alignment expertise. Acquisition candidates center on German mid-caps with captive coating reformulation capabilities navigating REACH compliance. Watch foundry capacity allocation signals between datacom transceivers and test instrumentation as inflection indicator for component availability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Coating Reformulation | ECHA Annex XIV mandates force magnesium fluoride stack qualification at Swiss and German suppliers. |
| Silicon Photonics Foundry Partnership | IMEC and CEA-Leti pilot line integration secures mode-converter subassembly placement. |
| Biomedical Certification Investment | ISO 10993 and FDA 21 CFR 1040 compliance unlocks 40-60% premium tier positioning. |
| Same-Day Fulfillment Infrastructure | North American research cluster 24-hour delivery mandates compress distributor inventory positioning. |
| Femtosecond Laser Micromachining Integration | Single-step waveguide inscription bundling expands addressable market beyond discrete coupler sales. |
Research Methodology
A spread of perspectives from silicon photonics foundry process engineers, precision optics procurement managers, biomedical device regulatory affairs leads, and university photonics laboratory directors converged on the working assumptions. Primary fieldwork combined with secondary validation from ECHA substance restriction databases, FDA 510(k) laser system filings, IEC fiber optic interconnect standards documentation, and German precision optics trade association capacity surveys. Bottom-up unit demand modeling and top-down market sizing triangulated volume estimates across the analysis window.
Segmentation dimensions modeled include product geometry, application certification tier, end-user type, and technology architecture across the projection horizon. CAGRs derived from weighted average of historical foundry equipment procurement cycles, REACH compliance timeline impacts, and autonomous vehicle LiDAR testing program expansion rates. Mode-converter deployment intensity and coating chemistry substitution velocity served as industry-specific forecast inputs.
Underlying assumptions cover silicon photonics capital commitment continuity, ECHA authorization timeline adherence, and Ukrainian synthetic fused silica supply stability, with deviation risk concentrated in foundry capacity reallocation toward datacom transceivers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Spatial Light Modulator Market
Optical Components
Silicon Photonics Market
Optical Components
Global Adaptive Optics Market
Optical Components
Global Wavelength Division Multiplexing (WDM) Equipment Market
Optical Components
Objective Lens Market
Optical Components
Erbium Oxide Market
Optical Components
Co-Packaged Optics Market
Optical Components
Optical Fiber and Plastic Conduit Market
Optical Components
Optical Transmitter Market
Optical Components
Erbium-Doped Fiber Amplifier Market
Optical Components
Optical Amplifier Market
Optical Components
Global Diffractive Optical Elements Market
Optical Components
Asia-Pacific Optical Film Market
Optical Components
High Speed Fiber Optic Sensor Market
Optical Components
Bio-Optics Market
Optical Components
LGP (Light Guide Plate) for TV Market