
 Cervical Cancer Drugs Market | 2026-2036
Cervical Cancer Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
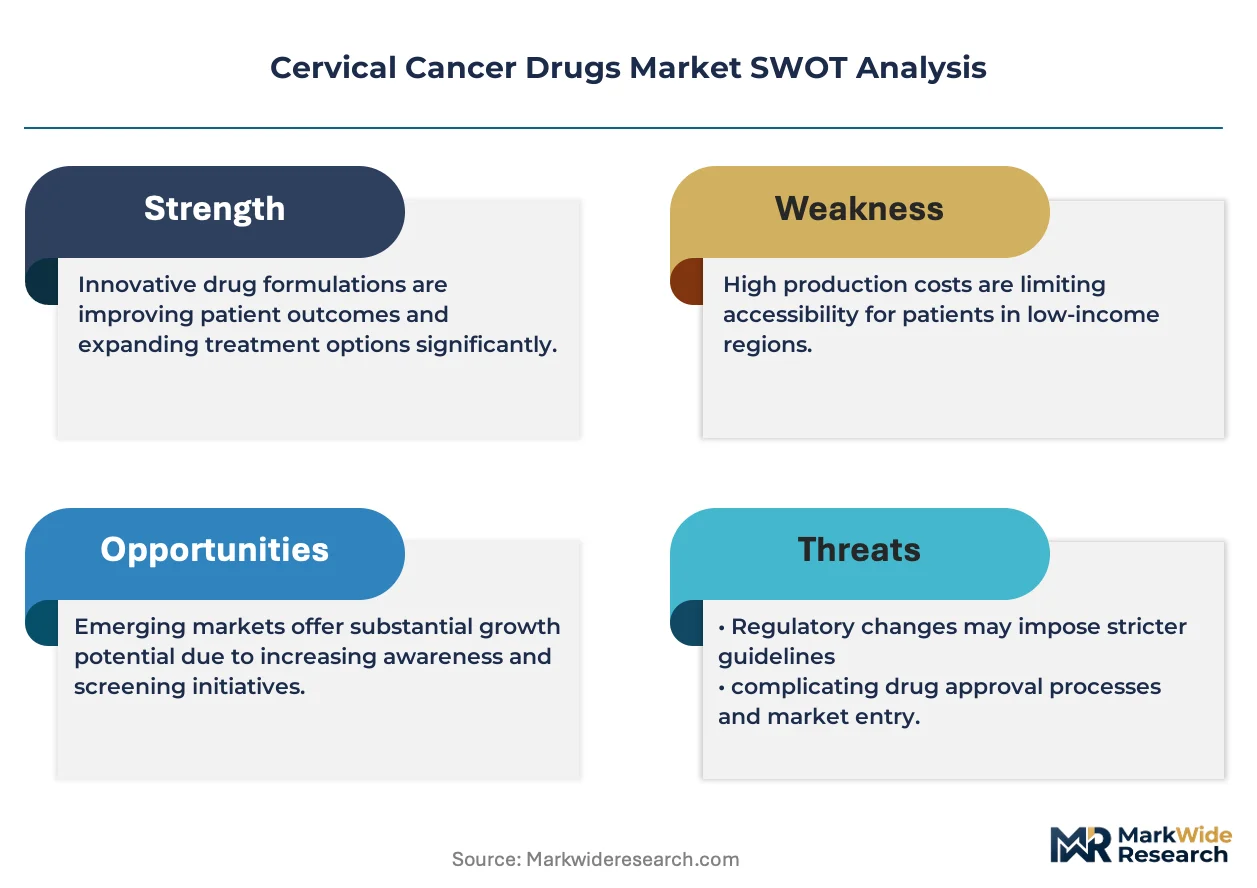
Cervical Cancer Drugs Market Analysis
Biologics manufacturing capacity in South Korea is decoupling from traditional small-molecule production networks. Merck & Co., Inc. leverages its PD-1 franchise to anchor immunotherapy penetration in recurrent and metastatic settings. F. Hoffmann-La Roche Ltd sustains broad oncology infrastructure across Europe and Asia. Bristol-Myers Squibb Company differentiates through checkpoint inhibitor combinations under active clinical investigation.
Cervical cancer drugs comprise systemic therapeutic agents designed to interrupt malignant cell proliferation in squamous or adenocarcinoma lesions of the uterine cervix, typically administered as platinum-taxane combinations, immune checkpoint inhibitors, or angiogenesis blockers with dosing calibrated to FIGO staging and patient performance status. Their primary purpose is to extend progression-free survival in locally advanced disease and improve overall survival in metastatic presentations. Immunotherapy now leads product type expansion as pembrolizumab combinations reshape first-line standards, while monoclonal antibodies within the drug class segment capture disproportionate margin pools due to biosimilar lag and manufacturing complexity. Intravenous administration still dominates volume, though subcutaneous formulations are gaining fastest as patient preference and clinic throughput pressures mount.
The FDA's breakthrough therapy designation and the EMA's PRIME scheme both compress regulatory review timelines for novel cervical cancer agents, directly shaping sponsor investment priorities and trial design. WHO prequalification requirements for low- and middle-income country procurement create parallel compliance tracks that manufacturers must navigate for volume access. Stakeholders should monitor how CMS national coverage determinations for combination regimens reshape commercial formularies and site-of-care economics.
Market Dynamics
Checkpoint inhibitor combinations are compressing treatment paradigms across FIGO staging categories, forcing oncology networks to reconfigure infusion capacity and biomarker testing workflows around pembrolizumab-based protocols.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The accelerated approval pathway compresses development timelines for novel agents in recurrent and metastatic settings, redirecting sponsor capital toward cervical-specific trials.
- South Korean Biologics Manufacturing:Dedicated capacity for monoclonal antibody production is decoupling from small-molecule networks, securing supply continuity for immune checkpoint inhibitors.
- Medicare Reimbursement Expansion:CMS national coverage determinations for combination regimens reshape prescribing patterns across United States oncology clinics, anchoring demand concentration.
Market Restraints
- Platinum Supply Concentration:Reliance on concentrated mining jurisdictions for cisplatin and carboplatin precursors creates input cost volatility that squeezes margin pools in first-line chemotherapy.
- Biosimilar Lag for Monoclonal Antibodies:Manufacturing complexity and analytical similarity requirements delay generic entry for PD-1 inhibitors, sustaining elevated pricing pressure on payers.
- EMA Parallel Track Requirements:Divergent evidence standards between FDA accelerated approval and EMA conditional marketing authorization force duplicate clinical investment for European access.
Strategic Opportunities
- Subcutaneous Formulation Migration:Patient preference for reduced infusion time and clinic throughput pressures are opening white space for subcutaneous checkpoint inhibitor delivery systems.
- WHO Prequalification Pathway:Compliance infrastructure for low- and middle-income country procurement creates volume access tiers beyond traditional OECD markets.
- Biomarker-Guided Patient Stratification:PD-L1 testing integration with next-generation sequencing is enabling precision enrollment in combination trials, compressing development risk.
Industry Challenges
- Immuno-oncology Talent Scarcity:Shortage of clinical investigators experienced with checkpoint inhibitor combination design slows trial activation across academic medical centers.
- Site-of-Care Economics Reconfiguration:Shift from hospital outpatient departments to community oncology practices requires cold-chain logistics and nursing competency redeployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cervical Cancer Drugs Market |
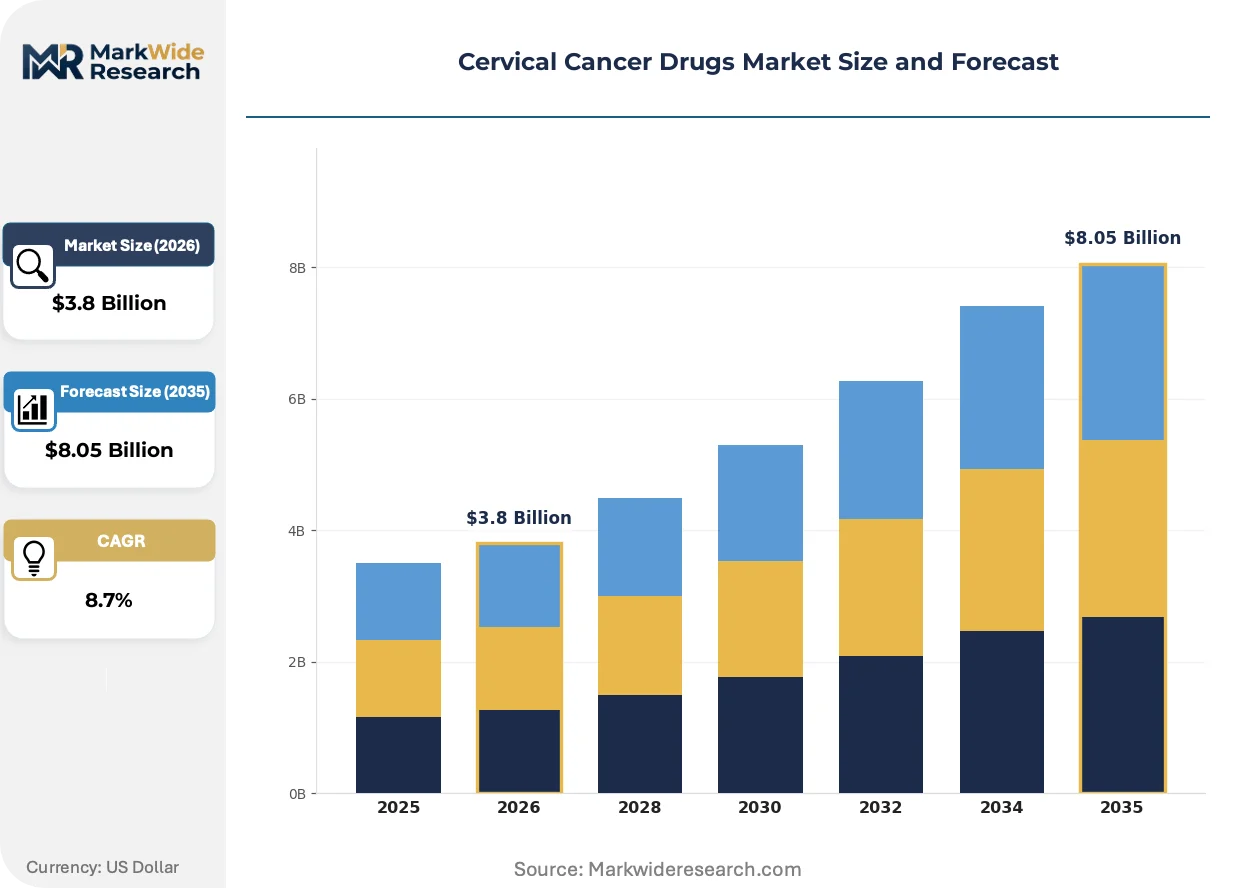
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Targeted Therapy, Hormonal Therapy Administration Route: Intravenous, Oral, Subcutaneous, Topical End User: Hospitals, Oncology Clinics, Research Institutions, Homecare Drug Class: Monoclonal Antibodies, Antineoplastic Agents, Vaccines, Others |
| Companies Covered | Merck & Co., Inc., F. Hoffmann-La Roche Ltd, Pfizer Inc., Seagen Inc., GSK plc, Novartis AG, Bristol-Myers Squibb Company, AstraZeneca PLC, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cervical Cancer Drugs Market Emerging Trajectories
Immunotherapy platform expansion is absorbing capital and clinical trial capacity at the expense of cytotoxic development, while administration modality and regulatory pathway innovations reshape competitive entry patterns.
Subcutaneous pembrolizumab formulations are absorbing patient volume from intravenous delivery across United States community oncology networks. Community practices prioritize throughput efficiency and reduced chair time. The technology is absorbing margin pressure from infusion center capacity constraints while preserving therapeutic equivalence.
EMA's PRIME scheme for priority medicines compresses scientific advice timelines and accelerates access to the centralized procedure for novel cervical cancer agents. Sponsors gain earlier regulatory engagement on pivotal trial design. European biotechnology developers are responding by anchoring development strategies in parallel FDA-EMA submission pathways.
Patient advocacy networks are compressing switching cycles between treatment lines as real-world evidence platforms disseminate progression-free survival data. Direct-to-patient education channels are displacing traditional physician-mediated information flows. This behavioral shift concentrates most visibly in United States markets where Medicare Advantage plans deploy prior authorization transparency tools.
Cervical Cancer Drugs Market Segmentation
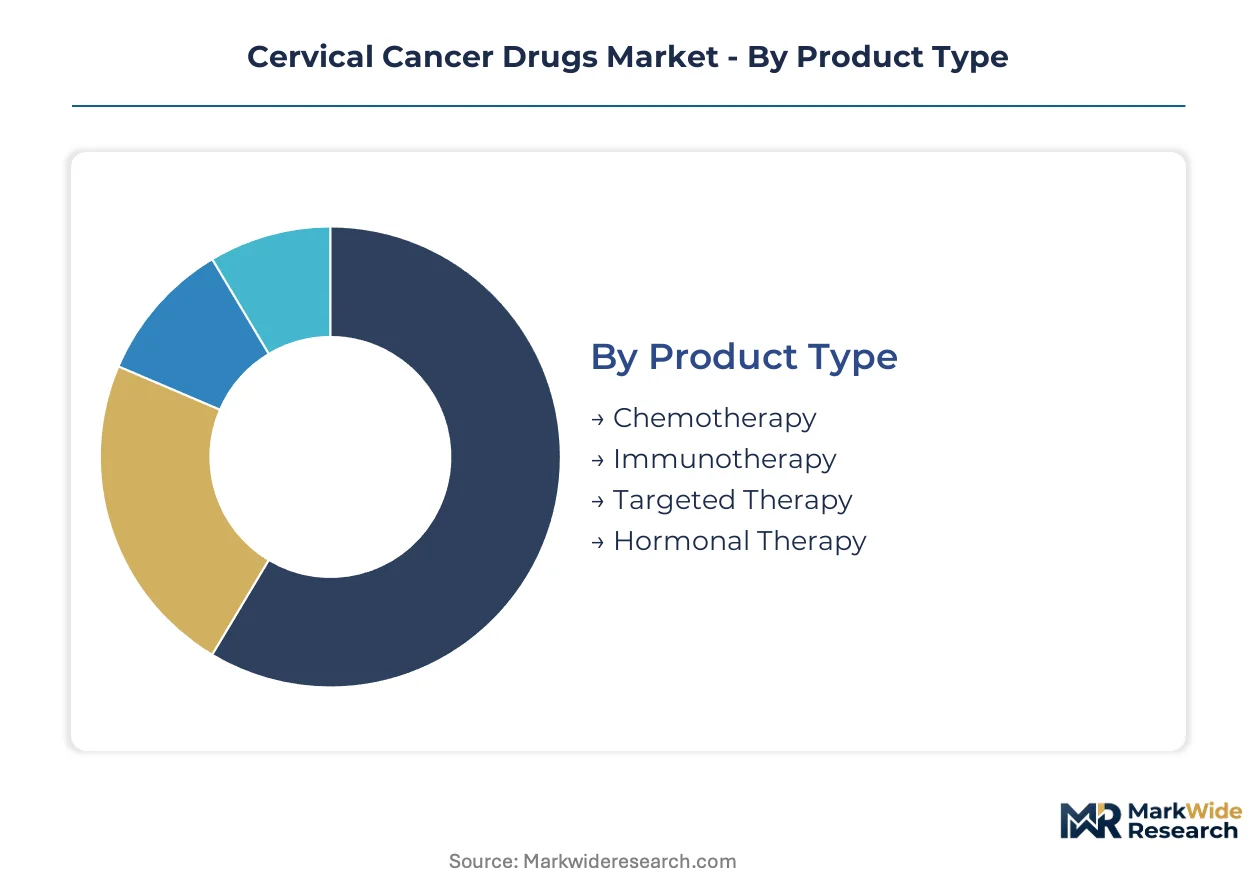
Cervical cancer drug segmentation reveals how treatment modality and delivery setting determine reimbursement pathways and margin structures. Product type and administration route splits expose where immunotherapy premiums concentrate versus where chemotherapy volume still dominates.
Product Type:
Volume concentrates in platinum-taxane chemotherapy while premium capture shifts toward checkpoint inhibitor combinations.
- Immunotherapy:PD-1 and PD-L1 inhibitors interrupt tumor immune evasion through T-cell activation. Demand clusters in United States oncology clinics where Medicare reimbursement anchors first-line pembrolizumab combinations for recurrent and metastatic disease.
- Chemotherapy:Cisplatin and carboplatin plus paclitaxel remain the backbone for locally advanced cervical cancer. Volume concentrates in hospital outpatient departments across India and Brazil where cost constraints limit immunotherapy access.
- Targeted Therapy:Bevacizumab and other angiogenesis inhibitors extend progression-free survival in select patients.
- Hormonal Therapy:Limited application in adenocarcinoma subtypes with hormone receptor positivity.
Today's leader: Chemotherapy. Tomorrow's challenger: Immunotherapy.
Administration Route:
Patient preference and clinic throughput economics are redistributing volume across delivery modalities.
- Intravenous:Infusion center delivery dominates checkpoint inhibitor administration with established cold-chain logistics. United States community oncology networks prioritize chair time efficiency as patient volumes strain capacity.
- Subcutaneous:Reduced administration time and lower nursing burden are capturing share fastest in European outpatient settings where healthcare worker scarcity pressures operational redesign.
- Oral:Convenience drives adherence in maintenance settings and resource-limited environments.
- Topical:Restricted to precancerous lesion management and palliative symptom control.
Intravenous anchors current volume. Subcutaneous climbs the fastest as formulation innovation accelerates.
End User:
Site-of-care migration from hospital systems to community practices reshapes distribution and service requirements.
- Oncology Clinics:Specialized infusion capacity and biomarker testing integration position these sites for immunotherapy expansion. United States community practices are absorbing volume from academic medical centers as prior authorization processes streamline.
- Hospitals:Complex comorbidity management and emergency response capability retain high-acuity cases. Indian tertiary hospitals concentrate first-line chemotherapy administration where public procurement schemes dominate.
- Research Institutions:Clinical trial enrollment and experimental protocol administration.
- Homecare:Subcutaneous self-administration and oral regimens enable remote monitoring models.
Hospitals retain acute complexity. Oncology clinics gain share fastest through convenience and cost positioning.
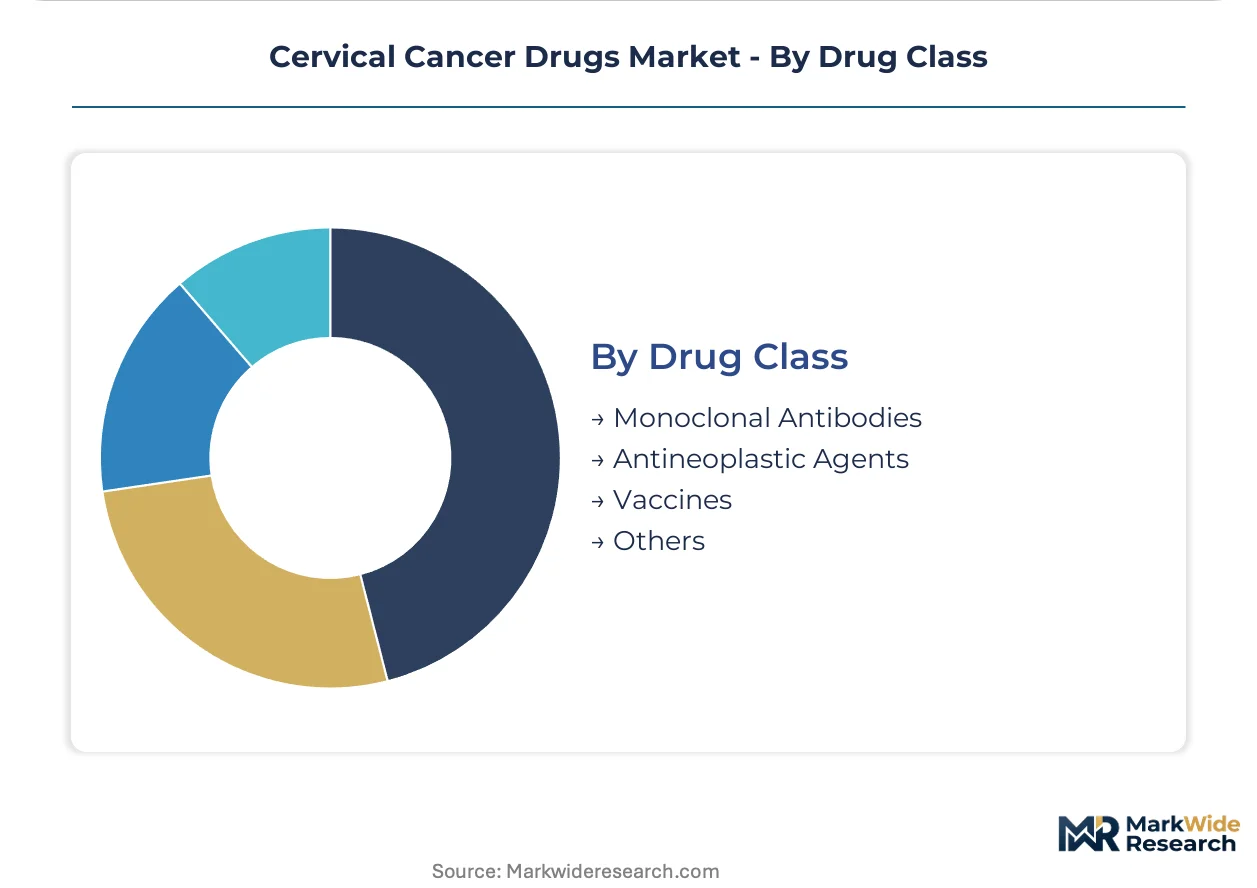
Drug Class:
Manufacturing complexity and biosimilar lag create divergent margin profiles across therapeutic categories.
- Monoclonal Antibodies:Recombinant protein production in mammalian cell cultures yields high specificity against PD-1 and PD-L1 targets. South Korean biologics manufacturers are decoupling capacity from small-molecule networks to secure supply continuity for pembrolizumab and atezolizumab.
- Antineoplastic Agents:Platinum compounds and taxanes face input cost volatility from concentrated mining jurisdictions for precursor metals.
- Vaccines:Prophylactic HPV immunization reduces incident cases in prevention-focused markets.
- Others:Small-molecule inhibitors and investigational agents in early development.
Monoclonal antibodies command premium positioning. Antineoplastic agents defend volume through cost accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing biologics manufacturing toward jurisdictions with streamlined GMP certification pathways and concentrated R&D tax incentives. South Korean contract manufacturers exploit this compliance-cost gap to capture monoclonal antibody production volume.
United States
Medicare reimbursement policies anchor demand concentration for pembrolizumab combinations in recurrent and metastatic settings. The FDA's breakthrough therapy designation compresses development timelines for novel agents. Oncology clinics in Texas and Florida are expanding immunotherapy infusion capacity to match rising patient volumes.
Germany
EMA's PRIME scheme for priority medicines accelerates scientific advice timelines for cervical cancer drug developers. The country's national pharmaceutical regulator enforces stringent batch-release protocols for imported biologics. Heidelberg and Munich host dense clusters of immuno-oncology trial sites investigating checkpoint inhibitor combinations.
South Korea
Dedicated biologics manufacturing capacity is decoupling from traditional small-molecule production networks. The MFDS maintains accelerated review pathways for innovative oncology therapies. Seoul-Incheon biotech corridors are securing supply continuity contracts for pembrolizumab and atezolizumab production.
India
Cost constraints concentrate first-line chemotherapy volume in hospital outpatient departments across Maharashtra and Karnataka. CDSCO approval pathways for biosimilars create parallel market entry tracks for trastuzumab and bevacizumab copies. Mumbai and Hyderabad manufacturing hubs are scaling platinum-compound production for export markets.
Japan
PMDA's sakigake designation system provides priority consultation for cervical cancer drug development programs. The country's national health insurance maintains distinct reimbursement tiers for innovative versus follow-on biologics. Tokyo-Osaka clinical research networks lead Asia-Pacific enrollment in PD-1 combination trials.
Cervical Cancer Drugs Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue biosimilar manufacturing and subcutaneous formulation niches. The market consolidates around three archetypes: integrated pharmaceutical conglomerates with PD-1 franchises, specialized oncology biotechnology developers, and contract manufacturing organizations with mammalian cell culture expertise. Dominant competitive moves include strategic partnerships for combination trial co-development and geographic licensing arrangements for emerging market access.
Among US-based integrated pharmaceutical conglomerates, Merck & Co., Inc. and Bristol-Myers Squibb Company exemplify the checkpoint inhibitor platform archetype, while Swiss-headquartered F. Hoffmann-La Roche Ltd occupies a position bridging diagnostic companion testing with therapeutic antibody development. These three entities represent contrasting approaches to immunotherapy market penetration.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| F. Hoffmann-La Roche Ltd |
| Pfizer Inc. |
| Seagen Inc. |
| GSK plc |
| Novartis AG |
| Bristol-Myers Squibb Company |
| AstraZeneca PLC |
| Sanofi |
| Others |
Supply Flow & Price Mechanics
Medicare Advantage prior authorization transparency tools in the United States are compressing switching cycles between treatment lines, forcing manufacturers to accelerate rebate negotiations with pharmacy benefit managers and compress net pricing spreads across oncology clinics.
Pricing Analysis
Wholesaler distribution margins absorb the primary pricing pressure in cervical cancer drug channels, with three-tier pricing structure across premium, standard, and economy levels stratifying by biomarker testing integration and infusion center certification. Price differentiation hinges on PD-L1 companion diagnostic bundling and cold-chain logistics reliability. Cost compression in first-line chemotherapy intensifies because platinum precursor volatility feeds through to net realized prices. Community oncology practices exhibit highest price sensitivity due to prior authorization burden, while academic medical centers prioritize clinical outcome data over acquisition cost.
Supply Chain Analysis
Reverse-logistics for temperature-controlled biologics returns minimal volume given perishable monoclonal antibody shelf constraints, though South Korean contract manufacturers are building refurbishment capabilities for fill-finish equipment. Active pharmaceutical ingredient production draws from India, China, and the United States for platinum salts and taxane precursors. Mammalian cell culture capacity rests on single-use bioreactor supply from specialized vendors in Germany and Massachusetts. Single-source vulnerability concentrates in South Korean fill-finish networks for pembrolizumab. Distribution runs through cold-chain logistics providers with validated 2-8°C handling across oncology clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cervical cancer drugs function as a stable compounder anchored by Medicare reimbursement expansion for immunotherapy combinations, with checkpoint inhibitor penetration creating durable revenue visibility across recurrent and metastatic treatment settings.
For Market Incumbents: Lock in pembrolizumab-based protocol anchoring through exclusive formulary contracts with United States oncology clinic networks. Expand backward integration into South Korean biologics manufacturing capacity to secure supply continuity against biosimilar lag expiration. Defensive positioning requires biomarker testing platform control and infusion center partnership density to repel emerging subcutaneous formulation entrants. For New Entrants and Emerging Players: FDA Breakthrough Therapy Designation in the United States opens a window for accelerated entry through combination trial co-development with established PD-1 franchises. White space concentrates in subcutaneous formulation development for European outpatient settings and WHO prequalification compliance for Indian and Brazilian hospital procurement channels. Community oncology practice prior authorization streamlining offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with contract manufacturing organizations possessing mammalian cell culture expertise and South Korean regulatory relationships. Long-term viability across the analysis window favors biologics capacity over small-molecule infrastructure given immunotherapy platform expansion. Acquisition targets should display validated GMP certification for monoclonal antibody production and established cold-chain distribution partnerships. Monitor CMS national coverage determinations for combination regimen reimbursement as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Checkpoint inhibitor combination protocols reshape FIGO staging treatment standards across academic medical centers. |
| Regulatory Approval Pathway | Parallel FDA-EMA submission strategies compress time-to-market for novel cervical cancer agents. |
| Manufacturing Scale-Up | South Korean biologics capacity expansion secures supply continuity for pembrolizumab and atezolizumab production. |
| Pipeline Diversification | Subcutaneous formulation development addresses patient preference and clinic throughput pressures in community settings. |
| Licensing Agreement | Geographic licensing arrangements unlock emerging market access beyond traditional OECD reimbursement systems. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov, and CMS Medicare reimbursement databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored market sizing across the analysis window.
Historical reference periods spanning pre-immunotherapy chemotherapy dominance through pembrolizumab combination approval anchored the forecast window, with analytical frameworks modeling treatment line, administration route, patient population, and regional regulatory cluster dimensions. CAGRs derived from patient volume projections cross-referenced with dosing regimen assumptions and net pricing trajectories. Forecast inputs incorporated biomarker testing penetration rates and infusion center capacity expansion timelines.
Revisions become necessary when CMS national coverage determinations shift combination regimen reimbursement, EMA conditional marketing authorization requirements diverge from FDA accelerated approval standards, or South Korean biologics manufacturing capacity experiences regulatory disruption. Practitioners should monitor prior authorization transparency tool deployment and WHO prequalification pathway compliance for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Atypical Antipsychotic Market
Pharmaceuticals
Global Non-Small Cell Lung Cancer Drugs Market
Pharmaceuticals
United States Pharmaceutical 3PL Market
Pharmaceuticals
Opium Tincture Market
Pharmaceuticals
Rupatadine Fumarate API Market
Pharmaceuticals
Global Paracetamol Market
Pharmaceuticals
Global Zika Vaccines Market
Pharmaceuticals
Hyperphosphatemia Market
Pharmaceuticals
Oral Thin Film Drugs Market
Pharmaceuticals
Compound Potassium Hydrogen Phosphate Injection Market
Pharmaceuticals
SGLT2 Inhibitors Market
Pharmaceuticals
Nuclear Medicines Radioisotopes Market
Pharmaceuticals
Global Pharmaceutical Traceability Market
Pharmaceuticals
North America Biguanide Market
Pharmaceuticals
Pharmacy and Drug Store Franchises Market
Pharmaceuticals
Adrenocorticotropic Hormone [ACTH] Market