
 Lamination Adhesive Market | 2026-2036
Lamination Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Lamination Adhesive Market Analytics
Water-based and reactive adhesive technologies are reshaping lamination workflows across high-speed packaging lines. Henkel leverages its European R&D base to sustain leadership in flexible food packaging grades. H.B. Fuller anchors North American supply through captive resin production and direct mill relationships. Dow competes on polyurethane chemistry breadth, extending from industrial films to automotive interior laminates.
Lamination adhesives bond multilayer substrates—films, foils, papers, and nonwovens—through chemistries including polyurethane, acrylic, and EVA systems cured thermally or by UV activation, achieving peel strengths from 1.5 to 8 N/cm depending on end-use. Water-based formulations now dominate food-contact applications where residual solvent migration poses regulatory risk, while reactive systems command premium positioning in automotive and electronics laminates requiring thermal cycling resistance. Hot melt adhesites occupy high-volume, cost-sensitive packaging tiers where speed of set outweighs ultimate bond performance.
EPA regulates VOC emissions from adhesive operations under 40 CFR Part 63, while REACH restricts isocyanate and solvent classifications across European supply chains, forcing reformulation investments. China's MEE enforces GB standards on airborne pollutant limits in manufacturing zones, tightening market access for imported solvent-based products. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and qualify for green procurement tenders.
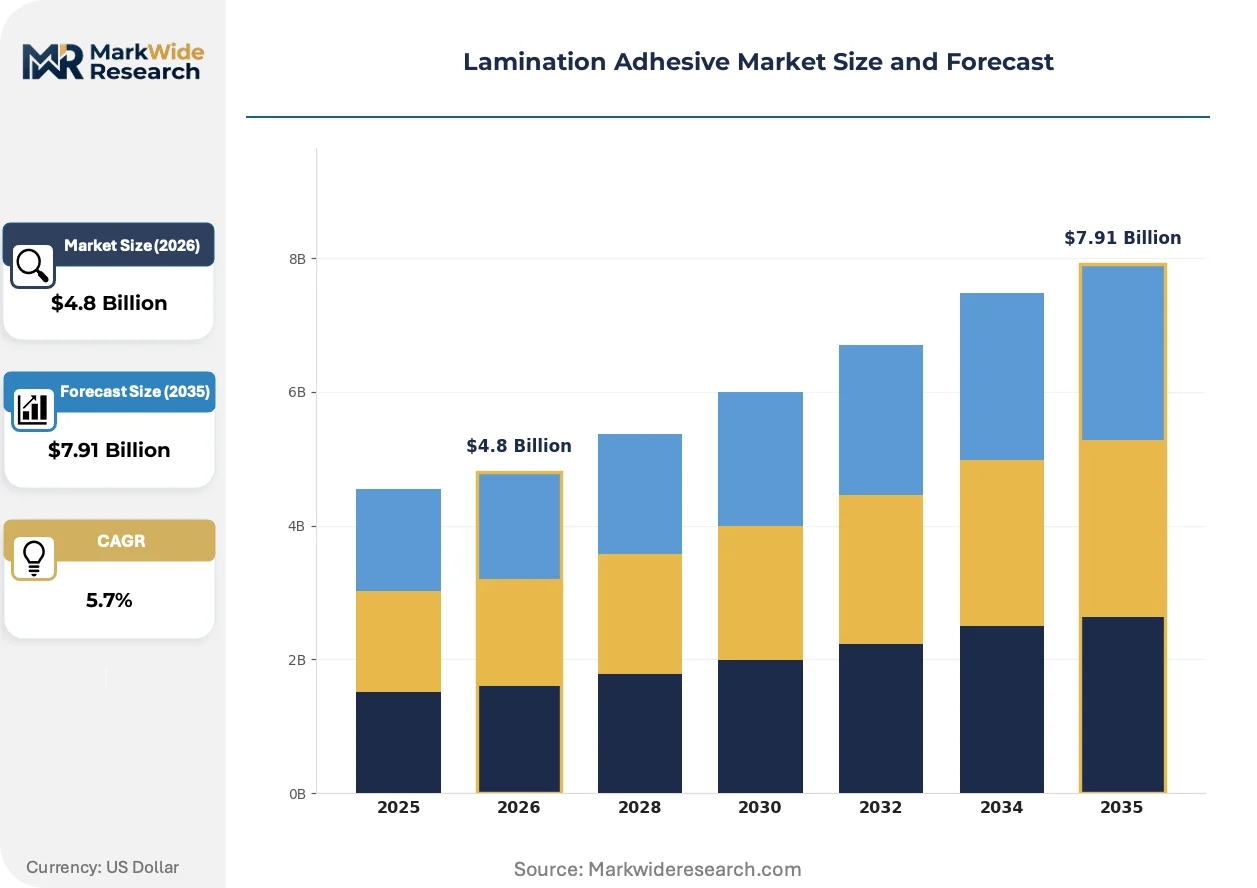
Market Dynamics
Solvent-free adhesive systems are displacing conventional solvent-based chemistries as food-packaging converters confront tightening VOC limits across manufacturing jurisdictions. This technology migration compresses formulation cycles and forces capital redeployment toward reactive polyurethane and UV-curable platforms.
Growth Catalysts
- REACH isocyanate restrictions:European ECHA classifications on aromatic isocyanates accelerate water-based and hot-melt adoption in flexible packaging laminates.
- India PLI-linked packaging expansion:Domestic converter capacity additions under the Production Linked Incentive scheme pull adhesive procurement toward localized supply chains.
- Solvent-free lamination lines:High-speed packaging equipment retrofits enable reactive polyurethane systems to bond films at 400+ meters per minute without thermal drying.
Market Restraints
- Polyol and isocyanate feedstock volatility:Crude-linked raw material costs swing formulation economics unpredictably, squeezing margin stability for mid-tier adhesive suppliers.
- Specialty resin supply concentration:Captive production of tailored polyesters and polyethers clusters among integrated chemical majors in Germany and the United States.
- Cure speed limitations of water-based systems:Thermal drying requirements constrain line speeds to 200-250 meters per minute, blocking deployment on the fastest flexible packaging equipment.
Strategic Opportunities
- India domestic converter buildout:Second-tier cities including Pune and Ahmedabad attract packaging line investments seeking proximity to agricultural processing zones.
- Battery pouch film lamination:Electric vehicle cell manufacturing creates demand for aluminum-polypropylene laminates requiring electrolyte-resistant adhesive chemistries.
- China dual carbon policy alignment:GB standards on carbon intensity in manufacturing zones incentivize low-VOC adhesive procurement in state-backed tender processes.
Industry Challenges
- Formulation chemist scarcity:Expertise in reactive polyurethane kinetics and UV photoinitiator selection concentrates among aging technical workforces in Western Europe.
- Multi-jurisdiction compliance synchronization:Divergent food-contact notification requirements between FDA, EFSA, and China's NMPA extend product qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lamination Adhesive Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-Based, Water-Based, Hot Melt, Reactive End Use Industry: Packaging, Automotive, Electronics, Construction Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale Curing Method: UV Curing, Thermal Curing, Pressure Sensitivity, Ambient Cure |
| Companies Covered | Henkel, 3M, H.B. Fuller, Dow, Arkema, BASF, Sika, Ashland, Coim Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lamination Adhesive Market Evolving Landscape
Digital printing integration and shorter packaging run lengths are compressing adhesive set-speed requirements while expanding substrate variety. Converter equipment investments now prioritize rapid changeover capability over maximum line speed.
UV-curable acrylic oligomer systems are rendering obsolete thermal drying stages on narrow-web label laminators. Specialty label converters in North America and Western Europe adopt these chemistries to eliminate energy-intensive oven infrastructure. The technology is rendering obsolete capital allocation patterns that favored solvent-based gravure coating stations.
China's MEE enforcement of GB 37822-2019 on volatile organic compound emissions forces solvent-based adhesive users toward end-of-pipe abatement or formulation substitution. Manufacturing facilities in the Yangtze River Delta and Pearl River Delta face intensified inspection cycles. Food-contact flexible packaging operations respond by qualifying water-based alternatives despite bond performance trade-offs on high-barrier film structures.
Converter procurement patterns are fragmenting as brand owners unbundle adhesive supply from film supplier arrangements. Mid-sized packaging houses in India and Southeast Asia now source adhesives directly from formulators rather than accepting captive chemistries bundled with substrate purchases. This disintermediation is most visible in snack food and ready-meal packaging segments where formulation customization commands price premiums.
Lamination Adhesive Market Segmentation
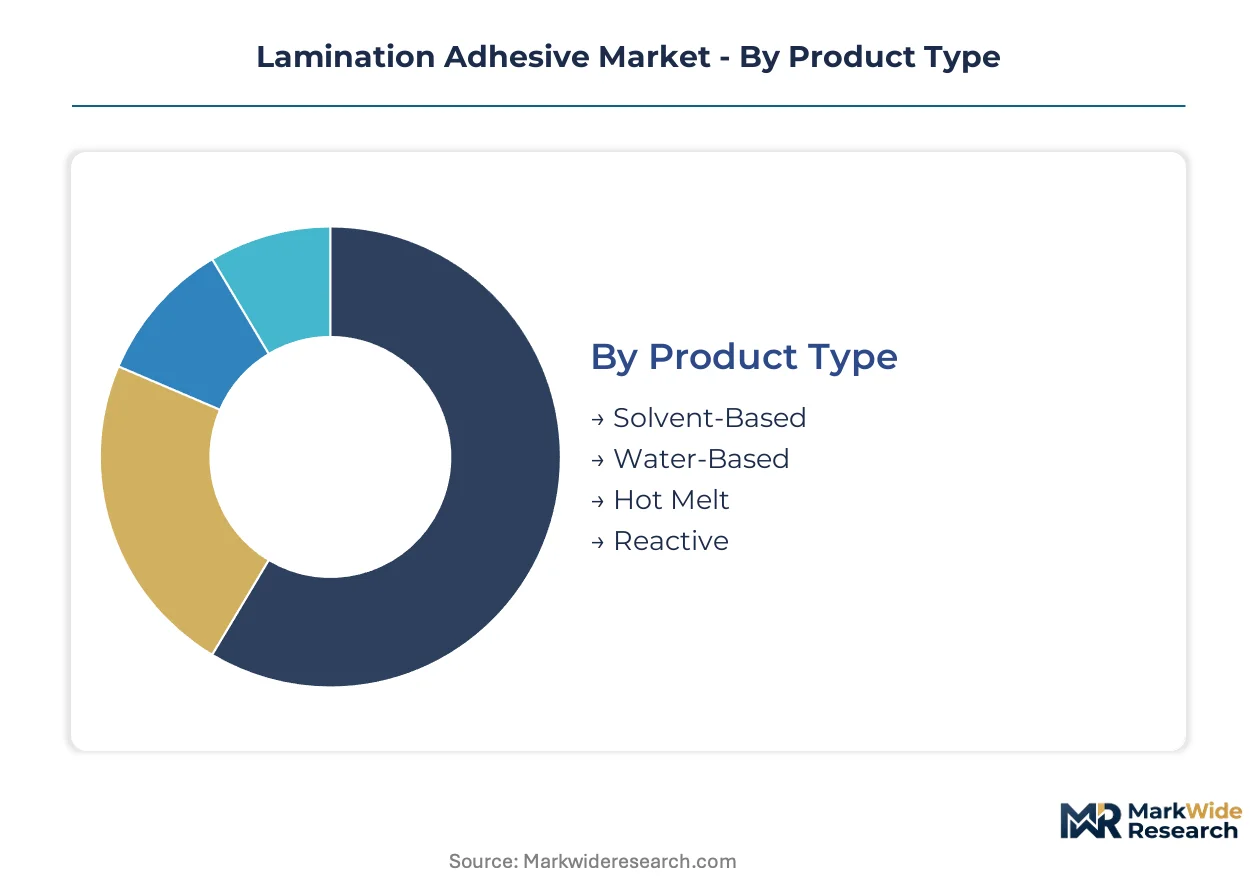
Lamination adhesive procurement patterns diverge sharply across chemistries and curing platforms. Each segment carries distinct capital requirements, regulatory exposure, and end-use concentration that reshapes supplier positioning.
Product Type:
Mature solvent systems coexist with emerging reactive platforms as converters navigate energy costs and VOC compliance.
- Solvent-Based:These aromatic polyurethane and acrylic formulations deliver aggressive wetting on low-surface-energy films and metallized substrates. Food-contact flexible packaging in India and Southeast Asia still sources these systems where thermal drying infrastructure is already sunk, though MEE inspections in China's Yangtze River Delta are forcing accelerated phase-outs.
- Water-Based:Acrylic and polyurethane dispersions eliminate residual solvent migration risks that trigger FDA and EFSA food-contact notifications. European converters under REACH isocyanate restrictions have standardized these for snack and ready-meal laminates, accepting the 200-250 meter per minute speed ceiling as a compliance trade-off.
- Hot Melt:EVA and metallocene polyolefin systems serve high-volume corrugated and label lamination where instant green strength enables rapid slitting.
- Reactive:Two-component polyurethane and UV-acrylic platforms bond aluminum-polypropylene battery pouch films for electric vehicle cells, commanding specification-driven procurement from cell manufacturers.
Water-based formulations handle the majority of throughput; reactive systems are expanding most quickly on share as automotive and electronics specifications proliferate.
End Use Industry:
Application intensity varies from commodity packaging volumes to precision electronics specifications.
- Packaging:Flexible food and beverage laminates consume the bulk of adhesive volume, with India PLI-linked converter buildouts in Pune and Ahmedabad pulling localized supply chain investments.
- Automotive:Interior trim lamination demands thermal cycling resistance from reactive polyurethane systems that maintain peel strength across dashboard temperature extremes.
- Electronics:Battery pouch films and display stack bonding require electrolyte-resistant chemistries that resist hydrofluoric acid attack in lithium-ion cell environments.
- Construction:Insulation panel and decorative surface lamination operates on cost-optimized hot melt and water-based platforms where bond aesthetics outweigh extreme performance.
Packaging absorbs the dominant volume share; electronics applications are gaining share fastest as cell manufacturing scales.
Distribution Channel:
Channel selection tracks customer scale and formulation customization requirements.
- Direct Sales:Integrated packaging houses and automotive Tier 1s negotiate annual contracts with formulators for tailored reactive systems, securing locked polyol pricing and technical service embedding.
- Distributors:Regional chemical distributors stock standard water-based and hot melt grades for mid-sized converters in India's second-tier packaging clusters, offering just-in-time replenishment.
- Online Retail:Narrow-web label converters and small job shops source UV-curable acrylics through specialty chemical platforms with documented batch certifications.
- Wholesale:Construction panel manufacturers purchase commodity EVA hot melts through building materials wholesalers on volume-indexed pricing.
Direct sales channels carry the highest value concentration; online retail is climbing the fastest as digital procurement penetrates specialty segments.
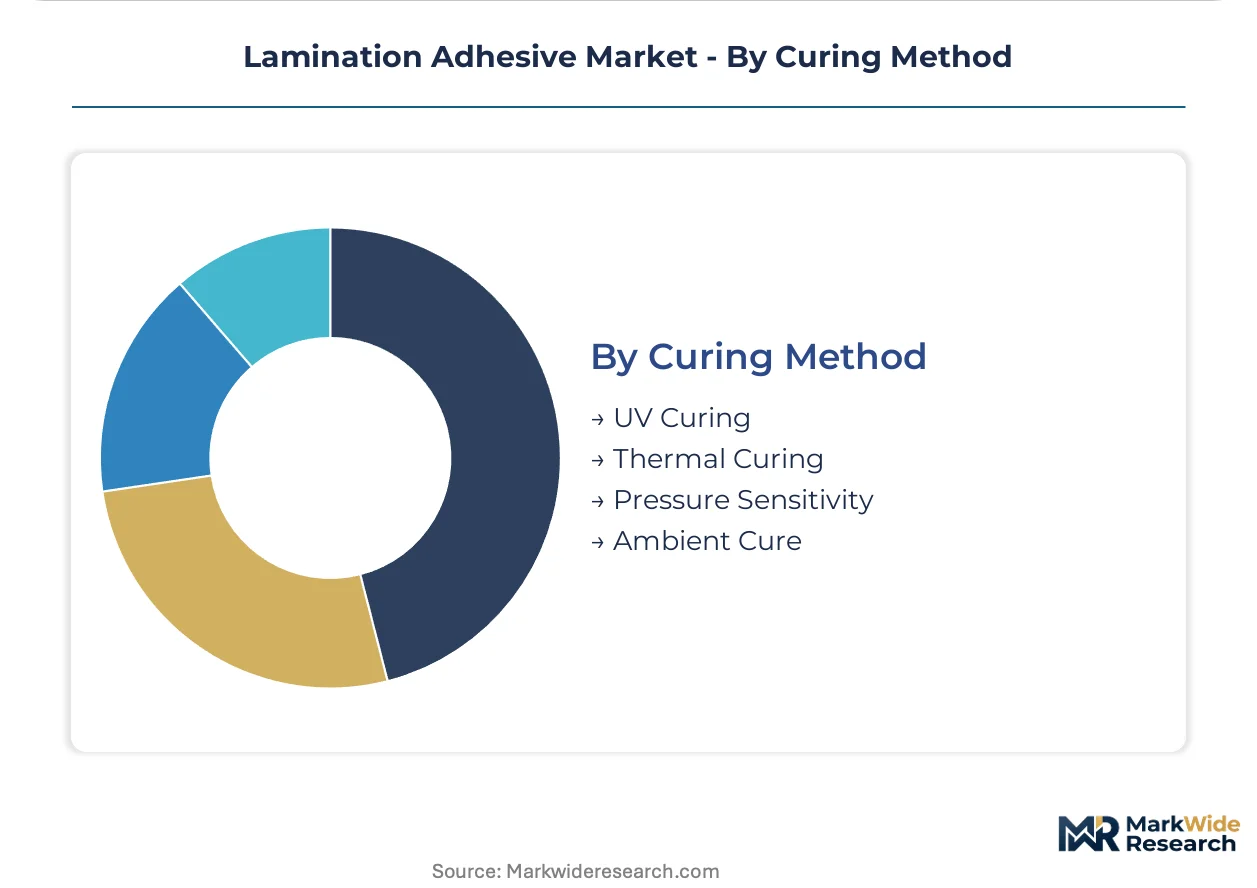
Curing Method:
Energy input requirements separate high-speed packaging from precision electronics workflows.
- UV Curing:Photoinitiator-triggered acrylic oligomers eliminate thermal drying entirely, enabling 400+ meter per minute speeds on narrow-web label equipment in North American and Western European converter bases.
- Thermal Curing:Convection and infrared ovens drive water-based and solvent-based film lamination, representing the installed base majority in emerging market packaging corridors.
- Pressure Sensitivity:Self-wound adhesive tapes and protective films deploy these systems for repositionable bonding in electronics assembly and automotive masking.
- Ambient Cure:Moisture-curing polyurethane and cyanoacrylate systems serve field repair and construction applications where oven infrastructure is unavailable.
Thermal curing retains the largest installed base; UV curing is expanding most rapidly as energy costs and speed requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flexible packaging converters in India and China are scaling procurement of solvent-free systems, while European and North American buyers prioritize REACH-compliant and FDA-notified formulations for food-contact applications.
United States
Food and beverage brand owners in the Midwest and Southeast are consolidating adhesive procurement under direct mill relationships. EPA enforcement of 40 CFR Part 63 VOC limits is accelerating water-based system adoption across Ohio and Wisconsin packaging corridors. Chicago-area converter clusters now specify reactive polyurethane platforms for high-speed snack food laminates.
Germany
Automotive interior trim manufacturers in Bavaria and Baden-Württemberg specify thermal-cycling-resistant reactive systems. ECHA restrictions on aromatic isocyanates under REACH are forcing reformulation investments among flexible packaging converters in the Rhine-Ruhr industrial zone. Stuttgart-based laminators now qualify UV-curable acrylics for narrow-web label applications.
China
Battery pouch film manufacturers in the Yangtze River Delta and Pearl River Delta are pulling electrolyte-resistant adhesive procurement. MEE enforcement of GB 37822-2019 VOC standards is eliminating solvent-based systems from food-contact operations in Shanghai and Suzhou. Shenzhen converter clusters are retrofitting lamination lines for 400+ meter per minute reactive polyurethane bonding.
India
Domestic packaging lines under PLI-linked incentives in Maharashtra and Gujarat are scaling capacity for agricultural processing proximity. FSSAI food-contact notifications are standardizing adhesive qualification protocols for snack and ready-meal exporters. Pune and Ahmedabad converter buildouts are localizing supply chain relationships with formulators.
Japan
Display stack and electronics laminators in the Kanto and Kansai regions specify moisture-cure polyurethane systems for precision bonding. METI carbon intensity guidelines are incentivizing low-VOC procurement in state-backed manufacturing zones. Osaka-area battery material suppliers are qualifying aluminum-polypropylene laminate adhesives for regional cell manufacturers.
Lamination Adhesive Market Competitive Landscape
Channel-controlling players compete with product-specialist players across formulation tiers and curing platforms. The market structures around three concentration levels: integrated chemical majors with captive resin production, mid-tier regional formulators serving converter clusters, and specialty technology licensors. Strategic moves center on backward integration into polyol supply and geographic expansion into India PLI-linked packaging corridors.
Among European-integrated chemical majors, Henkel and BASF occupy positions anchoring flexible food packaging and industrial film segments respectively. Dow exemplifies the polyurethane chemistry breadth archetype, spanning packaging laminates through automotive interior applications. These three represent distinct competitive postures: formulation leadership, raw material integration, and technology platform diversification.
| Leading Market Players |
|---|
| Henkel |
| 3M |
| H.B. Fuller |
| Dow |
| Arkema |
| BASF |
| Sika |
| Ashland |
| Coim Group |
| Others |
Value Network & Pricing Analysis
Captive polyol production in Germany and the United States concentrates margin capture upstream, forcing mid-tier formulators to accept volatile spot-market pricing for polyester and polyether feedstocks while integrated majors lock in contract spreads.
Pricing Analysis
Cost-plus contracts with crude-indexed polyol pricing dominate procurement between integrated suppliers and automotive Tier 1s. Three-tier pricing structure across premium, standard, and economy levels separates specification-grade reactive systems from commodity water-based grades. Cost compression in mid-tier solvent-free formulations is intensifying because converters retrofit lines faster than supply capacity expands. Small job shops and narrow-web label converters exhibit highest price sensitivity; battery cell manufacturers show least sensitivity due to specification lock-in.
Supply Chain Analysis
Toll manufacturing capacity for water-based acrylic dispersions clusters with German and U.S. chemical processors, while reactive polyurethane blending concentrates in China and India. The supply chain draws from aromatic isocyanates, specialty polyesters, and photoinitiator packages. Single-source vulnerability runs through isocyanate feedstocks where three integrated majors control European supply. Distribution runs through direct mill relationships for automotive and electronics specifications, with regional distributors serving mid-sized packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solvent-free lamination technology is disrupting procurement patterns as REACH isocyanate restrictions and China's GB 37822-2019 enforcement simultaneously eliminate legacy formulation options.
For Market Incumbents: Build formulation moats around electrolyte-resistant chemistries for battery pouch films before cell manufacturers finalize qualified supplier lists. Deepen backward integration into captive polyol supply to insulate margin from crude-linked volatility. Secure annual volume commitments from India PLI-linked converter buildouts in Pune and Ahmedabad to anchor regional share. For New Entrants and Emerging Players: Build out technical service capabilities for water-based system qualification among mid-sized Indian snack food converters currently disintermediating from film supplier bundles. Target second-tier cities in Maharashtra and Gujarat where localized supply relationships remain unconsolidated. Lead with rapid formulation customization and FSSAI notification support rather than price competition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European mid-tier formulators holding REACH-compliant portfolios but lacking India market access. Five-to-ten-year viability hinges on geographic diversification into PLI-linked packaging corridors and reactive system capabilities for automotive and electronics specifications. Monitor MEE enforcement intensity in Yangtze River Delta manufacturing zones as signal for solvent-based asset strandedness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Supply | Henkel and BASF lock in margin stability against crude-linked feedstock volatility. |
| India PLI-Linked Capacity Expansion | Localized production in Pune and Ahmedabad captures converter procurement localization. |
| REACH-Compliant Formulation Portfolio | ECHA isocyanate restrictions disqualify solvent-based competitors from European food-contact tenders. |
| Battery Pouch Film Qualification | Electrolyte-resistant adhesives secure specification-driven procurement from cell manufacturers. |
| UV-Curable Platform Development | Acrylic oligomer systems eliminate thermal drying infrastructure for narrow-web label converters. |
Research Methodology
A spread of perspectives from adhesive formulators, flexible packaging procurement directors, automotive Tier 1 material engineers, and regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with plant managers at lamination facilities and technical R&D directors at integrated chemical majors. Secondary validation drew from ECHA substance registrations, EPA 40 CFR Part 63 enforcement records, China MEE GB standard publications, and customs trade data for polyol and isocyanate flows. Bottom-up volume estimates triangulated against top-down chemical consumption models.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation by chemistry type, curing platform, end-use industry, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to disclosed capacity additions and converter equipment investment cycles. Key inputs included PLI scheme disbursement schedules, battery cell manufacturing capacity buildouts, and MEE inspection intensity indices for Yangtze River Delta zones.
Stress conditions across crude price bands, isocyanate supply disruptions, and regulatory acceleration scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about converter line retrofit rates and qualification timeline compression. Quarterly review of ECHA restriction proposals, MEE enforcement bulletins, and India PLI beneficiary announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Laminating Adhesives Market
Adhesives & Sealants
Adhesive Resin Market
Adhesives & Sealants
Global Construction Silicone Sealants Market
Adhesives & Sealants
Middle-East and Africa Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Europe Contact Adhesives Market
Adhesives & Sealants
Global Contact Adhesives Market
Adhesives & Sealants
North America Electronics Adhesives Market
Adhesives & Sealants
Middle East and Africa Adhesives Market
Adhesives & Sealants
Global Electrically Conductive Adhesives Market
Adhesives & Sealants
Heat Resistant Sealant Market
Adhesives & Sealants
Hot Melt Adhesives Market
Adhesives & Sealants
Construction Adhesives and Sealants Chemical Market
Adhesives & Sealants
Southeast Asia Adhesives and Sealants Market
Adhesives & Sealants
Australia Sealants Market
Adhesives & Sealants
Polysulfide Sealants Market
Adhesives & Sealants
Global Solvent Pressure Sensitive Adhesives Market