
 Global Sizing Agents Market | 2026-2036
Global Sizing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sizing Agents Market Intelligence
The transition to bio-based and recyclable sizing formulations is bifurcating the market between commodity and specialty performance tiers. BASF SE leverages its extensive chemical portfolio to offer advanced synthetic polymer solutions for high-speed paper machines. Kemira Oyj specializes in pulp and paper chemistry, focusing on water-intensive applications and sustainable product development. Solenis LLC competes through its strong service model and application expertise in both paper and textile industries.
Sizing agents are chemical additives applied during the manufacturing of paper and textiles to reduce liquid absorption and enhance surface characteristics. These compounds, often starch-based or synthetic polymers like acrylic copolymers, function by filling pores between fibers to control penetration of inks, water, or other fluids. Starch-based products command a significant volume share due to their low cost and natural origin, especially in paper production. However, synthetic polymers represent the fastest-growing segment, driven by performance demands in specialty packaging and technical textiles.
Regulatory frameworks such as the EU's REACH and the US FDA's guidelines for food-contact substances heavily influence chemical selection and formulation. In China, national GB standards for paper and textile products dictate permissible chemical residues, impacting market access for imported agents. Suppliers must navigate these divergent regional compliance requirements while balancing the performance needs of end-users with the push for sustainable, bio-derived materials.
Market Dynamics
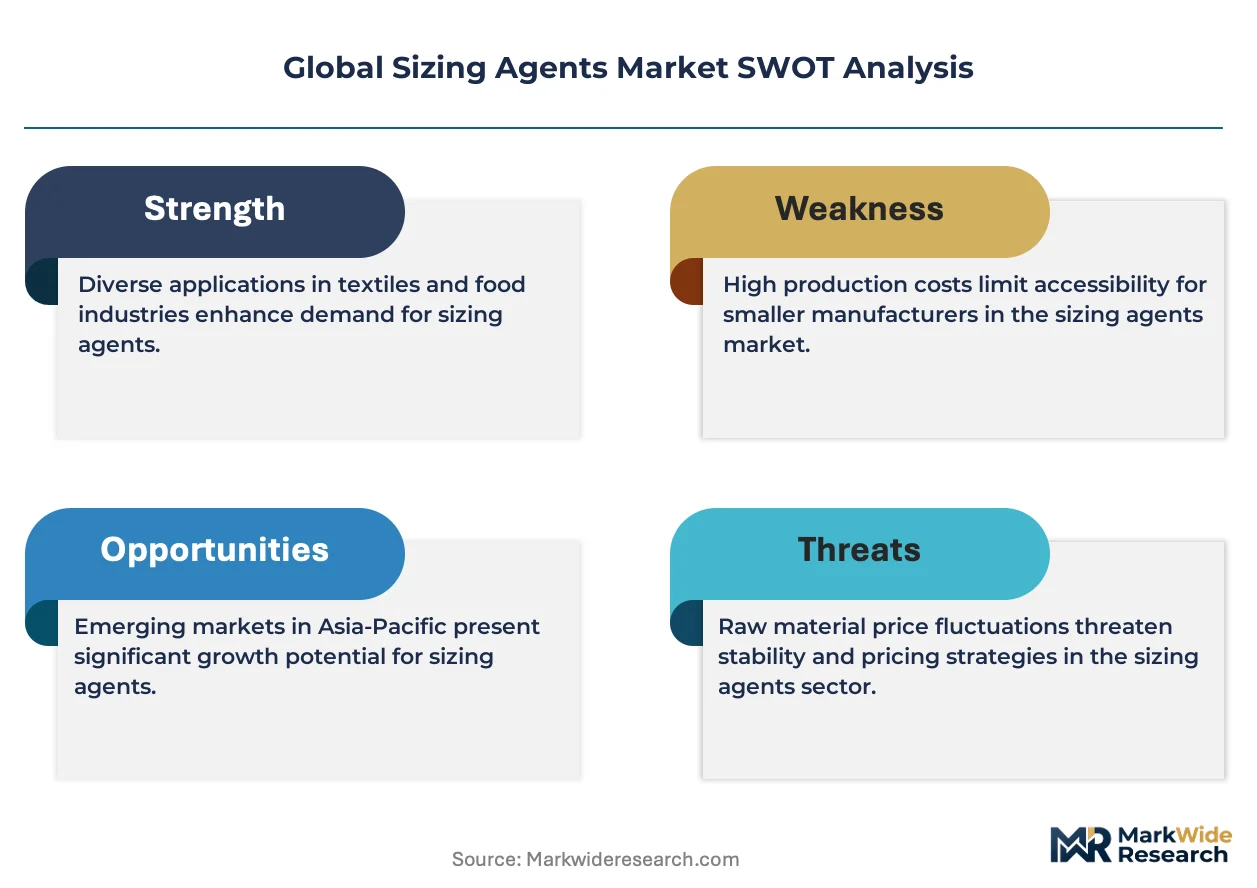
The primary structural force is the tension between sustainability mandates and performance requirements. This conflict compels chemical formulators to develop novel bio-based agents that can match the efficiency of synthetic polymers on high-speed paper and textile machinery.
Growth Catalysts
- E-commerce Packaging:Escalating demand for durable, water-resistant corrugated boxes and paper-based mailers for logistics requires higher volumes of performance sizing agents to ensure package integrity during transit.
- EU Green Deal:Policies promoting a circular economy and restricting single-use plastics are creating a direct pull for recyclable and compostable paper packaging, which depends on compatible, biodegradable sizing agents.
- Bio-Polymer Innovation:Advances in modified starches, cellulose derivatives, and other bio-polymers are enabling the development of cost-effective, sustainable alternatives that meet specific performance criteria in paper and textile applications.
Market Restraints
- Raw Material Volatility:The pricing and availability of key feedstocks, particularly natural starches like corn and tapioca, are subject to fluctuations in agricultural markets, impacting production costs and margin stability.
- Regulatory Compliance Costs:Adhering to stringent chemical safety and food-contact material regulations, such as the US FDA guidelines and the EU's REACH framework, requires significant investment in testing and documentation.
- Performance Deficits:Some bio-based sizing agents exhibit lower efficacy in high-humidity environments or on ultra-fast paper machines compared to established synthetic polymers, limiting their adoption in demanding applications.
Strategic Opportunities
- Fluorine-Free Formulations:Developing and marketing high-performance, fluorine-free sizing agents for food packaging and textiles presents a significant opportunity as regulations increasingly restrict PFAS chemicals.
- Technical Textiles:The expanding technical textiles sector in markets like India and Vietnam, for applications in automotive, construction, and medical fields, opens new avenues for specialized sizing formulations.
- Closed-Loop System Compatibility:Formulating sizing agents that are fully compatible with paper recycling processes, preventing contamination of recovered pulp, offers a competitive advantage with environmentally focused paper mills.
Industry Challenges
- Formulation Harmonization:Suppliers face the challenge of developing products that comply with a patchwork of divergent regional regulations, such as China's GB standards and Europe's REACH, complicating global product rollouts.
- Application Expertise Gap:The shift to novel bio-based chemistries requires significant training and on-site technical support for end-users to optimize machine runnability and achieve desired end-product quality, straining supplier resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sizing Agents Market |
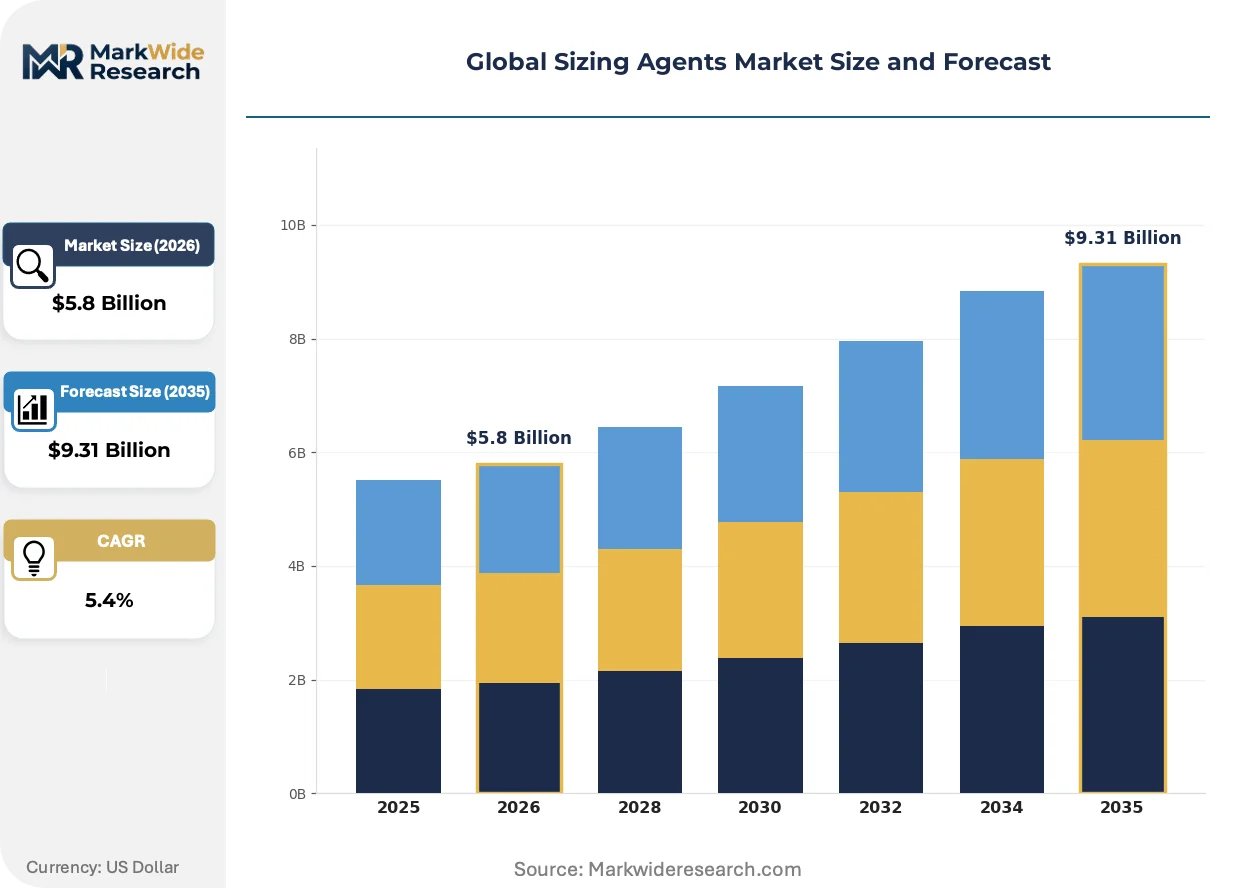
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.31 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starch-Based, Synthetic Polymers, Acrylic Copolymers, Polyvinyl Alcohol, Epoxy Resins Application: Textile Manufacturing, Paper Coating, Packaging Industry, Adhesive Formulation, Surface Treatment End User Industry: Textile Mills, Paper Producers, Packaging Manufacturers, Adhesive Suppliers, Coating Plants Formulation Type: Liquid, Powder, Emulsion, Solution, Dispersion |
| Companies Covered | BASF SE, Kemira Oyj, Solenis LLC, Evonik Industries, Buckman Laboratories, Seiko PMC Corporation, Aries Chemical, Dow Inc., Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sizing Agents Market Strategic Shifts & Innovations
The market is defined by a technological race to bridge the performance gap between low-cost natural starches and high-functionality synthetic polymers. This pursuit is creating distinct innovation pathways for commodity paper grades versus specialty technical materials.
Enzymatic starch conversion is a key process innovation allowing paper mills to modify native starch on-site. This technology gives mills precise control over viscosity and molecular weight to match specific paper grade requirements. On-site conversion is supplanting the reliance on third-party suppliers for pre-modified, higher-cost starches, shifting value to enzyme providers and equipment manufacturers.
European Union regulations, particularly REACH restrictions on per- and polyfluoroalkyl substances (PFAS), are forcing a complete reformulation of water- and grease-resistant sizing agents. This regulatory pressure directly impacts the specialty paper and food packaging sectors. Producers must now invest heavily in developing and validating alternative fluorine-free chemistries to maintain market access in the EU.
Consolidated purchasing by large, multinational paper and packaging conglomerates is altering supplier relationships. These buyers are moving away from simple transactional orders toward service-based contracts that bundle chemical supply with on-site technical support and performance guarantees. This shift is most prominent in China's competitive paper industry, where operational efficiency is paramount.
Global Sizing Agents Market Segmentation
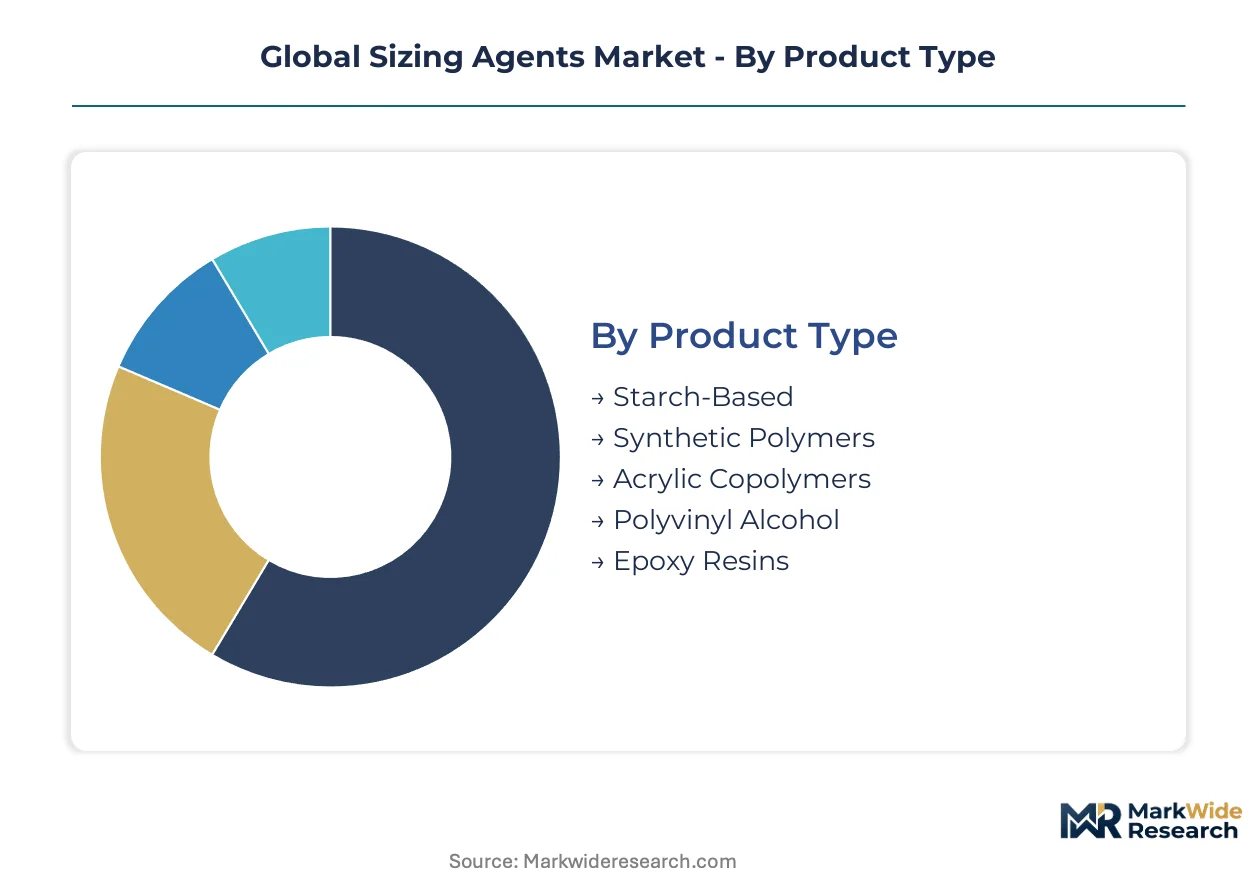
The sizing agents market is highly diversified, reflecting varied performance requirements across numerous industrial applications. Understanding these distinct segments is essential for chemical manufacturers to align product development with specific end-user demands and evolving regulatory landscapes. Segmentation highlights areas of technological innovation and market concentration.
Product Type:
The product type segment faces distinct substitution pressures, particularly for traditional formulations challenged by sustainability mandates and performance expectations. Bio-based alternatives are displacing older chemistries in many applications.
- Starch-Based:These agents derive from natural starches like corn or tapioca, offering cost-effectiveness and biodegradability. Demand concentrates in the paper production sector, particularly for commodity grades, driven by their natural origin and low cost.
- Synthetic Polymers:This category includes a broad range of petroleum-derived polymers providing superior water resistance and film-forming properties. Performance demands in specialty packaging and technical textiles are driving their expansion, especially in applications requiring high durability.
- Acrylic Copolymers:Acrylic copolymers deliver excellent binding and water barrier properties, finding use in high-performance paper and board.
- Polyvinyl Alcohol:Polyvinyl alcohol is known for its strong film-forming capabilities and adhesion, often used in textile sizing and paper coatings.
- Epoxy Resins:Epoxy resins provide high strength and chemical resistance, primarily utilized in specialized industrial coatings and composites.
Starch-Based products anchor the volume base while Synthetic Polymers represent the fastest-growing segment.
Application:
Each application area presents unique performance specifications for sizing agents, influencing formulation complexity and cost structures. End-use requirements dictate the chemical properties needed for effective sizing.
- Paper Coating:Sizing agents in paper coating enhance surface smoothness, printability, and liquid resistance for graphic papers and packaging. Demand intensifies from the global packaging industry requiring improved print fidelity and moisture barrier properties.
- Packaging Industry:Sizing agents are critical for producing durable, water-resistant paperboard and corrugated materials used in e-commerce and food packaging. Escalating demand for protective packaging in logistics drives the need for high-performance sizing.
- Textile Manufacturing:Sizing agents improve yarn strength and reduce breakage during weaving, enhancing fabric production efficiency.
- Adhesive Formulation:These agents modify rheology and improve adhesion properties in various adhesive products.
- Surface Treatment:Sizing agents are applied to various surfaces to alter their wettability and protective characteristics.
The Packaging Industry drives significant demand for sizing agents, with Paper Coating applications expanding most quickly due to specialized performance needs.
End User Industry:
The end-user industries exhibit varied purchasing patterns and regulatory compliance needs, directly impacting supplier engagement models. Large multinational conglomerates often seek bundled solutions, integrating chemical supply with technical support.
- Textile Mills:Textile mills utilize sizing agents to prepare yarns for weaving, minimizing friction and improving process efficiency. The expanding technical textiles sector in countries like India and Vietnam creates new demand for specialized formulations.
- Paper Producers:Paper producers consume large volumes of sizing agents to control liquid absorption and enhance paper strength. The transition to high-speed paper machines compels demand for efficient, high-performance synthetic polymers.
- Packaging Manufacturers:Packaging manufacturers require sizing agents for producing durable, moisture-resistant containers and flexible packaging materials. E-commerce growth drives demand for sustainable and protective packaging solutions.
- Adhesive Suppliers:Adhesive suppliers incorporate sizing agents to optimize the performance and stability of their adhesive products.
- Coating Plants:Coating plants use sizing agents to modify surface properties and improve the durability of coated materials.
Paper Producers account for the largest consumption volume, while Packaging Manufacturers demonstrate the steepest expansion trajectory driven by e-commerce requirements.
Formulation Type:
Formulation types reflect different delivery mechanisms and processing advantages, influencing ease of application and storage stability. Innovations in bio-based materials are leading to new formulation developments.
- Liquid:Liquid formulations offer ease of handling and direct application in industrial processes, requiring less preparation. These formulations are widely adopted across paper and textile manufacturing for continuous processes.
- Powder:Powder formulations provide extended shelf life and reduced shipping costs due to their concentrated nature. They require dissolution or dispersion before use in production lines.
- Emulsion:Emulsions are stable dispersions of immiscible liquids, commonly used for synthetic polymer-based sizing agents. These formulations deliver consistent performance in water-intensive applications.
- Solution:Solutions are homogenous mixtures, offering clarity and specific chemical properties for precise application.
- Dispersion:Dispersions involve solid particles suspended in a liquid medium, providing specific functional benefits for surface modification.
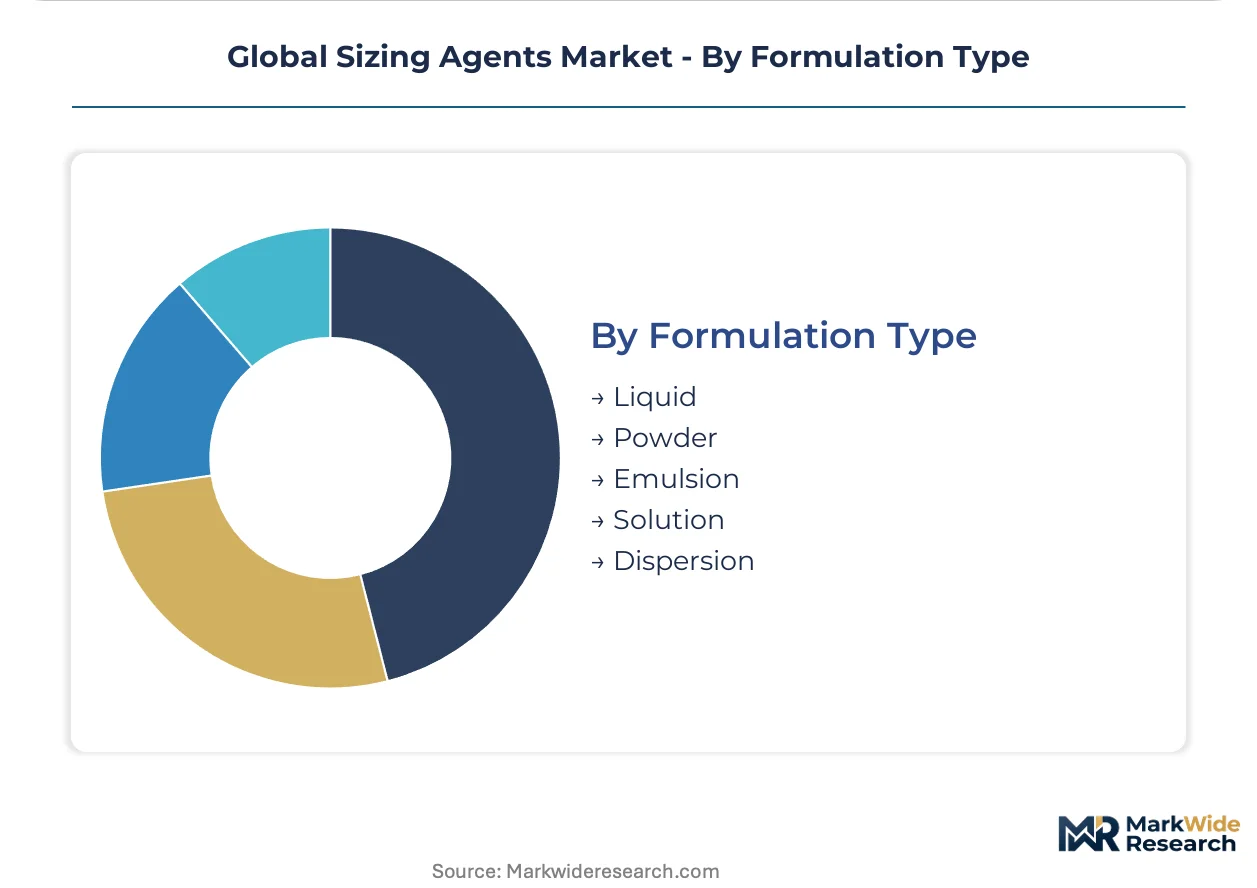
Liquid formulations maintain a significant market presence for their ease of use, with Emulsion formulations climbing the fastest due to their prevalence in advanced synthetic chemistries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply-side concentration for sizing agents increasingly centers on regions with robust paper and textile manufacturing. China's expansive production sectors drive significant demand for these chemical additives. This dynamic shapes global distribution and innovation pathways for both commodity and specialty formulations.
China
Demand for sizing agents in China is propelled by its vast paper and textile industries, especially for packaging and technical textiles. National GB standards for paper and textile products dictate permissible chemical residues, influencing market access for suppliers. Major industrial hubs like the Yangtze River Delta concentrate paper mills and textile factories, requiring high volumes of diverse sizing agents.
United States
The escalating demand for durable e-commerce packaging and specialty papers boosts sizing agent consumption in the United States. The US FDA's guidelines for food-contact substances influence chemical selection, particularly for packaging materials. Production facilities in the Southeast, a traditional paper and pulp region, focus on developing high-performance, sustainable formulations.
Germany
Germany's advanced manufacturing sector, including specialty paper and technical textiles, drives demand for high-performance sizing agents. The EU's REACH regulations mandate the transition to non-fluorinated and biodegradable sizing agents, impacting product development. Chemical clusters in the Rhine-Ruhr region are actively innovating bio-based alternatives compatible with stringent environmental standards.
India
Expanding technical textiles and growing paper packaging sectors fuel the need for sizing agents across India. The country's Bureau of Indian Standards (BIS) promotes quality and safety, influencing chemical sourcing for domestic manufacturers. Textile hubs in Gujarat and Maharashtra are increasing their adoption of specialized sizing formulations for diverse applications.
Global Sizing Agents Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the sizing agents market. The competitive landscape is bifurcated between large chemical conglomerates offering advanced synthetic solutions and specialized firms focusing on bio-based alternatives. Strategic archetypes include diversified chemical giants, pulp and paper chemistry specialists, and application-focused service providers. Companies pursue portfolio diversification and strategic partnerships to strengthen their market positions.
Specialists in pulp and paper chemistry, such as Kemira Oyj, focus on water-intensive applications and sustainable product development. BASF SE, a diversified chemical company, represents the archetype of large chemical portfolio holders, offering advanced synthetic polymer solutions. Solenis LLC, a global LLC, occupies a position emphasizing a strong service model and application expertise across paper and textile industries. These companies exemplify the strategic differentiation within the sizing agents market.
| Leading Market Players |
|---|
| BASF SE |
| Kemira Oyj |
| Solenis LLC |
| Evonik Industries |
| Buckman Laboratories |
| Seiko PMC Corporation |
| Aries Chemical |
| Dow Inc. |
| Huntsman Corporation |
| Others |
Cost & Logistics Intelligence
Days-of-inventory for specialty sizing agents reflects the complex supply chain for performance chemicals. This metric directly influences pricing power for advanced formulations, especially when raw material availability fluctuates.
Pricing Analysis
EU REACH regulations dictate the pricing tier structure for non-fluorinated sizing agents, creating a premium for compliant bio-based alternatives. Contract-based long-term offtake is common for large paper producers. Quality grade and after-sales technical support drive price differentiation. Pricing softness affects commodity starch-based products due to raw material volatility. Packaging manufacturers are less price-sensitive for high-performance solutions, while textile mills prioritize cost-effectiveness for basic applications.
Supply Chain Analysis
China and the United States anchor the production of diverse sizing agents, from commodity starches to synthetic polymers. The industry sources key inputs like corn and tapioca starch, alongside petroleum derivatives for synthetic formulations. Commodity price volatility for agricultural feedstocks presents a significant structural risk. Distribution typically runs through specialized chemical distributors or direct sales channels for large industrial end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sizing agents market presents a defensive-moat story, primarily due to regulatory entrenchment around product safety and performance standards. This creates high barriers to entry for new formulations and ensures sustained demand for compliant materials.
For Market Incumbents:Consolidate market share through strategic acquisitions of specialty bio-polymer innovators, securing intellectual property in sustainable chemistries. Invest heavily in R&D for fluorine-free formulations to address evolving EU regulations. Expand technical support capabilities in emerging markets like India to optimize application for local textile and paper producers. The shift towards non-fluorinated alternatives threatens legacy synthetic polymer portfolios, necessitating certification investment in new sustainable products.
For New Entrants and Emerging Players:Application expertise gaps exist among end-users transitioning to novel bio-based chemistries, creating an entry point for specialized service providers. Target small-to-mid sized paper mills in Southeast Asia seeking cost-effective, compliant starch modification solutions. The technical textiles sector in Vietnam offers significant white space for specialized, high-performance formulations. Offer bundled solutions combining bio-based products with on-site technical training and performance guarantees.
For Investors and Strategic Acquirers:Long-term, this sits as a specialty chemicals growth play because of the non-discretionary nature of sizing agents in paper and textile production. The market offers stable returns driven by continuous innovation in sustainable and high-performance materials over the next decade. Target vertically integrated mid-cap specialists with patented bio-polymer technologies and strong regional distribution networks. The accelerating adoption rate of enzyme-modified starches in major paper-producing regions indicates a key inflection point.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reduces environmental footprint and aligns with EU Green Deal policies for paper and packaging producers. |
| Long-term Supply Agreement | Secures consistent feedstock supply for starch-based sizing agents, mitigating raw material volatility risks. |
| Joint Venture | Accelerates development of novel bio-based formulations by combining chemical expertise with application knowledge. |
| Capacity Expansion | Meets escalating demand for performance sizing agents from the e-commerce packaging industry in China. |
| Product Launch | Introduces new fluorine-free sizing agents to capture market share in regulated food-contact packaging applications. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary validation. Primary research involved discussions with plant managers, procurement leads at packaging manufacturers, and R&D directors in chemical companies. This was triangulated with customs trade data, chemical industry reports, and regulatory filings from the US FDA and EU REACH. A bottom-up and top-down triangulation approach ensured data consistency and market sizing accuracy.
The forecast window spans nine years, employing a robust analytical framework to model market dynamics. Segmentation dimensions included product type, application, end-user industry, formulation type, and regional production hubs. Compound annual growth rates were derived from historical trends, projected demand drivers, and technological innovation rates. Key forecast inputs included e-commerce packaging growth rates and bio-polymer innovation indices.
Underlying assumptions cover stable geopolitical conditions and sustained industrial growth, with deviation risk concentrated in raw material volatility and evolving regulatory mandates. Forecasts reflect these assumptions, though unforeseen disruptions could alter market trajectories. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Butylated Hydroxytoluene Market
Additives
Global UV Stabilizers Market
Additives
Emulsifiers In Personal Care Market
Additives
North America Potassium Nitrate Market
Additives
Global Isosorbide Market
Additives
Liquid Thickeners Market
Additives
Polyoxyethylene Sorbitan Monostearate Market
Additives
Sodium Caprylate Market
Additives
Ultraviolet Light Stabilizer Market
Additives
Apocarotenal Market
Additives
Drilling Fluid Additives Market
Additives
Organic Dispersants Market
Additives
Global Low-Profile Additive Market
Additives
China Sodium Reduction Ingredient Market
Additives
Gasoline Additives Market
Additives
Asia-Pacific Feed Acidifiers Market