
 Autonomous Agricultural Machinery Market | 2026-2036
Autonomous Agricultural Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Agricultural Machinery Market Insights
Dealer and OEM direct-sales channels is fragmenting as subscription-based fleet management platforms and precision-agriculture service bundles displace traditional equipment financing. Deere & Company leverages its proprietary Operations Center software to lock in recurring revenue from autonomous tractor deployments. CNH Industrial anchors its competitive stance through Raven Industries integration, controlling guidance and autonomy stack development in-house. AGCO Corporation differentiates via FendtONE platform openness, allowing third-party developers to build on its robotic architecture.
Autonomous agricultural machinery encompasses self-propelled equipment capable of executing field operations without human operator intervention, integrating differential GPS guidance with sub-inch accuracy, LiDAR obstacle detection, and machine-learning-based implement control for tillage, planting, and chemical application. Crop Production applications currently dominate installed base value, while Pest Control via autonomous drone sprayers represents the fastest-expanding margin pool as aerial platforms reduce chemical volume and labor exposure. Robotics technology, particularly autonomous navigation stacks and computer vision for weed identification, sits at the center of R&D investment intensity across manufacturers.
The EPA governs autonomous sprayer chemical application rates and drift mitigation, while the FAA regulates unmanned aerial system flight corridors and beyond-visual-line-of-sight waivers for agricultural drones; together these agencies determine market access timelines and product certification costs for equipment entrants. ISO 12100 machinery safety standards and pending EU Machinery Regulation revisions on autonomous operation mode classification will shape export compliance burdens for North American manufacturers. Stakeholders must monitor regulatory harmonization progress between FAA beyond-visual-line-of-sight rulemaking and EASA equivalent frameworks to anticipate which autonomy tier achieves cross-border certification first.
Market Dynamics
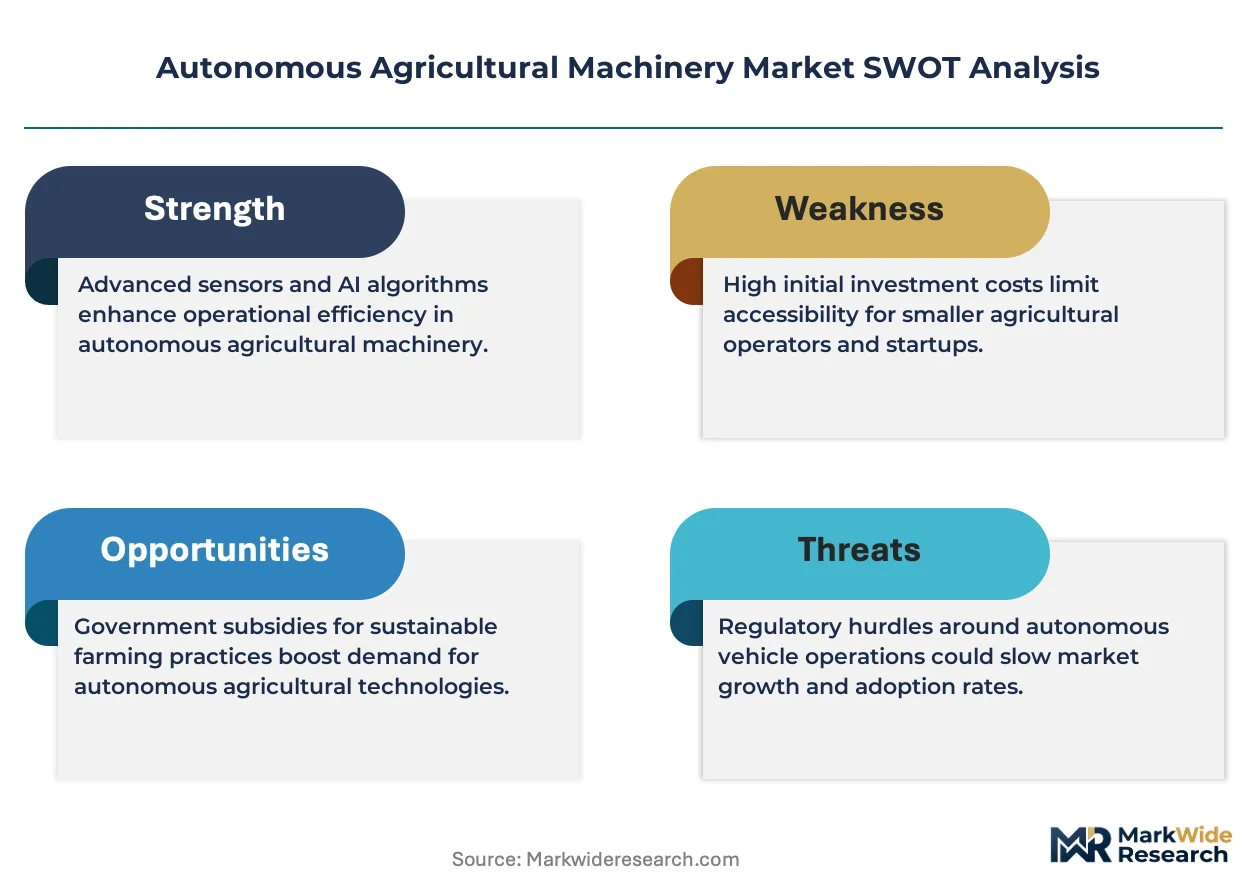
Subscription-based fleet management platforms are displacing traditional equipment financing across dealer and OEM direct-sales channels, locking buyers into recurring revenue relationships rather than asset ownership.
Growth Catalysts
- Labor scarcity in row-crop operations:Permanent farmworker shortages across the US Corn Belt and Canadian Prairie provinces accelerate deployment of driverless tractors for tillage and planting windows.
- FAA beyond-visual-line-of-sight waivers:Expanded flight corridor approvals for agricultural drones enable autonomous aerial spraying at scale, reducing chemical volume and operator exposure.
- Machine-learning weed identification:Computer vision systems trained on region-specific weed libraries cut herbicide application rates while preserving yield targets.
Market Restraints
- LiDAR sensor cost concentration:Supply of high-resolution obstacle detection hardware clusters among Asian component manufacturers, creating input price volatility.
- EPA-FAA joint certification friction:Dual-agency governance of unmanned aerial spraying platforms extends product approval timelines and compliance expenditures.
- Manual equipment substitution:Used conventional tractors retain residual value in smallholder operations, delaying autonomous upgrade cycles.
Strategic Opportunities
- Autonomous pest control services:Aerial drone sprayers represent the fastest-expanding margin pool as chemical application shifts from ground rigs to precision aerial platforms.
- EU Machinery Regulation alignment:Pending autonomous operation mode classification standards create first-mover advantage for manufacturers achieving cross-border certification.
- Third-party developer ecosystems:Open robotic architectures enable precision-agriculture service bundles built by independent software vendors on OEM platforms.
Industry Challenges
- Guidance stack integration complexity:Sub-inch differential GPS accuracy demands specialized calibration expertise scarce among dealer service technicians.
- ISO 12100 safety certification timelines:Machinery safety standard compliance for autonomous mode operation requires extended validation cycles before market release.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Agricultural Machinery Market |
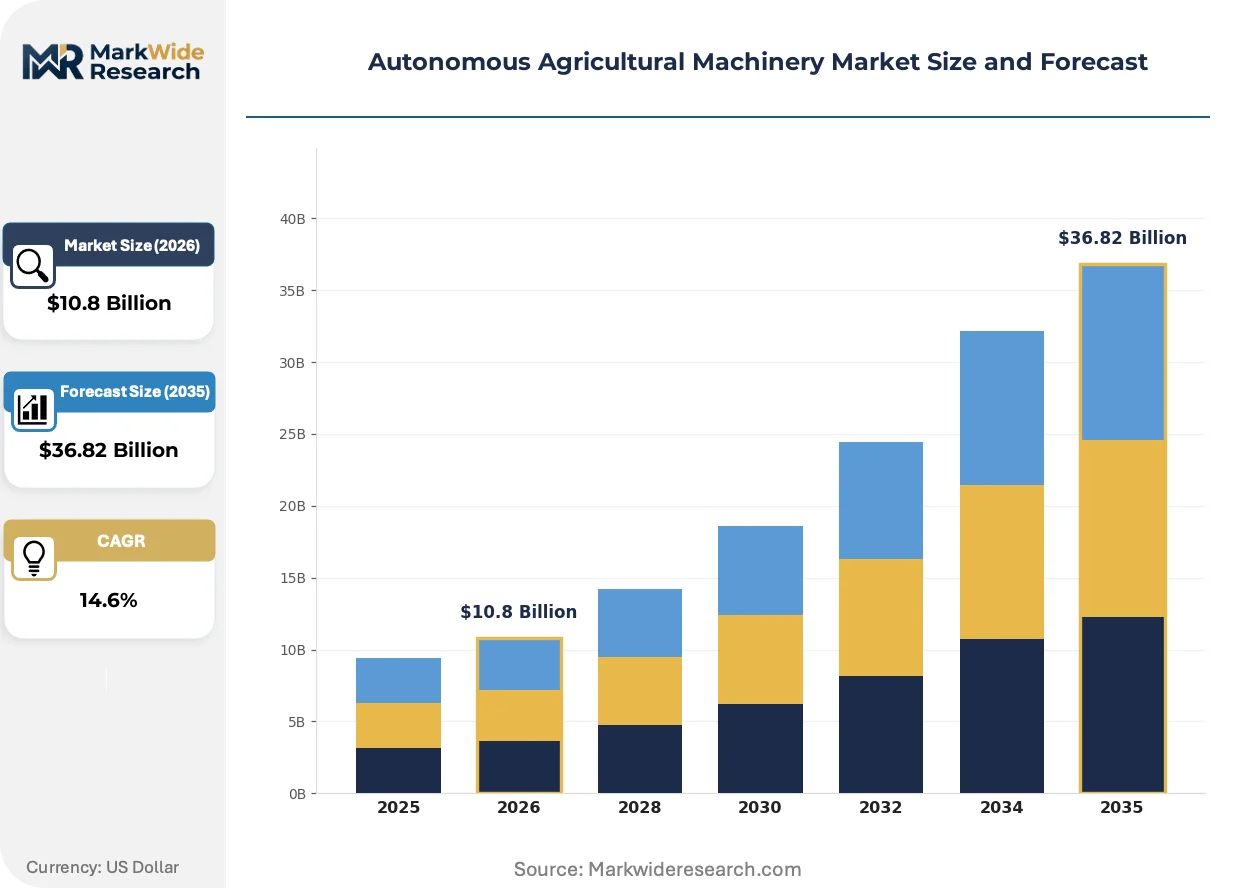
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $36.82 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Harvesters, Seeders, Sprayers Technology: GPS, Robotics, AI, IoT End User: Farmers, Agribusinesses, Cooperatives, Contractors Application: Crop Production, Soil Preparation, Pest Control, Irrigation |
| Companies Covered | Deere & Company, CNH Industrial, AGCO Corporation, Kubota Corporation, Mahindra and Mahindra Ltd., Yanmar Co. Ltd., DJI, Monarch Tractor, CLAAS KGaA mbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Agricultural Machinery Market Trends and Innovations
Autonomous navigation stacks and computer vision systems are compressing the technical barrier between precision guidance and full unmanned operation across multiple equipment categories.
Swarm robotics for coordinated field operation is collapsing the economic threshold for multi-machine deployment. Large-scale grain operations in North Dakota and Saskatchewan now run synchronized driverless tractor fleets for planting and cultivation. This compression enables 24-hour field windows without operator fatigue constraints, fundamentally altering equipment utilization economics.
REACH chemical authorization frameworks in Europe are tightening drift mitigation requirements for autonomous sprayers. Equipment manufacturers must demonstrate reduced off-target deposition through nozzle technology and flight-path optimization. Aerial application platforms face the steepest compliance burden, with EASA equivalent frameworks lagging FAA rulemaking by approximately 18-24 months.
Service contract structures now bundle hardware access with per-acre performance guarantees rather than capital purchase. Dealer networks in Iowa and Illinois pilot usage-based pricing for autonomous tillage fleets, transferring operational risk from farm balance sheets to equipment providers. This restructuring accelerates adoption among credit-constrained mid-scale operators who previously deferred technology investment.
Autonomous Agricultural Machinery Market Segmentation
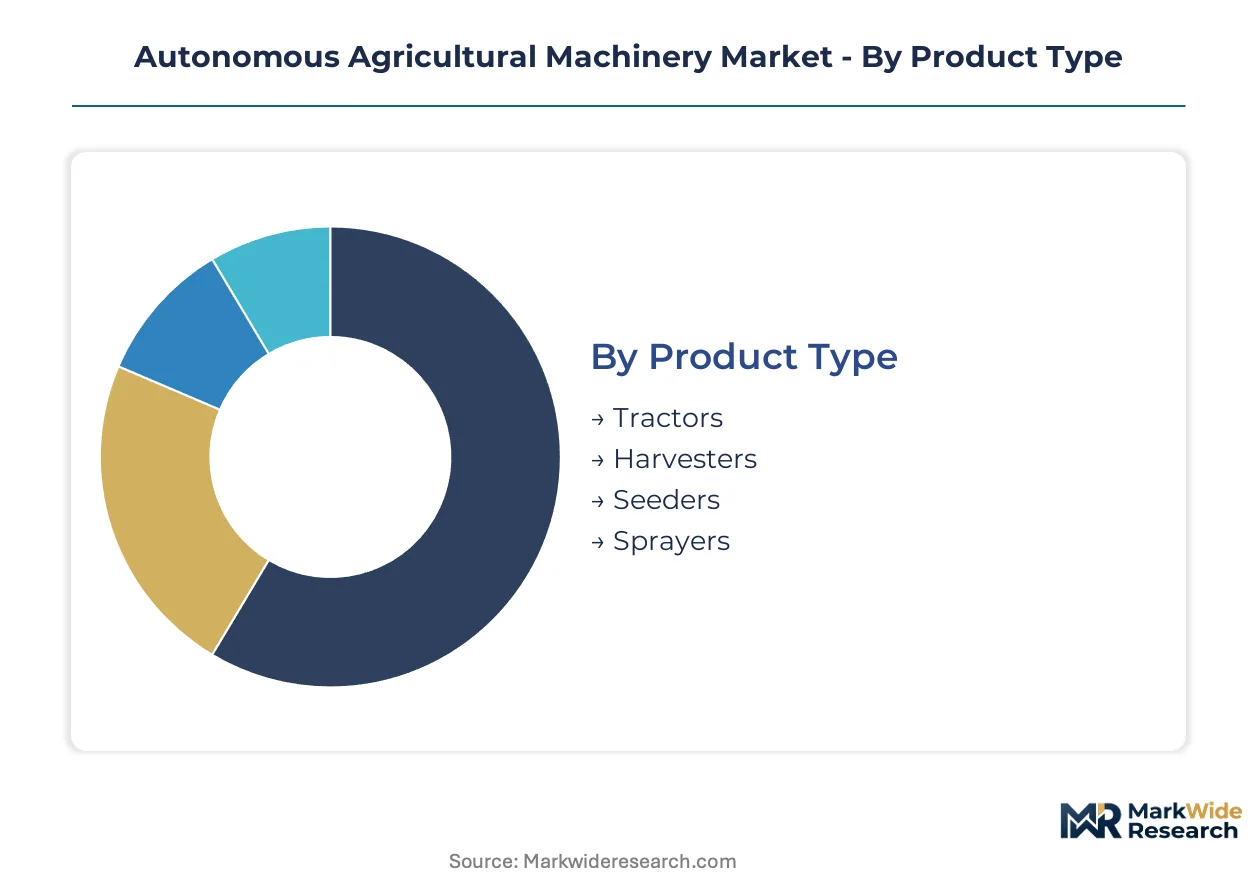
Segmentation in autonomous agricultural machinery reveals how technology maturity, buyer sophistication, and operational intensity shape procurement patterns. Equipment categories span from fully autonomous platforms to semi-autonomous retrofits, while end-user economics determine whether ownership or service models dominate adoption pathways.
Product Type:
Mature autonomous platforms anchor installed base value, while emerging categories reshape fleet economics through specialized functionality.
- Tractors:Self-propelled platforms integrate differential GPS guidance with sub-inch accuracy and LiDAR obstacle detection for unmanned tillage and planting operations. Demand concentrates in North Dakota and Saskatchewan grain operations where 24-hour field windows justify capital deployment against permanent farmworker shortages.
- Harvesters:Combines with autonomous navigation stacks execute grain and forage collection without operator intervention, utilizing machine-learning-based crop flow optimization. Iowa and Illinois large-scale operations drive procurement as labor scarcity peaks during narrow harvest windows.
- Seeders:Precision planting equipment with robotic row guidance enables variable-rate seeding across irregular field geometries.
- Sprayers:Ground rigs and aerial platforms apply chemicals through computer vision-guided nozzle control, reducing drift and volume.
Tractors handle the majority of throughput; sprayers are the fastest mover on share.
Technology:
Cost tier stratification separates foundational positioning systems from premium intelligence layers that command service-based pricing.
- GPS:Differential and RTK-GPS systems provide centimeter-level positional accuracy for field boundary mapping and implement tracking. US Corn Belt operations standardize on this foundation, though calibration expertise scarcity among dealer technicians constrains deployment velocity.
- Robotics:Autonomous navigation stacks and actuator control systems enable unmanned operation mode classification under ISO 12100 safety standards. Canadian Prairie provinces accelerate adoption as Raven Industries and Deere advance proprietary stack integration.
- AI:Computer vision trained on region-specific weed libraries enables targeted herbicide application.
- IoT:Fleet telemetry and remote diagnostics platforms support subscription-based service contracts.
GPS underpins most installed systems; robotics is expanding most quickly as full autonomy displaces precision guidance.
End User:
Customer type determines whether capital purchase or performance-based service contracts dominate transaction structures.
- Farmers:Owner-operators in the 500-2,000 acre range represent the core demand pool for autonomous tillage and planting equipment. Credit-constrained mid-scale operators in Illinois increasingly prefer usage-based pricing that transfers operational risk to equipment providers.
- Agribusinesses:Large integrated operations with internal agronomy teams deploy synchronized autonomous fleets across multi-state footprints. North Dakota corporate farms drive swarm robotics adoption for coordinated cultivation windows.
- Cooperatives:Member-owned purchasing entities aggregate demand for shared autonomous equipment pools.
- Contractors:Custom applicators and tillage service providers build autonomous capacity for per-acre revenue models.
Agribusinesses command the largest fleet deployments; contractors are gaining share fastest as service models proliferate.
Application:
Application intensity varies by operational criticality, with pest control representing the steepest margin expansion opportunity.
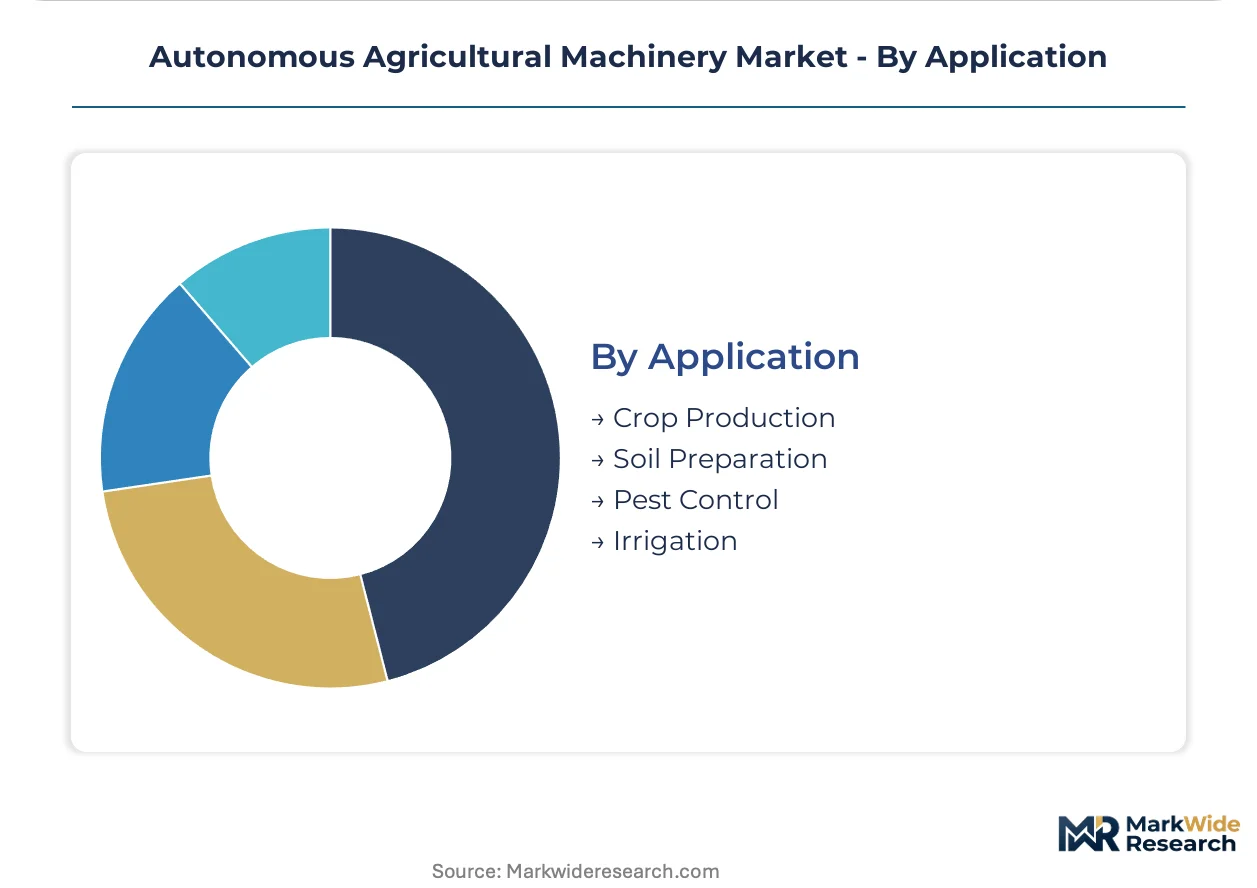
- Crop Production:Autonomous planting, cultivation, and harvest operations constitute the dominant value segment by installed base. US Corn Belt grain operations prioritize driverless tractors for narrow planting windows constrained by weather volatility.
- Pest Control:Aerial drone sprayers with beyond-visual-line-of-sight FAA waivers enable precision chemical application with reduced volume and operator exposure. This segment climbs the fastest as EPA-FAA joint certification pathways mature for unmanned aerial platforms.
- Soil Preparation:Autonomous tillage and residue management equipment prepares seedbeds with minimal compaction.
- Irrigation:Robotic pivot and drip system management optimizes water application through soil sensor integration.
Crop Production handles the majority of throughput; Pest Control is the fastest mover on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in North American grain operations while European compliance costs compress margins. US Corn Belt buyers capture scale economies through coordinated fleet deployment. German and French manufacturers absorb certification burdens from diverging EU-US regulatory frameworks.
United States
Driverless tractor procurement accelerates across Iowa and Illinois as permanent farmworker shortages narrow planting windows. The FAA governs beyond-visual-line-of-sight waivers for agricultural drones, with EPA joint certification extending approval timelines. North Dakota corporate farms deploy synchronized autonomous fleets for 24-hour cultivation cycles.
Canada
Saskatchewan and Manitoba grain operations scale autonomous harvester fleets to address seasonal labor gaps. Health Canada and PMRA coordinate chemical application standards for unmanned aerial platforms. Prairie province dealerships pilot usage-based pricing models for tillage equipment.
Germany
Precision agriculture software development clusters around Munich and Stuttgart engineering centers. The EU Machinery Regulation revision on autonomous operation mode classification drives compliance investment. Bavarian equipment manufacturers align ISO 12100 safety standards with pending Brussels directives.
China
Domestic LiDAR sensor production scales to reduce import dependency for obstacle detection hardware. MIIT and SAMR coordinate GB standards for agricultural robot safety classification. Yangtze River Delta integrators assemble cost-competitive navigation stacks for regional equipment OEMs.
Brazil
São Paulo and Mato Grosso soybean operations test autonomous sprayers for chemical volume reduction. ANVISA governs agrochemical application rates for unmanned platforms under converging federal standards. Campinas research clusters adapt computer vision systems for tropical weed identification libraries.
Autonomous Agricultural Machinery Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying navigation stacks and sensor modules. Market structure consolidates around agricultural equipment incumbents with software capabilities, while autonomy startups fragment across specialized applications. Two strategic archetypes dominate: vertically integrated OEMs controlling full technology stacks, and modular platform providers enabling third-party developer ecosystems. Competitive moves center on proprietary software lock-in and open-architecture partnership networks.
Within the integrated OEM tier, Deere & Company and CNH Industrial occupy positions defined by captive control over guidance and autonomy development. AGCO Corporation exemplifies the open-platform archetype through developer ecosystem cultivation. DJI anchors the aerial application segment with unmanned platform specialization. These three represent contrasting strategic postures on hardware-software integration depth.
| Leading Market Players |
|---|
| Deere & Company |
| CNH Industrial |
| AGCO Corporation |
| Kubota Corporation |
| Mahindra and Mahindra Ltd. |
| Yanmar Co. Ltd. |
| DJI |
| Monarch Tractor |
| CLAAS KGaA mbH |
| Others |
Pricing and Supply Chain Analysis
Tariff exposure on LiDAR sensor imports from Asian component manufacturers compresses margins across both premium autonomous tractor tiers and entry-level retrofit kits, forcing OEMs to widen pricing spreads between configured-to-order systems and standard configurations while reshuffling supplier geography toward domestic qualification programs.
Pricing Analysis
Configured-to-order pricing for autonomous tractors with sub-inch RTK-GPS and integrated LiDAR obstacle detection commands substantial premiums over standard precision-guidance configurations. Three-tier pricing structure across premium, standard, and economy levels separates full autonomy stacks from assisted-steering retrofits and basic GPS guidance. Price differentiation hinges on ISO 12100 safety certification tier and after-sales service bundling through subscription fleet management platforms. Cost compression in the economy tier is intensifying because used conventional tractors retain residual value among credit-constrained mid-scale operators. Agribusinesses with synchronized fleet deployments show least price sensitivity; smallholder cooperatives in the 500-2,000 acre range exhibit highest elasticity.
Supply Chain Analysis
Extended payment terms from LiDAR manufacturers in China, South Korea, and Japan strain working capital for North American equipment assemblers navigating component qualification cycles. Supply chains for high-resolution obstacle detection hardware draw from concentrated Asian sensor foundries, with robotic actuator systems sourcing from German and Japanese precision engineering clusters. Single-source vulnerability around RTK-GPS correction service providers creates chokepoint exposure for sub-inch accuracy claims. Distribution runs through dealer networks piloting usage-based pricing models in Iowa and Illinois, with OEM direct channels capturing large agribusiness accounts in North Dakota and Saskatchewan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle recovery as permanent farmworker shortages across the US Corn Belt and Canadian Prairie provinces force accelerated capital deployment against narrowing planting windows.
For Market Incumbents: Entrench proprietary software lock-in through Operations Center-style fleet management platforms that transfer operational risk from farm balance sheets to equipment providers. Deepen backward integration into autonomous navigation stack development to offset Raven Industries-style captive control by competitors. Defend against modular platform threats by restricting API openness for critical guidance functions while cultivating selective third-party partnerships in non-core applications. For New Entrants and Emerging Players: Pursue aerial pest control services as the fastest-expanding margin pool, where EPA-FAA joint certification friction delays incumbent drone platform deployment and creates regulatory arbitrage windows. Target custom applicator contractors building autonomous capacity for per-acre revenue models in Illinois and Manitoba. Anchor go-to-market positioning on chemical volume reduction guarantees validated through computer vision-guided nozzle control. For Investors and Strategic Acquirers: The market sits at an infrastructure-buildout phase that favors vertical stack integrators with proprietary guidance and autonomy development capabilities. Long-term viability over the next decade hinges on regulatory harmonization progress between FAA beyond-visual-line-of-sight frameworks and EASA equivalents. Monitor swarm robotics deployment velocity across North Dakota corporate farms as the inflection signal for multi-machine coordination economics achieving scale.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Fleet Management Platform Launch | Locks recurring revenue from Deere-style Operations Center deployments across Corn Belt agribusinesses. |
| Autonomous Navigation Stack Acquisition | Secures Raven Industries-style captive control over guidance and autonomy development in-house. |
| Third-Party Developer Ecosystem Cultivation | Enables FendtONE-style openness for precision-agriculture service bundles on robotic architecture. |
| EPA-FAA Joint Certification Fast-Track | Accelerates beyond-visual-line-of-sight waiver timelines for aerial drone sprayer market access. |
| Usage-Based Pricing Pilot Expansion | Transfers operational risk to equipment providers among credit-constrained Illinois mid-scale operators. |
Research Methodology
Operator-level perspectives from farm equipment procurement managers, precision agriculture service directors, dealer network principals, and autonomous systems integration engineers anchored the qualitative base for this study. Primary interview data combined with secondary validation from SEC equipment manufacturer filings, FAA beyond-visual-line-of-sight waiver databases, EPA agricultural chemical application records, and ISO machinery safety standard documentation. Bottom-up equipment shipment analysis triangulated against top-down agricultural capital expenditure surveys across the US Corn Belt and Canadian Prairie provinces.
Scenario-bracketing around regulatory approval velocity, labor scarcity severity, and LiDAR cost compression shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include equipment autonomy tier, technology stack configuration, end-user scale archetype, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and subscription service adoption curves incorporated machine-learning weed identification deployment rates and swarm robotics fleet coordination economics as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories, agricultural commodity price volatility, or trade policy on Asian sensor imports would shift the trajectory. Forecasts reflect documented assumptions on FAA rulemaking timelines and EPA drift mitigation standard evolution. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Turkey Agricultural Tractor Market
Agricultural Machinery
Garden and Orchard Tractors Market
Agricultural Machinery
Spain Agricultural Machinery Market
Agricultural Machinery
Hydrogen Powered Tractor Market
Agricultural Machinery
Agriculture Drones Market
Agricultural Machinery
Agricultural Haying and Forage Machinery Market
Agricultural Machinery
Agriculture Sprayers Market
Agricultural Machinery
Garden Tractor Market
Agricultural Machinery
US Agriculture Drone Market
Agricultural Machinery
North America Agricultural Tractors Market
Agricultural Machinery
Germany Agricultural Machinery Market
Agricultural Machinery
Agricultural Electric Tractor Market
Agricultural Machinery
Autonomous Farm Equipment Market
Agricultural Machinery
Compact Tractor Market
Agricultural Machinery
United States Agricultural Machinery Market
Agricultural Machinery
Agriculture and Farm Machinery Market