
 Shoulder Strap Insulated Cooler Market | 2026-2036
Shoulder Strap Insulated Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
Shoulder Strap Insulated Cooler Market Analytics
ISO 9001 quality management certification is bifurcating the competitive landscape into qualified manufacturers and commodity assemblers. Yeti Coolers leverages vertical integration to control foam-injection quality and thermal performance consistency. Pelican Products anchors its position through MIL-SPEC durability standards originally developed for protective cases. Igloo Products competes on manufacturing scale, operating one of the largest rotational-molding facilities in the cooler category.
A shoulder strap insulated cooler is a portable thermal retention vessel combining closed-cell foam insulation with a fabric or polymer shell, designed to maintain sub-ambient temperatures for perishable goods during transit. Soft-sided variants typically employ laminated TPU-coated nylon with welded seams to prevent thermal bridging and moisture ingress. Soft-sided coolers lead volume due to lighter carry weights and packability for day hikers, while backpack-style units represent the fastest-growing configuration as multi-day trekkers prioritize hands-free mobility. Hard-sided segments retain premium margin pools where rotomolded polyethylene construction commands durability premiums from fishing and hunting buyers.
EPA guidelines on hydrofluorocarbon propellants constrain domestic foam-blowing processes, pushing manufacturers toward pentane or water-based alternatives. REACH compliance in Europe restricts certain phthalate plasticizers in PVC liner materials, redirecting sourcing toward TPU or EVA formulations. California's Proposition 65 labeling requirements add compliance costs for brands distributing through West Coast retail channels. Stakeholders must monitor evolving state-level chemical disclosure rules and insulation performance testing protocols to avoid distribution disruptions.
Market Dynamics
The EU F-Gas Regulation is forcing manufacturers to abandon hydrofluorocarbon-based foam blowing agents, triggering a wholesale reformulation of insulation cores across European production lines while creating compliance gaps for importers.
Growth Catalysts
- REACH-compliant TPU formulations:European liner material mandates are redirecting sourcing from phthalate-laden PVC toward thermoplastic polyurethane, opening premium positioning for certified suppliers.
- Backcountry hunting segment:Multi-day wilderness expeditions in Montana and Idaho are driving demand for rotomolded shoulder-strap units with MIL-SPEC durability ratings.
- California Proposition 65:Chemical disclosure requirements for West Coast distribution channels are filtering out non-compliant brands, consolidating shelf space for certified manufacturers.
Market Restraints
- Pentane supply volatility:The transition from HFC to pentane-based foam blowing has concentrated input sourcing with petrochemical refiners in Texas and Louisiana, exposing margins to energy price swings.
- Rotational molding capacity:Domestic production of hard-sided units depends on a limited base of large-format molding equipment, creating bottlenecks during peak outdoor season.
- Welded seam durability:Soft-sided TPU-nylon laminates face performance ceilings in sub-zero conditions, constraining adoption among ice-fishing buyers in Minnesota and Wisconsin.
Strategic Opportunities
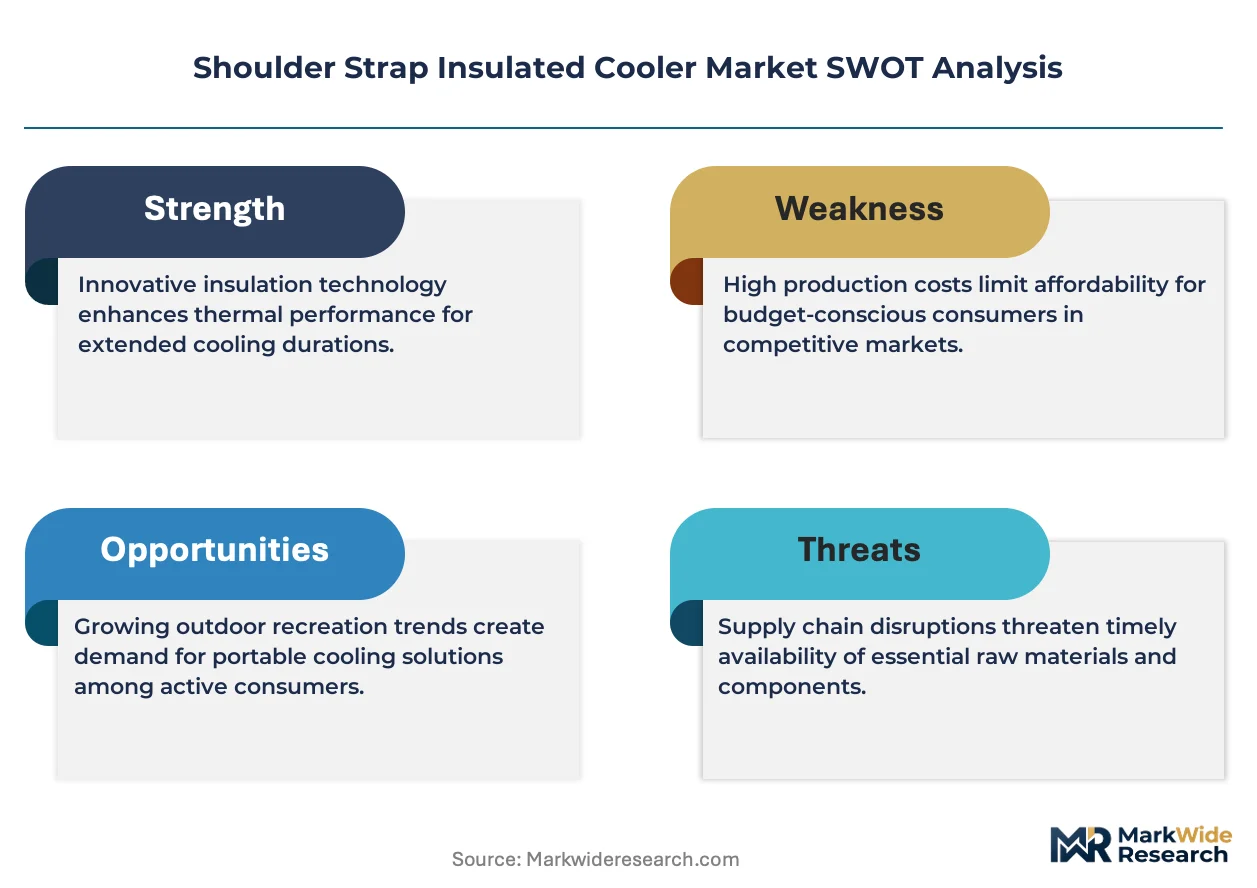
- ISO 9001 certification gap:The bifurcation between certified manufacturers and commodity assemblers creates acquisition targets for brands seeking quality-controlled supply.
- Backpack-style configuration:Hands-free mobility demands from Appalachian Trail through-hikers represent an underdeveloped product architecture relative to traditional tote formats.
- IRA clean manufacturing credits:Domestic producers investing in water-based foam alternatives can access federal incentives while positioning against imported competition.
Industry Challenges
- Thermal performance testing protocols:The absence of standardized ASTM methods for shoulder-strap cooler retention curves forces brands to fund proprietary validation, raising R&D overhead.
- Cross-border compliance layering:Simultaneous EPA, REACH, and state-level chemical rules require dedicated regulatory staff, disproportionately burdening mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shoulder Strap Insulated Cooler Market |
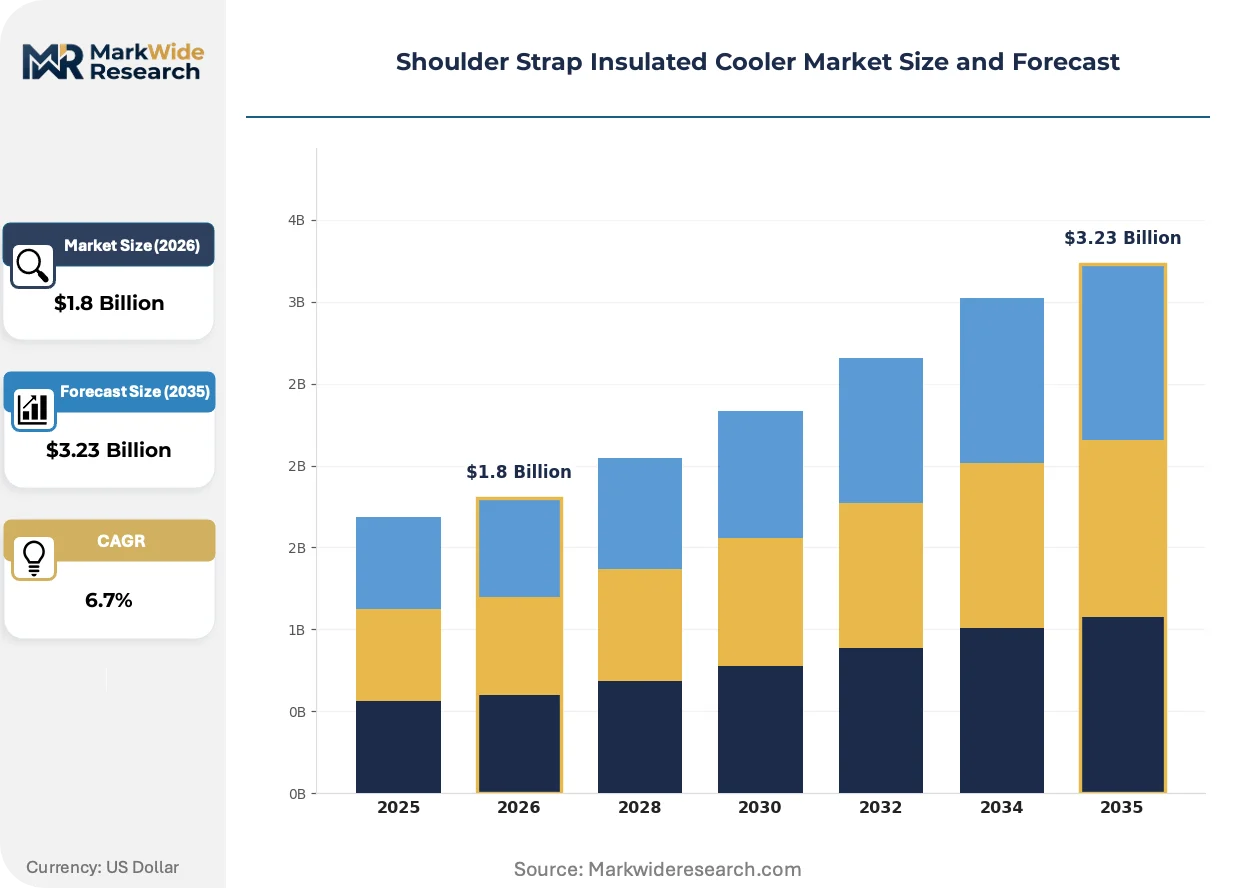
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft-sided, Hard-sided, Backpack-style, Wheeled Material: Polyester, Nylon, PVC, Rubber Size: Small, Medium, Large, Extra-large End User: Outdoor Enthusiasts, Picnic Goers, Beach Visitors, Campers |
| Companies Covered | Yeti Coolers, AO Coolers, Bison Coolers, Pelican Products, Grizzly Coolers, The Coleman Company, Igloo Products, Engel Coolers, RTIC Outdoors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shoulder Strap Insulated Cooler Market Evolving Landscape
Material science advances and regulatory chemistry constraints are converging to redefine insulation performance benchmarks, while distribution channels fragment between specialty retail and direct-to-consumer fulfillment.
Vacuum-insulated panel technology is displacing conventional closed-cell foam in premium shoulder-strap units. Alpine mountaineering outfitters in Colorado and Washington State are specifying VIP cores for high-altitude expeditions where thermal bridging compromises food safety. This displacement is compressing the performance advantage gap between soft-sided and hard-sided formats, forcing rotomolded producers to emphasize durability rather than insulation superiority.
The EPA's hydrofluorocarbon phase-down under SNAP regulations is eliminating remaining domestic production pathways for HFC-245fa blowing agents. Foam-injection facilities in Ohio and Tennessee are retooling for cyclopentane or water-blown systems, extending capital depreciation schedules and raising unit economics for mid-volume producers. Hard-sided manufacturers with captive molding operations are absorbing these costs faster than contract-dependent soft-sided assemblers.
Specialty outdoor retailers are ceding volume to brand-owned digital channels with configuration tools for strap geometry and colorway selection. REI and Bass Pro Shops are responding with exclusive color collaborations and in-store thermal testing demonstrations, but the shift is most pronounced among urban professionals in Austin and Denver who research insulation specifications online before purchasing. This channel migration is elevating the importance of standardized performance claims and third-party certification visibility on product detail pages.
Shoulder Strap Insulated Cooler Market Segmentation
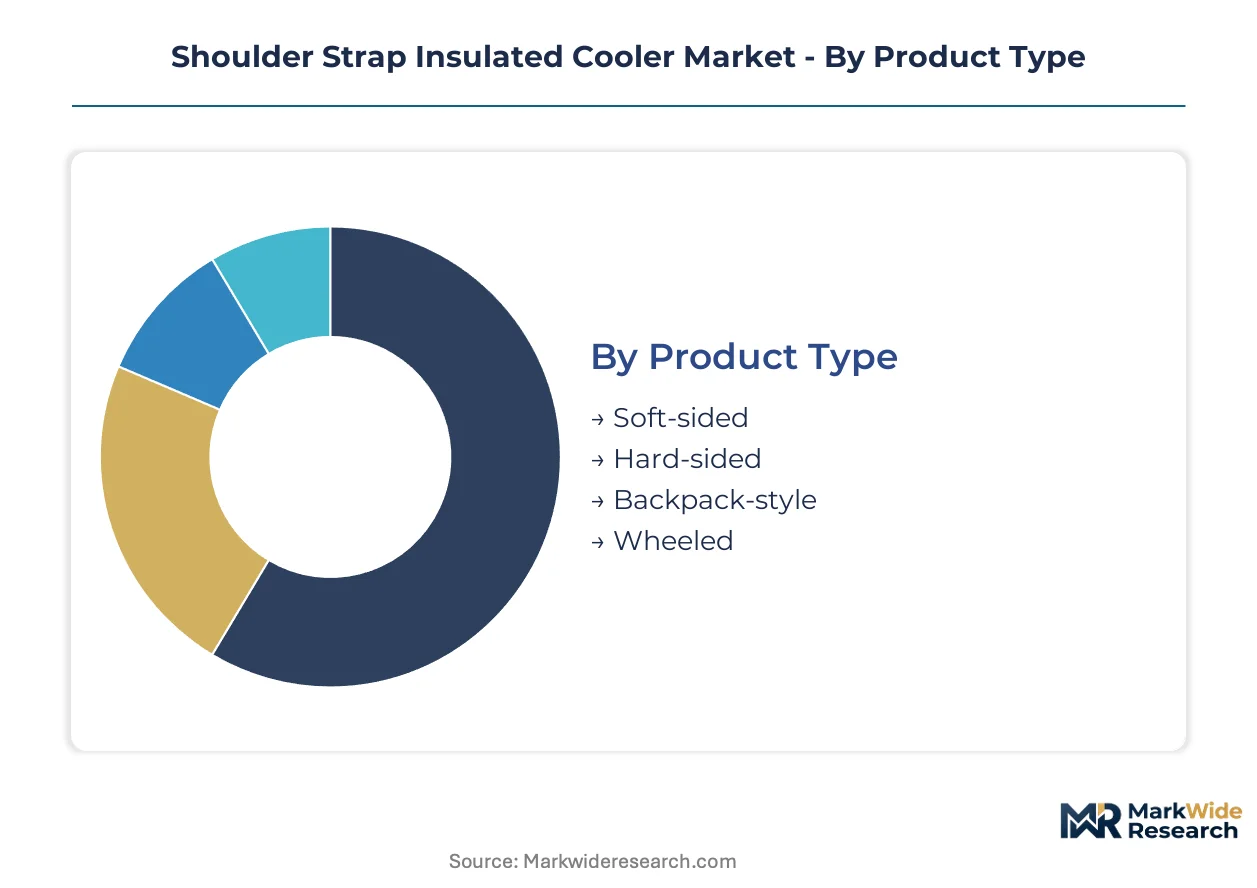
Segmentation in shoulder strap insulated coolers reveals distinct margin architectures across construction formats and user contexts. Product type and material choices drive the widest spreads between commodity assemblers and certified manufacturers.
Product Type:
Margin pools concentrate in hard-sided rotomolded units and the emerging backpack-style configuration, where technical barriers limit supplier entry.
- Soft-sided:Laminated TPU-coated nylon with welded seams prevents thermal bridging and moisture ingress. Day hikers in Germany and the Pacific Northwest favor these for lighter carry weights and packability, though sub-zero durability constraints limit ice-fishing adoption in Minnesota and Wisconsin.
- Backpack-style:Hands-free mobility architecture employing padded shoulder systems and load-distribution frames. Appalachian Trail through-hikers and multi-day trekkers in Colorado are driving the steepest expansion trajectory as manufacturers race to develop ergonomic frame geometries.
- Hard-sided:Rotomolded polyethylene construction commands durability premiums from fishing and hunting buyers. MIL-SPEC ratings anchor pricing power for protective-case heritage brands.
- Wheeled:Integrated chassis systems with telescoping handles for transport over paved surfaces. Beach visitors and picnic goers in coastal California and Florida favor these for parking-lot-to-site distances.
The dominant share belongs to Soft-sided, while Backpack-style is closing the gap fastest.
Material:
REACH compliance and EPA SNAP regulations are restructuring input sourcing economics, with TPU and advanced polyesters capturing premium positioning.
- Nylon:High-denier woven substrates with polyurethane coatings provide tear resistance and UV stability. European manufacturers are shifting toward REACH-compliant formulations as ECHA restrictions on phthalate plasticizers redirect sourcing from PVC.
- Polyester:Cost-effective solution-dyed fabrics with hydrophobic treatments. Volume production concentrates in Asian contract facilities serving mass-market retail channels.
- PVC:Legacy liner material facing regulatory pressure under REACH and California Proposition 65. Declining share as TPU displaces vinyl in premium European and West Coast distribution.
- Rubber:Molded TPE or natural rubber components for base abrasion resistance and grip surfaces. Specialized applications in marine and expedition-grade units.
Nylon holds the premium tier, though TPU-adjacent polyesters are gaining specification share in mid-market lines.
Size:
Capacity segmentation maps directly to trip duration and group composition, with medium and large formats capturing the core revenue base.
- Medium:20-35 liter capacity range optimized for day-trip provisions and single-user meal storage. This specification dominates REI and specialty retail velocity in Austin and Denver.
- Large:35-55 liter configurations serving overnight campers and small-group outings. Rotational molding capacity constraints in domestic facilities create seasonal bottlenecks for hard-sided variants.
- Small:Under 20 liter personal lunch carriers. Limited insulation performance requirements favor commodity manufacturing with minimal certification overhead.
- Extra-large:55+ liter expedition formats for backcountry hunting and multi-day river trips. Low volume but highest per-unit margins due to MIL-SPEC durability specifications.
Medium formats generate the highest absolute revenue, while Extra-large commands the widest margin spreads.
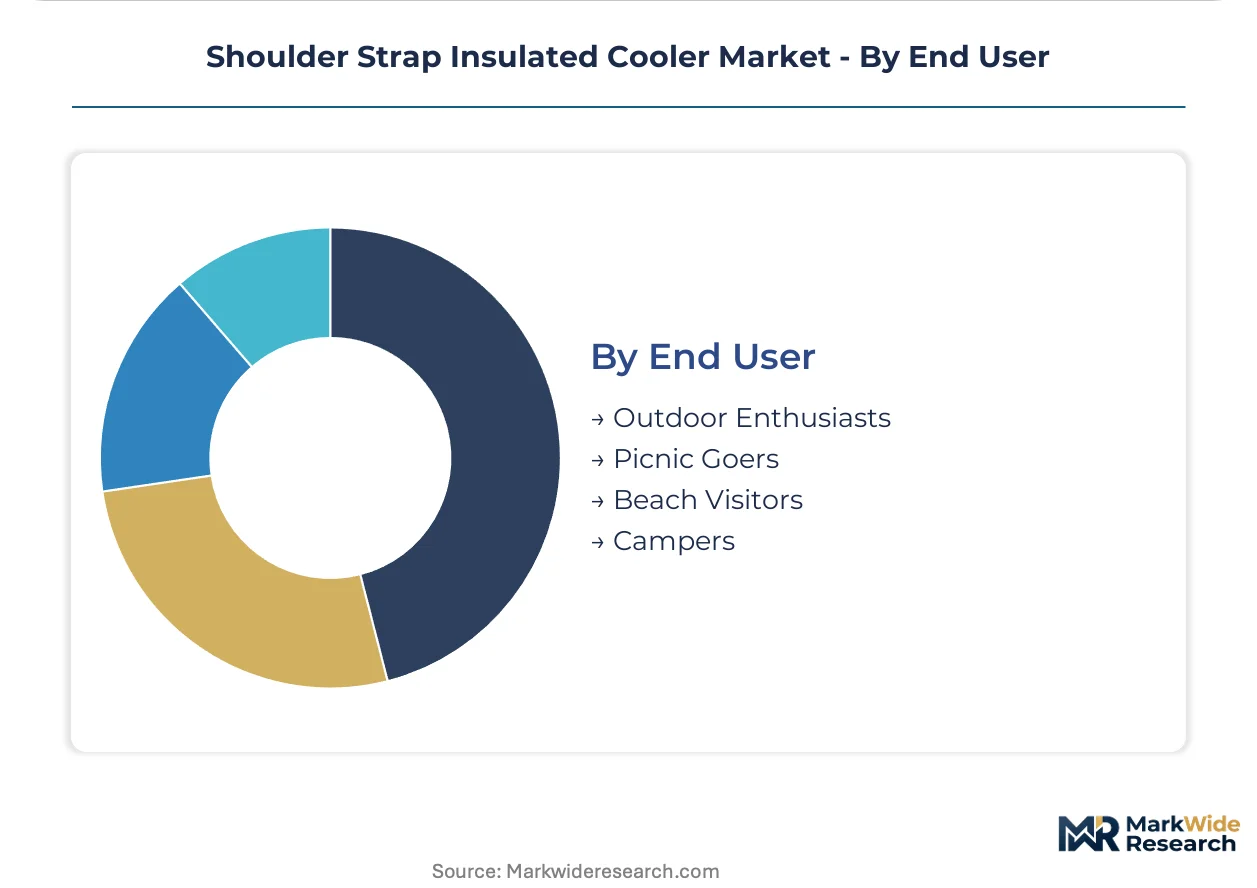
End User:
User context determines performance expectations and price elasticity, with technical outdoor segments tolerating significant premiums for certified thermal retention.
- Campers:Multi-day wilderness users requiring food safety compliance across variable temperature exposure. German consumers in particular demonstrate willingness to pay for ISO 9001-certified manufacturing.
- Outdoor Enthusiasts:Technical users spanning alpine mountaineering, backcountry hunting, and expedition kayaking. Vacuum-insulated panel specifications from Colorado outfitters are reshaping performance benchmarks.
- Beach Visitors:Sand and saltwater exposure drives demand for welded-seam construction and corrosion-resistant hardware. Florida and California coastal markets favor wheeled configurations for dune access.
- Picnic Goers:Casual day-use segment prioritizing aesthetic customization and lightweight transport. Brand-owned digital channels with colorway configurators are capturing share from specialty retailers.
Campers anchor volume demand, though Outdoor Enthusiasts are expanding most quickly as VIP technology penetrates alpine applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European distribution for premium outdoor equipment, connecting rotomolded cooler manufacturers to alpine outfitters across the continent. Container throughput from Asian contract facilities concentrates in Los Angeles-Long Beach for West Coast specialty retail channels. German rail freight corridors link production clusters in Bavaria to Scandinavian camping markets.
United States
Backcountry hunting expeditions in Montana and Idaho drive demand for MIL-SPEC durability ratings. EPA SNAP regulations phase down hydrofluorocarbon blowing agents, forcing foam-injection retooling in Ohio and Tennessee. Rotational molding capacity concentrates in domestic facilities serving peak outdoor season bottlenecks.
Germany
Premium camping gear consumption rises among outdoor enthusiasts prioritizing ISO 9001-certified manufacturing. EU F-Gas Regulation mandates abandonment of HFC-based foam blowing agents across European production lines. Bavarian industrial clusters supply REACH-compliant TPU formulations to liner material producers.
Japan
Alpine mountaineering outfitters in Nagano Prefecture specify vacuum-insulated panel cores for high-altitude thermal retention. METI efficiency standards influence insulation performance benchmarks for domestic manufacturers. Kanto region distribution hubs serve technical outdoor retailers across Honshu.
Canada
Multi-day wilderness trekkers in British Columbia and Alberta prioritize backpack-style configurations for hands-free mobility. Health Canada chemical disclosure rules align with California Proposition 65 requirements for cross-border brands. Ontario-based rotational molders supply hard-sided units to fishing lodges across the Canadian Shield.
Australia
Beach visitors in Queensland and New South Wales favor wheeled configurations for coastal dune access. TGA-aligned product safety frameworks govern thermal retention claims in specialty retail channels. Sydney and Melbourne digital commerce clusters drive brand-owned channel migration among urban professionals.
Shoulder Strap Insulated Cooler Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, creating a bifurcated structure where ISO 9001 qualification separates qualified manufacturers from commodity assemblers. The vendor base concentrates around three strategic archetypes: vertically integrated foam-injection operators controlling thermal consistency, MIL-SPEC heritage brands leveraging protective case durability standards, and scale-driven rotational molders maximizing production throughput. Dominant competitive moves include backward integration into captive foam-blowing capacity and strategic partnerships with alpine outfitters for VIP technology validation.
Within the premium-tier vector, Yeti Coolers exemplifies vertical integration architecture, while Pelican Products occupies a position anchored in protective-case heritage standards. Igloo Products represents the scale-driven archetype through large-format rotational molding capacity. These three entities collectively illustrate the competitive tension between quality-controlled supply chains and commodity manufacturing economics.
| Leading Market Players |
|---|
| Yeti Coolers |
| AO Coolers |
| Bison Coolers |
| Pelican Products |
| Grizzly Coolers |
| The Coleman Company |
| Igloo Products |
| Engel Coolers |
| RTIC Outdoors |
| Others |
Value Network & Pricing Analysis
Pentane substitution for hydrofluorocarbon blowing agents is redrawing procurement geography toward Texas and Louisiana petrochemical corridors while compressing margin buffers for mid-volume foam-injection operators. This input transition simultaneously elevates energy price exposure and consolidates supplier bargaining power among domestic refiners.
Pricing Analysis
Certification level creates the primary spread between ISO 9001-qualified manufacturers and commodity assemblers. Three-tier pricing structure across premium, standard, and economy levels reflects quality-grade differentiation, with MIL-SPEC durability ratings commanding widest spreads. Cost compression in mid-market soft-sided segments is intensifying because REACH-compliant TPU formulations carry material premiums. Picnic goers and casual beach visitors exhibit highest price sensitivity, while alpine mountaineering outfitters tolerate significant premiums for vacuum-insulated panel specifications.
Supply Chain Analysis
Inventory cycles for rotomolded hard-sided units extend through peak outdoor season bottlenecks, with lead times stretching when Ohio and Tennessee foam-injection facilities retool for cyclopentane systems. Supply concentrates in the United States for rotational molding capacity, China for laminated TPU-nylon fabrication, and Germany for REACH-compliant liner formulations. Raw material flows draw from polyethylene resin producers, closed-cell foam suppliers, and coated textile weavers. Single-source vulnerability in pentane supply from Gulf Coast refiners exposes margins to energy price swings. Distribution runs through specialty outdoor retailers, brand-owned digital channels with configuration tools, and mass-market big-box chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers, material formulations, and user contexts creates multiple niche entry points as backpack-style configurations and vacuum-insulated panel specifications reshape demand segmentation.
For Market Incumbents: Consolidate backward integration into captive foam-blowing capacity to secure thermal consistency against contract-dependent assemblers. Acquire ISO 9001-certified mid-tier manufacturers to fill quality-controlled supply gaps. Channel control through exclusive alpine outfitter partnerships defends premium positioning as VIP technology penetrates high-altitude applications. For New Entrants and Emerging Players: Anchor in the backpack-style configuration white space where ergonomic frame geometry development lags behind Appalachian Trail through-hiker demand. Target sub-zero ice-fishing segments in Minnesota and Wisconsin with welded-seam durability innovations. A direct-to-consumer launch with strap geometry configurators bypasses specialty retail gatekeepers. For Investors and Strategic Acquirers: EU F-Gas Regulation reshapes the acquisition landscape by devaluing HFC-dependent production assets and elevating pentane-retooled facilities. Long-term viability favors vertically integrated operators with captive molding and foam-injection capacity. The signal to watch is rotational molding equipment utilization rates during Q3 peak season as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam-Blowing Capacity | Captive pentane or water-blown systems insulate margins from Gulf Coast energy volatility. |
| ISO 9001 Certification Investment | Quality management credentials bifurcate supplier base and unlock premium retail shelf space. |
| Backpack-Style Configuration Development | Ergonomic load-distribution frames capture Appalachian Trail through-hiker expansion. |
| Vacuum-Insulated Panel Technology Partnership | Alpine outfitter validation in Colorado and Washington State compresses soft-hard performance gaps. |
| REACH-Compliant TPU Sourcing Transition | Phthalate-free liner formulations secure European distribution and West Coast retail access. |
Research Methodology
A spread of perspectives from foam-injection plant managers, specialty outdoor retail buyers, alpine outfitter procurement leads, and rotational molding equipment operators converged on the working assumptions. Primary fieldwork combined with secondary validation from EPA SNAP regulatory filings, ECHA REACH substance restrictions, customs trade data on TPU-coated textile imports, and SEC 10-K disclosures from listed cooler manufacturers. Bottom-up capacity utilization modeling and top-down consumer expenditure triangulation anchored volume estimates.
Product type, material formulation, capacity tier, and end-use context structured the analytical framework across the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro outdoor recreation expenditure trends. Industry-specific forecast inputs included rotational molding equipment installation rates and REACH compliance transition timelines for European liner material sourcing.
Material uncertainties — regulatory enforcement intensity on chemical disclosure, pentane supply disruptions from Gulf Coast weather events, and vacuum-insulated panel cost curves — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
North America and Europe Leaf Blower Market
Outdoor Gear
Japan Camping Tent Market
Outdoor Gear
Inflatable Tents Market
Outdoor Gear
Ice Axe Market
Outdoor Gear
Cordless Garden Equipment Market
Outdoor Gear
Bicycle Bags and Bag Packs Market
Outdoor Gear
Picnic Coolers Market
Outdoor Gear
Wheeled Insulated Cooler Market
Outdoor Gear
Spain Camping Equipment Market
Outdoor Gear
Hiking Backpack Water Filters Market
Outdoor Gear
Diving Equipment Market
Outdoor Gear
North America Pocket Knives Market
Outdoor Gear
Singapore Camping Equipment Market
Outdoor Gear
Camping Gas Canister Market
Outdoor Gear
Global Automatic Mower Market
Outdoor Gear
Rooftop Tent Market