
 Camping Gas Canister Market | 2026-2036
Camping Gas Canister Market Size, Share, and Industry Trends Forecast 2026-2036
Camping Gas Canister Market Insights
Aftermarket refill and recycling services is fragmenting as consumers weigh convenience against sustainability mandates. Coleman leverages its retail network to sustain broad shelf presence across mass-market channels. Iwatani anchors the Asian supply base with deep manufacturing scale in steel canister fabrication.
Camping gas canisters are sealed, pressurized metal vessels containing liquefied petroleum gas blends, typically butane, propane, or isobutane formulations, designed to deliver controlled fuel release for portable stoves and heating devices. Wall thickness, valve thread standards, and blend ratios determine performance across temperature ranges and altitude conditions. Mixture-type canisters lead volume as backpackers prioritize cold-weather reliability, while 230g capacity units occupy the margin-rich center of the hiking segment where weight and burn duration balance. Eco-friendly packaging variants are gaining fastest as retailers in Europe enforce reduced-plastic shelf requirements.
DOT hazardous materials regulations in the United States govern transport labeling and pressure testing, while REACH in Europe restricts certain metal coatings and chemical additives in valve assemblies. The EU F-Gas Regulation indirectly shapes canister formulation trends as manufacturers anticipate broader fluorinated gas restrictions. Stakeholders must monitor evolving refill-station infrastructure and deposit-return schemes as these programs threaten single-use canister economics in core European markets.
Market Dynamics
The camping gas canister market is being reshaped by tightening chemical compliance regimes that force material substitutions and manufacturing relocations, while alpine tourism clusters in Germany, Austria, and Switzerland sustain concentrated demand for high-performance fuel formulations.
Growth Catalysts
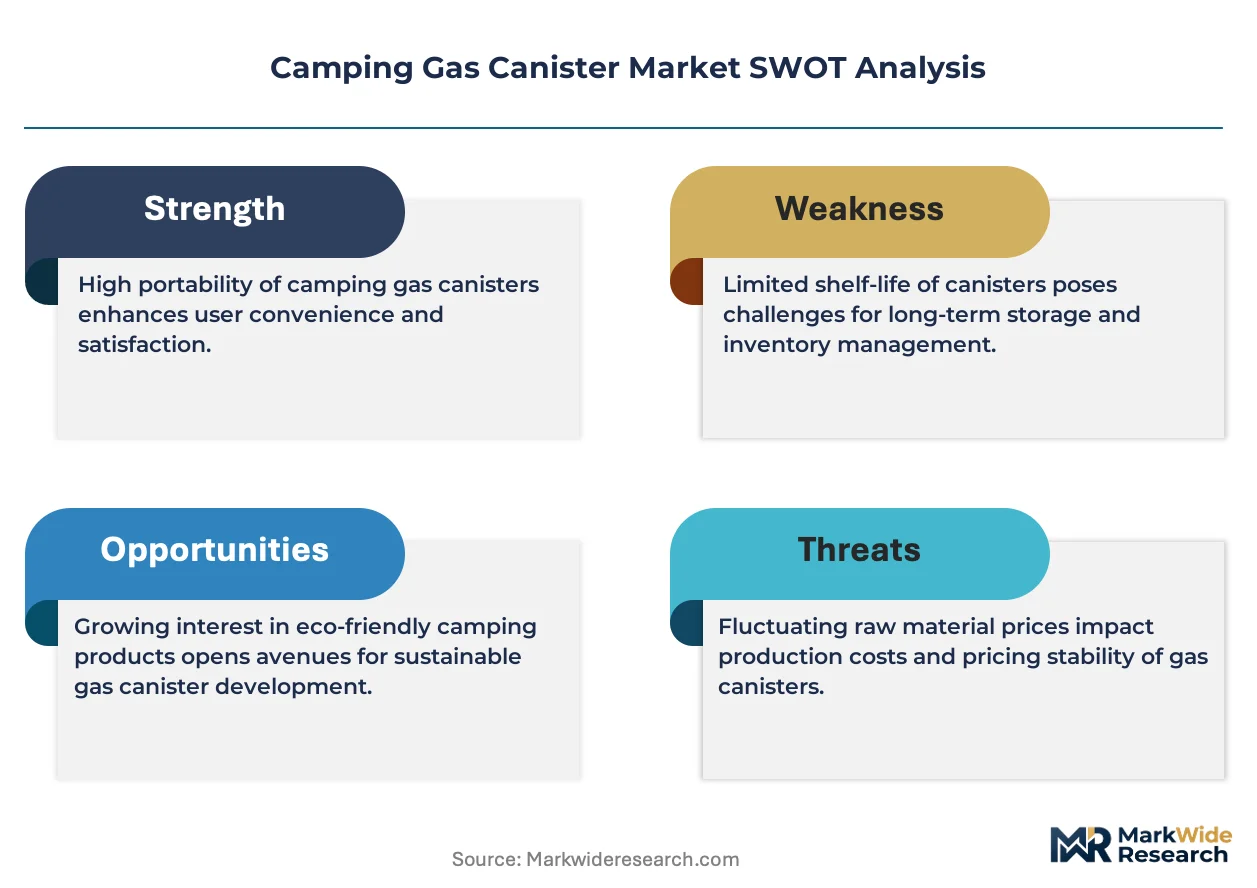
- REACH chemical restrictions:European regulators are phasing out specific metal coatings and valve additives, accelerating R&D investment in compliant sealing technologies and creating first-mover advantages for certified suppliers.
- Ultralight backpacking segment:Alpine tourism operators in Austria and Switzerland are specifying isobutane-propane blends for guided high-altitude expeditions, pulling premium mixture-type canister volumes.
- Steel fabrication scale:Deep manufacturing concentration in East Asian steel canister production is compressing unit costs and enabling margin expansion for export-oriented brands.
Market Restraints
- Propane feedstock volatility:Petrochemical input costs fluctuate with crude oil benchmarks, squeezing blenders' margins during price spikes and complicating long-term contract pricing.
- DOT transport classification:United States hazardous materials rules impose strict pressure-testing and labeling burdens, raising compliance costs for cross-border shipments and limiting small-batch import flexibility.
- Electric camp stove substitution:Battery-powered cooking systems are capturing car-camping and festival segments where weight constraints matter less, threatening volume in the 450g+ canister category.
Strategic Opportunities
- Deposit-return infrastructure:Germany's expanding refill-station network and canister deposit schemes are creating closed-loop service models that capture recurring revenue streams.
- Reduced-plastic packaging mandates:EU retailer shelf requirements are opening premium positioning for eco-friendly cardboard and fiber-based canister packaging variants.
- Smart valve integration:Convergence of pressure-sensor microelectronics with traditional mechanical valves is digitizing fuel-level monitoring for safety-conscious alpine users.
Industry Challenges
- Welding certification timelines:Pressure-vessel seam qualification under ISO standards requires 12-18 month validation cycles, delaying new product introductions.
- Specialized metallurgy talent:Thin-wall steel forming expertise for lightweight canisters concentrates in aging workforces at Japanese and Korean fabricators, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camping Gas Canister Market |
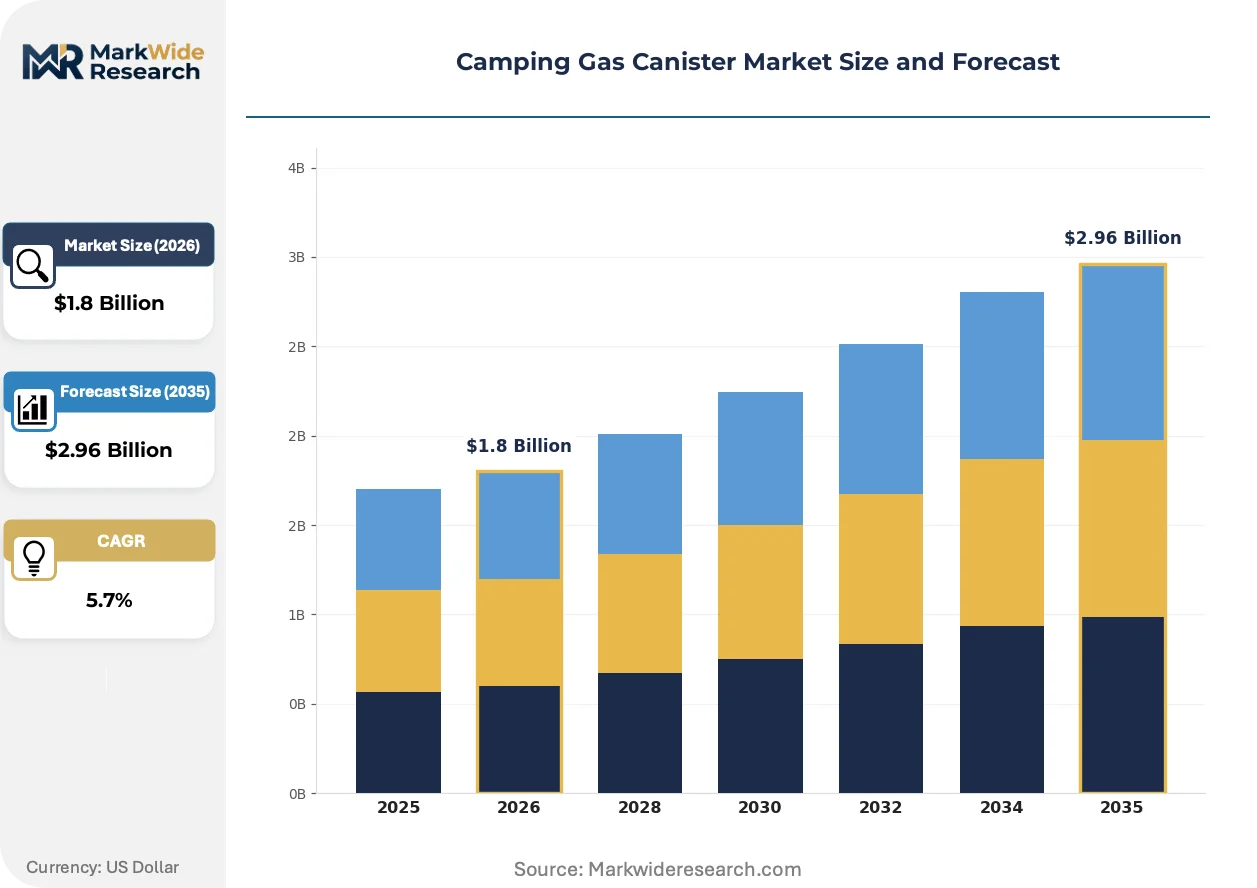
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Butane, Propane, Isobutane, Mixture Capacity: 100g, 230g, 450g, 500g Usage: Camping, Backpacking, Cooking, Emergency Packaging Type: Single Unit, Combo Pack, Eco-Friendly, Disposable |
| Companies Covered | Coleman, Kampa, GoSystem, Gasmate, Iwatani, Taeyang, Maxsun, Marina Corporation, SEUNG IL Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camping Gas Canister Market Trends and Innovations
Material science advances and regulatory pressure are converging to transform canister construction, valve design, and end-of-life handling protocols across the portable fuel sector.
Embedded pressure-sensor modules are digitizing fuel-level visibility for alpine users. These microelectronic systems transmit remaining capacity data to smartphone apps via Bluetooth Low Energy. Mountain guides in the Swiss Alps are adopting digitized canisters for client safety protocols, compressing the information asymmetry between novice users and fuel management risks.
EU F-Gas Regulation is tightening fluorinated gas restrictions and forcing blend reformulation. Manufacturers are accelerating propane-isobutane ratio adjustments to anticipate broader bans on synthetic refrigerant-class compounds. Cold-weather performance segments in Norway and Finland are responding by stockpiling legacy formulations ahead of phase-out deadlines.
Direct-to-consumer subscription models are displacing traditional retail replenishment cycles. Specialty outdoor retailers in Germany are unbundling after-sales refill services, with urban outdoor shops in Munich and Hamburg piloting exchange programs that bypass supermarket shelf competition. This channel shift is most visible in metropolitan areas where deposit-return infrastructure density supports logistics economics.
Camping Gas Canister Market Segmentation
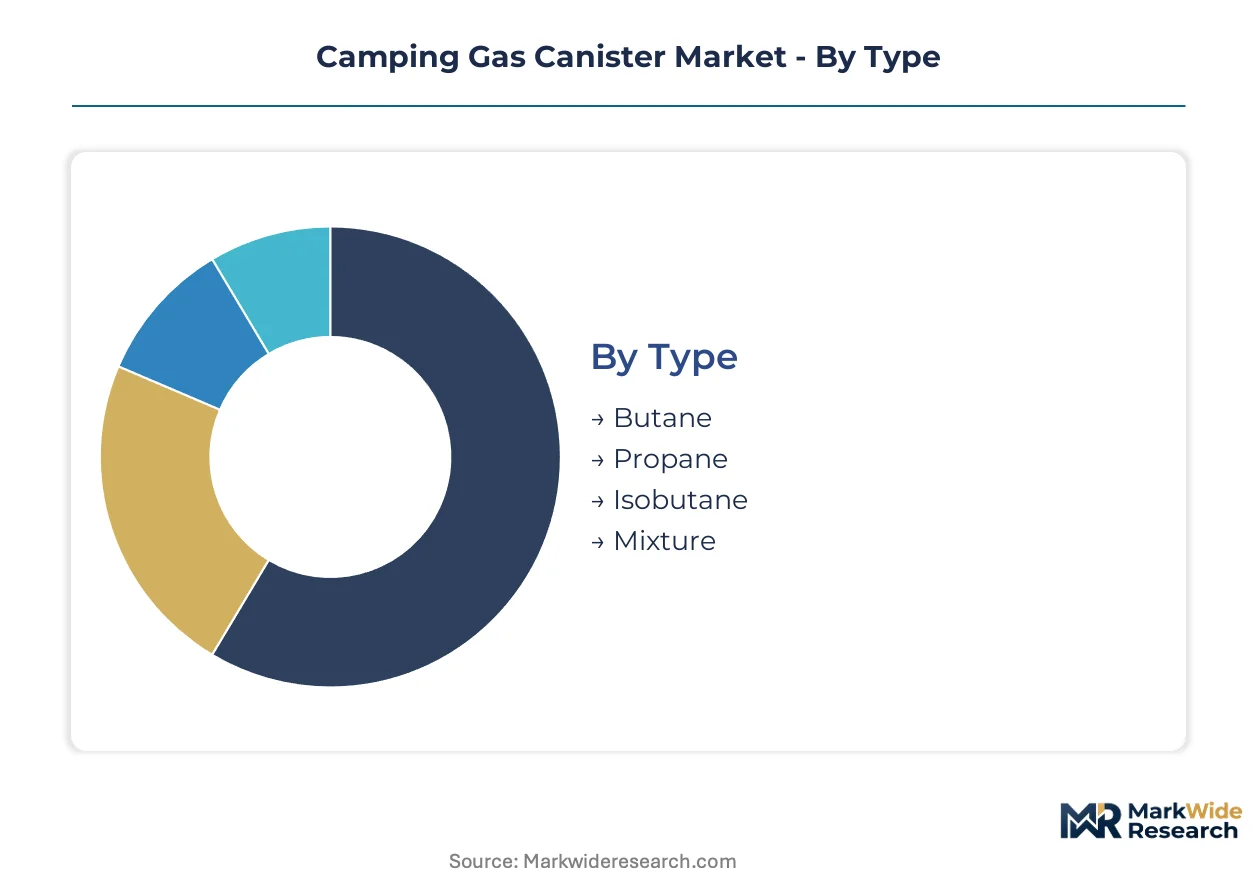
Canister segmentation reveals how fuel chemistry, vessel sizing, and end-use intensity create distinct margin profiles across outdoor recreation and emergency preparedness verticals. Each dimension carries regulatory and supply chain implications that reshape competitive positioning.
Type:
Mature propane and butane formulations coexist with emerging isobutane blends as altitude performance requirements intensify across alpine destinations.
- Mixture:Isobutane-propane blends optimize vapor pressure for sub-zero conditions. Alpine tourism operators in Austria and Switzerland specify these formulations for guided high-altitude expeditions, pulling premium volumes from recreational users seeking cold-weather reliability.
- Butane:Pure butane dominates warm-weather camping in Mediterranean climates where vapor pressure requirements moderate. Festival culture in Spain and Italy sustains concentrated demand for this cost-optimized formulation.
- Propane:High-vapor-pressure pure propane serves car-camping and basecamp scenarios where weight constraints relax. US national park concessionaires favor this variant for reliability across elevation ranges.
- Isobutane:Single-component isobutane targets ultralight purists demanding maximum energy density per gram. Japanese mountaineering clubs drive specialized import volumes for technical ascents.
Mixture formulations retain volume leadership; isobutane climbs the fastest as gram-counting backpackers prioritize energy density.
Capacity:
Cost tiers separate ultralight minimalists from basecamp comfort-seekers, with mid-range capacities capturing the margin-rich hiking core.
- 230g:The standard backpacking unit balances burn duration against pack weight. REI and specialty retailers in Colorado position this capacity as the default recommendation for multi-day treks, creating pricing power through inventory depth.
- 450g:Extended-trip and small-group formats favor this capacity for reduced per-meal packaging waste. Outfitters in Norway's fjord regions specify 450g for kayak touring where resupply points are sparse.
- 100g:Emergency kits and ultralight fastpacking favor this minimal format. California's earthquake preparedness programs subsidize 100g canister inclusion in residential emergency caches.
- 500g:Car-camping and festival catering select this maximum retail format. German camping retailers bundle 500g units with entry-level stove sets to capture first-time buyer spend.
230g holds the steepest expansion curve; 500g retains installed-base dominance among occasional campers.
Usage:
Application intensity varies from recreational leisure to survival-critical deployment, with each use case imposing distinct performance and certification requirements.
- Backpacking:Weight-constrained multi-day trekking demands isobutane-propane blends in sub-250g formats. Pacific Crest Trail thru-hiker communities in California and Oregon drive seasonal demand spikes and brand loyalty.
- Emergency:Disaster preparedness programs require multi-year shelf stability and universal stove compatibility. Japan's METI stockpiling specifications shape regional procurement standards for household resilience kits.
- Camping:Drive-up campground scenarios tolerate heavier formats and simpler butane formulations. KOA franchise locations across Texas and Florida standardize on 450g propane for rental equipment.
- Cooking:Mobile catering and food truck auxiliary power favor high-capacity propane for consistent flame control. Street food vendors in Seoul's night markets adapted camping canisters during regulatory transitions.
Backpacking captures the fastest volume growth; emergency applications command the highest per-unit margins through institutional procurement.
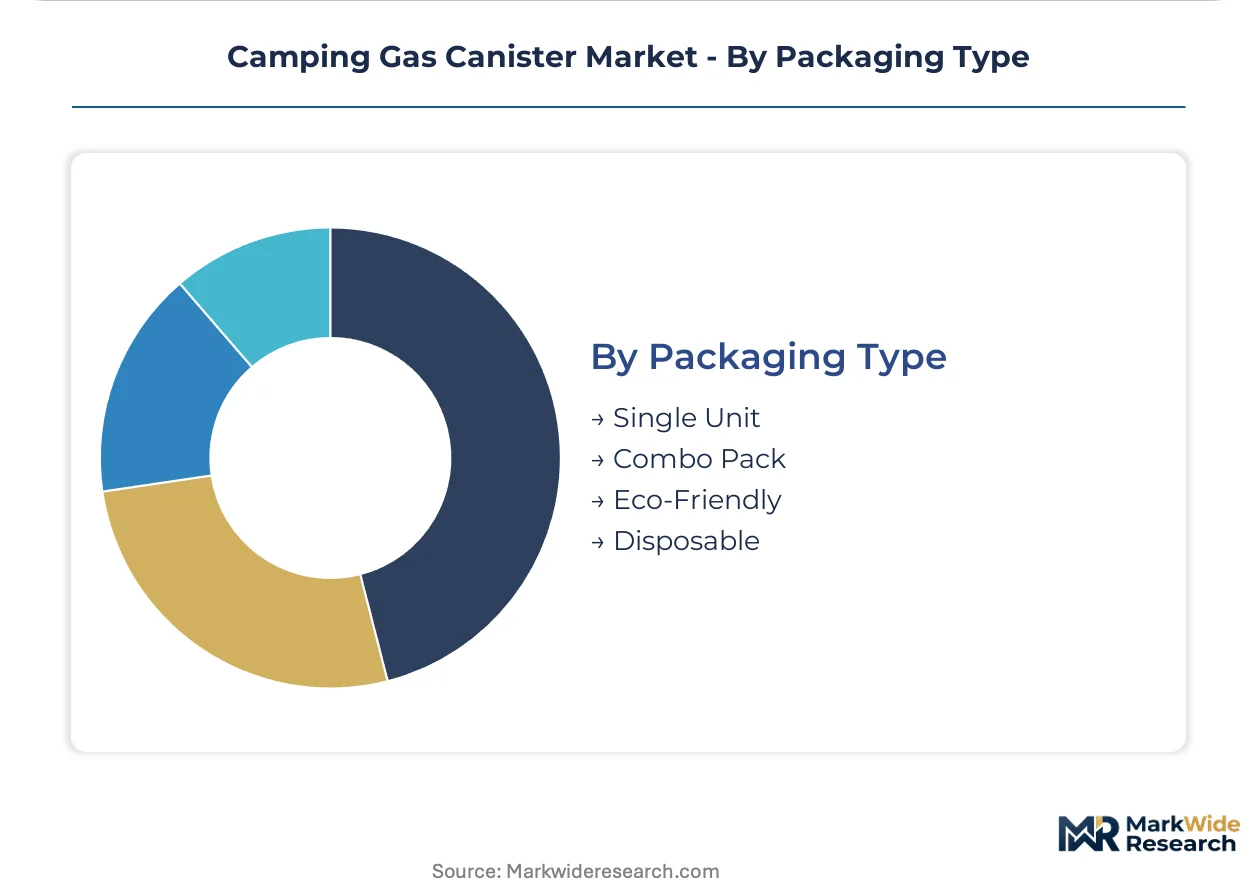
Packaging Type:
Customer type and environmental compliance separate single-unit convenience buyers from subscription-oriented eco-adopters.
- Eco-Friendly:Cardboard and fiber-based alternatives replace plastic shrink-wrap for EU retailer compliance. Munich outdoor shops pilot deposit-return schemes with fiber packaging to differentiate against supermarket competition.
- Single Unit:Impulse purchase formats dominate airport and convenience store channels. Tokyo station kiosks stock 100g single units for last-minute acquisition before mountain train departures.
- Combo Pack:Stove-plus-canister bundles reduce customer acquisition costs for entry-level brands. Walmart's outdoor seasonal displays prioritize combo packs for gift-giving occasions.
- Disposable:Non-refillable formats persist where deposit infrastructure remains underdeveloped. Southeast Asian markets rely on disposable units due to limited refill station density.
Eco-friendly variants gain share fastest; single-unit packaging retains channel ubiquity through impulse accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies: German consumers absorb premium isobutane-propane blends for alpine reliability, while Southeast Asian buyers prioritize low-unit-cost butane for warm-weather leisure camping.
Germany
Alpine tourism in Bavaria and festival culture nationwide sustain per-capita consumption leadership. REACH chemical restrictions from ECHA are accelerating compliant valve assembly redesigns among domestic distributors. Munich and Hamburg outdoor retailers pilot deposit-return schemes that bypass supermarket competition.
United States
Pacific Crest Trail thru-hiker communities in California and Oregon drive seasonal demand spikes for mixture-type canisters. DOT hazardous materials regulations impose strict pressure-testing and labeling burdens on cross-border shipments. Colorado specialty retailers leverage inventory depth to capture pricing power in the 230g backpacking segment.
Japan
METI stockpiling specifications shape household emergency preparedness procurement standards nationwide. Mountaineering clubs in Tokyo and Osaka drive specialized import volumes for single-component isobutane technical ascents. Kanto region fabricators concentrate thin-wall steel forming expertise for ultralight canister production.
China
Steel fabrication scale in Yangtze River Delta manufacturing clusters compresses unit costs for export-oriented brands. GB standards and MIIT directives govern pressure vessel certification timelines. Shenzhen and Guangzhou producers supply disposable-format canisters to Southeast Asian markets with limited refill infrastructure.
Norway
Fjord region outfitters specify 450g capacities for kayak touring where resupply points remain sparse. EU F-Gas Regulation anticipation drives stockpiling of legacy propane-isobutane formulations ahead of phase-out deadlines. Bergen and Tromsø retailers anchor cold-weather performance segment distribution.
Camping Gas Canister Market Competitive Landscape
Capability concentration sits with specialized steel-forming fabricators; scale advantage sits with diversified outdoor equipment conglomerates. The vendor base separates into three tiers: mass-market retailers with broad shelf presence, East Asian manufacturers with deep steel canister production scale, and regional specialists serving alpine tourism operators. Dominant competitive moves include strategic partnerships with refill-station infrastructure providers and portfolio diversification into eco-friendly packaging variants.
Among East Asian fabricators, Iwatani anchors steel canister supply chain positioning, while Taeyang and SEUNG IL Corporation occupy positions within the Korean manufacturing cluster. Coleman represents the mass-market retail archetype with established distribution networks. These named entities exemplify how geographic manufacturing concentration and channel access create divergent competitive advantages across premium mixture formulations and standard butane categories.
| Leading Market Players |
|---|
| Coleman |
| Kampa |
| GoSystem |
| Gasmate |
| Iwatani |
| Taeyang |
| Maxsun |
| Marina Corporation |
| SEUNG IL Corporation |
| Others |
Pricing and Supply Chain Analysis
Propane feedstock volatility tied to crude oil benchmarks compresses blender margins during price spikes while simultaneously widening spreads between premium isobutane-propane blends and standard butane formulations. This input cost instability forces manufacturers to choose between absorbing margin erosion or pushing price increases downstream, reshaping procurement relationships across the camping gas canister value chain.
Pricing Analysis
After-sales refill and exchange revenue streams drive lifetime customer value beyond initial canister purchase. Three-tier pricing structure across premium mixture formulations, standard butane, and economy propane levels separates alpine-performance buyers from festival campers and car-camping occasional users. Pricing pressure stems from electric camp stove substitution in the 450g+ segment as battery-powered alternatives capture car-camping demand. Backpackers purchasing 230g mixture canisters demonstrate lowest price sensitivity due to safety-critical altitude performance requirements, while Southeast Asian warm-weather buyers prioritize unit cost minimization above blend sophistication.
Supply Chain Analysis
Tariff exposure between China and the United States disrupts cross-border shipments of finished canisters and valve assemblies. Manufacturing gravity centers on China's Yangtze River Delta for steel fabrication, Japan's Kanto region for thin-wall forming expertise, and South Korea's industrial clusters for precision valve components. Raw material dependencies span specialized steel grades, propane-isobutane feedstocks, and microelectronic pressure sensors for smart valve variants. Single-source vulnerability concentrates in Japanese and Korean fabricators where aging workforces constrain capacity expansion. Distribution runs through mass-market retailers, specialty outdoor channels, and emerging direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The camping gas canister market sits in early-stage recovery as alpine tourism rebounds from pandemic-era disruption and guided expedition demand restarts across Austria and Switzerland.
For Market Incumbents: Entrench position through captive supply of compliant valve assemblies ahead of REACH chemical restriction deadlines, and deepen backward integration into steel canister fabrication to offset East Asian cost compression. Electric stove substitution in car-camping segments threatens volume in the 450g+ category; defend through exclusive partnerships with alpine tourism operators specifying isobutane-propane blends for guided expeditions. For New Entrants and Emerging Players: Germany's expanding deposit-return infrastructure and refill-station networks represent the most penetrable entry point for closed-loop service models capturing recurring revenue. Eco-friendly cardboard and fiber-based packaging variants for EU retailer compliance offer differentiation against supermarket competition. Pilot direct-to-consumer subscription programs in Munich and Hamburg where logistics density supports exchange economics. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized steel-forming fabricators with ISO pressure-vessel certification and established alpine tourism relationships. Long-term viability hinges on regulatory compliance capabilities and refill infrastructure access rather than commodity scale. Watch EU F-Gas Regulation implementation timelines as the critical inflection signal for blend reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Deposit-Return Infrastructure Partnership | Captures recurring revenue streams in Germany's expanding refill-station network. |
| Eco-Friendly Packaging Transition | Secures shelf placement at EU retailers enforcing reduced-plastic mandates. |
| Smart Valve Integration | Digitizes fuel-level monitoring for safety-conscious Swiss Alpine guides. |
| REACH Compliance Certification | Creates first-mover advantage as ECHA phases out specific metal coatings. |
| Direct-to-Consumer Subscription Launch | Bypasses supermarket competition in metropolitan outdoor retail channels. |
Research Methodology
The analysis maps mixture-type, butane, propane, and isobutane formulation sub-sectors, each validated through plant managers at steel fabrication facilities, procurement leads at outdoor equipment retailers, distribution channel partners, and technical R&D directors at valve assembly specialists. Primary interview findings triangulate against customs and trade data, steel industry association reports, SEC filings from diversified outdoor conglomerates, and pressure-vessel certification databases. Bottom-up capacity estimates and top-down demand projections reconcile across the modeling period.
Assumptions held fixed include REACH chemical restriction implementation timelines and DOT hazardous materials classification standards, while propane feedstock pricing and electric stove substitution rates were varied across sensitivity scenarios. Segmentation dimensions modeled encompass fuel chemistry type, vessel capacity tier, end-use intensity, and packaging format. CAGRs derive from historical volume trajectories adjusted for regulatory inflection points and alpine tourism recovery patterns. Forecast inputs include METI stockpiling procurement cycles and EU F-Gas Regulation anticipation effects.
Practitioners should monitor crude oil benchmark volatility, refill-station infrastructure deployment rates, and electric camp stove battery efficiency improvements for early signals of forecast deviation. Material shifts in European chemical compliance timelines or alpine tourism operator procurement specifications would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Spain Camping Equipment Market
Outdoor Gear
Canoe Paddles Market
Outdoor Gear
Artificial Grass Turf Market
Outdoor Gear
Rechargeable Camping Gear Market
Outdoor Gear
Camping Equipment and Furniture Market
Outdoor Gear
Bicycle Bags and Bag Packs Market
Outdoor Gear
UK Camping Equipment Market
Outdoor Gear
North America Robotic Lawn Mower Market
Outdoor Gear
Shoulder Strap Insulated Cooler Market
Outdoor Gear
US Backpacks Market
Outdoor Gear
South Korea Camping Equipment Market
Outdoor Gear
North America and Europe Leaf Blower Market
Outdoor Gear
China Camping Equipment Market
Outdoor Gear
China Camping Tent Market
Outdoor Gear
Japan Camping Equipment Market
Outdoor Gear
Beach Umbrella Market