
 Picnic Coolers Market | 2026-2036
Picnic Coolers Market Size, Share, and Industry Trends Forecast 2026-2036
Picnic Coolers Market Insights
Premium rotomolded construction is rotating the Picnic Coolers Market toward higher-margin tiers as consumers prioritize multi-day ice retention and structural durability. YETI Holdings Inc. leverages its proprietary PermaFrost insulation and direct-to-consumer channel to command price premiums in the hard cooler segment. Igloo Products Corp anchors mass-market volume through broad retail distribution and seasonal promotional cycles. Pelican Products Inc. differentiates via lifetime warranty positioning and military-grade engineering heritage.
Picnic coolers are thermally insulated portable containers engineered to maintain sub-ambient temperatures for perishable food and beverages, typically employing polyurethane foam cores with rotomolded polyethylene or laminated fabric exteriors to achieve ice retention spans of 24 hours to 10 days depending on construction grade. Their primary commercial purpose spans outdoor recreation, tailgating, commercial catering, and emergency preparedness applications where passive cold chain integrity determines usability. Hard coolers dominate absolute revenue contribution due to higher unit values and replacement cycles tied to UV degradation of exterior shells, while soft coolers represent the fastest-expanding margin pool as urban consumers prioritize collapsible storage and airline-compliant dimensions. The 31-50 quart capacity band captures the largest family-oriented demand cluster, balancing weekend excursion payload against vehicle transportability.
The US EPA regulates blowing agents in polyurethane foam insulation under SNAP program requirements, compelling manufacturers to transition from HFC-based formulations toward hydro-olefin or water-blown alternatives that alter thermal performance coefficients and material costs. The Consumer Product Safety Commission oversees child safety standards for latch mechanisms and lid closure systems on hard cooler designs. California's Proposition 65 chemical disclosure mandates affect labeling requirements for products containing trace phthalates or heavy metals in exterior coatings. Stakeholders must monitor evolving state-level extended producer responsibility frameworks for plastic products that could impose end-of-life recycling fees or material recovery obligations on cooler manufacturers.
Market Dynamics
The US EPA's SNAP program mandates on hydrofluorocarbon blowing agents are forcing polyurethane foam reformulations that alter thermal performance coefficients and manufacturing economics across the insulated container sector.
Growth Catalysts
- Rotomolded construction adoption:Outdoor recreation communities in Texas, Florida, and Arizona are prioritizing multi-day ice retention capabilities for extended desert and coastal excursions.
- Sun Belt replacement cycles:Year-round outdoor activity in southern US states sustains premium product turnover as UV degradation accelerates shell deterioration.
- Extended producer responsibility frameworks:California's evolving plastic recovery mandates are incentivizing closed-loop material designs that reduce end-of-life disposal costs.
Market Restraints
- Polyol and isocyanate cost volatility:Petrochemical feedstock fluctuations directly compress margin structures for domestic rotomolded manufacturers.
- Technical performance trade-offs:Water-blown and hydro-olefin foam alternatives deliver inferior R-values versus legacy HFC formulations, extending cooling duration claims.
- Substitution by rental models:Event catering services in metropolitan areas are shifting toward temporary cold chain equipment leases for single-use occasions.
Strategic Opportunities
- Airline-compliant soft cooler expansion:Urban consumers in New York, Chicago, and Seattle are driving collapsible, checkpoint-friendly designs for business travel and commuting.
- Emergency preparedness stockpiling:FEMA-adjacent community resilience programs in hurricane-prone Gulf Coast counties are creating institutional procurement channels.
- Direct-to-consumer channel maturation:Manufacturer-owned digital platforms are capturing margin previously allocated to big-box retail slotting fees.
Industry Challenges
- Thermal engineering talent scarcity:Domestic workforce gaps in polymer chemistry and rotational molding process optimization constrain product development velocity.
- Proposition 65 compliance complexity:California's chemical disclosure requirements for exterior coating trace contaminants create labeling and supply chain verification burdens.
- Rotational molding equipment lead times:Multi-year capital equipment delivery schedules limit capacity expansion responsiveness to demand spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Picnic Coolers Market |
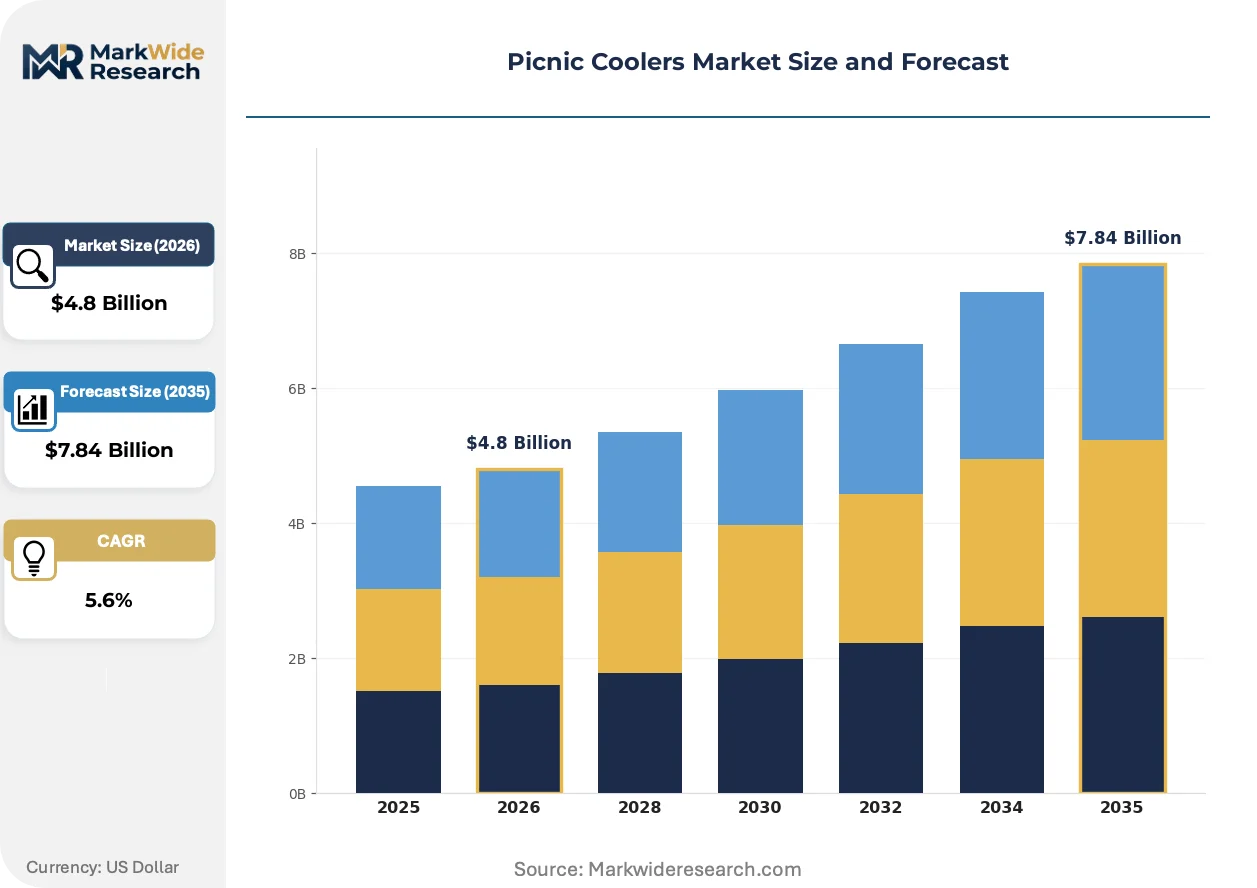
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Coolers, Soft Coolers, Ice Packs, Cooler Bags Material: Plastic, Stainless Steel, Aluminum, Fiberglass Capacity: 10-20 Quarts, 21-30 Quarts, 31-50 Quarts, 51+ Quarts End User: Families, Outdoor Enthusiasts, Campers, Event Planners |
| Companies Covered | YETI Holdings Inc., Igloo Products Corp, The Coleman Company Inc., Pelican Products Inc., Grizzly Coolers, Bison Coolers, Engel Coolers, ORCA Coolers, Rubbermaid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Picnic Coolers Market Trends and Innovations
Material science advances and regulatory chemistry transitions are fragmenting competitive advantage sources across hard and soft cooler categories. Manufacturers now compete on thermal coefficient precision rather than brand heritage alone.
Vacuum-insulated panel technology is bifurcating the premium segment from conventional foam-core construction. Expedition-grade buyers in Alaska and Montana are adopting VIP-enhanced designs for 7-10 day backcountry retention. This thermal performance gap is compressing mid-tier price positioning and forcing legacy brands toward either commodity volume or ultra-premium engineering investment.
The US EPA's Significant New Alternatives Policy continues tightening acceptable blowing agent lists for polyurethane production. Foam suppliers must validate hydro-olefin and hydrocarbon formulations through updated thermal conductivity testing protocols. Hard cooler manufacturers serving military and commercial catering contracts face compressed certification timelines as 2025 formulation deadlines approach.
Subscription-based cooler access models are emerging in metropolitan outdoor retail corridors. REI and specialty outfitters in Denver and Portland now offer seasonal equipment libraries that displace individual ownership for occasional users. This consumption-pattern shift concentrates durable goods demand among frequent adventurers while expanding service revenue pools for retail intermediaries.
Picnic Coolers Market Segmentation
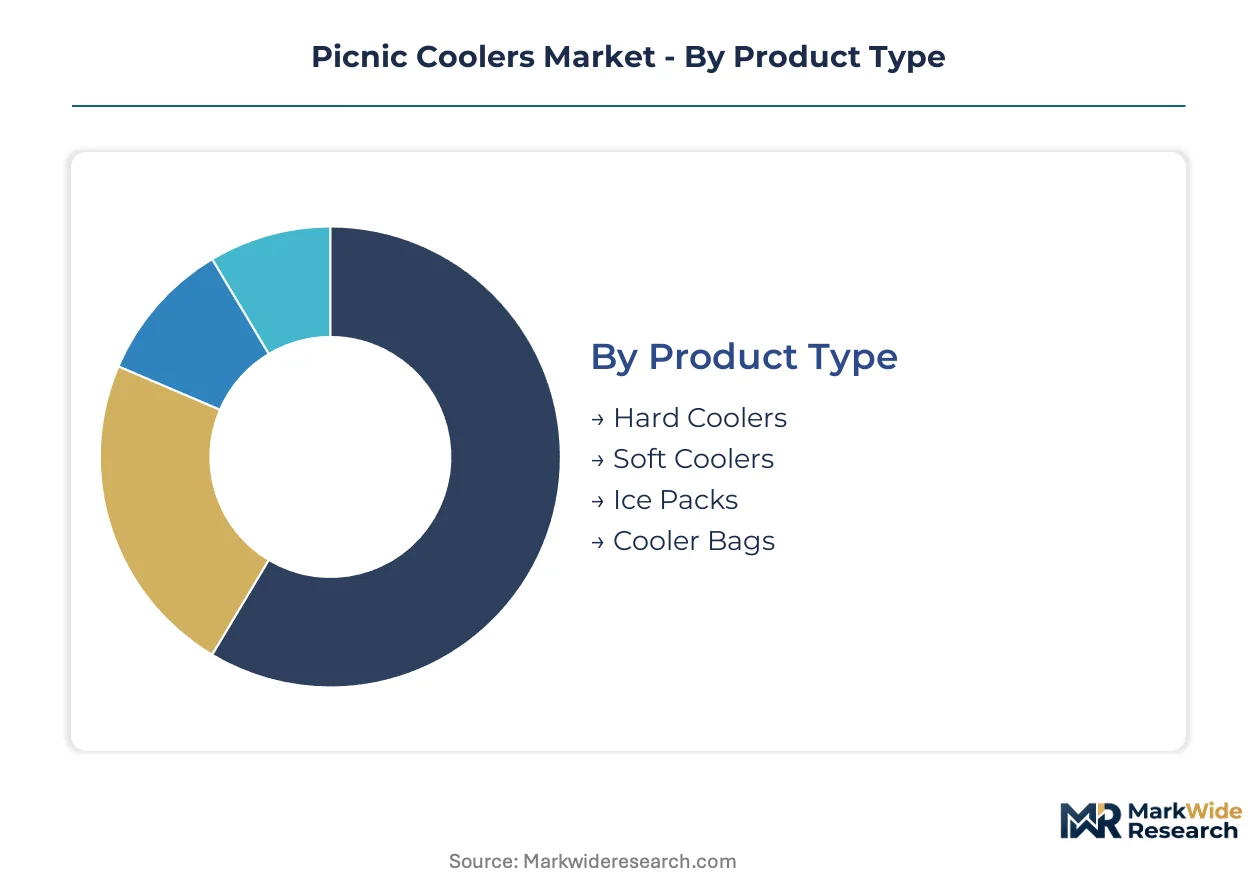
Segmentation in the Picnic Coolers Market reveals distinct channel affinities that shape margin capture and inventory velocity. Hard coolers flow predominantly through specialty outdoor retailers and direct-to-consumer platforms, while soft coolers and cooler bags concentrate in mass-market big-box and e-commerce channels.
Product Type:
Channel mix varies sharply across product types, with hard coolers commanding premium shelf space in outdoor specialty stores and soft coolers saturating airline-accessible urban retail corridors.
- Hard Coolers:Rotomolded polyethylene shells with polyurethane foam cores deliver 3-10 day ice retention for extended expeditions. Demand concentrates in Texas, Florida, and Arizona where year-round desert and coastal recreation sustains replacement cycles against UV shell degradation.
- Soft Coolers:Laminated fabric exteriors with closed-cell foam insulation prioritize collapsible storage and checkpoint-compliant dimensions for urban commuters. New York, Chicago, and Seattle consumers drive fastest expansion through business travel and daily commuting applications.
- Ice Packs:Phase-change gel formulations extend cooling duration in hybrid systems.
- Cooler Bags:Lightweight insulated totes serve single-day recreational and grocery transport needs.
By volume, hard coolers lead. By growth pace, soft coolers are climbing the fastest.
Material:
Cost tier alignment determines procurement concentration, with rotomolded plastic anchoring mass-market volume and metal alternatives capturing premium positioning.
- Plastic:Rotomolded polyethylene dominates through scalable manufacturing and design flexibility for complex geometries. The US EPA's SNAP program mandates on hydrofluorocarbon blowing agents are forcing thermal performance recalibration across polyurethane-dependent plastic constructions.
- Stainless Steel:Vacuum-insulated double-wall construction targets expedition-grade buyers in Alaska and Montana seeking 7-10 day backcountry retention without foam degradation.
- Aluminum:Lightweight corrosion-resistant shells serve marine and coastal applications.
- Fiberglass:High strength-to-weight ratios support custom commercial catering configurations.
Plastic commands absolute unit volume. Stainless steel generates highest per-unit margin expansion.
Capacity:
Application context drives capacity selection, with vehicle-constrained weekend excursions favoring mid-range volumes and basecamp scenarios demanding maximum payload.
- 31-50 Quarts:The family-oriented sweet spot balances weekend excursion payload against trunk and truck bed transportability. Sun Belt states sustain replacement cycles as UV exposure accelerates shell deterioration in this high-usage capacity band.
- 51+ Quarts:Extended expedition and commercial catering configurations prioritize multi-day ice retention for group provisions. Gulf Coast hurricane preparedness programs create institutional procurement channels for large-capacity emergency stockpiling.
- 10-20 Quarts:Personal and commuter-scale designs for single-day use.
- 21-30 Quarts:Compact couple and small-group configurations for day trips.
Mid-capacity 31-50 quart designs anchor revenue concentration. Large-format 51+ quart models are expanding most quickly through commercial and institutional channels.
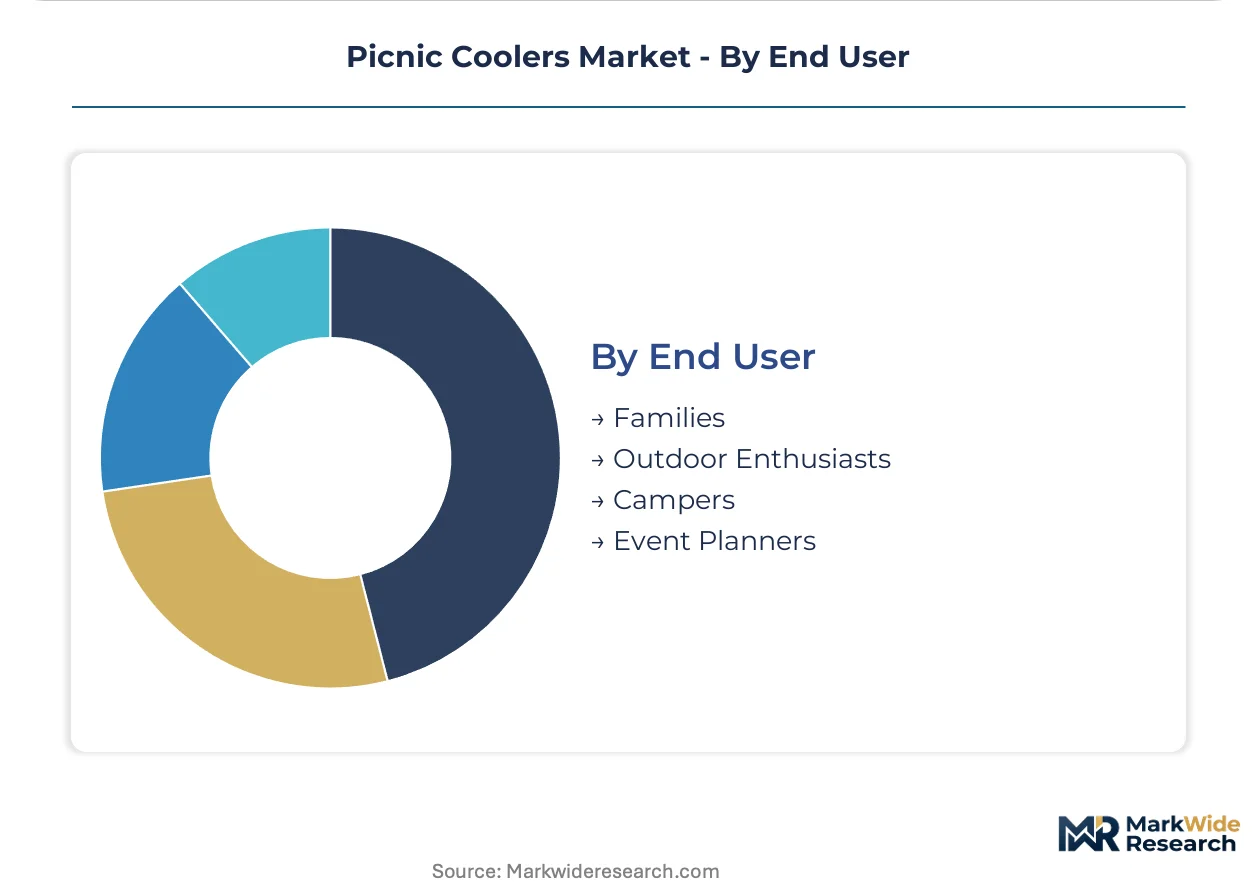
End User:
Customer type segmentation maps directly to pricing tolerance and feature prioritization, from durability demands in remote recreation to convenience requirements in urban event contexts.
- Outdoor Enthusiasts:Expedition-grade buyers prioritize rotomolded construction and multi-day ice retention for backcountry and remote water access. FEMA-adjacent community resilience programs in hurricane-prone counties create institutional procurement overlap with individual preparedness purchases.
- Families:Multi-use purchasers balance weekend recreation, youth sports, and emergency preparedness in single-product decisions. Seasonal promotional cycles at mass retailers concentrate volume in this price-sensitive segment.
- Campers:Recreation-specific users emphasizing portability and packability for site-based cooling.
- Event Planners:Commercial catering services shifting toward rental models for single-use occasions in metropolitan areas.
Families generate highest absolute unit demand. Outdoor enthusiasts command steepest expansion trajectory through premium product turnover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotomolded cooler manufacturing concentrates in the United States, where polyurethane foam expertise and rotational molding infrastructure anchor global supply. Demand patterns diverge sharply across climatic zones, with year-round outdoor recreation in southern states sustaining replacement cycles against UV degradation. Regulatory pressure from the US EPA's SNAP program on blowing agent formulations is reshaping regional production economics.
United States
Sun Belt states including Texas, Florida, and Arizona drive premium cooler turnover through year-round desert and coastal recreation. The US EPA's SNAP program mandates hydrofluorocarbon phase-downs, compelling foam reformulations by 2025. Austin and Houston host dense clusters of rotational molding facilities serving both consumer and military contract channels.
Germany
Expedition-grade demand from Alpine recreation and commercial catering sustains vacuum-insulated panel adoption. ECHA's REACH regulations govern chemical disclosures for exterior coatings and foam additives. Bavaria's precision manufacturing corridor around Munich supplies high-performance thermal engineering components to European cooler assemblers.
China
Cost-optimized soft cooler production for export markets dominates volume, with domestic demand rising through urban outdoor retail expansion. The Ministry of Ecology and Environment enforces dual carbon goals affecting petrochemical feedstock sourcing. The Pearl River Delta manufacturing cluster in Guangdong Province integrates laminated fabric production with foam lamination capabilities.
Japan
Compact soft cooler demand accelerates through business travel recovery and commuter-oriented outdoor retail. METI oversees JIS standards for thermal performance testing and material safety. The Kansai region around Osaka maintains specialty rotational molding capacity for premium domestic brands.
Australia
Extended backcountry retention requirements in remote interior regions sustain ultra-premium hard cooler demand. The Therapeutic Goods Administration adjacent framework influences food-contact material standards. Queensland's coastal manufacturing bases serve both domestic recreation and Asia-Pacific export channels.
Picnic Coolers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the insulated container sector. The market structures around three tiers: premium engineering specialists commanding price premiums through proprietary thermal systems, mass-market volume players leveraging retail distribution scale, and emerging direct-to-consumer challengers capturing margin through digital channels. Dominant competitive moves include portfolio diversification across hard and soft cooler categories and strategic partnerships with specialty outdoor retailers.
Within the premium engineering tier, YETI Holdings Inc. and Pelican Products Inc. exemplify proprietary insulation technology positioning. Igloo Products Corp anchors mass-market volume through established retail relationships. These three entities represent distinct strategic archetypes: technology-driven premium pricing, military-grade durability positioning, and promotional-cycle volume capture respectively.
| Leading Market Players |
|---|
| YETI Holdings Inc. |
| Igloo Products Corp |
| The Coleman Company Inc. |
| Pelican Products Inc. |
| Grizzly Coolers |
| Bison Coolers |
| Engel Coolers |
| ORCA Coolers |
| Rubbermaid |
| Others |
Pricing and Supply Chain Analysis
Rotational molding equipment lead times stretching 18-24 months compress capacity expansion responsiveness and anchor pricing power with incumbent manufacturers holding installed base advantages. This inventory constraint interacts with polyurethane foam reformulation costs under EPA mandates to stratify margin capture across construction tiers.
Pricing Analysis
The US EPA's SNAP program dictates the pricing tier structure by forcing thermal performance recalibration across foam-dependent constructions. Three-tier pricing structure across premium, standard, and economy levels separates vacuum-insulated panel designs from rotomolded foam-core models and collapsible soft cooler alternatives. Cost compression in mid-tier rotomolded products is intensifying because water-blown and hydro-olefin foam alternatives deliver inferior R-values versus legacy HFC formulations. Families purchasing through mass retail promotional cycles exhibit highest price sensitivity, while expedition-grade buyers in Alaska and Montana demonstrate lowest sensitivity due to performance-critical application requirements.
Supply Chain Analysis
Inventory constraints on rotational molding equipment concentrate manufacturing capacity in the United States, China, and Australia. Domestic production draws from petrochemical feedstocks including polyol and isocyanate formulations, laminated fabric substrates from Guangdong Province, and vacuum-insulated panel components from Bavaria's precision manufacturing corridor. Single-source vulnerability in foam blowing agent supply creates exposure as 2025 formulation deadlines approach. Distribution runs through specialty outdoor retailers for hard coolers and mass-market big-box channels for soft cooler variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Picnic Coolers Market represents an early-cycle expansion story as FEMA-adjacent community resilience programs institutionalize emergency preparedness procurement beyond individual consumer purchases.
For Market Incumbents: Compound defensive positioning through backward integration into polyurethane foam formulation capabilities and captive supply of rotomolded shell production. Incumbents must secure thermal engineering talent pools in Austin and Houston manufacturing clusters before workforce gaps constrain product development velocity. Capacity addition in Sun Belt states captures replacement cycle concentration against UV degradation-driven turnover. For New Entrants and Emerging Players: Lead with airline-compliant soft cooler designs targeting urban commuter corridors in New York, Chicago, and Seattle where checkpoint-friendly dimensions drive fastest expansion. The collapsible storage segment offers most penetrable white space as established players concentrate on hard cooler premium positioning. Direct-to-consumer channel maturation enables margin capture previously allocated to big-box retail slotting fees. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized cooler divisions lacking direct-to-consumer infrastructure. Long-term viability across the analysis window hinges on regulatory chemistry transition execution and thermal coefficient precision rather than brand heritage alone. The signal to watch is subscription-based cooler access model traction in metropolitan outdoor retail corridors as a consumption-pattern shift indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | Manufacturer-owned digital platforms capture margin previously allocated to REI and specialty retailer slotting fees. |
| Closed-Loop Material Design Investment | California's evolving plastic recovery mandates incentivize designs reducing end-of-life disposal cost exposure. |
| Vacuum-Insulated Panel Technology Integration | VIP-enhanced designs bifurcate premium segment from conventional foam-core construction in expedition-grade applications. |
| FEMA-Adjacent Procurement Channel Development | Community resilience programs in hurricane-prone Gulf Coast counties create institutional revenue stability. |
| Thermal Engineering Talent Acquisition | Domestic workforce gaps in polymer chemistry constrain product development velocity for rotomolded manufacturers. |
Research Methodology
A standing panel of rotational molding plant managers, polyurethane foam R&D directors, outdoor specialty retail buyers, and FEMA procurement coordinators provided ongoing calibration across primary interview cycles. Secondary validation drew from US EPA SNAP program filings, ECHA REACH substance registrations, customs trade data on insulated container imports, and SEC 10-K disclosures from publicly traded manufacturers. Bottom-up demand modeling triangulated against top-down market sizing from petrochemical feedstock consumption patterns.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, material construction, capacity band, end-user archetype, and regional climatic zone. CAGRs derived from fitted growth curves incorporating replacement cycle frequency, regulatory compliance cost pass-through, and channel mix evolution. Industry-specific inputs encompassed UV degradation rates by geographic exposure and foam thermal conductivity coefficients under reformulated blowing agents.
Forecasts assume regulatory continuity in US EPA SNAP implementation and ECHA REACH chemical disclosure regimes; material policy shifts would require re-modeling of manufacturing cost structures and competitive positioning. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Camping Equipment Market
Outdoor Gear
Trail Running Bags Market
Outdoor Gear
Hiking Backpack Water Filters Market
Outdoor Gear
Sleeping Bag Market
Outdoor Gear
Camping Equipment and Furniture Market
Outdoor Gear
Deer Hunting Blinds Market
Outdoor Gear
Japan Camping Tent Market
Outdoor Gear
Rechargeable Camping Gear Market
Outdoor Gear
Snow Chain Market
Outdoor Gear
Singapore Camping Equipment Market
Outdoor Gear
Fairway Mowers Market
Outdoor Gear
Camp Fire Tripod Market
Outdoor Gear
Shoulder Strap Insulated Cooler Market
Outdoor Gear
Bicycle Bags and Bag Packs Market
Outdoor Gear
Hunting Boots Market
Outdoor Gear
Diving Equipment Market