
 Bicycle Bags and Bag Packs Market | 2026-2036
Bicycle Bags and Bag Packs Market Size, Share, and Industry Trends Forecast 2026-2036
Bicycle Bags and Bag Packs Market Outlook
Waterproof membrane lamination is reshaping how bicycle bags achieve weather protection without weight penalties. Thule Group leverages its automotive cargo heritage to anchor premium rack-mounted systems across European retail channels. Specialized Bicycle Components competes through integrated frame bag geometries tailored to its own bike platforms. Ortlieb Sportartikel GmbH dominates welded-seam construction, sustaining its position in long-distance touring.
Bicycle bags and bag packs comprise purpose-built cargo systems constructed from coated textiles, thermoplastic films, and structural foams, designed to attach to frames, handlebars, seats, or racks while maintaining stability during pedaling motion. Nylon and polyester substrates with polyurethane or thermoplastic polyurethane coatings provide tear resistance below 200 grams per square meter, meeting the primary purpose of protecting gear from precipitation and road spray during transit. Panniers and frame bags lead volume due to commuter reliance on rack-mounted stability, while waterproof fabric variants capture margin pools through material differentiation. Backpacks represent the fastest-growing configuration as e-bike commuters seek off-bike portability without rack dependency.
EU REACH restrictions on perfluorinated compounds constrain waterproof coating formulations, pushing manufacturers toward silicone-based alternatives. Germany's KBA and France's ANSM influence product safety testing protocols for load-bearing straps and reflective elements. China's GB standards and SAMR oversight govern export certification for textile components. Stakeholders must monitor evolving chemical compliance timelines and decide between reformulating existing lines or accelerating bio-based material partnerships.
Market Dynamics
Waterproof membrane lamination is collapsing the historical trade-off between weather protection and weight penalties, forcing incumbent coating suppliers to reformulate or cede position to silicone-based alternatives.
Growth Catalysts
- E-bike commuter expansion:Battery-assisted pedaling extends trip distances beyond traditional cycling ranges, creating sustained demand for rack-independent cargo solutions across Copenhagen, Amsterdam, and Tokyo.
- EU REACH chemical standards:Perfluorinated compound restrictions accelerate material innovation, rewarding early movers in silicone-based waterproofing with regulatory headroom unavailable to legacy coating portfolios.
- Urban cycling infrastructure:Dedicated lane construction in German, Dutch, and Japanese cities normalizes bicycle-dependent commuting, anchoring pannier and frame bag volume through daily-use reliability requirements.
Market Restraints
- TPU film supply concentration:Thermoplastic polyurethane substrate production clusters in China's Yangtze River Delta, exposing European and North American assemblers to freight cost volatility and customs processing delays.
- Welded-seam equipment capex:Radio-frequency welding machinery for waterproof construction requires six-figure capital commitments, constraining mid-tier manufacturers to stitched-seam alternatives with inferior moisture ingress performance.
- Polyester feedstock price linkage:Crude oil derivative exposure in synthetic textile substrates transmits petrochemical volatility directly into bill-of-materials costs without hedging mechanisms at smaller production scales.
Strategic Opportunities
- Indian urban mobility:Metro rail integration with last-mile cycling in Bangalore, Delhi, and Mumbai remains underpenetrated by purpose-built bag systems, presenting first-mover positioning before infrastructure maturation.
- Modular attachment standards:Convergence between quick-release rack systems and handlebar mounting interfaces enables cross-platform compatibility, reducing consumer lock-in and expanding addressable market for accessory specialists.
- Reflective element mandates:France's ANSM and Germany's KBA testing protocols for visibility accessories create regulatory tailwinds for integrated lighting-compatible bag designs in touring and commuter segments.
Industry Challenges
- RF welding technician scarcity:Skilled operators capable of thermoplastic seam construction command premium wages in Germany and the Netherlands, constraining production scaling for waterproof bag specialists.
- Dual certification timelines:Simultaneous EU REACH chemical compliance and China's GB textile export certification require parallel documentation tracks, extending product launch cycles by four to six months.
- Legacy inventory stranding:Existing perfluorinated coating stocks face accelerated obsolescence under tightening chemical regulations, forcing write-downs or discounted channel clearance.
Report Scope
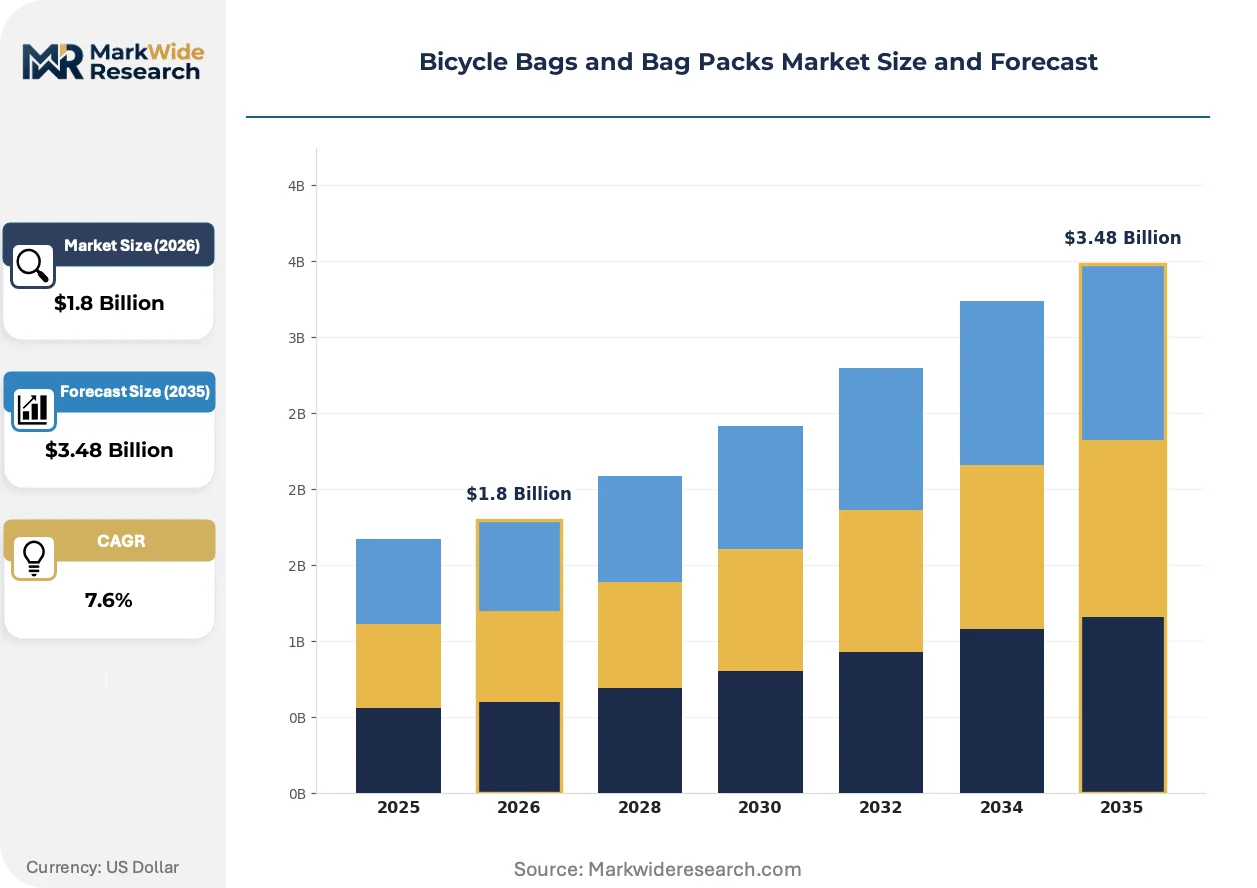
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bicycle Bags and Bag Packs Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frame Bags, Panniers, Backpacks, Handlebar Bags Material: Nylon, Polyester, Canvas, Waterproof Fabric Usage: Commuting, Touring, Mountain Biking, Recreational Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Thule Group, Trek Bicycle Corporation, Specialized Bicycle Components, Ortlieb Sportartikel GmbH, Deuter Sport GmbH, Giant Manufacturing Co., Osprey Packs, Topeak, Merida Industry Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bicycle Bags and Bag Packs Market Strategic Shifts
Material science breakthroughs and regulatory chemistry constraints are compressing traditional competitive advantages in weatherproofing, while urban infrastructure investments reshape where and how cargo systems attach to bicycles.
Silicone-based membrane lamination is collapsing the performance hierarchy between premium welded-seam construction and mid-tier coated fabrics. E-bike commuters in Tokyo and Amsterdam adopt these lighter alternatives for daily 15-30 kilometer trips, eroding the historical justification for heavy-duty touring-grade protection in urban use cases. The weight reduction enables frame bag geometries previously impractical for carbon fiber road bikes.
EU REACH perfluorinated compound restrictions force reformulation across European supply chains. Manufacturers dependent on legacy C6 and C8 chemistry face ingredient substitution costs while silicone and hydrocarbon alternatives achieve comparable hydrostatic head ratings at 15-20% material cost premiums. German touring specialists and Danish commuter brands confront the tightest compliance deadlines, accelerating partnerships with bio-based coating developers.
Direct-to-consumer channel expansion disrupts traditional bicycle retail distribution for accessory procurement. Urban cyclists in Copenhagen and Berlin research waterproof ratings and attachment compatibility through manufacturer websites before purchase, reducing shop floor consultation dependence. This compresses wholesale margin pools while rewarding brands with searchable technical documentation and modular fitment guides.
Bicycle Bags and Bag Packs Market Segmentation
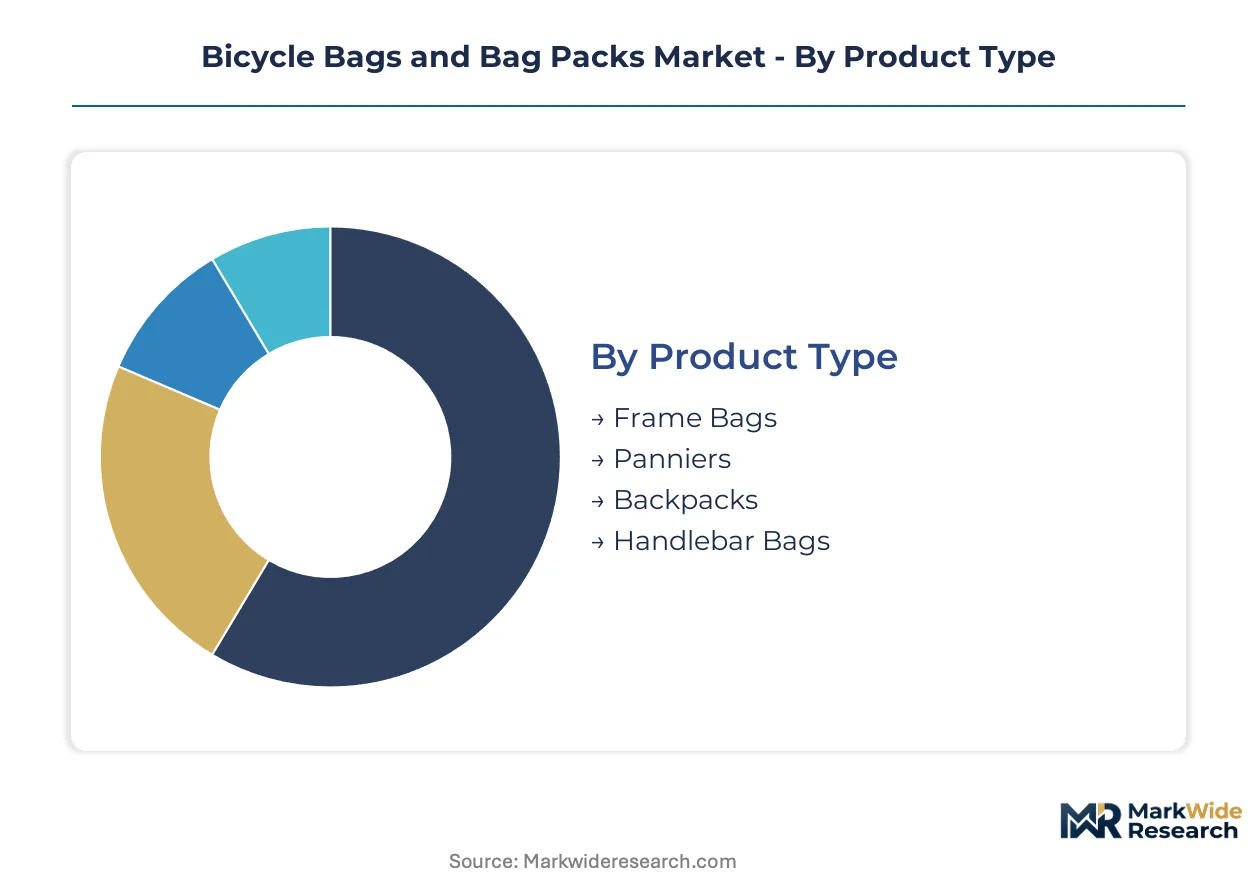
Segmentation in bicycle bags reveals how usage intensity and environmental exposure dictate material specifications and attachment geometries. Product configuration and capacity tiering determine manufacturing complexity, while material selection governs regulatory compliance pathways across EU REACH and China's GB standards.
Product Type:
Cost tier stratification separates rack-dependent systems from portable alternatives, with attachment hardware driving price positioning across commuter and touring applications.
- Panniers:Dual-sided rack-mounted containers constructed from coated textiles with reinforced back panels and quick-release mounting hardware. Demand concentrates in Amsterdam and Copenhagen where dedicated cycling lanes support daily-loaded cargo stability. Rack compatibility standards vary between European and Asian bicycle manufacturers, fragmenting attachment system design.
- Backpacks:Ergonomic shoulder-strap configurations with ventilated back panels and stabilized load distribution for off-bike portability. E-bike commuters in Tokyo and Berlin adopt these for multimodal journeys combining cycling with rail transit, eliminating rack dependency. Weight distribution engineering must accommodate battery-assisted speeds without compromising pedaling biomechanics.
- Frame Bags:Triangular or rectangular geometries fitting within bicycle main frames, constructed from lightweight nylon with minimal seam count. Demand centers on gravel and endurance road cyclists seeking tool and nutrition storage without aerodynamic penalty.
- Handlebar Bags:Cylindrical or wedge-shaped front-mounted systems with map/document compartments and quick-access closures. Touring cyclists in Germany favor these for navigation device visibility and immediate-access storage.
Panniers command the established base. The steepest expansion runs through Backpacks.
Material:
Application severity determines substrate selection, with chemical compliance timelines now constraining traditional waterproof coating formulations.
- Waterproof Fabric:Laminated membrane constructions achieving hydrostatic head ratings above 10,000mm through thermoplastic polyurethane or silicone-based coatings without seam stitching. Long-distance touring specialists in Germany and the Netherlands specify these for multi-day weather exposure. EU REACH perfluorinated compound restrictions accelerate migration toward silicone alternatives at 15-20% material cost premiums.
- Nylon:Polyamide substrates with polyurethane coatings providing tear resistance below 200 grams per square meter and abrasion resilience for frame bag applications. Chinese manufacturing clusters in the Yangtze River Delta dominate substrate supply, exposing European assemblers to freight volatility.
- Polyester:PET-based textiles with lower moisture absorption than nylon, preferred for pannier construction where dimensional stability under load matters. Crude oil derivative exposure transmits petrochemical price volatility directly into production economics.
- Canvas:Heavy cotton duck or synthetic blends with waxed or PVC treatments for aesthetic-driven urban commuter segments. Limited weather performance restricts adoption to fair-weather cycling markets.
Waterproof Fabric captures premium positioning. Nylon dominates volume throughput.
Usage:
Customer type differentiation separates daily utility cycling from episodic recreational activity, with equipment durability specifications scaling accordingly.
- Commuting:Daily urban transit applications requiring weather reliability, theft-deterrent mounting, and reflective visibility integration. Infrastructure expansion in Copenhagen, Amsterdam, and Tokyo normalizes bicycle-dependent transport, anchoring pannier and frame bag volume through reliability requirements.
- Touring:Multi-day or expedition cycling demanding maximum cargo capacity, waterproof integrity, and repairability in remote conditions. German and Dutch cyclists drive specifications for welded-seam construction and modular attachment systems.
- Mountain Biking:Technical off-road applications prioritizing secure retention during vibration and impact, with minimal frame contact to prevent damage. Hydration integration and tool organization dominate design priorities.
- Recreational:Episodic fair-weather cycling with lower durability requirements and greater price sensitivity. Weekend cyclists in urban parks and rail-trail networks populate this segment.
Commuting anchors current volume. Touring sustains margin concentration.
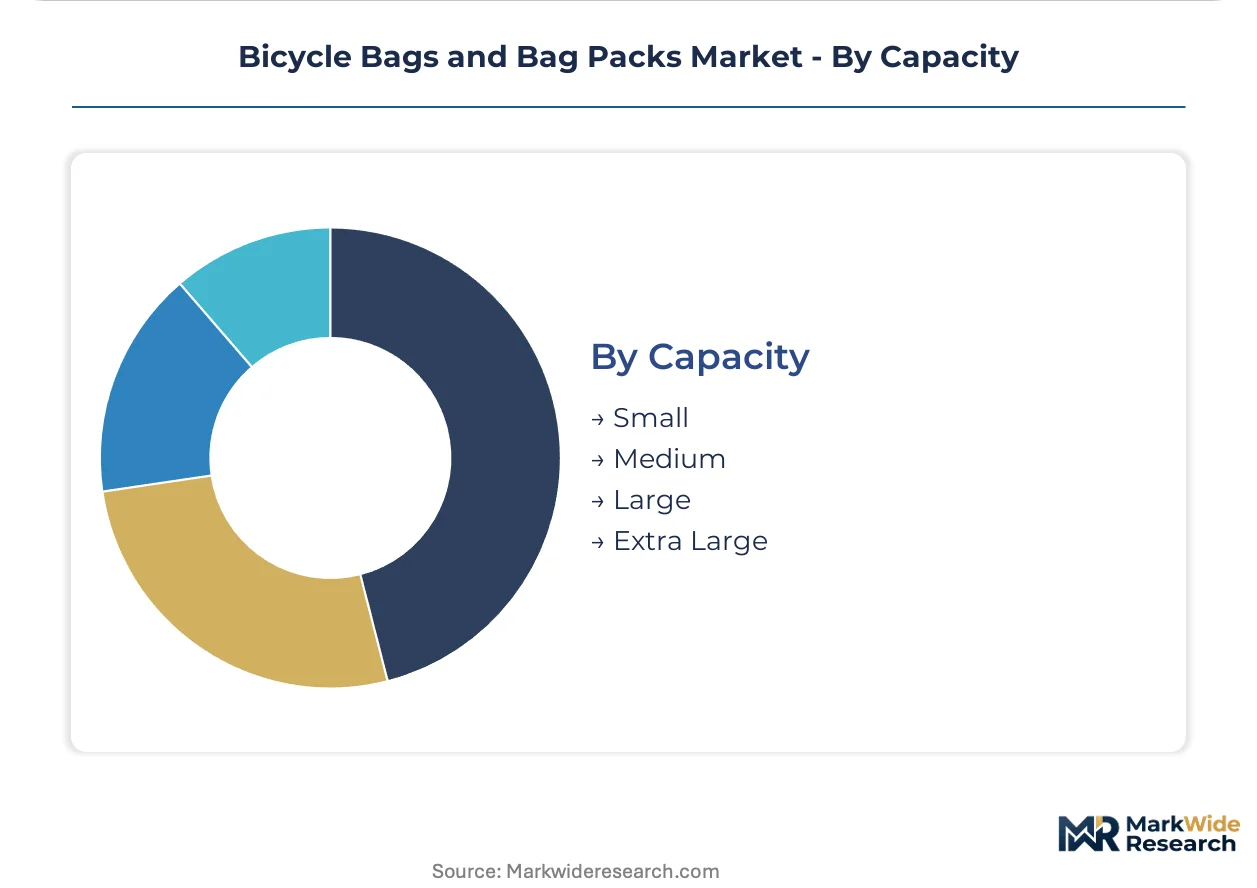
Capacity:
Volume tiering aligns with trip duration and load-bearing frame compatibility, with geometry constraints limiting large-format options on specific bicycle categories.
- Large:Systems exceeding 20 liters per unit or 40 liters combined, designed for touring pannier sets and extended commuting with laptop and clothing storage. Frame geometry and rack load limits restrict compatibility to steel and aluminum touring bicycles.
- Medium:10-20 liter configurations balancing daily utility with weight minimization, dominant in frame bags and compact panniers. Carbon fiber road bike compatibility drives demand as frame bag geometries proliferate.
- Small:Under 10 liter systems for tools, spare tubes, and nutrition, standard on performance-oriented bicycles where minimalism prevails. Handlebar and top-tube mounting predominate.
- Extra Large:Specialized expedition configurations exceeding 25 liters per bag for self-supported touring, requiring reinforced racks and frame strength validation.
Medium capacity holds the volume center. Large formats gain share fastest in e-bike applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export certification complexity and import duty structures vary sharply across manufacturing and consumption hubs, creating divergent market access conditions for bicycle bag producers. China dominates substrate supply while European assemblers navigate REACH compliance timelines. North American demand concentrates in urban commuter corridors with expanding cycling infrastructure.
Germany
Long-distance touring cyclists in Bavaria and Baden-Württemberg sustain premium demand for welded-seam waterproof construction. Germany's KBA mandates rigorous load-bearing strap testing, elevating compliance costs for imported systems. Stuttgart and Munich anchor specialized retail networks where technical consultation drives purchasing decisions for expedition-grade equipment.
China
Yangtze River Delta manufacturing clusters supply TPU films and coated nylon substrates to global assemblers, though SAMR export certification under GB standards creates documentation bottlenecks. Shanghai and Suzhou concentrate radio-frequency welding equipment production, constraining capacity expansion for waterproof bag specialists. Domestic e-bike commuter adoption in Hangzhou and Chengdu stimulates local frame bag demand.
United States
Pacific Northwest and Northeast urban corridors drive backpack configuration growth among multimodal commuters combining cycling with rail transit. EPA chemical oversight influences coating ingredient transparency requirements for imported textile products. Seattle and Portland municipal cycling investments normalize daily bicycle-dependent transport, anchoring rack-independent cargo system volume.
Netherlands
Amsterdam and Utrecht cycling infrastructure density sustains pannier demand for daily-loaded urban transit applications. EU REACH perfluorinated compound restrictions impose the tightest compliance deadlines on Dutch commuter brands, accelerating silicone-based membrane adoption. Randstad manufacturing retains limited final assembly capacity despite raw material import dependence.
Japan
Tokyo and Osaka e-bike commuters adopt lightweight frame bags for 15-30 kilometer daily trips, prioritizing weight minimization over heavy-duty weather protection. METI industrial standards govern textile product safety certification, creating parallel documentation tracks for European exporters. Kansai region distributors specialize in compact geometries compatible with carbon fiber road bike platforms.
Bicycle Bags and Bag Packs Market Competitive Environment
On the supply side, the industry is bifurcated between premium welded-seam specialists and volume-oriented coated-fabric assemblers, with mid-tier players squeezed by capital equipment requirements and chemical reformulation costs. Three archetypes dominate: automotive-heritage cargo brands leveraging distribution scale, bicycle OEMs integrating proprietary bag geometries, and dedicated outdoor specialists commanding technical credibility. Competitive moves center on backward integration into membrane lamination capacity and accelerated bio-based coating partnerships to secure regulatory headroom.
Within the premium welded-seam tier, Ortlieb Sportartikel GmbH exemplifies technical specialization anchored in German manufacturing heritage, while Thule Group occupies a position translating automotive cargo systems expertise into bicycle rack-mounted applications. Specialized Bicycle Components sits within the bicycle OEM-integrated archetype, representing platform-specific design alignment between bags and frame geometries. These three companies illustrate divergent strategic postures: pure-play technical authority, cross-category brand leverage, and vertical ecosystem control.
| Leading Market Players |
|---|
| Thule Group |
| Trek Bicycle Corporation |
| Specialized Bicycle Components |
| Ortlieb Sportartikel GmbH |
| Deuter Sport GmbH |
| Giant Manufacturing Co. |
| Osprey Packs |
| Topeak |
| Merida Industry Co. |
| Others |
Value Chain & Pricing Dynamics
TPU film supply concentration in China's Yangtze River Delta determines both pricing tier spreads and supply chain shape for European and North American assemblers. Freight cost volatility and customs processing delays compress margins on mid-tier coated fabrics while rewarding premium welded-seam specialists with captive membrane lamination capacity.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Premium welded-seam construction commands price multiples based on hydrostatic head certification and radio-frequency welding equipment amortization. Standard coated fabrics face cost compression from polyester feedstock volatility linked to crude oil derivatives. Economy canvas variants attract the most price-sensitive recreational cyclists in fair-weather markets.
Supply Chain Analysis
Extended payment terms from Yangtze River Delta substrate suppliers strain working capital for European assemblers navigating dual certification timelines. TPU films and coated nylon substrates draw from Shanghai and Suzhou manufacturing clusters. Single-source vulnerability concentrates in radio-frequency welding equipment production. Distribution runs through specialized bicycle retail networks in Germany and the Netherlands alongside direct-to-consumer channels in Copenhagen and Berlin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as e-bike commuter adoption outpaces legacy touring-grade supply capacity, creating niches for lightweight frame bag specialists and silicone-based membrane innovators.
For Market Incumbents: Pre-empt silicone-based coating substitution by securing bio-based material partnerships before EU REACH perfluorinated compound deadlines tighten. Incumbent welded-seam specialists must defend technical authority through backward integration into membrane lamination capacity, denying mid-tier competitors access to comparable hydrostatic head ratings. For New Entrants and Emerging Players: Build out modular attachment standard expertise to exploit cross-platform compatibility demand in Indian urban mobility corridors. Bangalore and Delhi metro-rail integration with last-mile cycling remains underpenetrated by purpose-built bag systems, offering first-mover positioning through quick-release rack system specialization. For Investors and Strategic Acquirers: EU REACH chemical compliance milestones reshape the acquisition landscape toward silicone-based membrane capability and bio-based coating partnerships. Long-term viability favors targets with regulatory headroom and captive lamination capacity. Watch for accelerated obsolescence signals in legacy perfluorinated coating inventories as write-downs pressure distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Lamination | Captive TPU film capacity insulates Ortlieb and Thule from Yangtze River Delta supply volatility. |
| Bio-Based Coating Partnership | Silicone-based alternatives secure EU REACH compliance headroom unavailable to legacy C6 chemistry portfolios. |
| Direct-to-Consumer Channel Expansion | Searchable technical documentation reduces Copenhagen and Berlin shop floor consultation dependence. |
| Modular Attachment Standard Adoption | Quick-release rack convergence expands addressable market for cross-platform accessory specialists. |
| Indian Urban Mobility Entry | Bangalore and Delhi metro-cycling integration offers first-mover positioning before infrastructure maturation. |
Study Parameters
Operator-level perspectives from product managers at Thule Group and Ortlieb Sportartikel GmbH, procurement leads at Yangtze River Delta substrate suppliers, and category buyers at German specialized retail networks anchored the qualitative base. Secondary validation drew from EU REACH regulatory filings, China's GB textile standards documentation, and customs trade data for TPU film imports. Bottom-up demand modeling triangulated against top-down market sizing across waterproof fabric, nylon, polyester, and canvas material tiers.
Scenario-bracketing framed volume and value outputs across the projection horizon by product type, material compliance pathway, usage intensity, and capacity tier. Segmentation dimensions modeled included pannier, backpack, frame bag, and handlebar bag configurations alongside commuter, touring, mountain biking, and recreational applications. CAGRs derived from trend extrapolation of e-bike adoption curves and cycling infrastructure investment pipelines in Copenhagen, Amsterdam, Tokyo, and Berlin.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese membrane lamination entrants or accelerated EU REACH enforcement would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
US Backpacks Market
Outdoor Gear
China Camping Equipment Market
Outdoor Gear
Cordless Garden Equipment Market
Outdoor Gear
Diving Regulator Market
Outdoor Gear
Crash Pads Market
Outdoor Gear
North America and Europe Leaf Blower Market
Outdoor Gear
Shoulder Strap Insulated Cooler Market
Outdoor Gear
Outdoor Hot Tub Market
Outdoor Gear
Picnic Coolers Market
Outdoor Gear
Australia Camping Equipment Market
Outdoor Gear
Ice Axe Market
Outdoor Gear
Campsite Cooking Gears Market
Outdoor Gear
New Zealand Camping Equipment Market
Outdoor Gear
Japan Camping Tent Market
Outdoor Gear
Rain Boots Market
Outdoor Gear
Diving Equipment Market