
 North America and Europe Leaf Blower Market | 2026-2036
North America and Europe Leaf Blower Market Size, Share, and Industry Trends Forecast 2026-2036
North America and Europe Leaf Blower Market Analysis
Battery-electric motor architecture is rewriting product development priorities across the leaf blower industry. STIHL leverages its captive battery platform to anchor professional-grade cordless lines in European markets. Husqvarna Group competes through integrated connectivity features that extend fleet management tools to landscaping contractors. Stanley Black & Decker positions its cordless portfolio toward residential homeowners seeking interchangeable power tool batteries.
North America and Europe leaf blowers are air-moving machines designed to displace debris through directed airflow, typically generating velocities from 120 to 250 miles per hour via centrifugal or axial fan impellers, and serve grounds maintenance across residential lawns, commercial properties, and municipal spaces. Electric battery power sources now lead unit growth as lithium-ion energy density improvements enable runtime parity with gasoline equivalents for mid-duty cycles. Handheld configurations dominate residential volume while backpack models retain margin concentration in commercial landscaping where operator endurance determines productivity.
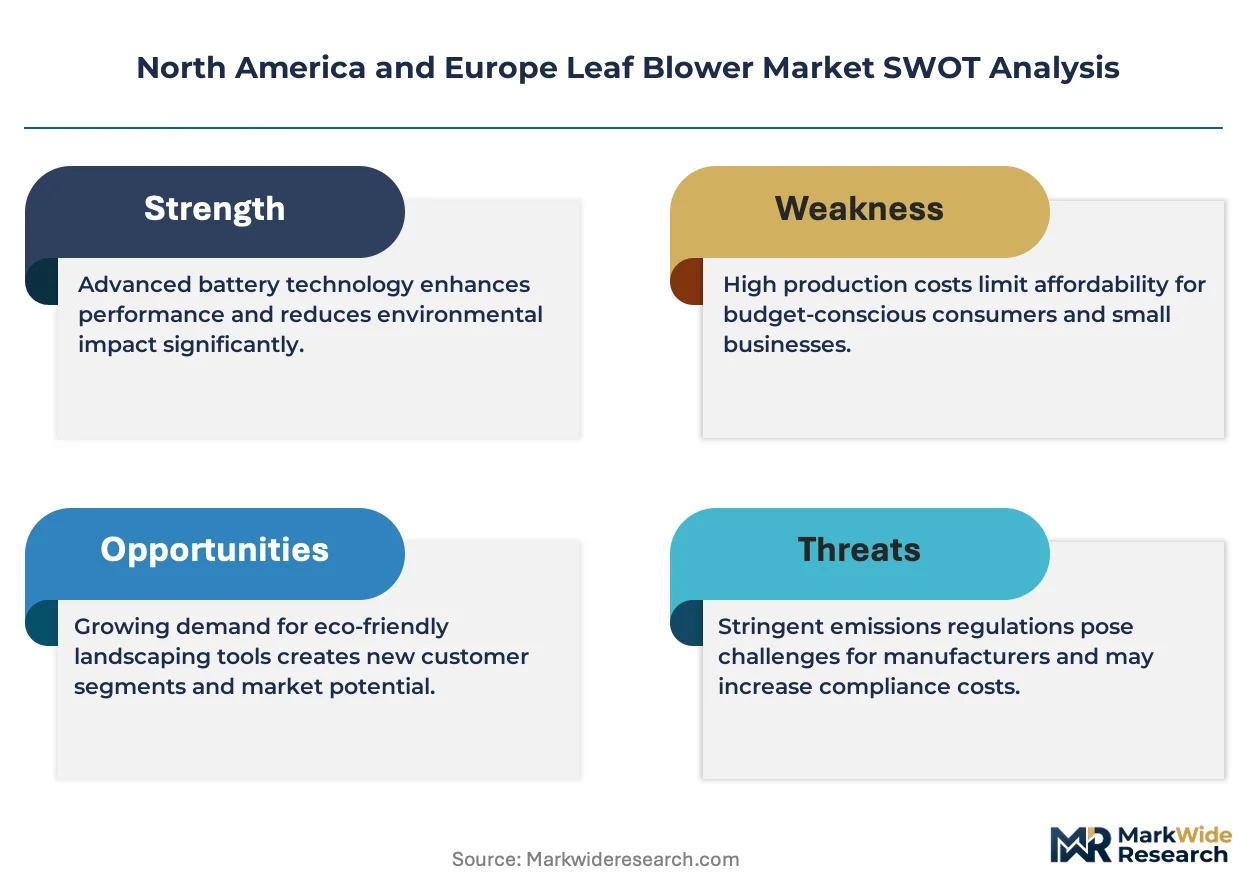
EPA emissions certification requirements and the EU F-Gas Regulation jointly constrain gasoline-powered product introductions across both regions, compelling manufacturers to redirect R&D toward zero-emission architectures. The California Air Resources Board enacts the most stringent small-engine standards in North America, creating a de facto product gate for national distribution decisions. Stakeholders must monitor battery supply chain localization policies and evolving decibel ordinances in metropolitan jurisdictions to anticipate platform investment timing.
Market Dynamics
EPA emissions certification and the EU F-Gas Regulation are compressing gasoline-powered product lifecycles while lithium-ion energy density improvements accelerate battery-electric substitution in professional landscaping fleets.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for hydrofluorocarbon refrigerants in small engines are forcing manufacturers to abandon combustion architectures entirely.
- Suburban municipal procurement:Landscaping contractors across Germany and the United States now mandate battery-electric platforms in fleet replacement cycles.
- Lithium-ion energy density:Cell chemistry improvements have delivered runtime parity with gasoline equivalents for mid-duty clearing cycles.
Market Restraints
- Cobalt and lithium price volatility:Battery raw material cost swings compress margin structures for cordless platform manufacturers.
- Decibel ordinance fragmentation:Metropolitan jurisdictions in California, New York, and Bavaria impose conflicting noise limits that complicate product standardization.
- Gasoline equipment residual value:Secondary market liquidity for combustion-engine blowers is collapsing ahead of regulatory deadlines.
Strategic Opportunities
- Interchangeable battery ecosystems:Residential homeowners in the United States are consolidating around power tool platforms that span drills, saws, and outdoor equipment.
- France and Netherlands municipal electrification:Urban green space maintenance contracts are specifying zero-emission equipment mandates.
- Brushless motor convergence:Integration of sensorless control algorithms with high-torque density designs is opening professional-grade performance tiers.
Industry Challenges
- Technician skill transition:Commercial landscaping operations lack electrical diagnostics training for battery pack servicing and motor controller troubleshooting.
- Certification timeline compression:EPA and CARB certification windows for new gasoline products are narrowing faster than R&D cycles can accommodate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America and Europe Leaf Blower Market |
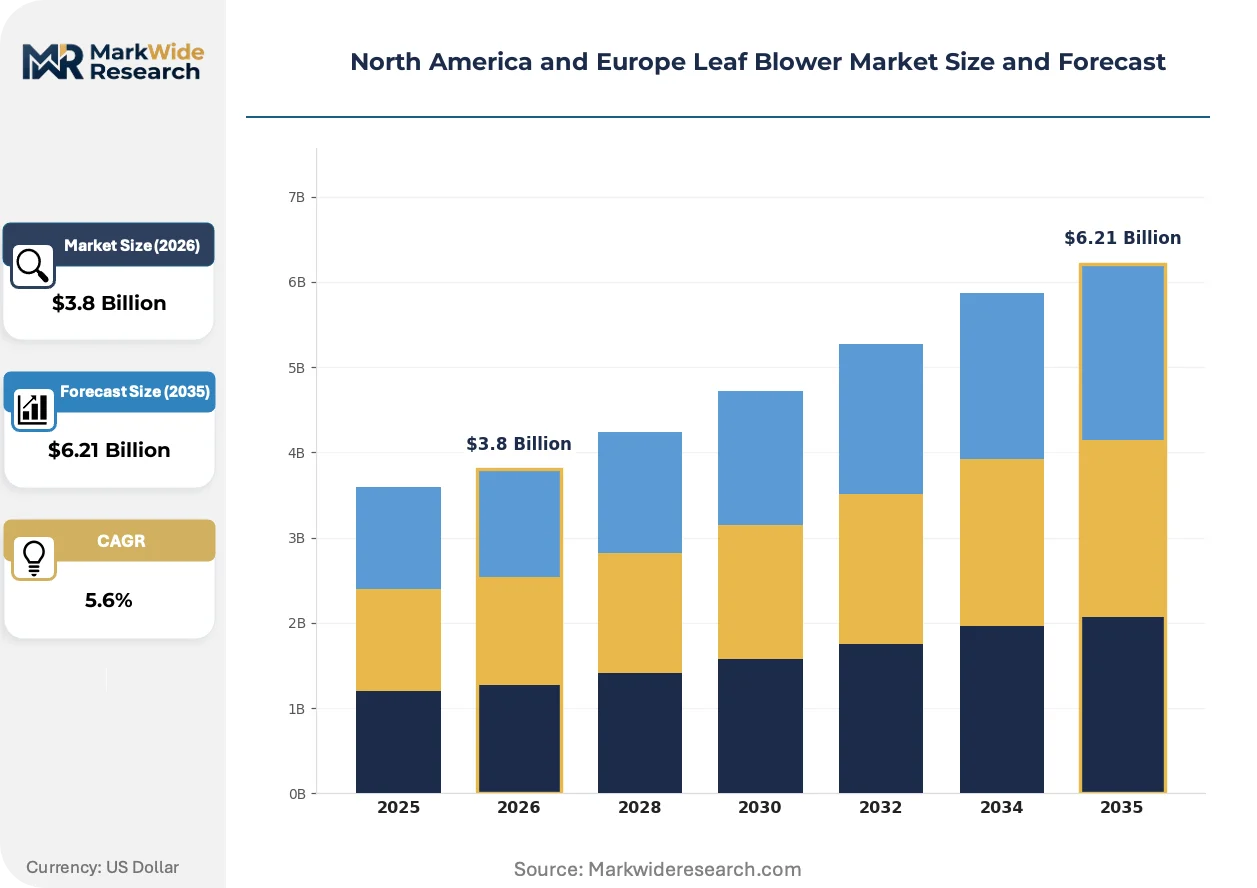
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Backpack, Walk-behind, Robotic Power Source: Gasoline, Electric Corded, Electric Battery, Hybrid Application: Residential, Commercial, Industrial, Agricultural End User: Homeowners, Landscaping Companies, Municipalities, Contractors |
| Companies Covered | Husqvarna Group, STIHL, Stanley Black & Decker, The Toro Company, Robert Bosch GmbH, Honda, ECHO, Makita Corporation, Emak S.p.A, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America and Europe Leaf Blower Market Emerging Trajectories
Product architecture is pivoting from engine displacement metrics to watt-hour capacity ratings as the primary performance differentiator. Manufacturers are embedding connectivity modules and fleet telemetry to capture recurring software revenue from hardware platforms.
Brushless DC motor architectures paired with silicon carbide power electronics are rendering obsolete brushed motor designs and mechanical speed governors in mid-duty equipment. Landscaping contractors in Germany are specifying these platforms for noise-sensitive commercial properties. The shift eliminates carbon brush maintenance intervals and enables precise airflow modulation through firmware.
The California Air Resources Board's small off-road engine standards are prohibiting new gasoline-powered product introductions after 2024. Equipment distributors are liquidating combustion inventory ahead of enforcement deadlines. Manufacturers are redirecting California-bound production entirely to battery-electric SKUs.
Buying patterns among United States landscaping contractors are consolidating around equipment-as-a-service models where battery packs are leased separately from blower hardware. This unbundles capital expenditure and transfers cell degradation risk to manufacturers. Municipal procurement offices in Texas and Florida are piloting these structures for seasonal grounds maintenance.
North America and Europe Leaf Blower Market Segmentation
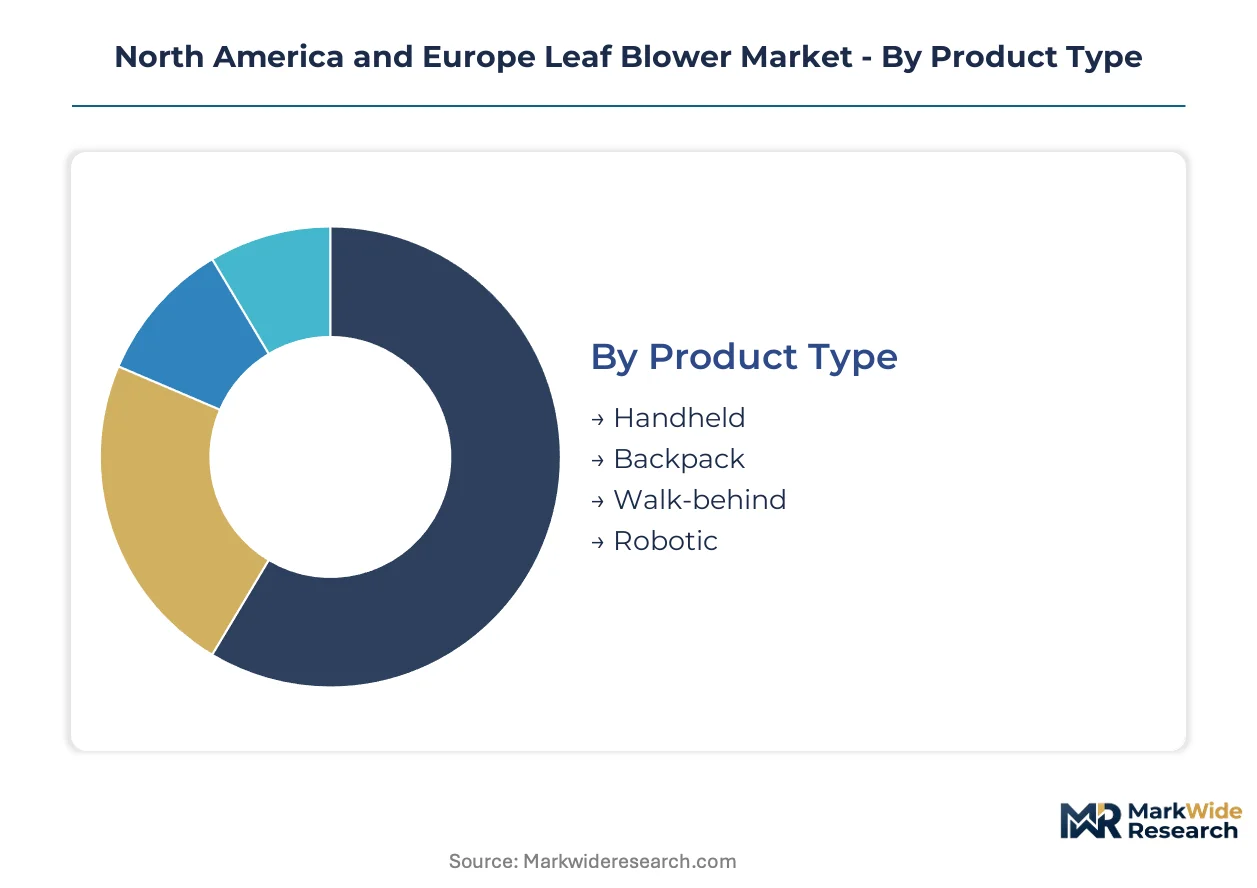
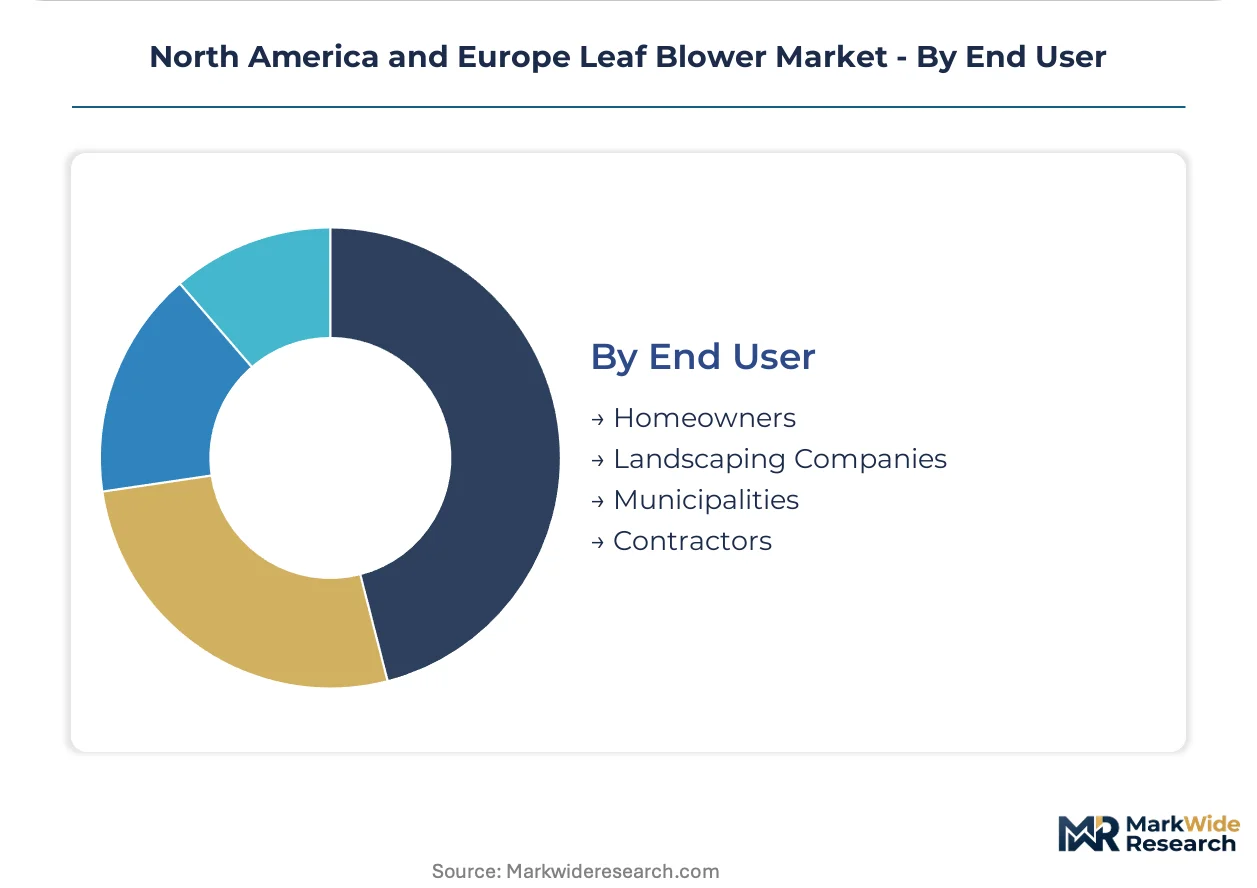
Segmentation in the North America and Europe leaf blower market reveals how regulatory pressure and end-use economics are fragmenting demand across equipment architectures. Procurement patterns diverge sharply between residential homeowners optimizing for interchangeability and commercial operators prioritizing runtime endurance.
Product Type:
Mature configurations dominate current revenue, while emerging robotic platforms are gaining traction in precision maintenance applications.
- Handheld:Compact centrifugal impeller designs generate 120-180 mph airflow velocities through pistol-grip housings optimized for single-hand operation. Residential homeowners in suburban United States municipalities favor these units for driveway and patio clearing where maneuverability outweighs runtime. Lithium-ion pack interchangeability with power tool ecosystems drives replacement cycles.
- Backpack:Axial fan impellers mounted on padded harness frames distribute weight across operator shoulders for sustained 4-6 hour duty cycles. Landscaping companies across Germany specify these for commercial property maintenance where EPA emissions compliance and EU F-Gas Regulation restrictions have eliminated gasoline alternatives. Brushless motor architectures with silicon carbide controllers now match gasoline torque curves.
- Walk-behind:Wheeled chassis configurations with 24-36 inch clearing widths target large-area debris displacement.
- Robotic:Autonomous navigation platforms with perimeter wire or LiDAR boundary mapping are emerging in golf course and campus maintenance contracts.
Handheld configurations retain volume leadership; robotic platforms hold the steepest expansion curve.
Power Source:
Cost tier stratification separates premium battery platforms from economy corded alternatives, with hybrid architectures occupying a narrowing middle ground.
- Gasoline:Two-stroke and four-stroke combustion engines face accelerating phase-out under CARB small off-road engine standards and EU F-Gas Regulation enforcement timelines. Residual demand concentrates in Texas and Florida contractor fleets where seasonal intensity favors energy density over emissions compliance.
- Electric Corded:Tethered AC motor designs deliver continuous runtime without battery degradation concerns. Homeowners in fixed-property suburban settings with accessible outdoor outlets favor these for cost-sensitive replacement purchases.
- Electric Battery:Lithium-ion cell packs with 2.5-12 amp-hour capacities now achieve runtime parity with gasoline equivalents for mid-duty cycles. Cell chemistry improvements in nickel-manganese-cobalt and lithium-iron-phosphate formulations are displacing earlier cobalt-heavy designs.
- Hybrid:Dual-power architectures allowing gasoline generator backup for battery platforms are losing procurement share as pure-electric runtime improves.
Electric battery platforms are climbing the fastest; gasoline systems face steepest contraction.
Application:
Volume concentration follows property scale, while margin distribution favors commercial contracts with fleet standardization requirements.
- Residential:Single-family and multi-family property maintenance drives unit volume through retail and e-commerce channels. Homeowners in the United States prioritize battery platform compatibility with existing power tool investments.
- Commercial:Office parks, retail centers, and hospitality properties demand equipment-as-a-service models with leased battery packs. Municipal procurement offices in France and the Netherlands are mandating zero-emission specifications for green space contracts.
- Industrial:Manufacturing facility grounds and logistics yard maintenance requires heavy-duty debris clearing capacity.
- Agricultural:Orchard and vineyard operations use specialized low-noise configurations for harvest residue management.
Residential applications retain volume leadership; commercial contracts are gaining share fastest.
End User:
Customer type determines procurement channel and service attachment rates, with landscaping companies driving professional-grade specification.
- Homeowners:Individual property owners purchase through home improvement retailers and online marketplaces, favoring interchangeable battery ecosystems.
- Landscaping Companies:Fleet operators across Germany and the United States are consolidating procurement around connectivity-enabled platforms with telemetry-based maintenance scheduling.
- Municipalities:Urban parks departments and highway maintenance divisions specify zero-emission equipment under procurement mandates in California, New York, and Bavaria.
- Contractors:Seasonal and specialty service providers seek flexible leasing structures to match equipment capacity with contract duration.
Landscaping companies retain volume leadership; municipalities are expanding procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export battery-electric platforms to United States landscaping fleets, while California's regulatory stringency creates product specifications that flow eastward across North American distribution channels.
United States
Landscaping contractors in Texas and Florida favor gasoline equipment for seasonal intensity, though California's Air Resources Board mandates zero-emission procurement by 2024. The EPA's small off-road engine standards compress certification timelines nationwide. Equipment distributors in the Southeast liquidate combustion inventory ahead of enforcement deadlines.
Germany
Commercial property maintenance contracts specify brushless motor architectures with silicon carbide controllers for noise-sensitive sites. The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants in small engines, eliminating combustion alternatives entirely. Industrial clusters in Baden-Württemberg concentrate battery pack assembly for professional-grade platforms.
France
Municipal green space contracts in Île-de-France mandate zero-emission equipment for urban parks maintenance. The EU Green Deal accelerates electrification timelines for groundskeeping fleets. Paris metropolitan procurement offices pilot equipment-as-a-service models with leased battery packs.
Canada
Residential homeowners in Ontario and British Columbia prioritize cordless platforms compatible with existing power tool ecosystems. Health Canada's PMRA regulates small-engine emissions in alignment with EPA standards. Vancouver's decibel ordinances restrict gasoline blower operation in dense neighborhoods.
United Kingdom
Landscaping companies in Greater London face ultra-low emission zone constraints on vehicle fleets carrying gasoline equipment. The UK's net-zero procurement guidelines favor battery-electric grounds maintenance tools. Industrial distributors in the Midlands consolidate inventory around interchangeable battery platforms.
North America and Europe Leaf Blower Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic tiers differentiated by battery ecosystem control, connectivity integration, and power tool platform interchangeability. German and Swedish manufacturers anchor the professional-grade segment with captive battery architectures. United States-based conglomerates leverage residential power tool compatibility for homeowner markets. Competitive moves concentrate on fleet telemetry software licensing and backward integration into lithium-ion cell sourcing.
Among the established equipment manufacturers, Husqvarna Group, STIHL, and Stanley Black & Decker occupy distinct positioning vectors. Husqvarna Group exemplifies the connectivity-enabled fleet management archetype. STIHL represents the captive battery platform specialist model with European manufacturing concentration. Stanley Black & Decker anchors the residential interchangeability tier, leveraging power tool battery ecosystems for homeowner penetration. These three entities collectively illustrate how R&D redirection toward zero-emission architectures is fragmenting competitive advantage across battery chemistry, motor control firmware, and distribution channel alignment.
| Leading Market Players |
|---|
| Husqvarna Group |
| STIHL |
| Stanley Black & Decker |
| The Toro Company |
| Robert Bosch GmbH |
| Honda |
| ECHO |
| Makita Corporation |
| Emak S.p.A |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese lithium-ion cell manufacturing is compressing battery pack costs while simultaneously eroding pricing power for European and North American OEMs who lack captive cell production. This utilization asymmetry forces manufacturers to absorb margin compression or accelerate backward integration into cell sourcing.
Pricing Analysis
Next-generation silicon carbide controller architectures command 15-25% price premiums over incumbent brushed motor equivalents, while prior-generation nickel-cadmium battery platforms face accelerated obsolescence discounts. Three-tier pricing structure across premium brushless systems, standard lithium-ion configurations, and economy corded alternatives stratifies the market. Cost compression in battery raw materials is intensifying because cobalt and lithium price volatility feeds through to cell suppliers. Residential homeowners exhibit highest price sensitivity, prioritizing interchangeable battery ecosystem compatibility over performance specifications.
Supply Chain Analysis
Contract manufacturing for motor controllers and battery management systems concentrates in Taiwanese EMS providers and Chinese ODMs serving German and U.S. equipment brands. Cell production draws from South Korean and Chinese suppliers, with pack assembly clustering in Baden-Württemberg and Shenzhen industrial zones. Neodymium magnet sourcing rests on Chinese rare earth processing capacity, creating single-source vulnerability for brushless motor production. Distribution runs through home improvement retail chains, industrial equipment distributors, and direct-to-contractor fleet sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet telemetry software subscriptions and predictive maintenance service contracts are expanding faster than hardware unit sales, transforming capital equipment into recurring revenue platforms. This service-attach dynamic rewards manufacturers who embed connectivity modules at the point of sale.
For Market Incumbents: Insulate professional-grade margin pools by accelerating captive battery platform lock-in among landscaping contractors facing EPA certification timeline compression. Deepen backward integration into lithium-iron-phosphate cell chemistry to offset cobalt price volatility. Prioritize firmware-controlled airflow modulation as a differentiable feature that resists commoditization.
For New Entrants and Emerging Players: Establish a beachhead in robotic autonomous navigation platforms for golf course and campus maintenance contracts where incumbent presence remains limited. Target municipal procurement offices in France and the Netherlands piloting equipment-as-a-service structures. Lead with leased battery pack economics that transfer degradation risk from operators.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across residential cordless platforms as manufacturing scale effects mature and cell chemistry standardizes. Long-term viability favors vertically integrated specialists with captive battery architectures over brand licensors dependent on third-party cell supply. Monitor CARB enforcement actions and EU F-Gas Regulation phase-down schedules as demand inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Battery Platform Expansion | STIHL and Husqvarna Group anchor professional loyalty through proprietary cell architectures incompatible with competitor hardware. |
| Fleet Telemetry Software Licensing | Connectivity modules enable recurring revenue from landscaping contractors seeking predictive maintenance scheduling. |
| Silicon Carbide Controller Integration | Brushless motor architectures with SiC electronics match gasoline torque curves while eliminating carbon brush maintenance. |
| Equipment-as-a-Service Pilot Programs | Municipal procurement offices in Texas and Florida test leased battery structures for seasonal grounds maintenance. |
| Lithium-Iron-Phosphate Chemistry Transition | Cell chemistry improvements displace cobalt-heavy designs, reducing raw material cost volatility exposure. |
Methodological Framework
Initial hypotheses were tested against primary input from landscaping fleet managers, municipal procurement officers, battery pack engineering directors, and industrial equipment distributors, then refined through secondary validation. Primary fieldwork drew from structured interviews across Germany, the United States, France, and Canada. Secondary sources included EPA certification databases, EU F-Gas Regulation implementation timelines, customs trade data for lithium-ion cell imports, and SEC filings from listed equipment manufacturers. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Demand-supply balance modeling anchored volume projections across the analysis window, with segmentation dimensions spanning product type, power source architecture, application intensity, and end-user procurement channel. CAGRs were derived from regression analysis of historical substitution patterns between gasoline and battery-electric platforms, adjusted for regulatory enforcement timelines. Key forecast inputs included CARB small off-road engine standard adoption curves and EU Green Deal procurement mandate penetration rates.
Sensitivities concentrate around battery raw material price spikes, decibel ordinance fragmentation across metropolitan jurisdictions, and technician training bottlenecks for electrical diagnostics. Forecasts embed assumptions regarding lithium-ion energy density improvement trajectories and regulatory enforcement consistency. Quarterly review of CARB certification waiver approvals and EU member state procurement mandate implementation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Japan Camping Equipment Market
Outdoor Gear
North America Robotic Lawn Mower Market
Outdoor Gear
Camp Fire Tripod Market
Outdoor Gear
China Camping Equipment Market
Outdoor Gear
Singapore Camping Equipment Market
Outdoor Gear
Camping Gas Canister Market
Outdoor Gear
Beach Umbrella Market
Outdoor Gear
Australia Camping Equipment Market
Outdoor Gear
Artificial Grass Turf Market
Outdoor Gear
Bicycle Bags and Bag Packs Market
Outdoor Gear
Global Automatic Mower Market
Outdoor Gear
Camping Cooler Market
Outdoor Gear
Campsite Cooking Gears Market
Outdoor Gear
Mexico Camping Equipment Market
Outdoor Gear
Trail Running Bags Market
Outdoor Gear
Cordless Garden Equipment Market