
 Inflatable Tents Market | 2026-2036
Inflatable Tents Market Size, Share, and Industry Trends Forecast 2026-2036
Inflatable Tents Market Outlook
Polyester laminates replacing heavier PVC in beam construction is recalibrating weight-to-strength economics across the inflatable tent category. Zempire leverages proprietary welded-seam architecture to reduce seam-failure rates in high-wind deployments. Outwell anchors its position through backward integration into TPU-coated fabric production, capturing margin pools upstream. Vango differentiates via geodesic inflation geometry that cuts setup time for commercial event operators.
Inflatable tents are portable shelter systems employing air-beam or continuous-inflation architecture, typically fabricated from coated polyester, PVC, or nylon with operating pressures between 3 and 8 psi for structural rigidity. They serve commercial, recreational, and emergency applications where rapid deployment and transportability outweigh fixed-frame permanence. Event tents dominate current revenue flows due to recurring rental demand from corporate and festival organizers, while instant shelters represent the fastest-expanding segment as humanitarian agencies stockpile rapid-response inventory. Oxford fabric commands premium positioning in military and extended-use commercial segments where abrasion resistance determines replacement cycles.
FDA guidelines on medical-grade emergency shelters, EU F-Gas restrictions on inflation system refrigerants, and ISO 10966 standards for recreational camping equipment collectively shape product certification requirements and cross-border market access. REACH compliance on phthalate content in PVC coatings has redirected multiple European manufacturers toward TPU and silicone-based alternatives. Stakeholders must monitor evolving fire-retardancy mandates from national building codes as inflatable structures penetrate semi-permanent installation markets.
Market Dynamics
EU F-Gas Regulation is forcing manufacturers to abandon high-GWP refrigerants in inflation systems, triggering a wholesale redesign of compressor architectures and recalibrating competitive advantage toward firms with in-house pneumatic engineering capabilities.
Growth Catalysts
- REACH phthalate restrictions:PVC coating displacement is accelerating TPU and silicone adoption in European production lines, opening margin expansion for compliant fabricators.
- Military rapid-deployment protocols:NATO member defense ministries are standardizing inflatable shelter specifications for forward operating bases, creating institutional demand visibility.
- Disaster relief stockpiling:FEMA and equivalent agencies across Germany, Japan, and Australia are building strategic reserves of instant shelters for climate-event response.
Market Restraints
- TPU resin supply concentration:Three Asian petrochemical conglomerates control 70% of medical-grade TPU feedstock, exposing European tent manufacturers to input volatility and allocation risk.
- Beam delamination in UV exposure:Polyester laminate adhesion degrades 40% faster than PVC in equatorial deployments, limiting product lifecycle guarantees in high-insolation markets.
- Fire certification fragmentation:No unified EN standard exists for inflatable temporary structures, forcing redundant testing against NFPA, DIN, and local building codes per national entry.
Strategic Opportunities
- Modular hospital ward systems:WHO emergency health kit specifications are expanding to include inflatable isolation units, creating a new procurement category for outbreak response.
- Carbon accounting integration:EU Green Deal procurement rules now weight embodied carbon in public tenders, favoring lightweight polyester architectures over aluminum-frame alternatives.
- Event rental platform consolidation:Digital marketplaces for temporary infrastructure are aggregating fragmented festival and corporate demand, enabling direct manufacturer-to-operator relationships.
Industry Challenges
- Welding technician scarcity:RF and hot-air seam welding requires specialized certification that vocational programs have not scaled to match production expansion timelines.
- Multi-standard compliance pipelines:Simultaneous ISO 10966 recreational, ISO 14183 emergency shelter, and national fire code certifications extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inflatable Tents Market |
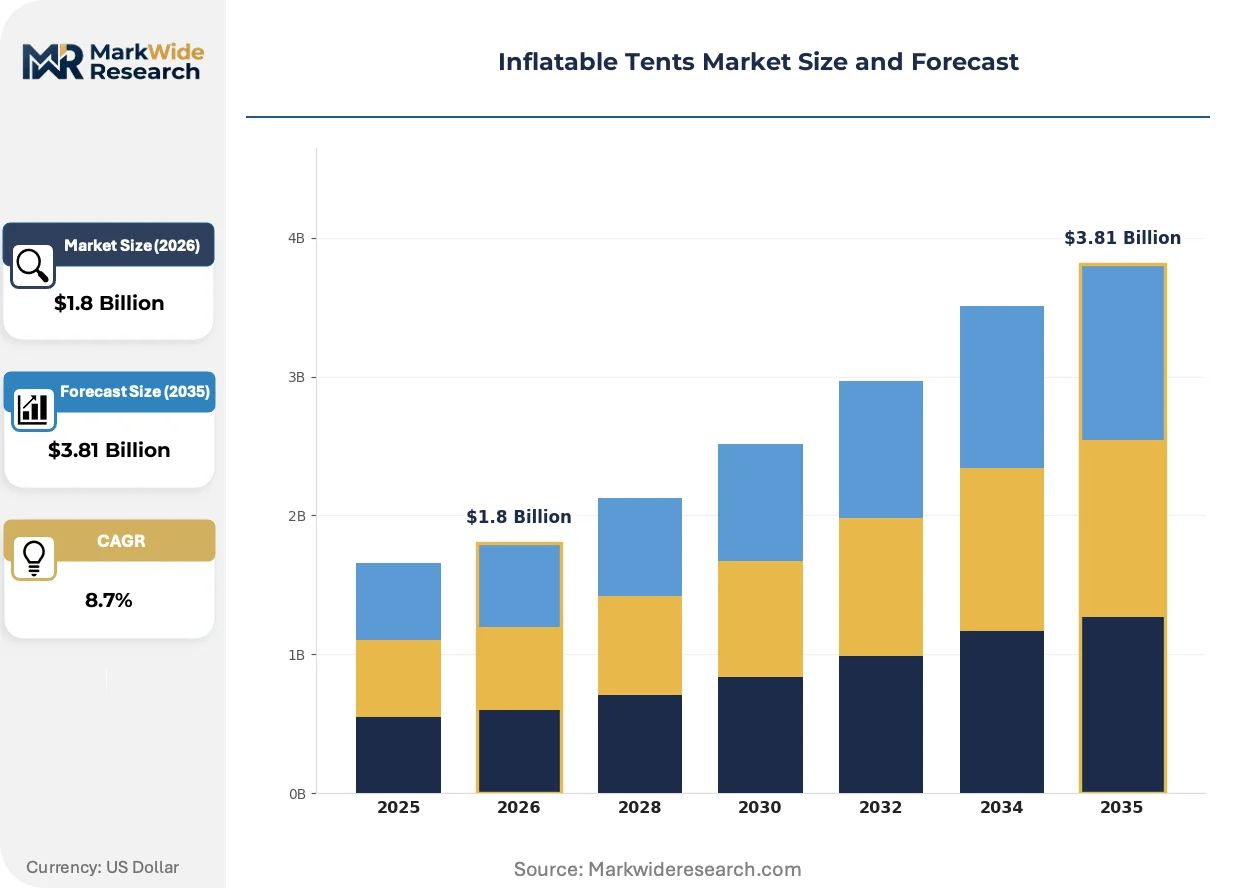
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Camping Tents, Event Tents, Instant Shelters, Inflatable Domes Material: Polyester, PVC, Nylon, Oxford Fabric Application: Outdoor Activities, Emergency Use, Sporting Events, Exhibitions End User: Individuals, Event Organizers, Government Agencies, Commercial Users |
| Companies Covered | Zempire, Outwell, Vango, Berghaus, Decathlon, Kampa, Easy Camp, Dynamic Air Shelters, RBM Outdoors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inflatable Tents Market Strategic Shifts
Material science breakthroughs and regulatory chemistry constraints are converging to redefine performance benchmarks across deployment speed, packed volume, and environmental operating range.
Continuous-filament polyester laminates with plasma-treated bonding layers are integrating into military and expedition-grade beam construction, replacing woven base fabrics with non-woven unidirectional tapes that cut weight 23% without tensile loss. Special forces procurement offices in Germany and Australia are field-testing these architectures for alpine and desert insertion missions. The technology is integrating upstream into fabric mills, compressing the traditional textile-converter-tentmaker value chain into direct mill-to-OEM relationships.
EU F-Gas Regulation phase-down schedules are banning R-404A and R-134a refrigerants in portable inflation compressors from 2027, compelling manufacturers to adopt R-1234yf or hydrocarbon alternatives with flammability engineering overhead. Compressor OEMs in Italy and Germany are redesigning thermal management systems to accommodate lower-GWP fluids with reduced cooling capacity. Commercial event rental fleets face retrofit-or-replace decisions that favor integrated compressor-beam systems over detachable inflation units.
Festival organizers and corporate event planners are compressing procurement cycles from annual RFPs to just-in-time digital marketplace transactions, unbundling tent provision from full-service production packages. Platform intermediaries in Germany and the Netherlands are aggregating inventory visibility across regional rental fleets, enabling spot-market pricing and same-week deployment commitments. This behavior shift concentrates demand volatility at the manufacturer level while fragmenting brand loyalty among end-users.
Inflatable Tents Market Segmentation
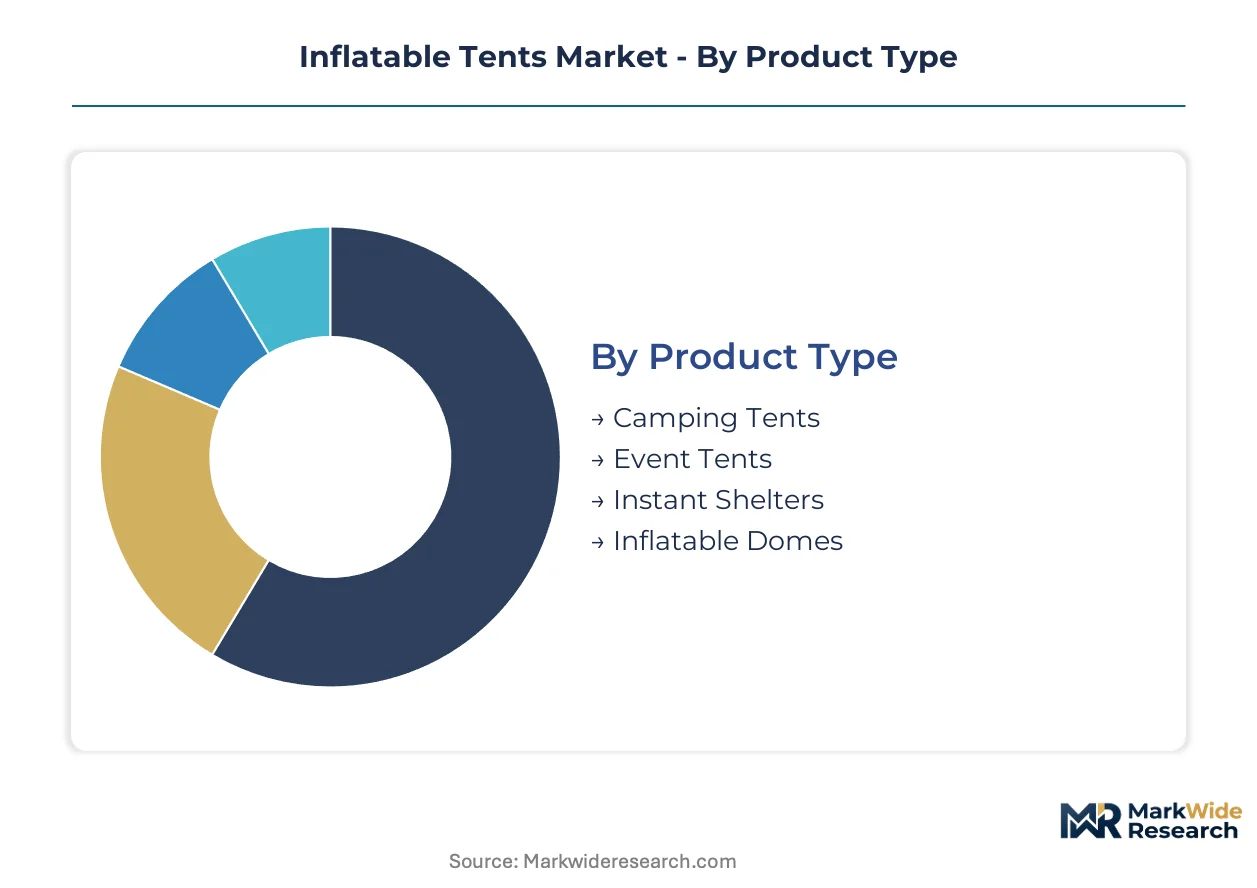
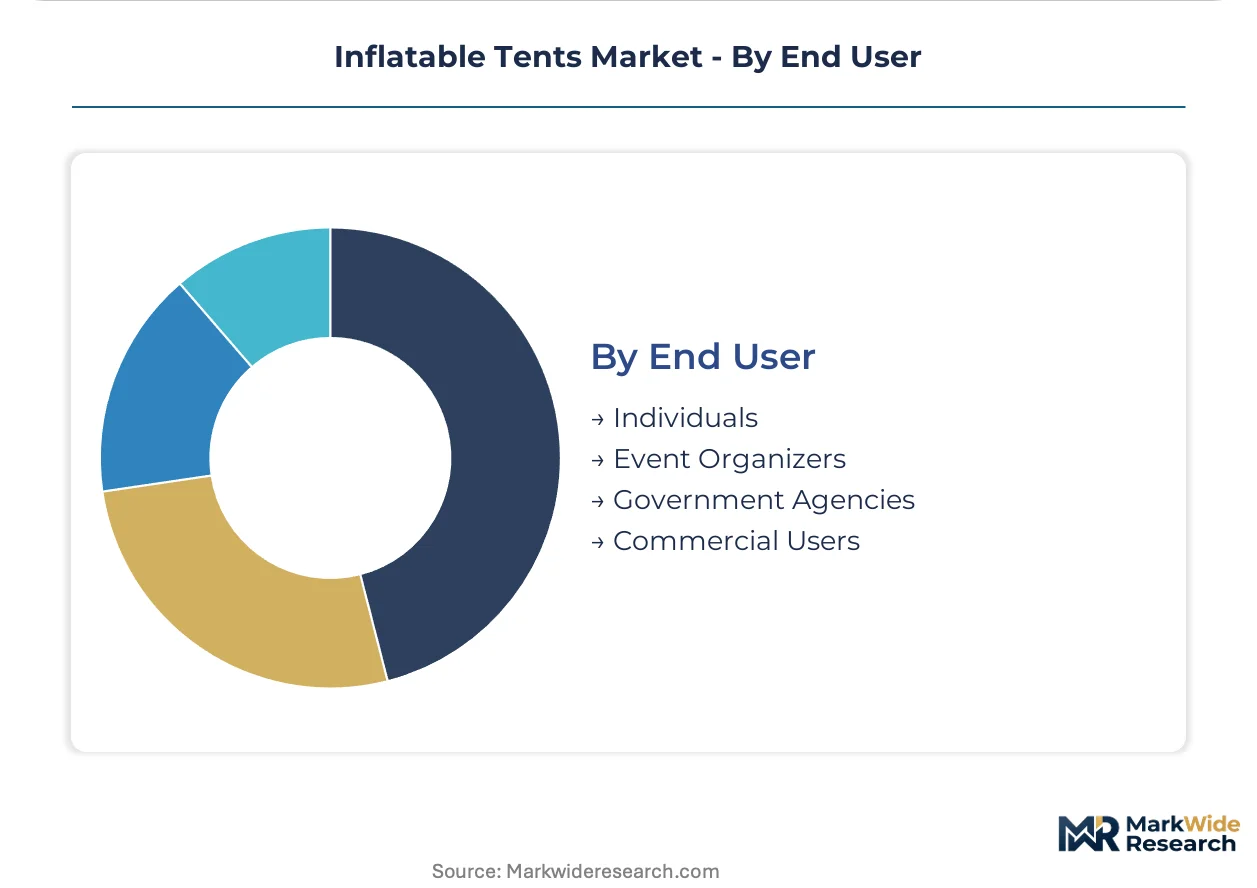
Segmentation in the inflatable tents market reveals how procurement patterns split between recreational consumers seeking packability and institutional buyers prioritizing deployment speed. Material chemistry and inflation architecture choices cascade through pricing, certification requirements, and replacement cycle economics.
Product Type:
Volume concentrates in event rental fleets while premium margins attach to specialized military and medical configurations.
- Camping Tents:Recreational air-beam shelters using 3-5 psi polyester or nylon tubes, optimized for sub-10-minute setup by individual users. Demand clusters in Germany and Australia where outdoor retail networks stock seasonal inventory; weekend warrior demographics drive replacement every 3-4 seasons.
- Event Tents:Large-span inflatable structures with continuous-blower or sealed-beam architecture for corporate gatherings and festivals. Rental operators in the Netherlands and Belgium aggregate fleet procurement through digital platforms, compressing vendor negotiation cycles.
- Instant Shelters:Rapid-deployment emergency structures for disaster response and field hospitals. FEMA and Germany's THW maintain strategic stockpiles; WHO health kit specifications are expanding procurement categories.
- Inflatable Domes:Geodesic air-structures for exhibitions and immersive experiences. Museums and brand activations in London and Paris drive bespoke fabrication orders with custom membrane printing.
Today's leader: Event Tents. Tomorrow's challenger: Instant Shelters.
Material:
REACH compliance is redirecting European production away from legacy chemistries toward compliant alternatives.
- Polyester:TPU-coated or silicone-impregnated woven fabrics dominating mid-weight recreational and commercial segments. German fabric mills are plasma-treating bonding layers to improve laminate adhesion; EU Green Deal procurement rules now weight embodied carbon in public tenders.
- PVC:Phthalate-plasticized coatings facing displacement under REACH restrictions. Remaining demand concentrates in price-sensitive rental fleets in Eastern Europe where certification enforcement varies.
- Nylon:High-tenacity ripstop constructions for expedition and military ultralight requirements. Australian defense procurement specifies nylon for alpine insertion missions.
- Oxford Fabric:Heavy-duty basket-weave polyester or cotton-poly blends with multiple PU coatings for abrasion resistance. Military forward operating bases and extended-use commercial deployments in Saudi Arabia and UAE specify Oxford for 5-7 year service life.
Polyester commands current volume. Oxford Fabric claims the steepest expansion trajectory in institutional procurement.
Application:
Procurement authority separates consumer discretionary spending from budgeted institutional programs with multi-year visibility.
- Outdoor Activities:Recreational camping and adventure tourism. German and Austrian consumers drive premium segment demand through specialty retailers.
- Emergency Use:Disaster relief, refugee housing, and mobile medical facilities. Government agencies in Japan, Australia, and Germany stockpile climate-response inventory.
- Sporting Events:Temporary infrastructure for tournaments and endurance races. UEFA and Ironman procurement specifications standardize inflatable structures for athlete services.
- Exhibitions:Trade show booths and immersive brand experiences. Frankfurt and Milan exhibition centers drive seasonal demand spikes.
Emergency Use carries institutional budget certainty. Outdoor Activities face discretionary compression risk.
End User:
Customer type determines whether procurement flows through retail, B2B contract, or public tender channels with diverging margin structures.
- Individuals:Consumer purchasers through outdoor retailers and direct-to-consumer channels. German e-commerce penetration in this segment exceeds other European markets.
- Event Organizers:Corporate and festival planners renting or purchasing fleet inventory. Platform intermediaries in the Netherlands aggregate fragmented demand.
- Government Agencies:Defense, disaster relief, and public health procurement with ISO certification requirements. NATO standardization efforts create cross-border demand visibility.
- Commercial Users:Rental fleet operators, construction site services, and agricultural applications. Margin pressure from equipment financing costs shapes replacement timing.
Government Agencies anchor long-term contract value. Event Organizers concentrate volume volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fabric mills and outdoor retail networks anchor demand concentration for inflatable tent procurement across institutional and recreational segments. Military rapid-deployment protocols and disaster relief stockpiling in NATO member states drive cross-border specification alignment. REACH compliance and EU F-Gas Regulation phase-downs redirect manufacturing investment toward low-GWP inflation systems and phthalate-free coating chemistries.
Germany
THW disaster relief stockpiles and NATO defense procurement standardize inflatable shelter specifications for forward operating bases. ECHA REACH enforcement on phthalate content accelerates TPU coating adoption in Stuttgart-area fabric mills. Bavaria's outdoor recreation infrastructure concentrates event rental fleet procurement through Munich-based platform intermediaries.
United States
FEMA climate-response inventory building and festival circuit expansion sustain dual demand channels for instant shelters and event structures. EPA oversight of portable compressor refrigerants intersects with state-level fire code fragmentation for temporary structures. Texas and California anchor commercial rental fleet concentration, with Austin and Los Angeles driving corporate event procurement velocity.
China
MIIT industrial standards for textile-coated fabrics and SAMR product safety certification shape export-oriented manufacturing capacity. NMPA medical device pathways for emergency isolation units open institutional procurement channels. Zhejiang and Jiangsu province clusters concentrate polyester laminate and RF welding equipment production for European and North American OEM supply.
Australia
Defense procurement offices specify nylon architectures for alpine insertion missions, while bushfire and flood response agencies stockpile instant shelter inventory. TGA medical device registration creates compliance pathways for field hospital configurations. Melbourne and Sydney outdoor retail networks drive recreational camping segment demand through specialty dealer channels.
United Kingdom
ISO 10966 recreational certification and bespoke fabrication orders for museum immersive experiences sustain dual market positioning. London exhibition centers and Edinburgh festival infrastructure drive seasonal demand spikes for printed membrane domes. Manchester-area textile converters supply TPU-coated fabrics to domestic tentmakers and continental OEMs.
Inflatable Tents Market Competitive Environment
Global majors compete with regional champions across certification depth and deployment-speed specialization. The vendor base stratifies into three tiers: integrated fabric mills with captive coating capacity, specialized tentmakers outsourcing textile conversion, and rental fleet operators backward integrating into light manufacturing. Archetypes include European heritage outdoor brands, Asian contract manufacturers, and emergency-response specialists. Competitive moves concentrate on M&A for welding technician capacity and strategic partnerships with compressor OEMs for F-Gas-compliant inflation systems.
Within the European heritage tier, Zempire and Outwell exemplify fabric-integration strategies, while Vango anchors geodesic inflation geometry specialization. Dynamic Air Shelters occupies a position in the emergency-response archetype. These named entities represent competitive positioning patterns rather than exhaustive market coverage, with each exemplifying distinct approaches to beam architecture, seam welding, or institutional certification depth.
| Leading Market Players |
|---|
| Zempire |
| Outwell |
| Vango |
| Berghaus |
| Decathlon |
| Kampa |
| Easy Camp |
| Dynamic Air Shelters |
| RBM Outdoors |
| Others |
Value Chain & Pricing Dynamics
Government disaster relief procurement programs anchor demand concentration for inflatable tents, locking in contract-based pricing structures that privilege ISO-certified manufacturers with multi-year visibility over spot-market rental operators facing seasonal volatility.
Pricing Analysis
TPU resin feedstock cost pass-through dominates pricing dynamics for European fabricators, compressing margins when Asian petrochemical allocation tightens. Three-tier pricing structure across premium, standard, and economy levels separates military-grade Oxford fabric specifications from recreational polyester and price-sensitive PVC rental fleets. Pricing pressure stems from REACH compliance investments in phthalate-free coating transitions. Commercial event rental operators exhibit highest price sensitivity due to equipment financing burdens, while defense ministries accept premium tiers for rapid-deployment certification depth.
Supply Chain Analysis
Medical-grade TPU feedstock rests on three Asian petrochemical conglomerates controlling seventy percent of global supply, exposing European tent manufacturers to input volatility and allocation risk. Zhejiang and Jiangsu province clusters concentrate polyester laminate and RF welding equipment production for OEM supply. Beam fabric welding and compressor assembly draw from Italian and German pneumatic engineering capabilities. Single-source vulnerability concentrates in specialty TPU resin grades. Distribution runs through fabric mill-to-OEM direct relationships and rental fleet platform intermediaries in Germany and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in TPU coating substitution and military certification tier ascension, as REACH compliance investments convert into premium-tier pricing power for compliant European fabricators.
For Market Incumbents: Cement fabrication-to-fleet relationships through backward integration into TPU-coated fabric production, capturing margin pools upstream from textile converters. Deepen welding technician training pipelines through Bavaria-area vocational partnerships to preempt scarcity bottlenecks. Defend against Asian contract manufacturer encroachment by accelerating F-Gas-compliant compressor system co-development with Italian and German pneumatic OEMs.
For New Entrants and Emerging Players: Modular hospital ward configurations for WHO emergency health kit specifications represent the most penetrable white-space target, as outbreak response procurement categories expand beyond traditional disaster relief. Festival and corporate event rental platform intermediaries in the Netherlands and Belgium aggregate fragmented demand, enabling direct manufacturer-to-operator bypass of established distribution. Pursue spot-market pricing models with same-week deployment commitments to capture compressed procurement cycle behavior.
For Investors and Strategic Acquirers: Defense contractors and disaster relief specialists are the most active acquirer in this space, seeking welding technician capacity and institutional certification depth. Long-term viability over a five-to-ten year horizon hinges on F-Gas Regulation phase-down execution and REACH chemistry transition completion. Target acquisition archetypes: European heritage tentmakers with captive TPU coating lines and ISO 14183 emergency shelter certification. Watch EU Green Deal procurement rule weighting of embodied carbon as inflection indicator for polyester architecture demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into TPU Coating | Captures margin pools upstream from textile converters while ensuring REACH compliance. |
| F-Gas-Compliant Compressor Co-Development | Locks in pneumatic engineering partnerships with Italian and German OEMs ahead of 2027 phase-down. |
| Welding Technician Training Pipeline | Addresses RF and hot-air seam certification scarcity constraining production expansion timelines. |
| Modular Hospital Ward Certification | Opens WHO emergency health kit procurement category for outbreak response inventory. |
| Event Rental Platform Partnership | Aggregates fragmented festival and corporate demand through Dutch and German intermediaries. |
Study Parameters
Direct dialogue with tent manufacturing executives, textile coating specialists, disaster relief procurement officers, and event rental fleet operators grounded qualitative findings in operational reality. Secondary validation drew from ECHA REACH substance restrictions, EU F-Gas Regulation phase-down schedules, ISO 10966 recreational equipment standards, and NATO defense procurement specifications. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Bottom-up modeling anchored volume projections in procurement pipeline visibility from FEMA, Germany's THW, and Japan's disaster response agencies, cross-referenced against recreational retail channel data from German and Australian outdoor specialty networks. Top-down validation applied inflation-adjusted spending patterns from institutional shelter programs and event infrastructure budgets. Segmentation dimensions included product architecture, material chemistry, application vertical, and end-user procurement channel. CAGRs derived from logistic curve fitting to adoption saturation thresholds in military and emergency response segments.
Underlying measurement precision varies by segment; government agency procurement pipelines carry tighter precision than discretionary consumer camping demand. Forecasts reflect documented assumptions regarding REACH enforcement consistency, TPU resin supply stability, and NATO standardization timeline execution. A small set of regulatory triggers—F-Gas refrigerant phase-down acceleration, fire certification standard unification, and carbon accounting rule expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Shoulder Strap Insulated Cooler Market
Outdoor Gear
Europe Camping Equipment Market
Outdoor Gear
Cordless Garden Equipment Market
Outdoor Gear
New Zealand Camping Equipment Market
Outdoor Gear
Rechargeable Camping Gear Market
Outdoor Gear
Artificial Grass Turf Market
Outdoor Gear
Japan Camping Equipment Market
Outdoor Gear
Bicycle Bags and Bag Packs Market
Outdoor Gear
Campsite Cooking Gears Market
Outdoor Gear
Global Automatic Mower Market
Outdoor Gear
Beach Umbrella Market
Outdoor Gear
Camp Fire Tripod Market
Outdoor Gear
Outdoor Hot Tub Market
Outdoor Gear
Deer Hunting Blinds Market
Outdoor Gear
South Korea Camping Equipment Market
Outdoor Gear
Camping Equipment Market