
 North America Pocket Knives Market | 2026-2036
North America Pocket Knives Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pocket Knives Market Insights
Artisanal blade grinding expertise is reorganizing competitive dynamics across the North America pocket knives landscape as master smiths retire faster than apprentices enter the trade. Benchmade leverages its Oregon-based manufacturing scale to sustain domestic production capacity despite labor scarcity. Bark River Knives anchors its position through proprietary convex edge geometry that differentiates its fixed-blade offerings from mass-market alternatives. Montana Knife Company competes by controlling regional sourcing of high-carbon steels from western US forges.
Pocket knives constitute handheld cutting tools with deployable or fixed blades typically measuring under four inches, constructed from alloyed steels heat-treated to RC 58-61 hardness for edge retention and corrosion resistance. Their primary commercial purpose spans utility cutting, emergency preparedness, and recreational tasks across consumer and professional contexts. Folding knives dominate volume flows through outdoor retailers and specialty stores, while titanium-handled variants command premium positioning among everyday carry users seeking reduced pocket weight. Carbon steel blades attract collector attention for patina development and sharpenability, though stainless formulations lead mainstream sales through lower maintenance requirements.
The US Consumer Product Safety Commission and Transport Security Administration jointly shape product design and distribution constraints through blade-length restrictions and carry prohibitions that vary by jurisdiction. Health Canada maintains parallel edge-tool safety standards affecting cross-border shipment compliance for manufacturers serving both markets. Stakeholders must monitor evolving municipal ordinances in major Canadian and US urban centers as blade-carry regulations fragment further.
Market Dynamics
Artisanal blade grinding expertise is vanishing faster than apprentices enter the trade, forcing manufacturers to automate convex edge geometry or lose the premium tier entirely. This talent scarcity compresses margins at the top while mass-market stainless formulations absorb volume growth.
Growth Catalysts
- Pacific Northwest outdoor recreation culture:Washington and Oregon sustain concentrated demand for premium fixed-blade and folding knives through hunting, fishing, and backcountry use cases that resist digital substitution.
- US Consumer Product Safety Commission edge-tool standards:Interstate commerce compliance requirements create barriers that favor established domestic manufacturers with in-house testing laboratories over gray-market imports.
- Titanium handle fabrication:Reduced pocket weight specifications from everyday carry users drive material substitution in the $150-plus price band, expanding addressable premium volume.
Market Restraints
- High-carbon steel price volatility:Regional forges in Montana and Idaho face energy input cost swings that transmit directly to blade blank pricing, compressing gross margins on collector-grade carbon steel models.
- Transport Security Administration carry prohibitions:Blade-length restrictions and air travel bans fragment distribution economics, forcing manufacturers to maintain separate channel strategies for airport-adjacent retail versus general outdoor merchants.
- Master smith retirement velocity:The replacement rate for proprietary convex grinding expertise sits below one apprentice per three retirees, capping scalable premium output regardless of demand signals.
Strategic Opportunities
- Municipal ordinance fragmentation in Canadian urban centers:Toronto and Vancouver blade-carry regulations remain less restrictive than comparable US cities, creating temporary arbitrage windows for cross-border specialty retail expansion.
- Health Canada parallel safety standard harmonization:Aligned edge-tool testing protocols with US CPSC frameworks reduce dual-certification costs for manufacturers serving both markets from single production lines.
- Direct-to-consumer digital channels:Specialty knife forums and maker-owned storefronts bypass traditional outdoor retailer margin stacks, capturing full premium pricing for limited-run artisanal releases.
Industry Challenges
- Convex edge geometry skill transfer:Automated grinding systems cannot replicate hand-finished convex profiles that define collector preference, forcing reliance on aging human capital with no scalable training pipeline.
- Heat-treatment certification timelines:RC 58-61 hardness validation for new steel alloys requires extended third-party metallurgical testing that delays product launches by 8-14 months.
- Cross-border shipment compliance complexity:Divergent municipal blade-carry laws across US states and Canadian provinces force SKU fragmentation and inventory positioning costs that erode working capital efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pocket Knives Market |
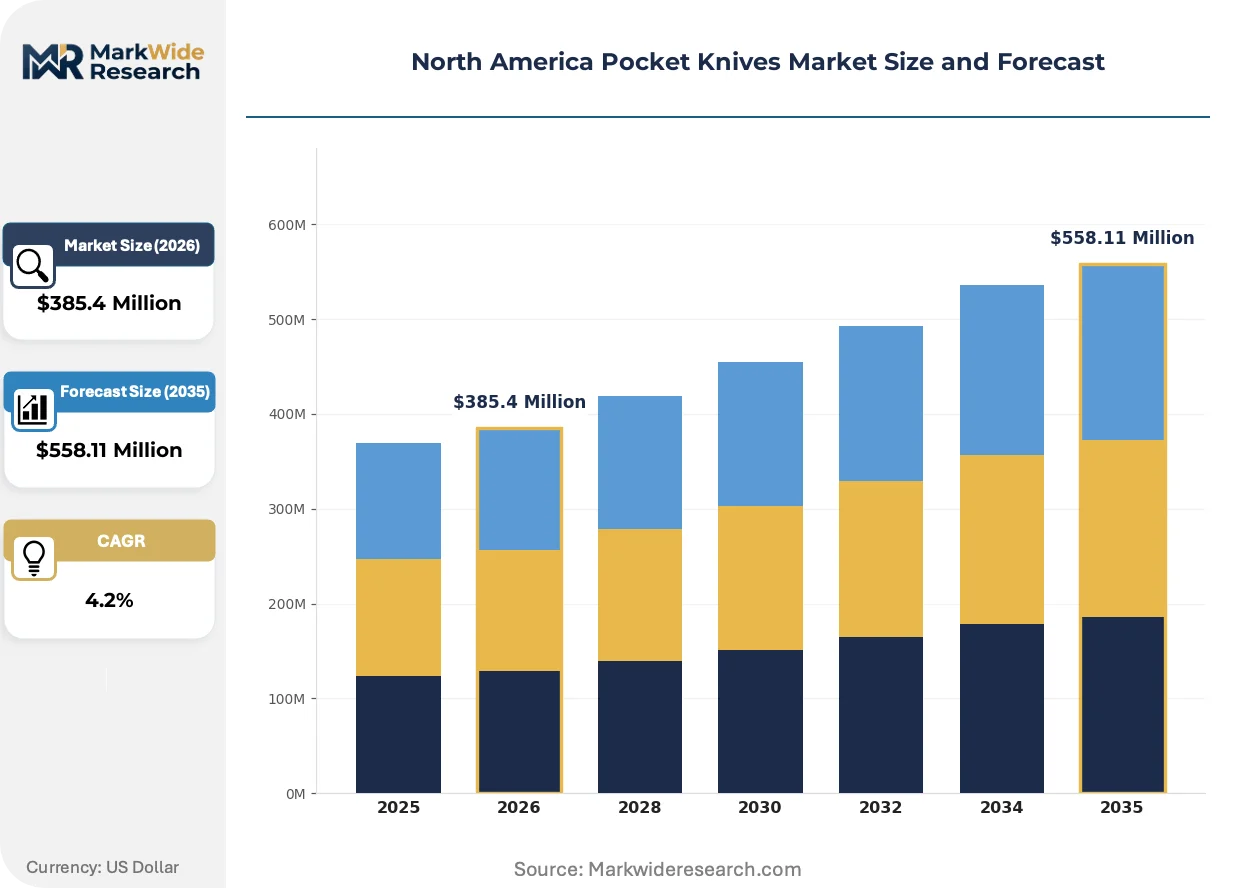
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $558.11 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Knives, Multi-tools, Fixed Blade Knives, Swiss Army Knives Material: Stainless Steel, Carbon Steel, Titanium, Synthetic End User: Outdoor Enthusiasts, Collectors, Everyday Carry Users, Survivalists Distribution Channel: Online Retail, Specialty Stores, Department Stores, Outdoor Retailers |
| Companies Covered | SOG Knives, Bark River Knives, Benchmade, Montana Knife Company, Columbia River Knife and Tool, Buck Knives, Chris Reeve Knives, Tactile Knife Co., Gerber Gear, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pocket Knives Market Trends and Innovations
Material science advances and shifting carry regulations are fragmenting the traditional premium-mass market boundary. Manufacturers now compete on weight reduction and jurisdictional compliance rather than blade geometry alone.
Ceramic matrix composites are decomposing the titanium-stainless duopoly in ultralight handle construction. Everyday carry professionals in Seattle and Portland adopt these materials despite brittleness trade-offs, accepting replacement cycles in exchange for sub-two-ounce pocket presence. The technology is decomposing the historical correlation between premium pricing and metal construction.
The US Consumer Product Safety Commission maintains active enforcement of sharp-edge safety standards that manufacturers must navigate for interstate commerce. Health Canada maintains parallel protocols that occasionally diverge on tip-sharpness testing methodologies, forcing dual-track quality systems. Canadian border provinces bear the highest compliance burden as cross-shipment volumes concentrate through Vancouver and Toronto distribution nodes.
Collector preference is rotating toward carbon steel patina development as a visible authenticity signal. Online knife communities disseminate forced-patina techniques that accelerate blade character, compressing the traditional multi-year ownership cycle into months. This behavioral shift concentrates most visibly in the Pacific Northwest, where artisanal craft heritage validates hand-finished aesthetics over factory consistency.
North America Pocket Knives Market Segmentation
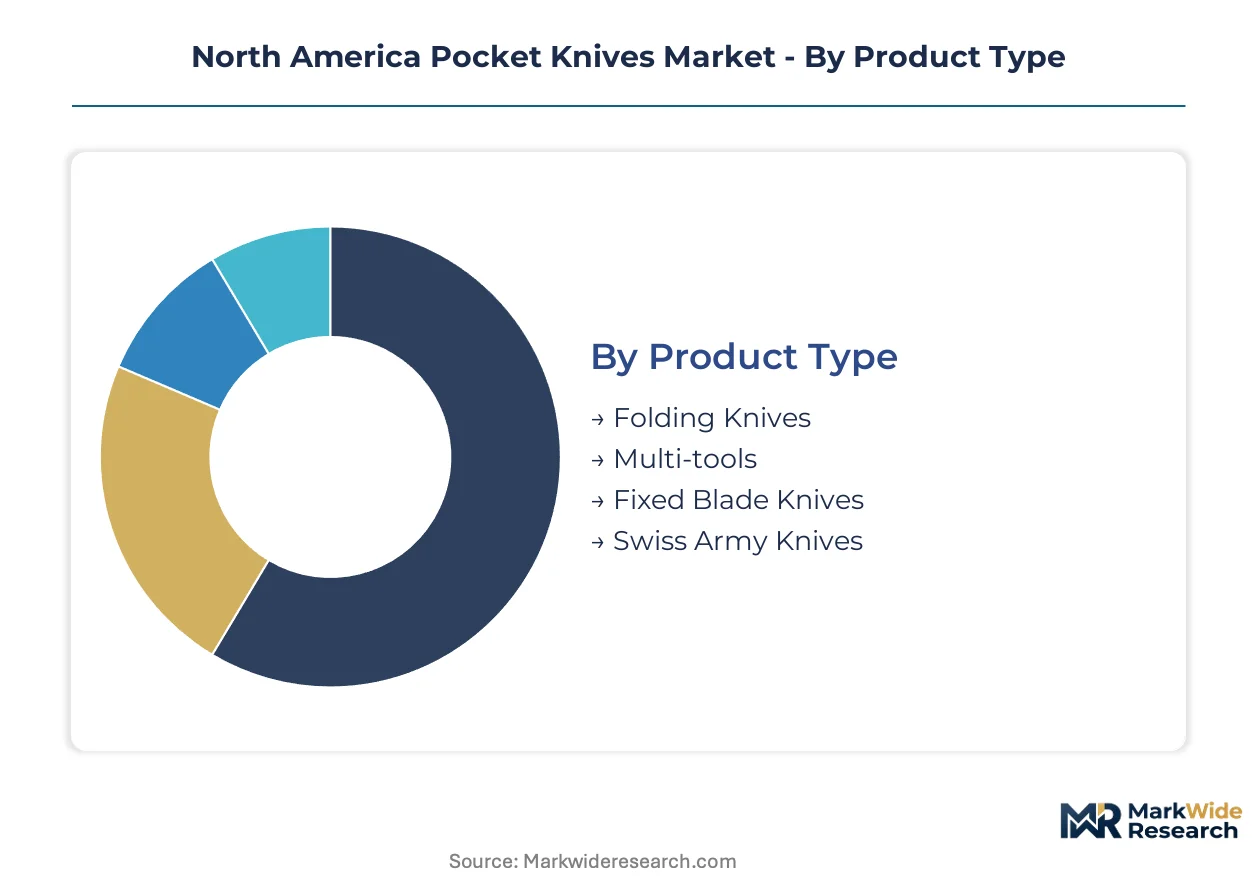
Pocket knife segmentation in North America reflects divergent compliance burdens and carry restrictions that reshape channel economics. Manufacturers must align product specifications with jurisdiction-specific blade-length ordinances while matching material choices to end-use durability requirements.
Product Type:
US Consumer Product Safety Commission edge-tool standards apply differential testing protocols depending on blade deployment mechanism, creating compliance cost tiers across mechanical categories.
- Folding Knives:Spring-assisted or manual pivot mechanisms with locking liners dominate volume flows through outdoor retailers. Washington and Oregon outdoor recreation culture sustains concentrated demand for premium locking variants that resist digital substitution.
- Multi-tools:Integrated plier-based platforms with interchangeable bit drivers attract utility-focused everyday carry users in urban professional segments. Reduced pocket weight specifications from Seattle and Portland professionals drive titanium-handled configurations in the premium tier.
- Fixed Blade Knives:Full-tang construction with sheath carry systems faces stricter municipal ordinances in major US urban centers, compressing addressable geography.
- Swiss Army Knives:Slip-joint non-locking mechanisms navigate Transport Security Administration prohibitions more flexibly, preserving airport-adjacent retail viability.
Folding knives handle the majority of throughput; multi-tools are expanding most quickly on share as utility integration appeals to urban professionals.
Material:
Cost tier stratification separates collector-grade carbon formulations from mass-market stainless variants, with titanium commanding premium positioning through weight reduction.
- Stainless Steel:Chromium-alloyed formulations requiring minimal maintenance dominate mainstream sales through lower care burdens. Health Canada parallel safety standards favor corrosion-resistant specifications for cross-border shipment compliance.
- Carbon Steel:High-carbon blade blanks from Montana and Idaho forges develop visible patina as authenticity signals for collectors. Regional forges face energy input cost swings that transmit directly to pricing, compressing margins on artisanal models.
- Titanium:Grade 5 alloy handles reduce pocket presence below two ounces, capturing everyday carry volume in the Pacific Northwest.
- Synthetic:G-10 and carbon fiber composites decompose the historical metal-premium correlation through ceramic matrix advances.
Stainless steel handles the majority of throughput; carbon steel is gaining share fastest as forced-patina techniques accelerate collector acquisition cycles.
End User:
Application intensity varies dramatically between recreational utility and emergency preparedness use cases, reshaping durability specifications and price band acceptance.
- Outdoor Enthusiasts:Hunting, fishing, and backcountry practitioners in the Pacific Northwest sustain premium fixed-blade and folding demand that resists digital substitution.
- Collectors:Hand-finished convex geometry and visible patina development drive preference for artisanal craft heritage over factory consistency.
- Everyday Carry Users:Urban professionals integrate compact blades into daily utility routines, representing the fastest-expanding buyer segment.
- Survivalists:Emergency preparedness practitioners prioritize full-tang reliability and fire-steel compatibility in blade selection.
Outdoor enthusiasts handle the majority of throughput; everyday carry users show the steepest expansion trajectory as urban professional adoption accelerates.
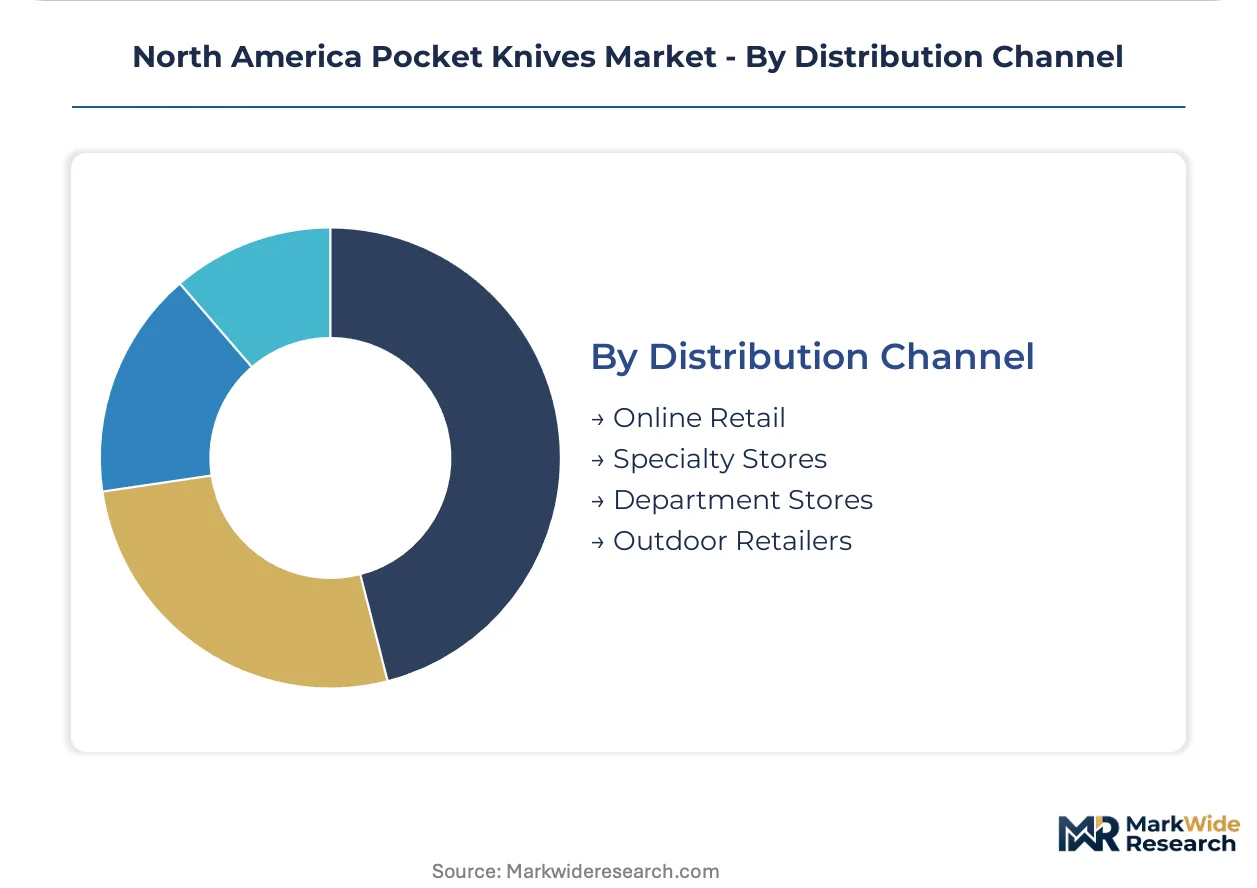
Distribution Channel:
Margin stack compression and jurisdictional carry law fragmentation force parallel channel strategies with divergent inventory positioning economics.
- Online Retail:Direct-to-consumer digital channels bypass traditional outdoor retailer margin stacks, capturing full premium pricing for limited-run artisanal releases.
- Specialty Stores:Knife forums and maker-owned storefronts concentrate collector-grade carbon steel and titanium-handled premium variants.
- Department Stores:Mass-market stainless formulations dominate through lower maintenance requirements and accessible price positioning.
- Outdoor Retailers:Folding knives flow through this channel most intensively, though Transport Security Administration prohibitions fragment distribution economics.
Outdoor retailers handle the majority of throughput; online retail is climbing the fastest as direct-to-consumer models capture margin from specialty releases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pacific Northwest concentrates premium fixed-blade consumption through hunting and backcountry use cases, while urban professionals in coastal metros drive titanium-handled everyday carry demand that diverges from traditional outdoor utility patterns.
United States
The US Consumer Product Safety Commission enforces sharp-edge safety standards that create compliance barriers favoring domestic manufacturers with in-house testing laboratories. Washington and Oregon sustain artisanal craft heritage through master smith operations in Portland and Seattle metro clusters. Transport Security Administration blade-length restrictions fragment distribution economics between airport-adjacent retail and general outdoor merchants.
Canada
Health Canada maintains parallel edge-tool safety standards that occasionally diverge from US protocols on tip-sharpness testing methodologies. Toronto and Vancouver blade-carry regulations remain less restrictive than comparable US cities, creating temporary arbitrage windows for cross-border specialty retail. Vancouver distribution nodes bear elevated compliance burden as cross-shipment volumes concentrate through British Columbia border provinces.
Mexico
Northern border states concentrate manufacturing assembly operations supplying US retailers through maquiladora arrangements. The Secretariat of Economy oversees industrial standards coordination with US CPSC frameworks for export-bound production. Monterrey and Tijuana industrial clusters process blade blanks from regional forges into finished goods for North American distribution.
Pacific Northwest Sub-Region
Montana and Idaho forges supply high-carbon steel blanks to artisanal manufacturers facing energy input cost volatility. Seattle and Portland everyday carry professionals adopt ceramic matrix composite handles despite brittleness trade-offs. Oregon-based manufacturing scales sustain domestic production capacity despite master smith retirement velocity exceeding apprentice entry rates.
North America Pocket Knives Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with domestic manufacturers leveraging in-house heat-treatment laboratories to navigate US CPSC compliance timelines. The structure fragments across four strategic archetypes: artisanal convex-grinding specialists, scale-driven titanium fabricators, regional steel sourcing controllers, and direct-to-consumer digital natives. Competitive moves concentrate on backward integration into blade blank supply and direct-to-consumer channel bypass of traditional outdoor retailer margin stacks.
Within the artisanal specialist tier, Bark River Knives and Chris Reeve Knives exemplify proprietary geometry expertise that resists automated replication. Benchmade occupies a position as an integrated scale manufacturer with Oregon-based production capacity. Montana Knife Company represents regional sourcing control over western US forge networks for high-carbon steel procurement.
| Leading Market Players |
|---|
| SOG Knives |
| Bark River Knives |
| Benchmade |
| Montana Knife Company |
| Columbia River Knife and Tool |
| Buck Knives |
| Chris Reeve Knives |
| Tactile Knife Co. |
| Gerber Gear |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements with Montana and Idaho forges lock in high-carbon steel supply visibility for artisanal manufacturers while insulating against energy-driven price swings that compress margins on collector-grade carbon steel models. These contracts tether pricing power to regional forge capacity rather than spot market volatility, creating divergent cost structures between premium hand-finished tiers and mass-market stainless alternatives.
Pricing Analysis
Project-based pricing for limited-run artisanal releases captures full premium through direct-to-consumer channels, while mass-market stainless formulations transact on per-unit scales through outdoor retailers. Price differentiation separates titanium-handled everyday carry configurations from carbon steel collector pieces, with convex edge geometry commanding brand premiums that automated grinding cannot replicate. Cost compression in the mid-tier stainless segment is intensifying because gray-market imports absorb volume growth, eroding domestic manufacturer margins. Everyday carry users in Seattle and Portland show lowest price sensitivity for sub-two-ounce titanium variants, while department store channels face highest sensitivity on maintenance-burdened carbon steel.
Supply Chain Analysis
Master smith retirement velocity creates a chokepoint that caps scalable premium output regardless of demand signals from Pacific Northwest outdoor recreation culture. Blade blank supply draws from Montana and Idaho regional forges for high-carbon steel, Oregon-based manufacturing scales for titanium fabrication, and Mexican maquiladora clusters for assembly operations. Single-source vulnerability concentrates in aging convex grinding expertise with no scalable training pipeline, forcing reliance on human capital that exits faster than apprentices enter. Distribution runs through outdoor retailers for folding knife volume, specialty storefronts for collector-grade releases, and airport-adjacent channels for TSA-compliant slip-joint mechanisms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as urban professional adoption of everyday carry utility accelerates faster than traditional outdoor segment saturation, with titanium-handled configurations penetrating professional demographics previously unreached by blade culture.
For Market Incumbents: Secure proprietary convex grinding expertise through structured apprenticeship pipelines before master smith retirement velocity extinguishes scalable premium output. Benchmade should anchor Oregon-based capacity expansion against labor scarcity, while Bark River Knives defends geometry differentiation through captive supply of high-carbon blanks from western forge networks. Gray-market import substitution poses the central threat to mass-market stainless margins. For New Entrants and Emerging Players: Health Canada parallel safety standard harmonization offers a certification fast-track for manufacturers seeking dual-market entry with reduced compliance burden. Target Toronto and Vancouver specialty retail expansion where blade-carry regulations remain less restrictive than comparable US cities, leveraging ceramic matrix composite handle innovation to decompose the historical metal-premium correlation. Direct-to-consumer digital storefronts provide the optimal go-to-market angle for limited-run artisanal positioning. For Investors and Strategic Acquirers: Regional steel sourcing controllers with captive forge relationships in Montana and Idaho represent the priority acquisition archetype, offering backward integration value that spot-market procurement cannot replicate. Long-term viability hinges on whether convex edge geometry skill transfer can outpace demographic collapse in the artisanal tier. Watch municipal ordinance fragmentation in major Canadian and US urban centers as the inflection signal for channel strategy pivot requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Regional Forge Networks | Montana and Idaho high-carbon steel sourcing secures blade blank supply visibility against energy cost volatility. |
| Direct-to-Consumer Digital Channel Launch | Maker-owned storefronts bypass outdoor retailer margin stacks to capture full premium on limited-run releases. |
| Convex Grinding Apprenticeship Pipeline | Structured skill transfer addresses master smith retirement velocity that caps scalable premium output. |
| Titanium Handle Fabrication Scale-Up | Grade 5 alloy capacity expansion serves Seattle and Portland everyday carry demand for sub-two-ounce pocket presence. |
| Cross-Border Compliance Harmonization | Aligned US CPSC and Health Canada testing protocols reduce dual-certification costs for single production lines. |
Research Methodology
Cross-validation between primary interviews with master smiths, outdoor retailer category managers, and everyday carry forum moderators anchors the qualitative findings against secondary validation from US CPSC enforcement records, Health Canada safety standard filings, and Pacific Northwest customs trade data. Bottom-up triangulation aggregates forge-level production estimates with channel inventory positioning, while top-down verification cross-checks against regional outdoor recreation expenditure patterns and artisanal maker release schedules.
Sensitivity analysis across blade material substitution rates, municipal ordinance adoption timelines, and master smith retirement velocity tests forecast stability throughout the projection horizon. The analytical framework models segmentation across product type, material formulation, end-user application intensity, and distribution channel economics, with CAGRs derived from regression against historical adoption curves in comparable utility tool categories. Heat-treatment certification timelines and Transport Security Administration prohibition enforcement patterns serve as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of stable US-Canada trade framework and continued Pacific Northwest outdoor recreation participation; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as municipal blade-carry regulations evolve and ceramic matrix composite handle durability data accumulates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Mexico Camping Equipment Market
Outdoor Gear
Camping Equipment and Furniture Market
Outdoor Gear
Deer Hunting Blinds Market
Outdoor Gear
Hiking Backpack Water Filters Market
Outdoor Gear
Inflatable Tents Market
Outdoor Gear
Shoulder Strap Insulated Cooler Market
Outdoor Gear
Fairway Mowers Market
Outdoor Gear
Spain Camping Equipment Market
Outdoor Gear
Wheeled Insulated Cooler Market
Outdoor Gear
China Camping Tent Market
Outdoor Gear
Germany Camping Equipment Market
Outdoor Gear
Artificial Grass Turf Market
Outdoor Gear
China Camping Equipment Market
Outdoor Gear
Europe Camping Equipment Market
Outdoor Gear
Shared Umbrella Market
Outdoor Gear
Camping Gas Canister Market