
 Ice Axe Market | 2026-2036
Ice Axe Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Axe Market Analytics
Carbon fiber composite construction is reconfiguring how manufacturers balance strength-to-weight ratios in modern ice axe design. Petzl leverages in-house lamination expertise to control premium product lines. Black Diamond anchors North American distribution through specialty retail partnerships. Grivel competes on heritage forged-steel heritage while diversifying into hybrid material platforms.
An ice axe is a mountaineering tool comprising a metal head with adze or hammer, a shaft, and a spike, typically measuring 50 to 75 centimeters in length, designed for self-arrest, balance, and anchoring on snow and ice terrain. Technical axes command the highest margin pools due to precision manufacturing tolerances and certification requirements. Recreational users represent the fastest-growing end-user category as alpine tourism infrastructure expands in Eastern Europe and Central Asia. Carbon fiber material adoption accelerates among professional climbers despite premium pricing, while aluminum sustains volume leadership in entry-level segments.
CE marking under the EU Personal Protective Equipment Regulation mandates third-party testing for ice axes sold across European markets, directly shaping product development timelines and compliance costs. The UIAA safety standard, administered by the International Climbing and Mountaineering Association, functions as a de facto global benchmark that manufacturers must satisfy for access to guided expedition procurement channels. Stakeholders must monitor evolving national park permit systems and liability frameworks that increasingly require documented equipment certification for commercial guiding operations.
Market Dynamics
Carbon fiber composite shafts are compressing traditional aluminum's dominance as mountaineering schools and alpine federations rewrite equipment procurement standards around weight-to-strength benchmarks.
Growth Catalysts
- UIAA Safety Standard 152:Mandatory third-party testing for guided expedition procurement channels creates certification-driven replacement cycles across European alpine regions.
- Mountaineering school procurement:Curriculum standardization in Switzerland, Austria, and France mandates technical axe inventories, institutionalizing bulk purchasing agreements.
- Carbon fiber lamination:Automated layup processes reduce unit production costs, expanding addressable professional climber segments previously priced out of composite platforms.
Market Restraints
- Prepreg carbon fiber supply:Toray and Hexcel control aerospace-grade fiber allocation, creating input bottlenecks for axe manufacturers scaling composite production.
- CE marking compliance costs:EU Personal Protective Equipment Regulation mandates Notified Body involvement, extending product development timelines by 8-14 months for new entrants.
- Fixed-blade crampon substitution:Hybrid traction systems reduce self-arrest dependency on steep alpine terrain, compressing technical axe attach rates among recreational users.
Strategic Opportunities
- Kazakhstan alpine tourism infrastructure:Government-backed resort development in the Tien Shan range creates first-mover distribution advantages for certified equipment suppliers.
- Modular head systems:Interchangeable adze-hammer-pick configurations address multi-terrain use cases, commanding premium positioning against single-purpose competitors.
- Digital certification tracking:Blockchain-anchored equipment lifecycle records align with emerging liability frameworks in French and Italian commercial guiding regulations.
Industry Challenges
- Composite repair technician scarcity:Carbon fiber damage assessment requires specialized training absent from standard outdoor equipment service curricula, constraining aftermarket revenue capture.
- Multi-standard harmonization delays:Divergent testing protocols between UIAA and emerging national alpine federation standards fragment R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Axe Market |
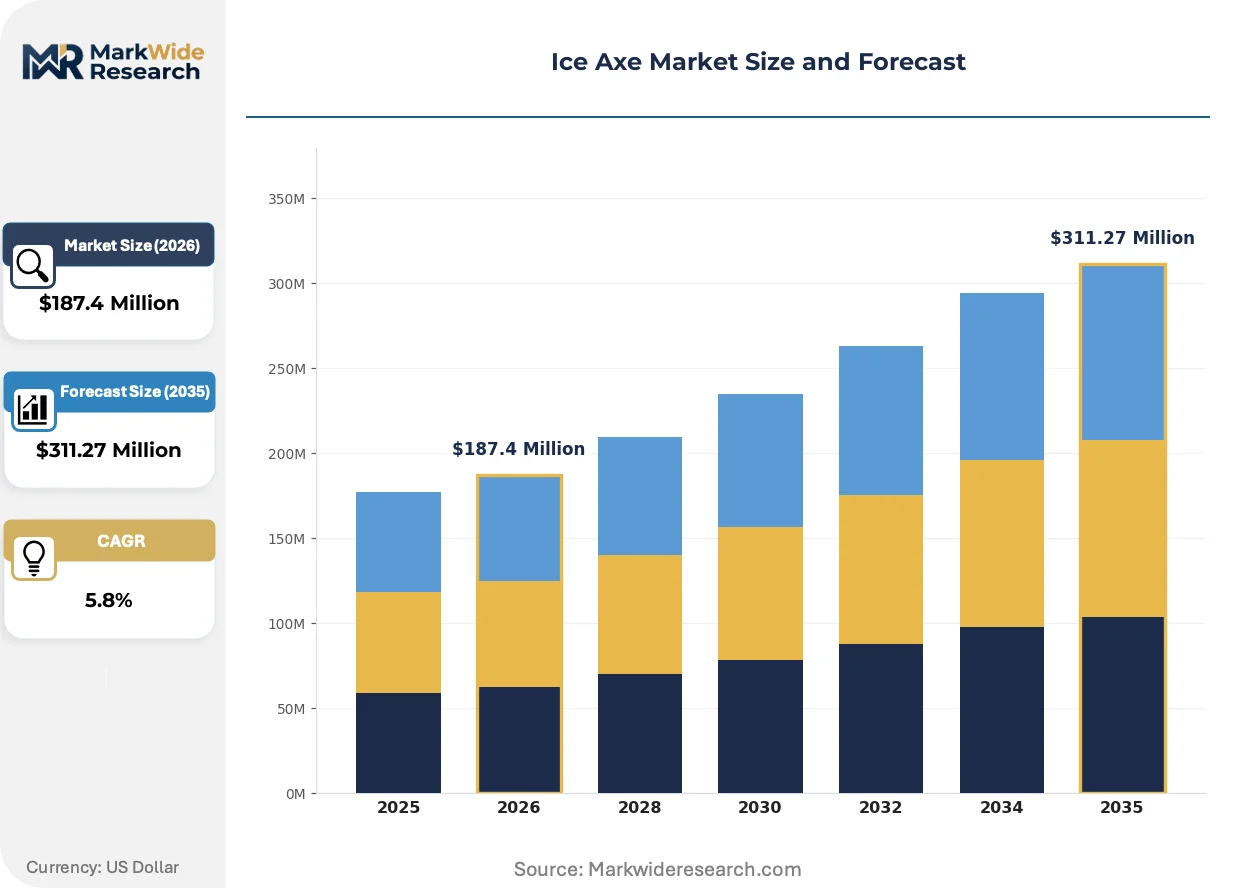
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Camping Axes, Climbing Axes, Technical Axes, General Purpose Axes Material: Aluminum, Steel, Composite, Carbon Fiber End User: Professional Climbers, Recreational Users, Outdoor Enthusiasts, Mountaineering Schools Feature: Adjustable Length, Lightweight Design, Ergonomic Grip, Anti-Slip Handle |
| Companies Covered | Salewa, DMM, Petzl, Blue Ice, Grivel, Black Diamond, Climbing Technology, Deuter, CAMP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Axe Market Evolving Landscape
Material science advances and certification digitization are rewriting how manufacturers compete on safety verification, weight reduction, and channel access across alpine equipment procurement.
Titanium alloy pick inserts are rendering obsolete traditional hardened steel penetration components in high-altitude technical axes. Expedition operators above 6,000 meters specify titanium-carbide hybrid picks for reduced brittleness in sub-zero conditions. The shift is compressing steel-forging capacity utilization among heritage manufacturers while accelerating electron-beam welding adoption for insert bonding.
EU Green Deal sustainable product requirements are mandating recycled aluminum content disclosures and carbon footprint labeling for PPE categories including mountaineering equipment. Manufacturers must document scope 3 emissions across supply chains to maintain CE marking validity. Swiss and Austrian brands with captive European smelter relationships hold compliance timing advantages over Asia-dependent competitors.
Direct-to-expedition procurement platforms are disintermediating specialty retail for high-volume guided operator contracts. Outfitters in Nepal and Patagonia now source technical axes through centralized federation purchasing cooperatives, bypassing traditional distributor markups. This channel compression concentrates price negotiation leverage with UIAA-certified manufacturers while marginalizing regional distributors without certification laboratory partnerships.
Ice Axe Market Segmentation
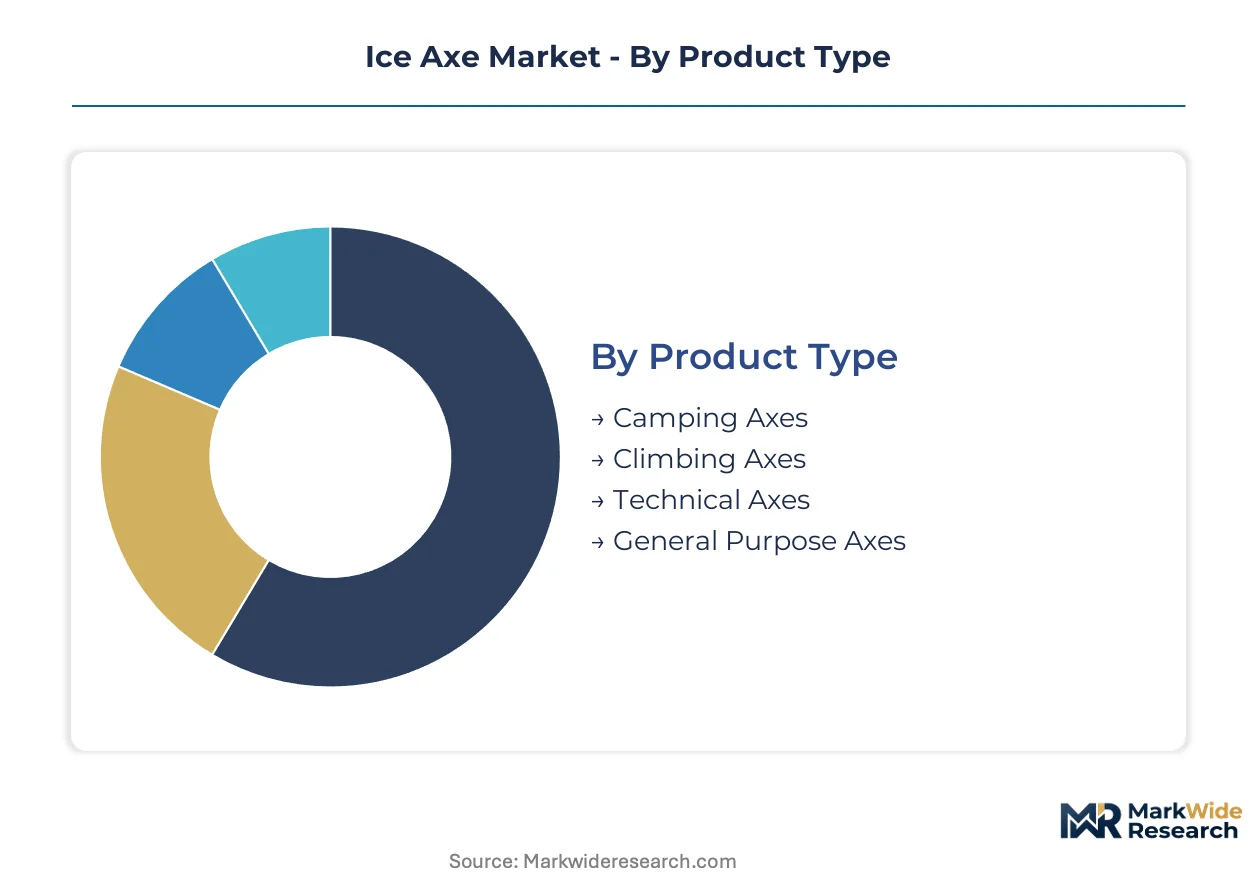
Ice axe segmentation maps directly to risk tolerance and certification requirements across alpine use cases. Procurement patterns diverge sharply between institutional buyers with mandated UIAA compliance and recreational consumers prioritizing weight and ergonomics over technical specifications.
Product Type:
Use-case spectrum spans from casual snow walking to vertical ice climbing, with each tier demanding distinct head geometry, shaft rigidity, and pick penetration profiles.
- Technical Axes:Aggressive curved shafts and interchangeable pick systems support vertical ice and mixed terrain. Swiss and Austrian mountaineering schools mandate these for guided instruction, creating institutional procurement pipelines with multi-year replacement cycles.
- Climbing Axes:Straight shafts with moderate pick angles serve alpine rock-and-ice transitions. Demand concentrates among professional climbers in the Mont Blanc massif and Dolomites where rapid route changes require versatile tool geometry.
- Camping Axes:Short shafts with broad adzes suit snow camping and glacier travel. Weekend trekkers in the Tatra Mountains and Scottish Highlands drive volume.
- General Purpose Axes:Hybrid designs balance self-arrest utility with modest climbing capability. Rental fleets and entry-level retail in emerging alpine tourism markets favor this category.
The dominant share belongs to General Purpose Axes, while Technical Axes is closing the gap fastest.
Material:
Cost tier stratification separates aerospace-grade composites from commodity aluminum, with steel occupying a narrowing premium-forged niche.
- Carbon Fiber:Automated layup processes achieve strength-to-weight ratios impossible with metals. Professional climbers on Himalayan expeditions specify carbon fiber shafts for load reduction above 6,000 meters, though Toray and Hexcel supply constraints limit manufacturer scaling.
- Aluminum:7075-T6 aircraft-grade alloys dominate entry-level and rental segments. Swiss and Austrian brands with captive European smelter relationships hold cost advantages under EU Green Deal recycled content mandates.
- Composite:Fiberglass-reinforced polymers bridge aluminum and carbon fiber price points. Eastern European manufacturers exploit this tier for price-sensitive export markets.
- Steel:Forged heads and full-steel shafts persist in heritage product lines and extreme cold applications where brittleness resistance trumps weight concerns.
Aluminum retains volume leadership, though Carbon Fiber is expanding most quickly among certified professional segments.
End User:
Customer type determines channel structure, with institutional buyers bypassing retail entirely through federation procurement cooperatives.
- Mountaineering Schools:Federations in Switzerland, France, and Austria mandate certified technical axe inventories, creating predictable bulk purchasing with UIAA 152 compliance requirements.
- Professional Climbers:Expedition operators and high-altitude guides specify titanium-carbide picks and carbon fiber shafts, sourcing through direct-to-expedition platforms that disintermediate distributors.
- Recreational Users:Alpine tourism infrastructure expansion in Kazakhstan and Georgia drives first-time buyer volume through specialty retail.
- Outdoor Enthusiasts:Casual snowshoers and glacier hikers prioritize ergonomics and price over technical certification, concentrating in mass outdoor retail channels.
Mountaineering Schools anchor institutional revenue stability, while Recreational Users is gaining share fastest on tourism infrastructure investment.
Feature:
Design differentiation increasingly centers on adjustability and grip technology as manufacturers seek premium positioning beyond material specifications.
- Lightweight Design:Sub-400-gram targets for technical axes drive carbon fiber adoption and hollow-shaft aluminum extrusion. Weight reduction commands premium pricing in professional segments.
- Adjustable Length:Telescoping shafts adapt to terrain and user height, particularly valued by guiding operations serving diverse client physiques on Mont Blanc standard routes.
- Ergonomic Grip:Thermoplastic elastomer overmolds and finger rest geometry reduce fatigue on long alpine routes. Italian and French manufacturers lead industrial design integration.
- Anti-Slip Handle:Textured surfaces and drainage channels maintain grip in wet ice conditions, a baseline expectation rather than differentiator in technical segments.
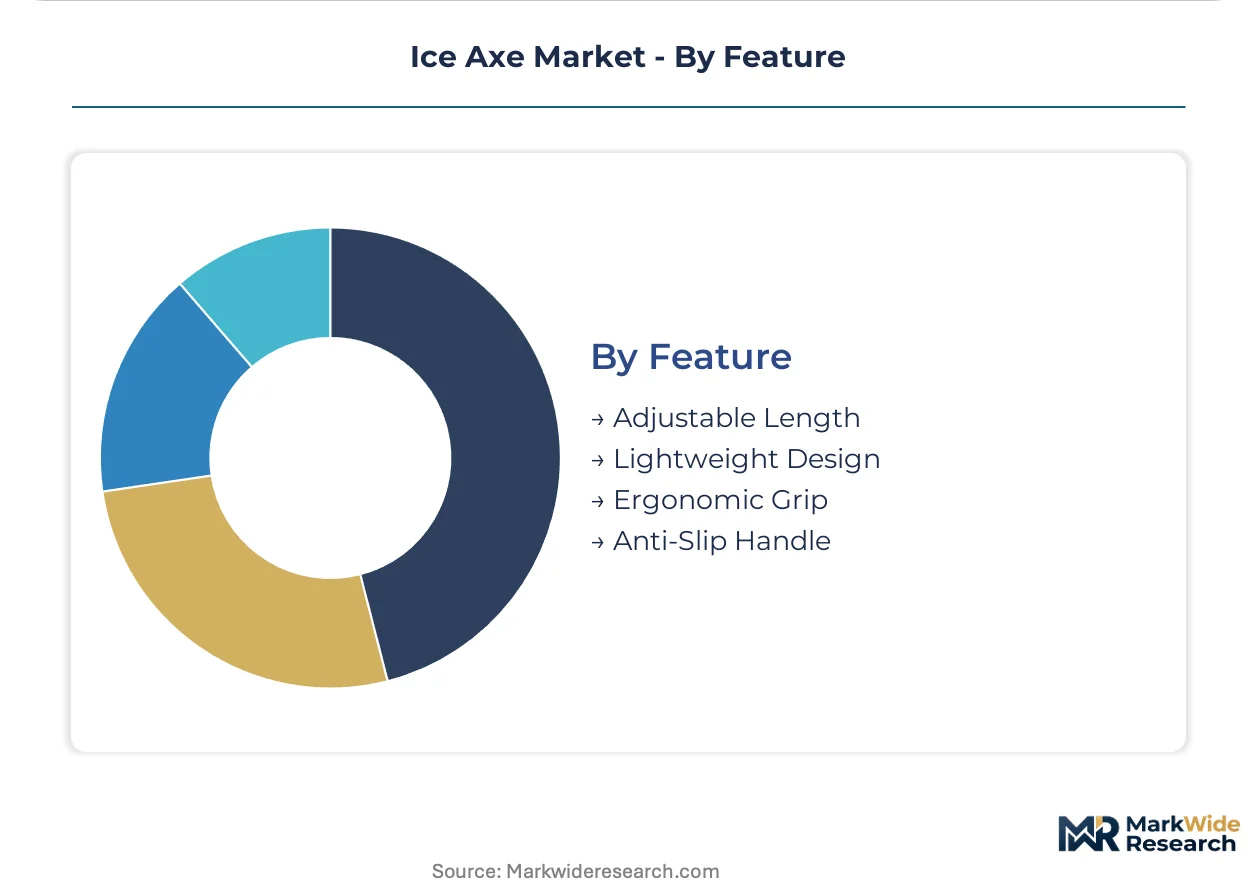
Lightweight Design holds the dominant share, though Adjustable Length is climbing the fastest as modular tool systems gain professional acceptance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guided expedition operators and mountaineering federations concentrate equipment procurement in alpine jurisdictions with mandatory certification regimes. Institutional buyers in Switzerland, Austria, and France drive technical axe demand through curriculum standardization. Recreational tourism expansion in Central Asia and the Caucasus creates new retail channels for entry-level inventory.
Switzerland
The Swiss Alpine Club mandates UIAA-certified technical axes for all guided ascents, creating institutional procurement pipelines that refresh on three-year cycles. Swissmedic oversees equipment safety notifications under EU PPE Regulation alignment. Bern and Interlanken host federation procurement cooperatives that aggregate demand from 250+ certified mountain guides.
France
ANSM enforces PPE compliance for commercial guiding operations in the Mont Blanc massif and Ecrins National Park. The Chamonix valley concentrates expedition outfitter headquarters serving Himalayan and Patagonian routes. French alpine federations require documented equipment certification for liability insurance coverage.
Austria
The Austrian Alpine Association standardizes technical axe inventories across 280 affiliated mountaineering schools. Tyrol and Vorarlberg host composite materials R&D clusters serving carbon fiber shaft manufacturers. National park permit systems in the Hohe Tauern increasingly require certified equipment declarations.
Kazakhstan
Government-backed resort development in the Tien Shan range drives first-time buyer volume through Almaty-based specialty retailers. The national tourism agency subsidizes alpine infrastructure investment under diversification mandates. Domestic distributors without UIAA laboratory partnerships face exclusion from federation procurement channels.
Italy
The Dolomites UNESCO World Heritage designation intensifies guided expedition permit scrutiny around equipment documentation. Turin and Bergamo anchor industrial design clusters specializing in ergonomic grip engineering. Italian alpine guides' associations lobby for harmonized certification standards across trans-border routes into Switzerland and Austria.
Ice Axe Market Competitive Landscape
Channel-controlling players compete with product-specialist players across certification-driven procurement and retail distribution segments. The vendor base stratifies into heritage forged-steel manufacturers, composite materials specialists, and diversified outdoor equipment conglomerates. Three archetypes dominate: federation-certified technical specialists, carbon fiber laminators with aerospace supply relationships, and mass-market aluminum extruders serving rental fleets. Competitive moves center on Notified Body partnerships for CE marking acceleration and direct-to-expedition platform development bypassing regional distributors.
Within the heritage-forged tier, Grivel anchors Italian alpine equipment manufacturing traditions. Petzl and Black Diamond occupy positions as vertically integrated specialists controlling composite lamination and North American distribution respectively. These three exemplify how certification laboratory relationships and captive material supply chains determine access to institutional procurement channels.
| Leading Market Players |
|---|
| Salewa |
| DMM |
| Petzl |
| Blue Ice |
| Grivel |
| Black Diamond |
| Climbing Technology |
| Deuter |
| CAMP |
| Others |
Value Network & Pricing Analysis
Single-source dependency on Toray and Hexcel for aerospace-grade prepreg carbon fiber simultaneously compresses margin structures at the premium tier and forces supply chain consolidation around certified laminate partners. This input bottleneck determines both the 40-60% price spread between carbon fiber technical axes and aluminum entry models and the geographic clustering of composite manufacturing in European alpine regions with captive fiber allocation agreements.
Pricing Analysis
Cost-plus contracts with aluminum indexation dominate procurement between federation cooperatives and heritage manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates UIAA-certified technical axes from recreational aluminum models and rental fleet generics. Price differentiation rests on certification grade and volume scale, with institutional buyers commanding 15-25% discounts on multi-year replacement cycles. Cost compression in the standard tier is intensifying because Eastern European composite extruders are undercutting Western laminate specialists on general-purpose inventory. Recreational users exhibit highest price sensitivity, while expedition operators prioritize performance metrics over unit cost.
Supply Chain Analysis
Export-control regimes on carbon fiber precursor technology limit flows from Japan and the United States to non-allied manufacturing jurisdictions. Geographic supply concentration centers on Italy for forged-steel heritage production, Switzerland and Austria for carbon fiber lamination, and China for aluminum shaft extrusion. Raw material dependencies include Toray T800H fiber, 7075-T6 aluminum billet, and titanium-carbide pick inserts. Single-source vulnerability runs through the two-fiber duopoly controlling aerospace-grade allocation. Distribution runs through federation procurement cooperatives for institutional buyers and specialty retail chains for recreational segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment replacement cycles tied to UIAA certification expiration dates position this market for cyclical recovery as alpine federations refresh technical axe inventories on standardized three-year rotations.
For Market Incumbents: Insulate margin pools by securing multi-year fiber allocation agreements with Toray or Hexcel before capacity constraints tighten further. Deepen backward integration into automated layup equipment to reduce unit conversion costs against emerging Eastern European competitors. Prioritize Notified Body partnership expansion to accelerate CE marking timelines for modular head system launches. For New Entrants and Emerging Players: Establish a beachhead in Kazakhstan's Tien Shan alpine tourism corridor before incumbent distributors consolidate retail shelf space. Target the composite bridge tier between aluminum and carbon fiber price points where heritage brands maintain legacy positioning. Pursue direct-to-expedition platform partnerships with Nepalese and Patagonian outfitters bypassing traditional distributor markups. For Investors and Strategic Acquirers: The market sits at a pre-consolidation phase that favors vertically integrated laminate specialists with captive fiber relationships over asset-light brand licensors. Long-term viability over the next decade hinges on compliance timing advantages under EU Green Deal scope 3 disclosure mandates. Watch for UIAA laboratory partnership announcements as inflection indicators for which manufacturers will capture federation procurement channel access.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Partnership Expansion | CE marking acceleration under EU PPE Regulation compresses product development timelines by 8-14 months for new technical axe launches. |
| Carbon Fiber Lamination Capacity Buildout | Automated layup investment reduces unit production costs and expands addressable professional climber segments previously priced out. |
| Direct-to-Expedition Platform Development | Bypassing regional distributor markups concentrates price negotiation leverage with UIAA-certified manufacturers in Nepal and Patagonia. |
| Modular Head System Launch | Interchangeable adze-hammer-pick configurations command premium positioning against single-purpose competitors in technical segments. |
| Blockchain Certification Tracking Integration | Equipment lifecycle records align with emerging liability frameworks in French and Italian commercial guiding regulations. |
Research Methodology
Initial hypotheses were tested against primary input from alpine guide association procurement officers, composite materials R&D directors, federation equipment standardization committee members, and specialty retail category buyers, then refined against secondary validation from UIAA safety standard documentation, EU PPE Regulation compliance filings, Swissmedic equipment safety notifications, and customs trade data on carbon fiber precursor imports. Bottom-up demand modeling across end-user segments was triangulated with top-down market sizing from manufacturer shipment disclosures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, material grade, end-user archetype, and certification status cluster. CAGRs were derived from replacement cycle analysis and tourism infrastructure investment pipelines. Industry-specific forecast inputs incorporated mountaineering school enrollment trajectories and alpine federation curriculum standardization timelines.
Sensitivities concentrate around prepreg carbon fiber allocation disruptions, UIAA standard revision schedules, and national park permit system changes. Forecasts reflect assumptions on fiber supply continuity, certification harmonization progress, and alpine tourism infrastructure completion rates. Material shifts in EU Green Deal enforcement stringency or emerging national alpine federation standards fragmentation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Deer Hunting Blinds Market
Outdoor Gear
Japan Camping Equipment Market
Outdoor Gear
Camping Cooler Market
Outdoor Gear
Global Automatic Mower Market
Outdoor Gear
Diving Regulator Market
Outdoor Gear
Europe Camping Equipment Market
Outdoor Gear
Beach Umbrella Market
Outdoor Gear
North America Robotic Lawn Mower Market
Outdoor Gear
Australia Camping Equipment Market
Outdoor Gear
Mexico Camping Equipment Market
Outdoor Gear
Professional Gear Bags Market
Outdoor Gear
Wheeled Insulated Cooler Market
Outdoor Gear
New Zealand Camping Equipment Market
Outdoor Gear
Inflatable Tents Market
Outdoor Gear
Campsite Cooking Gears Market
Outdoor Gear
Rain Boots Market