
 Singapore Camping Equipment Market | 2026-2036
Singapore Camping Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Camping Equipment Market Insights
Premium ultralight specifications is collapsing the gap between recreational and technical camping gear in Singapore. Decathlon S.A. leverages its vertical supply chain to dominate mass-market accessibility across the island. Johnson Outdoors, Inc. anchors its position through specialized marine-compatible equipment suited to Singapore's humid coastal conditions. VF Corporation competes on brand equity and technical apparel integration with core equipment lines.
Camping equipment comprises portable shelters, sleep systems, load-bearing packs, and field cooking apparatus engineered from ripstop nylon, silicone-coated polyester, aircraft-grade aluminum, and hydrophobic down or synthetic fills, with waterproof ratings typically exceeding 3000mm hydrostatic head for tropical precipitation resistance; its primary purpose is to enable temporary habitation and self-sufficiency in outdoor environments without fixed infrastructure. Tents and backpacks capture the dominant margin pools as replacement cycles compress with humidity-driven fabric degradation in Singapore's climate. Cooking gear represents the fastest-growing product type as campsite dining experiences gain traction among casual campers and family segments. Nylon and polyester materials lead volume due to their strength-to-weight ratios and rapid-dry properties essential for equatorial conditions.
Singapore's Consumer Product Safety Office enforces durability and flammability standards for portable gas stoves and tent fabrics, while the National Environment Agency regulates chemical content in water-resistant coatings through environmental protection mandates. The Building and Construction Authority's green mark criteria increasingly shape supplier selection for outdoor education programs and institutional procurement. Stakeholders must monitor evolving sustainability certifications and local content requirements as Singapore advances its circular economy roadmap for consumer goods.
Market Dynamics
Singapore's camping equipment sector is restructuring around humidity-resistant material specifications, with the Building and Construction Authority's green mark criteria now filtering procurement decisions for outdoor education programs and institutional buyers island-wide.
Growth Catalysts
- BCA Green Mark Standards:Mandatory sustainability criteria for public sector outdoor education procurement are redirecting supplier selection toward certified low-carbon material providers.
- Adventure Tourism Expansion:Domestic operators are scaling lightweight gear procurement to serve multi-day trekking packages across regional trail networks.
- Ripstop Nylon Innovation:Silicone-coated variants with rapid-dry properties are extending equipment replacement cycles in equatorial humidity conditions.
Market Restraints
- Petrochemical Input Volatility:Nylon and polyester resin prices fluctuate with regional refinery output, compressing margin visibility for domestic distributors.
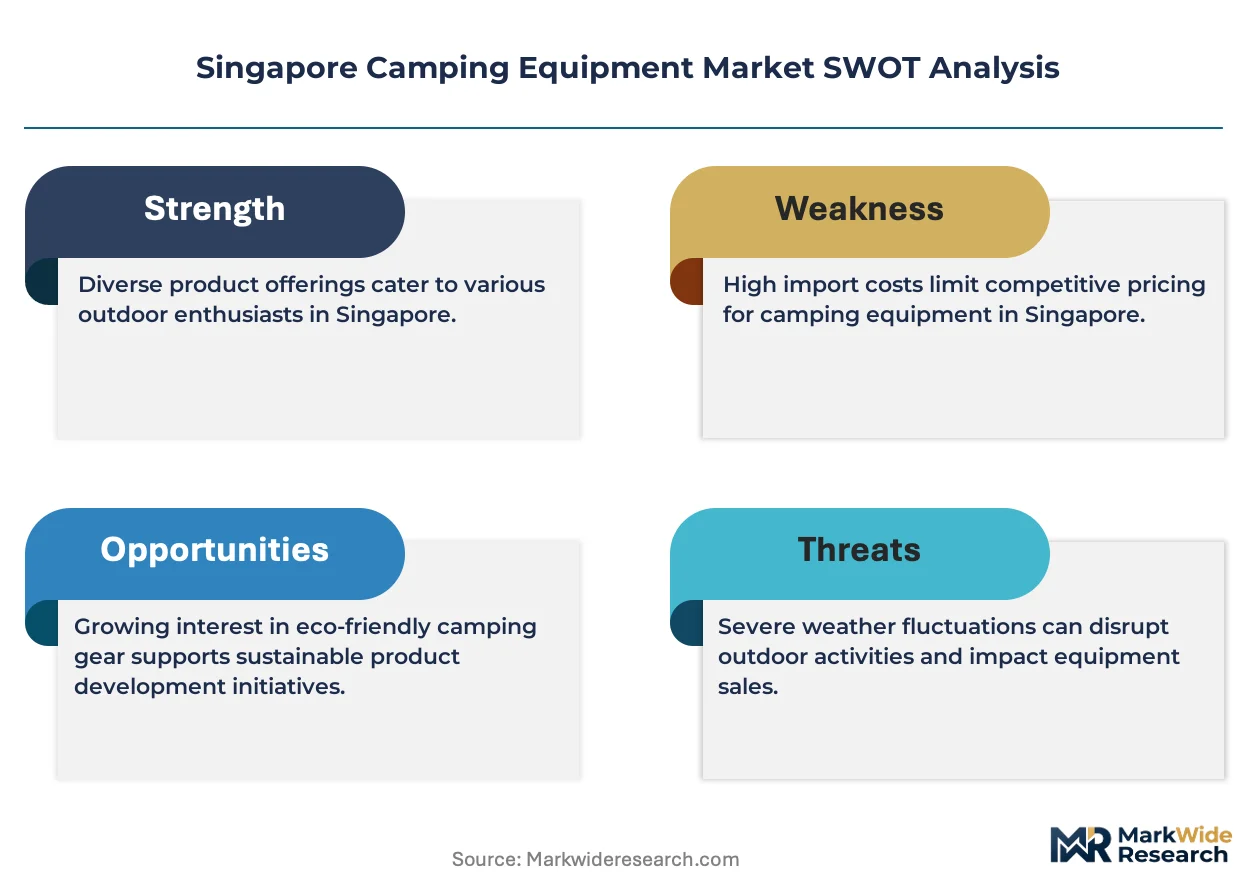
- Single-Source Coating Suppliers:Hydrophobic DWR treatments concentrate among specialty chemical producers in Northeast Asian manufacturing zones.
- Urban Storage Constraints:High-density housing limits consumer inventory capacity, suppressing multi-item purchase patterns.
Strategic Opportunities
- Central Region Retail Corridors:Orchard Road and Bugis adventure hubs remain underpenetrated for experiential showroom concepts combining gear with guided trip booking.
- Marine-Compatible Equipment:Cross-application potential exists for kayakers and paddleboarders seeking corrosion-resistant shelter systems.
- Circular Economy Roadmap:Extended producer responsibility frameworks under development by the National Environment Agency will favor modular repairable designs.
Industry Challenges
- Technical Textile Engineering Talent:Local universities produce limited graduates specializing in tropical-performance fabric chemistry.
- NEA Chemical Compliance Timelines:Water-resistant coating reformulations require 18-24 month approval cycles that delay product refresh schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Camping Equipment Market |
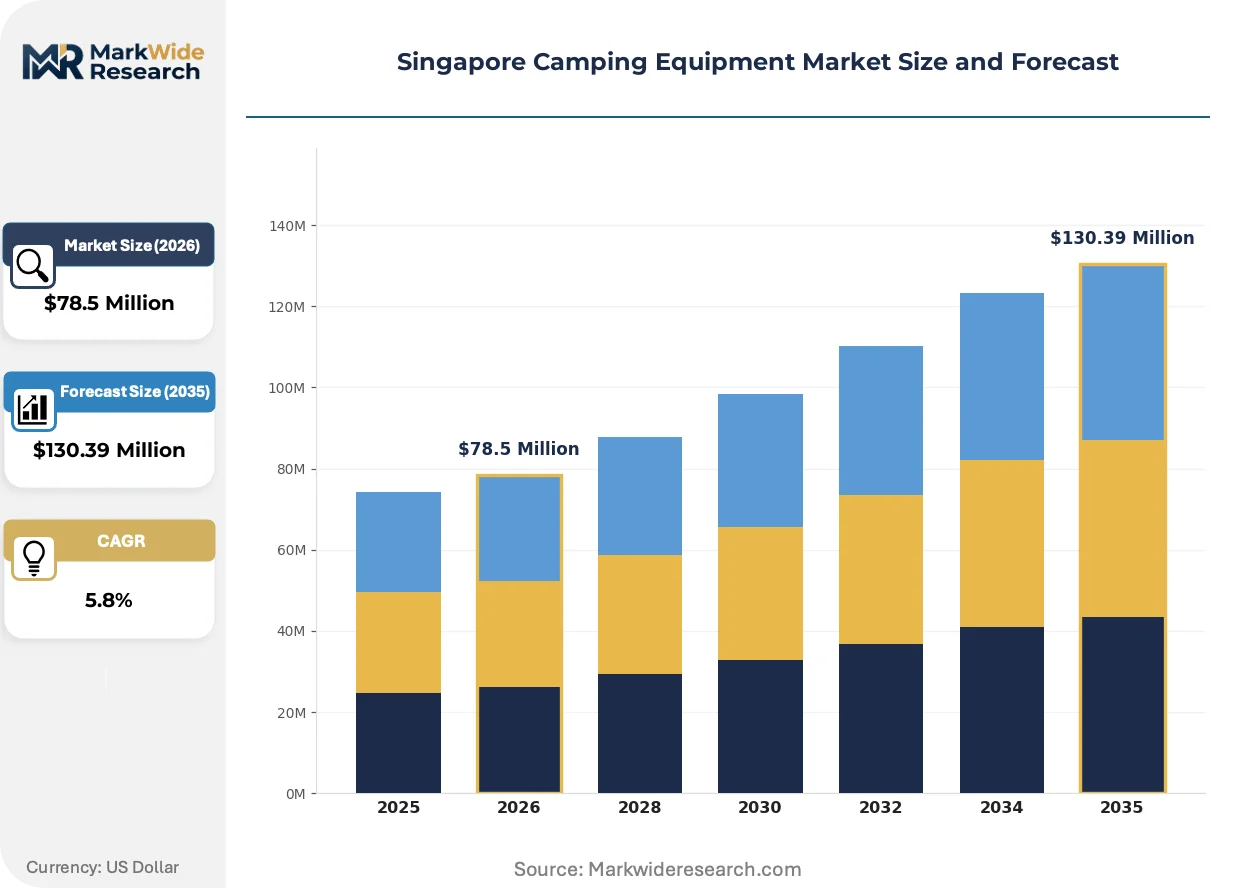
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $130.39 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tents, Sleeping Bags, Backpacks, Cooking Gear End User: Casual Campers, Adventure Enthusiasts, Families, Outdoor Organizations Material: Nylon, Polyester, Cotton, Aluminum Distribution Channel: Online Retailers, Specialty Stores, Department Stores, Sporting Goods Shops |
| Companies Covered | Decathlon S.A., Johnson Outdoors, Inc., VF Corporation, Big Agnes, Inc., Newell Brands, Inc., Dometic Group AB, Oase Outdoors ApS, Exxel Outdoors, LLC, AMG Group Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Camping Equipment Market Trends and Innovations
Material science convergence with sustainability mandates is compressing traditional equipment replacement models. Three distinct vectors are restructuring how gear is engineered, certified, and consumed across Singapore's outdoor retail landscape.
Silicone-impregnated nylon is decomposing the historical separation between recreational and technical camping categories. Adventure tourism operators now specify ultralight shelters for mass-market trekking packages. This convergence is collapsing premium-mid-tier price stratification as single products serve dual use cases.
REACH-aligned chemical restrictions are accelerating fluorocarbon-free DWR coating adoption across Southeast Asian supply chains. The National Environment Agency's parallel environmental protection mandates on persistent organic pollutants are forcing reformulation timelines. Tent and apparel manufacturers serving Singapore must now dual-certify for EU export and domestic compliance simultaneously.
Experience-integrated retail is displacing traditional transaction-focused outdoor stores. Consumers now expect gear demonstrations tied to actual trip bookings within single physical locations. This pattern concentrates within the Central Region's adventure hubs where operators combine equipment sales with guided expedition logistics.
Singapore Camping Equipment Market Segmentation
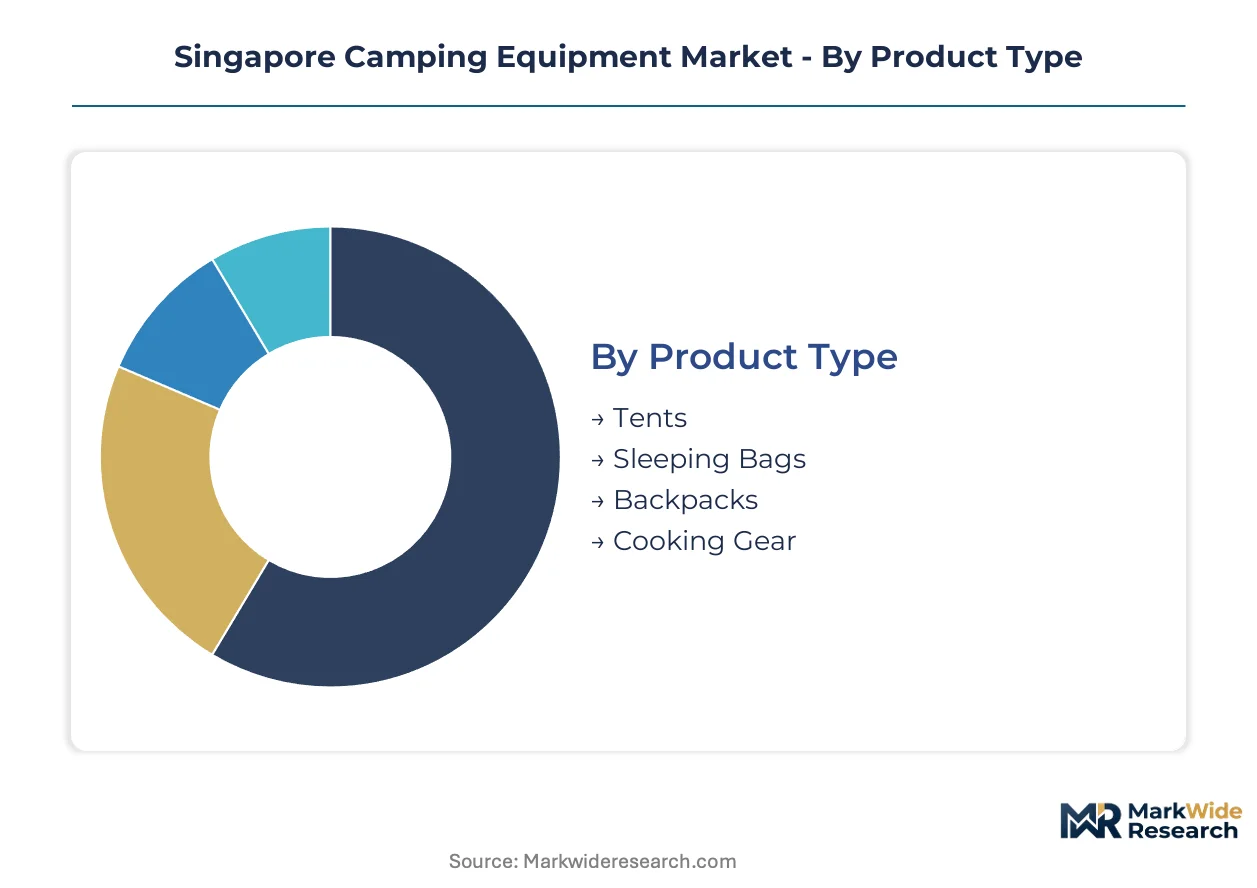
Singapore's camping equipment segmentation reflects regulatory pressure on material sourcing and the Central Region's retail corridor concentration. Procurement patterns diverge sharply between institutional buyers bound by BCA Green Mark criteria and individual consumers prioritizing rapid-dry performance in equatorial humidity.
Product Type:
The Consumer Product Safety Office enforces divergent flammability and durability standards across shelter, sleep, and cooking systems, creating compliance-based tiering in supplier portfolios.
- Tents:Silicone-coated nylon and polyester constructs with hydrostatic head ratings exceeding 3000mm dominate procurement. Adventure tourism operators in the Central Region specify ultralight variants for multi-day regional trekking packages, compressing replacement cycles through humidity-driven fabric degradation.
- Backpacks:Ripstop nylon shells with aircraft-grade aluminum frame components anchor technical specifications. Demand concentrates among adventure enthusiasts seeking load-bearing efficiency for Singapore's limited trail access and cross-border expedition logistics.
- Sleeping Bags:Hydrophobic down and synthetic fills engineered for tropical moisture resistance.
- Cooking Gear:Portable gas stoves and field cooking apparatus; campsite dining experiences are expanding adoption among casual campers and family segments in urban outdoor hubs.
Established volume favors Tents; emerging adoption favors Cooking Gear.
End User:
Cost tier differentiation separates mass-market accessibility from technical performance specifications across Singapore's consumer base.
- Adventure Enthusiasts:Technical-grade equipment with marine-compatible corrosion resistance and ultralight load specifications. Procurement runs through specialty retailers in Bugis and Orchard Road adventure hubs combining gear with guided expedition booking.
- Families:Mid-tier durability-focused products emphasizing rapid-dry convenience and simplified setup protocols. The National Environment Agency's chemical compliance timelines influence purchase timing for water-resistant coating safety.
- Casual Campers:Entry-level accessibility through mass-market retail channels.
- Outdoor Organizations:Institutional procurement bound by BCA Green Mark sustainability criteria for public sector outdoor education programs.
Margin concentration sits with Adventure Enthusiasts; volume expansion favors Families.
Material:
Supply concentration for petrochemical-derived textiles creates input cost volatility that reshapes tiered pricing across nylon and polyester dominance.
- Nylon:Ripstop variants with silicone impregnation deliver strength-to-weight ratios essential for equatorial conditions. Regional refinery output fluctuations in Northeast Asian manufacturing zones compress margin visibility for domestic distributors.
- Polyester:Silicone-coated rapid-dry specifications extend equipment replacement cycles against humidity degradation. The Building and Construction Authority's green mark standards now filter supplier selection toward certified low-carbon material providers.
- Cotton:Limited adoption due to moisture retention in tropical climates; niche heritage aesthetic applications.
- Aluminum:Aircraft-grade alloys for frame and cookware components; corrosion resistance prioritization for coastal proximity.
Technical performance anchors Nylon; sustainability certification is accelerating Polyester.
Distribution Channel:
Geography of retail concentration in Singapore's Central Region creates experiential showroom advantages over transaction-focused formats.
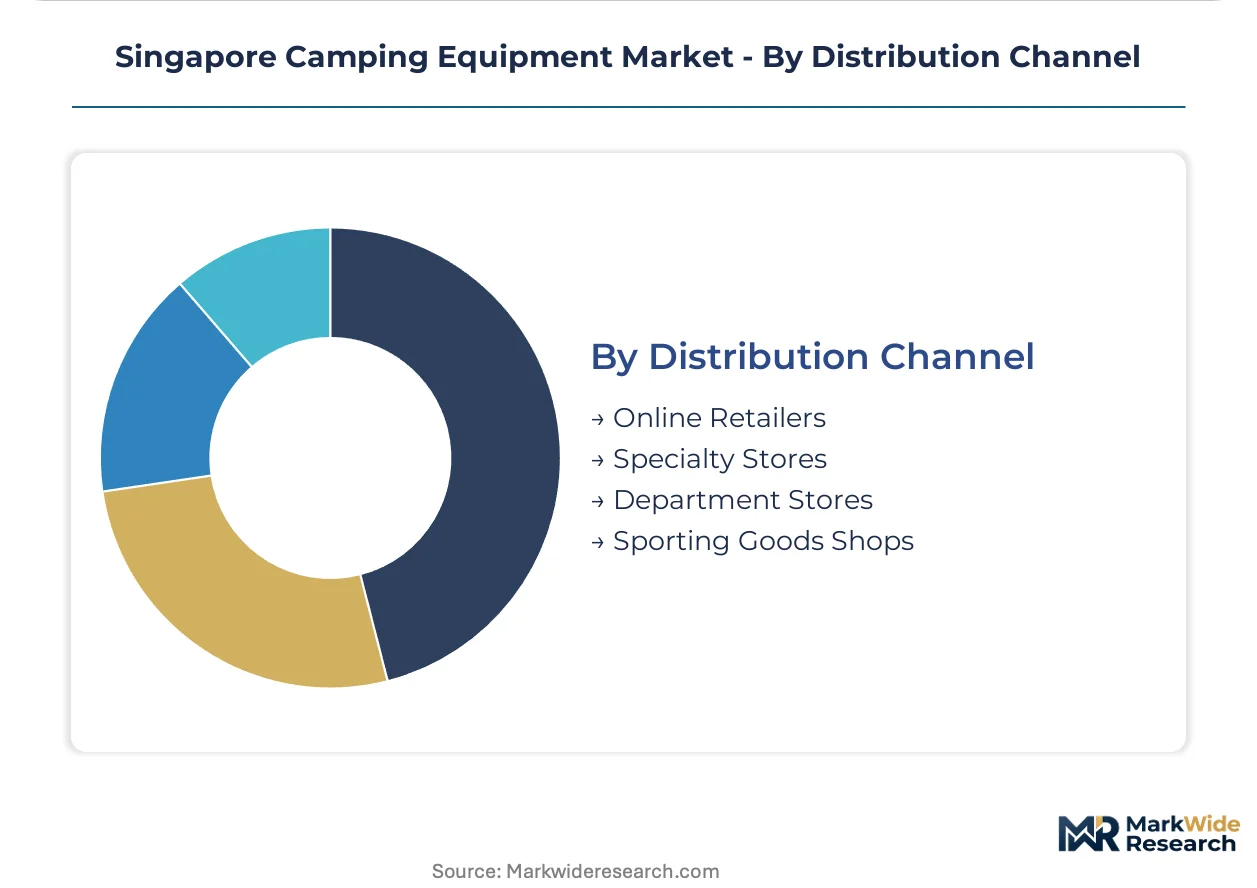
- Specialty Stores:Experience-integrated concepts in Orchard Road and Bugis corridors combine gear demonstration with actual trip booking logistics. Adventure tourism operators leverage these hubs for guided expedition package sales alongside equipment procurement.
- Online Retailers:Mass-market accessibility with vertical supply chain efficiency. Urban storage constraints in high-density housing suppress multi-item purchase patterns, favoring single-transaction convenience.
- Department Stores:Mid-tier family segment reach with limited technical consultation capacity.
- Sporting Goods Shops:Cross-category outdoor equipment access with marine-compatible gear adjacencies for kayakers and paddleboarders.
Service integration favors Specialty Stores; transaction efficiency favors Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical suppliers for hydrophobic coatings concentrate in Northeast Asian manufacturing zones, creating input dependencies for Singapore-based equipment distributors. This supply-side geography shapes procurement timelines and margin structures across the island's outdoor retail corridors.
Central Region
Orchard Road and Bugis adventure hubs generate concentrated demand for experience-integrated retail concepts. The Building and Construction Authority's green mark standards filter institutional procurement for outdoor education programs. Specialty showrooms in these districts now combine gear demonstrations with guided expedition bookings.
East Region
Marine-compatible equipment demand from kayakers and paddleboarders drives corrosion-resistant shelter specifications. The National Environment Agency regulates chemical content in water-resistant coatings through environmental protection mandates. Retail clusters near East Coast Park serve coastal recreation segments with salt-resistant product lines.
West Region
Adventure tourism operators scale lightweight gear procurement for multi-day regional trekking packages. The Consumer Product Safety Office enforces durability standards for portable gas stoves and tent fabrics. Distribution warehouses in Jurong logistics corridors support cross-border expedition logistics.
North Region
Family-oriented camping demand concentrates in suburban outdoor recreation zones with simplified setup protocols. The National Environment Agency's circular economy roadmap shapes extended producer responsibility expectations. Retail access points in Woodlands and Yishun serve entry-level and mid-tier durability segments.
Northeast Region
Institutional buyers in outdoor education programs drive BCA Green Mark-compliant procurement volumes. The Building and Construction Authority's sustainability criteria redirect supplier selection toward certified low-carbon material providers. Punggol and Sengkang corridors host emerging experiential retail concepts targeting family segments.
Singapore Camping Equipment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Singapore's camping equipment sector. The market structure consolidates around three distinct tiers: mass-market accessibility players leveraging vertical supply chains, technical specialists engineering humidity-resistant specifications, and brand-equity competitors integrating apparel with core equipment lines. Strategic moves concentrate on portfolio diversification toward marine-compatible corrosion resistance and experiential retail service integration.
Within the mass-market accessibility tier, Decathlon S.A. exemplifies scale-driven efficiency through its captive supply chain architecture. Among technical specialists, Johnson Outdoors, Inc. occupies a position emphasizing equatorial climate engineering, while VF Corporation represents brand-equity consolidation across technical apparel and equipment integration. These three anchors illustrate the competitive vectors reshaping procurement relationships with Singapore's adventure tourism operators and institutional buyers.
| Leading Market Players |
|---|
| Decathlon S.A. |
| Johnson Outdoors, Inc. |
| VF Corporation |
| Big Agnes, Inc. |
| Newell Brands, Inc. |
| Dometic Group AB |
| Oase Outdoors ApS |
| Exxel Outdoors, LLC |
| AMG Group Ltd. |
| Others |
Pricing and Supply Chain Analysis
Decathlon's vertical supply chain efficiency anchors Singapore's price floors, compressing margin headroom for distributors while concentrating procurement power among Northeast Asian textile manufacturers. This scale dynamic forces mid-tier competitors toward service differentiation or certification premiums to escape commodity pricing traps.
Pricing Analysis
The Consumer Product Safety Office's flammability and durability mandates dictate the pricing tier structure across tents, backpacks, and cooking systems. Three-tier pricing stratifies across premium technical specifications, standard rapid-dry convenience, and economy accessibility levels. Price differentiation hinges on BCA Green Mark certification status and silicone-coating technology grade. Cost compression in the standard tier is intensifying because petrochemical input volatility from regional refinery output squeezes distributor margins. Casual campers exhibit highest price sensitivity, while adventure enthusiasts absorb premiums for marine-compatible corrosion resistance.
Supply Chain Analysis
Northeast Asian manufacturing zones for hydrophobic DWR treatments create a chokepoint that Singapore distributors cannot bypass without 18-24 month NEA reformulation timelines. Raw material flows draw from China for ripstop nylon, South Korea for silicone-coated polyester, and Japan for aircraft-grade aluminum frame components. Single-source vulnerability concentrates among specialty chemical producers for water-resistant coatings. Distribution runs through Jurong logistics corridors for cross-border expedition fulfillment and Central Region experiential showrooms for service-integrated retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's camping equipment sector rewards service-attach strategies: guided expedition booking layers expand faster than hardware sales as adventure tourism operators bundle logistics with gear procurement.
For Market Incumbents: Compound defensive positioning through backward integration into silicone-coating technology and captive repair service networks. The NEA's extended producer responsibility frameworks threaten asset-light distributors with compliance cost displacement. Certification investment in BCA Green Mark standards creates switching costs for institutional procurement relationships. For New Entrants and Emerging Players: Anchor in marine-compatible equipment white space serving East Region kayakers and paddleboarders with corrosion-resistant shelter systems. The most penetrable segment sits with family-oriented casual campers in North Region suburban zones seeking simplified setup protocols. A direct experiential showroom model combining gear demonstration with trip booking logistics bypasses Decathlon's scale advantage. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors technical textile specialists with tropical-performance fabric chemistry capabilities over brand-aggregators. Long-term viability rests on circular economy readiness as the National Environment Agency advances modular repairable design mandates. The inflection indicator to watch is NEA approval velocity for fluorocarbon-free DWR formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Experiential Retail Integration | Orchard Road and Bugis showrooms combining gear sales with guided expedition bookings capture service-attach margins. |
| Fluorocarbon-Free DWR Transition | REACH-aligned reformulations position suppliers for dual EU-export and domestic NEA compliance simultaneously. |
| Marine-Compatible Product Line Extension | Corrosion-resistant shelters address East Region kayaker demand with salt-resistant specifications. |
| BCA Green Mark Certification Investment | Certified low-carbon material access unlocks public sector outdoor education procurement volumes. |
| Modular Repairable Design Development | Extended producer responsibility frameworks favor equipment architectures supporting component replacement cycles. |
Research Methodology
A spread of perspectives from adventure tourism operators, specialty retail buyers, textile procurement managers, and outdoor education program directors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through Singapore Customs import records, BCA Green Mark certification databases, and NEA chemical compliance filings. Bottom-up equipment shipment data triangulated against top-down adventure tourism expenditure estimates.
Product type, end user archetype, material specification, and distribution channel dimensions structured the analytical framework across the projection horizon. CAGRs derived from regression analysis against humidity-driven replacement cycle compression and institutional procurement growth curves. Forecast inputs incorporated NEA reformulation timeline probabilities and BCA sustainability criteria adoption rates.
Material uncertainties — petrochemical price volatility, NEA approval delays, and circular economy roadmap acceleration — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as extended producer responsibility implementation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Japan Camping Equipment Market
Outdoor Gear
Trail Running Bags Market
Outdoor Gear
Rain Boots Market
Outdoor Gear
Artificial Grass Turf Market
Outdoor Gear
Snow Chain Market
Outdoor Gear
Cordless Garden Equipment Market
Outdoor Gear
North America and Europe Leaf Blower Market
Outdoor Gear
UK Camping Equipment Market
Outdoor Gear
Bicycle Bags and Bag Packs Market
Outdoor Gear
Camping Gas Canister Market
Outdoor Gear
Camping Equipment Market
Outdoor Gear
Canoe Paddles Market
Outdoor Gear
Outdoor Hot Tub Market
Outdoor Gear
Spain Camping Equipment Market
Outdoor Gear
Campsite Cooking Gears Market
Outdoor Gear
Crash Pads Market