
 Wheeled Insulated Cooler Market | 2026-2036
Wheeled Insulated Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
Wheeled Insulated Cooler Market Analytics
Rotomolded manufacturing is fragmenting the wheeled insulated cooler category into performance tiers that separate weekend users from expedition-grade buyers. Yeti Coolers leverages proprietary PermaFrost insulation to command premium positioning in the hard-sided segment. Igloo Products anchors volume distribution through mass retail channels with price-accessible polyethylene models. ORCA Coolers differentiates through domestic manufacturing credentials and lifetime warranty structures that compete directly against imported alternatives.
A wheeled insulated cooler combines a thermally insulated chamber with rolling mobility hardware, typically employing polyurethane foam cores between polyethylene or nylon shells to maintain sub-ambient temperatures for 24–72 hours depending on ice load and ambient exposure; its primary commercial purpose is preserving perishables during mobile outdoor recreation, foodservice transport, and remote worksite operations. Hard-sided polyethylene dominates unit economics due to durability and cost efficiency, while soft-sided nylon variants capture fastest-growing demand among ultralight backpackers and kayak anglers seeking collapsible portability. Electric-powered thermoelectric models represent a nascent margin pool where lithium-ion battery integration and solar compatibility attract early adopters in extended off-grid camping.
The US Consumer Product Safety Commission oversees mechanical safety standards for rolling hardware and child entrapment hazards in cooler latches, while California's Proposition 65 mandates disclosure of phthalate content in flexible vinyl components used in select soft-sided designs. The EPA's evolving framework on recycled content in durable goods will pressure manufacturers to validate post-consumer polyethylene feedstocks without compromising rotomolded structural integrity. Stakeholders must monitor whether state-level extended producer responsibility laws expand to recreational durables, as this would reshape collection logistics and material recovery economics across the value chain.
Market Dynamics
Rotomolded polyethylene manufacturing has consolidated premium tier production among facilities capable of uniform wall thickness and integrated hinge molding, compressing margins for injection-molded competitors while extending replacement cycles through structural durability gains.
Growth Catalysts
- State park outdoor recreation procurement:Expanded visitor services programs across American South state park systems are standardizing wheeled cooler fleets for rental operations and concession infrastructure.
- REACH chemical compliance:European Union REACH restrictions on phthalate plasticizers in flexible vinyl components are accelerating substitution toward TPU-coated nylon in soft-sided cooler manufacturing.
- Thermoelectric lithium-ion integration:Battery chemistry advances enabling 48-hour off-grid cooling are opening expedition-grade segments previously served solely by passive ice retention.
Market Restraints
- Polyethylene resin price volatility:Feedstock cost swings tied to naphtha cracking economics compress rotomolded margin structures without commensurate pricing power in mass retail channels.
- Guangdong Province mold fabrication concentration:Critical rotational mold tooling supply concentrates in Pearl River Delta facilities, creating single-source vulnerability for North American manufacturers.
- Passive cooling duration ceiling:Polyurethane foam core R-values face theoretical limits around 6-8 per inch, constraining ice retention extension without proportional weight penalties.
Strategic Opportunities
- Extended producer responsibility tailwinds:California SB 54 and analogous state frameworks are mandating post-consumer recycled content thresholds that favor domestic rotomolders with validated PE feedstock chains.
- Kayak angler ultralight demand:Collapsible soft-sided designs under 8 pounds empty weight are capturing saltwater flats fishing segments in Florida and Texas coastal markets.
- Solar-thermoelectric hybrid systems:Photovoltaic panel integration with 12V cooling circuits enables indefinite off-grid operation in desert camping and overlanding applications.
Industry Challenges
- Rotational mold technician scarcity:Specialized oven operation and mold maintenance skills concentrate among aging workforces in Ohio and Texas manufacturing clusters.
- CPSC child entrapment certification timelines:Revised mechanical safety testing for latch mechanisms extends new product introduction cycles by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheeled Insulated Cooler Market |
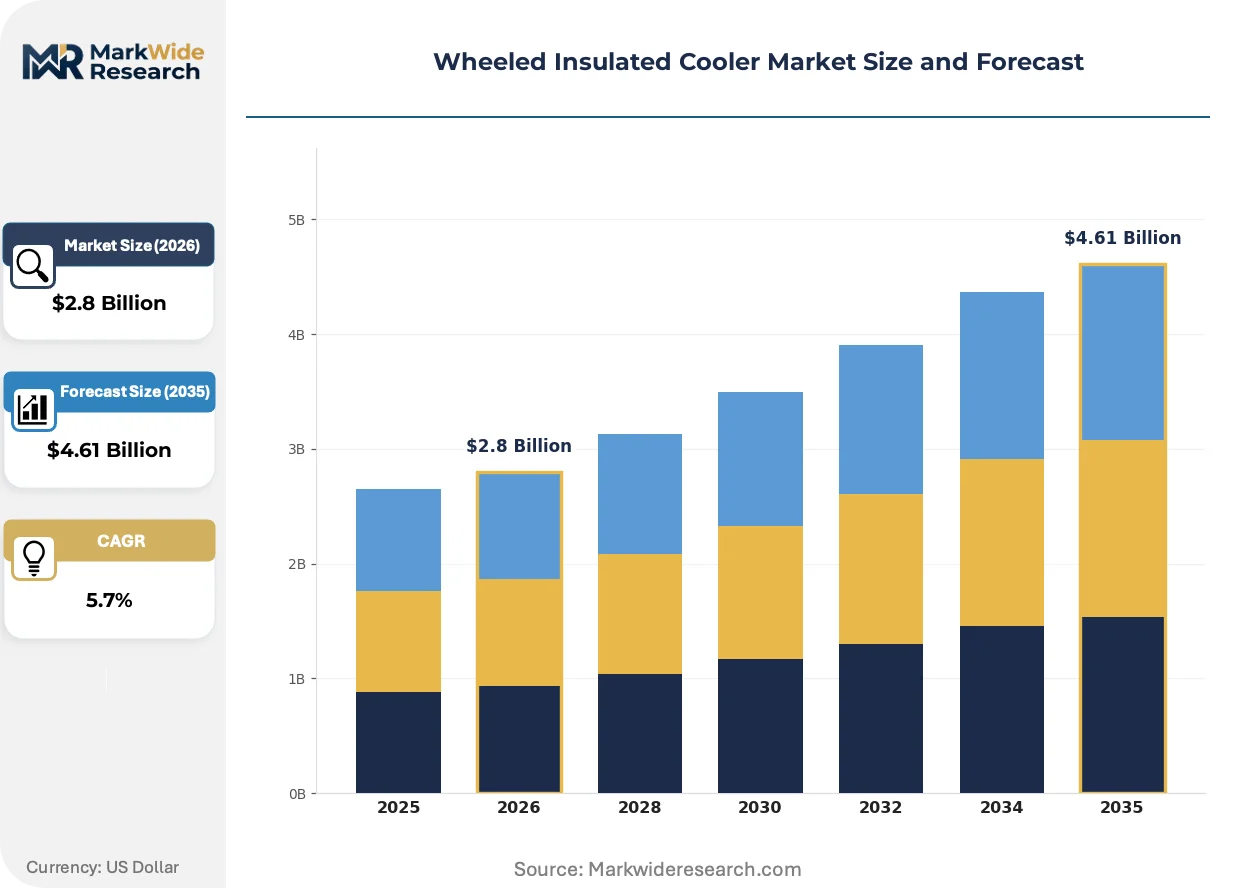
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard-Sided, Soft-Sided, Electric, Hybrid Material: Polyethylene, Nylon, Stainless Steel, Aluminum Capacity: 20 QT, 50 QT, 70 QT, 100 QT End User: Camping, Fishing, Tailgating, Outdoor Events |
| Companies Covered | Yeti Coolers, Igloo Products, The Coleman Company, Pelican Products, AO Coolers, ORCA Coolers, Bison Coolers, Thermos, RTIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheeled Insulated Cooler Market Evolving Landscape
Material science breakthroughs and regulatory pressure on chemical content are compressing traditional product lifecycles while opening performance tiers previously inaccessible to mid-market manufacturers.
Vacuum-insulated panel technology is rendering obsolete conventional polyurethane foam cores in expedition-grade wheeled coolers. Arctic research stations and remote medical transport operators are adopting VIP-equipped units despite 40% weight premiums. This thermal performance leap is rendering obsolete the historical trade-off between ice retention duration and portable weight.
EPA recycled content validation protocols are pressuring rotomolders to document post-consumer polyethylene feedstock chains without compromising structural integrity. California's implementing regulations under SB 54 mandate 30% recycled content in durable goods by 2028. Hard-sided cooler manufacturers are responding by securing offtake agreements with agricultural film reclaimers in Iowa and Illinois.
Direct-to-consumer channel expansion is fragmenting traditional sporting goods retail concentration. Specialty overlanding outfitters in Colorado and Utah are bypassing mass merchant distribution to offer customization services including laser-etched corporate branding and modular accessory rails. This channel shift is most visible in the $400-plus price tier where buyer research cycles extend 60-90 days and specification comparison dominates purchase decisions.
Wheeled Insulated Cooler Market Segmentation
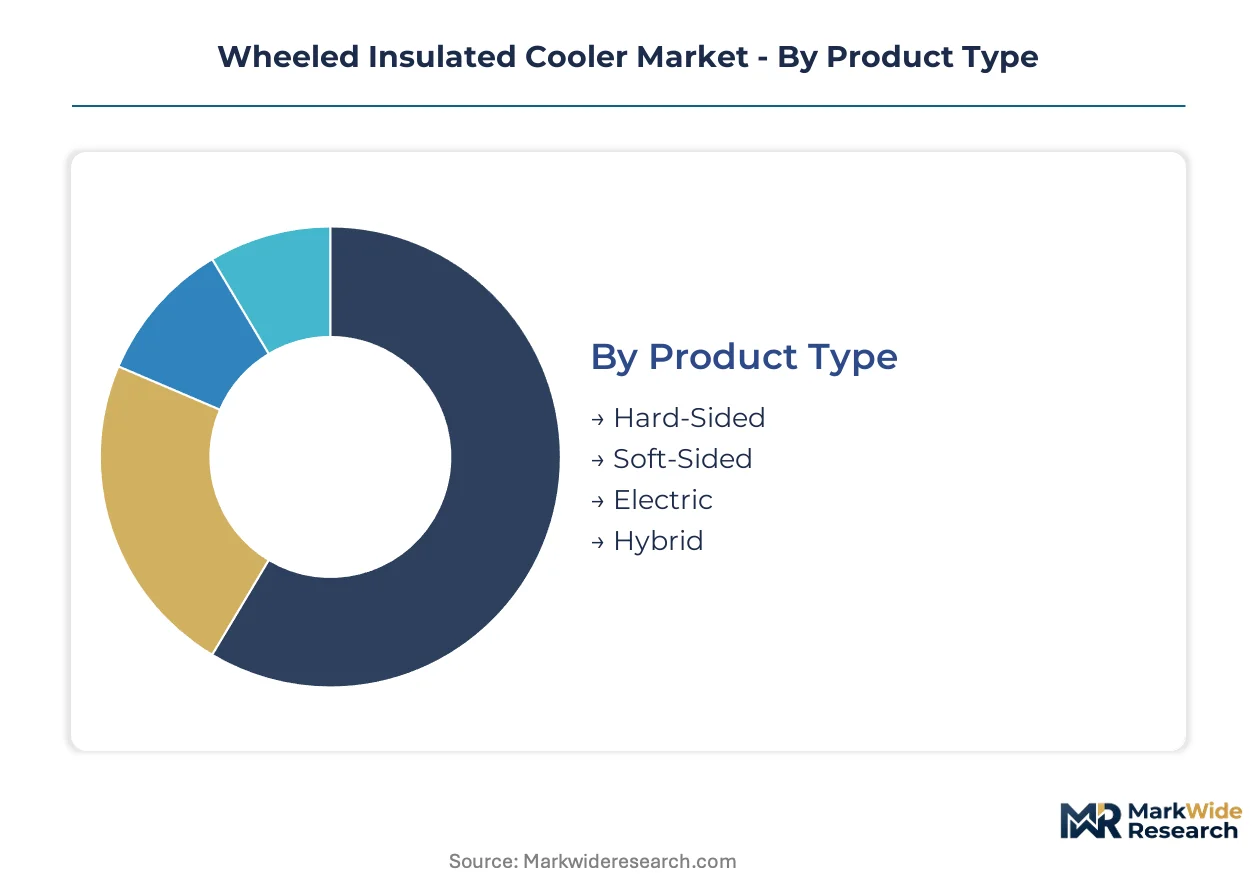
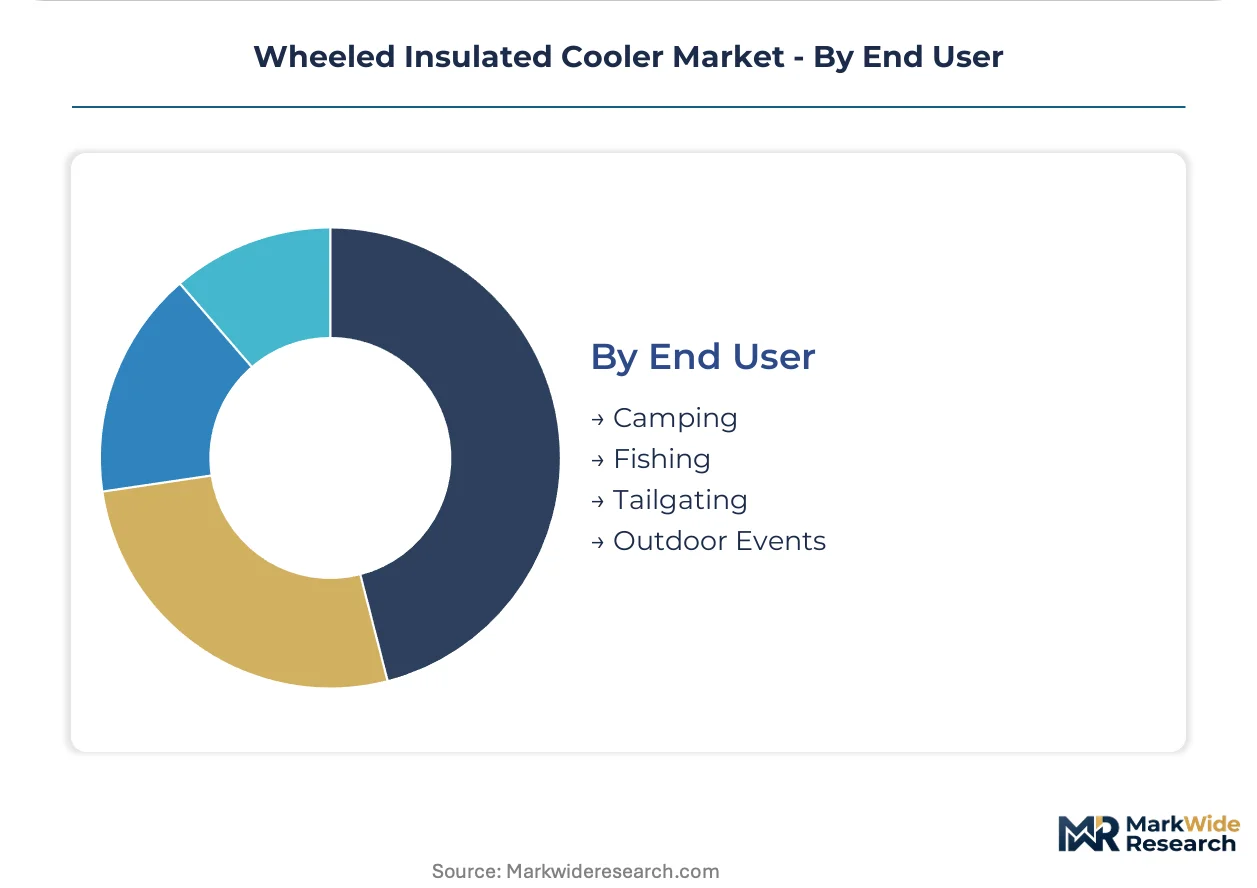
Wheeled cooler manufacturers align production assets against distinct performance tiers and mobility requirements. Product architecture, material selection, capacity scaling, and end-use intensity each create separable demand pools with divergent margin profiles and replacement cadences.
Product Type:
Cost tier stratification separates weekend recreational users from expedition-grade buyers willing to absorb premium positioning.
- Hard-Sided:Rotomolded polyethylene shells with polyurethane foam cores deliver 48–72 hour ice retention. American South state parks standardize these units for rental fleets where durability justifies higher procurement outlays.
- Soft-Sided:TPU-coated nylon constructions under 8 pounds empty weight collapse for kayak transport. Saltwater flats anglers in Florida and Texas coastal markets rotate toward these designs as deck space constraints tighten.
- Electric:Thermoelectric cooling circuits with lithium-ion battery integration enable 48-hour off-grid operation. Early adoption concentrates in desert overlanding segments where ice resupply is impractical.
- Hybrid:Passive insulation layers combined with auxiliary 12V cooling extend duration without full electric dependency. Remote medical transport operators in Arizona and New Mexico evaluate these units for vaccine distribution.
Hard-Sided holds installed capacity. Soft-Sided is rotating up the share rankings.
Material:
Application severity dictates material selection, with chemical exposure and impact frequency driving specification divergence.
- Polyethylene:Linear low-density resins dominate rotomolded construction for chemical resistance and uniform wall thickness. California SB 54 recycled content mandates are pressuring manufacturers to validate post-consumer agricultural film feedstocks from Iowa and Illinois reclaimers.
- Nylon:High-tenacity ballistic weaves with TPU coatings replace phthalate-laden vinyl under REACH compliance. European Union ECHA restrictions accelerate substitution timelines for soft-sided export production.
- Stainless Steel:Marine-grade 316L formulations resist salt corrosion in commercial fishing deck applications. Pacific Northwest salmon charter operators specify these units for hold integration.
- Aluminum:Extruded alloy frames reduce weight for aircraft catering and remote worksite transport. Oilfield service contractors in Permian Basin operations favor aluminum-core designs for helicopter sling load compatibility.
Polyethylene commands volume share. Nylon is climbing the fastest as regulatory pressure intensifies.
Capacity:
Customer type clustering around trip duration and party size creates discrete volume bands with limited cross-shopping.
- 20 QT:Personal day-trip configurations suit solo kayak anglers and urban picnic users. Direct-to-consumer channels in Colorado and Utah overlanding outfitters move these units with modular accessory rail customization.
- 50 QT:Weekend family camping standard balances portability against 72-hour retention for four-person provisions. Mass retail distribution anchors volume here.
- 70 QT:Extended expedition capacity serves backcountry hunting parties and river guide operations. Replacement cycles stretch longest in this tier due to intermittent use patterns.
- 100 QT:Commercial foodservice and tournament fishing operations demand maximum payload. CPSC child entrapment certification complexity extends new product introduction timelines by 4–6 months for latch mechanisms at this scale.
50 QT anchors manufacturer throughput. 20 QT is gaining share fastest among ultralight specialty channels.
End User:
Geography concentrates demand intensity, with climate and cultural practice shaping replacement frequency.
- Camping:Desert and alpine applications prioritize ice retention duration over weight. Solar-thermoelectric hybrid systems attract extended off-grid users in Mojave and Sonoran desert corridors.
- Fishing:Saltwater corrosion exposure and fish hold integration requirements specify marine-grade hardware. Gulf Coast and Atlantic Southeast markets sustain year-round replacement cycles.
- Tailgating:American South college football and NASCAR event calendars drive seasonal procurement spikes. Rotomolded durability justifies premium positioning for repeated transport loading.
- Outdoor Events:Catering and festival infrastructure demands foodservice-compliant construction with NSF certification. California and Texas event rental fleets standardize wheeled configurations for concession mobility.
Fishing holds established revenue concentration. Camping is expanding most quickly as off-grid recreation participation rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese rotational mold fabricators supply North American cooler manufacturers through Pearl River Delta export corridors, while domestic production clusters in Ohio and Texas serve regional demand with validated post-consumer polyethylene feedstocks.
United States
American South state parks expand wheeled cooler procurement for visitor rental fleets, with Texas and Florida coastal markets sustaining year-round replacement cycles from saltwater fishing and tailgating culture. EPA recycled content validation protocols pressure manufacturers to document agricultural film reclaim feedstocks from Iowa and Illinois. Rotomolded production concentrates in Ohio and Texas manufacturing clusters where specialized oven operation skills face workforce scarcity.
Germany
REACH compliance mandates accelerate substitution from phthalate-laden vinyl toward TPU-coated nylon in soft-sided cooler export production bound for EU markets. ECHA restrictions on flexible vinyl plasticizers reshape material specification for German outdoor retailers distributing across Central Europe. Bavarian fabricators develop vacuum-insulated panel integration for expedition-grade units serving Alpine camping segments.
China
Guangdong Province mold fabrication facilities supply critical rotational tooling to North American manufacturers, creating single-source vulnerability for premium cooler production. MIIT industrial standards govern durable goods manufacturing while domestic demand concentrates in coastal urban recreation markets. Yangtze River Delta processors refine lithium-ion thermoelectric integration for export-bound electric cooler variants.
Japan
METI energy efficiency guidelines influence thermoelectric cooling circuit specifications for domestic outdoor recreation applications. Japanese consumers prioritize collapsible soft-sided designs under 8 pounds for ultralight hiking and kayak fishing in mountain lake environments. Osaka-based distributors channel premium hard-sided imports through specialty outdoor retailers rather than mass merchant networks.
Australia
Remote medical transport operators in Northern Territory and Western Australia evaluate hybrid passive-electric coolers for vaccine distribution across desert corridors. TGA medical device adjacent standards inform thermal performance certification for clinical-grade units. Queensland saltwater charter fleets specify marine-grade stainless hardware for deck-integrated fish hold applications in Great Barrier Reef tourism operations.
Wheeled Insulated Cooler Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered price bands defined by thermal performance duration and durability certification. Mass retail distribution anchors volume throughput for injection-molded polyethylene models, while direct-to-consumer specialty channels fragment premium-tier concentration. Three archetypes dominate: rotomolded performance specialists, mass-market volume distributors, and ultralight collapsible fabricators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as manufacturers secure validated recycled feedstock chains and rotational mold technician pipelines.
Among North American-based fabricators, Yeti Coolers and ORCA Coolers exemplify premium-tier positioning through domestic manufacturing credentials and extended warranty structures, while Igloo Products anchors volume distribution across mass retail channels. These three companies represent the structural segmentation between expedition-grade performance positioning and accessible price-point penetration.
| Leading Market Players |
|---|
| Yeti Coolers |
| Igloo Products |
| The Coleman Company |
| Pelican Products |
| AO Coolers |
| ORCA Coolers |
| Bison Coolers |
| Thermos |
| RTIC |
| Others |
Value Network & Pricing Analysis
Guangdong Province mold fabrication concentration creates single-source vulnerability that compresses rotomolder pricing power while simultaneously forcing premium-tier buyers toward domestic production with validated feedstock chains. This dependency structure widens the spread between mass retail polyethylene units and expedition-grade domestic alternatives as tariff exposure and resin volatility feed through tiered cost structures.
Pricing Analysis
Vacuum-insulated panel technology commands substantial premiums over conventional polyurethane foam cores, while rotomolded polyethylene with PermaFrost-grade insulation occupies the mid-tier and injection-molded alternatives anchor economy positioning. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence and domestic manufacturing credentials. Pricing pressure stems from naphtha cracking feedstock volatility that compresses margins without commensurate retail pricing power. Mass retail channels exhibit highest price sensitivity, while expedition-grade buyers prioritize thermal performance duration over unit cost.
Supply Chain Analysis
Pearl River Delta contract manufacturers hold critical rotational mold tooling capacity serving North American premium cooler fabricators. Raw material flows draw from Saudi Arabian naphtha derivatives for polyethylene resin, Iowa and Illinois agricultural film reclaimers for post-consumer feedstocks, and Texas and Ohio manufacturing clusters for finished assembly. Single-source vulnerability in Guangdong tooling creates exposure to logistics disruption and trade policy shifts. Distribution runs through mass merchant retail for volume tiers, direct-to-consumer specialty channels for premium positioning, and state park procurement systems for institutional fleet sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wheeled insulated cooler market sits in a cyclical recovery phase driven by expanded state park outdoor recreation procurement across the American South. This public-sector demand inflection favors manufacturers with validated domestic production and extended warranty structures.
For Market Incumbents: Entrench position through backward integration into post-consumer polyethylene feedstock chains from Iowa and Illinois agricultural film reclaimers, securing California SB 54 compliance ahead of 2028 thresholds. Deepen rotational mold technician pipelines in Ohio and Texas clusters to offset workforce scarcity threatening production continuity. Defend against electric thermoelectric substitutes by extending passive cooling duration through vacuum-insulated panel integration.
For New Entrants and Emerging Players: Pursue ultralight soft-sided segments under 8 pounds for kayak angler demand in Florida and Texas coastal markets, where deck space constraints and REACH-compliant TPU-coated nylon substitution create white-space opportunity. Target direct-to-consumer channels in Colorado and Utah overlanding outfitters with modular customization services including laser-etched branding and accessory rail integration. Establish go-to-market presence through specialty retail bypass rather than mass merchant penetration.
For Investors and Strategic Acquirers: The market sits at an early-cycle expansion phase that favors domestic rotomolders with validated recycled content chains and lifetime warranty differentiation. Long-term viability hinges on regulatory tailwinds for extended producer responsibility and thermoelectric lithium-ion integration capability. Acquisition targets should demonstrate secured mold technician pipelines and offtake agreements with agricultural film reclaimers. Watch EPA recycled content validation protocol enforcement as inflection signal for feedstock cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Post-Consumer Feedstock Integration | California SB 54 compliance secures market access ahead of 2028 recycled content mandates. |
| Vacuum-Insulated Panel Adoption | Arctic research station demand validates thermal performance leap for expedition-grade positioning. |
| Direct-to-Consumer Channel Expansion | Colorado and Utah overlanding outfitters bypass mass retail with customization services. |
| Rotational Mold Technician Pipeline | Ohio and Texas workforce development offsets aging skilled labor concentration. |
| Thermoelectric Lithium-Ion Integration | Desert overlanding segments enable 48-hour off-grid cooling previously served solely by ice. |
Research Methodology
A standing panel of rotomolded manufacturing plant managers, state park procurement officers, specialty outdoor retail buyers, and agricultural film reclaimer operations leads provided ongoing calibration across the study period. Primary interviews with rotational mold technicians and CPSC certification consultants combined with secondary validation from EPA recycled content protocols, California SB 54 implementing regulations, and ECHA REACH restriction databases. Bottom-up unit shipment modeling triangulated against top-down value aggregation across product type, material, capacity, and end-user segmentation dimensions.
Scenario-bracketing framed low, base, and high cases reflecting polyethylene resin price volatility bands and state park procurement budget trajectories. Volume and value outputs across the projection horizon integrated hard-sided, soft-sided, electric, and hybrid product architectures with polyethylene, nylon, stainless steel, and aluminum material specifications. CAGRs derived from regression analysis of replacement cycle data and geographic demand intensity patterns, with thermoelectric lithium-ion adoption curves and vacuum-insulated panel penetration serving as technology-shift inputs.
Macroeconomic conditions sit as an overlay; deviation in naphtha cracking spreads and tariff schedules on Chinese rotational mold tooling would shift the trajectory. Forecasts reflect documented assumptions regarding state park budget allocations and REACH compliance substitution timelines. Quarterly review of Iowa and Illinois agricultural film reclamation capacity and Guangdong mold fabrication lead times is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Cordless Garden Equipment Market
Outdoor Gear
Camping Cooler Market
Outdoor Gear
Snow Chain Market
Outdoor Gear
North America Pocket Knives Market
Outdoor Gear
Trail Running Bags Market
Outdoor Gear
Camping Equipment and Furniture Market
Outdoor Gear
New Zealand Camping Equipment Market
Outdoor Gear
Shared Umbrella Market
Outdoor Gear
Singapore Camping Equipment Market
Outdoor Gear
Japan Camping Equipment Market
Outdoor Gear
South Korea Camping Equipment Market
Outdoor Gear
Ice Axe Market
Outdoor Gear
Deer Hunting Blinds Market
Outdoor Gear
Bicycle Bags and Bag Packs Market
Outdoor Gear
Crash Pads Market
Outdoor Gear
Camping Equipment Market