
 Hiking Backpack Water Filters Market | 2026-2036
Hiking Backpack Water Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Hiking Backpack Water Filters Market Insights
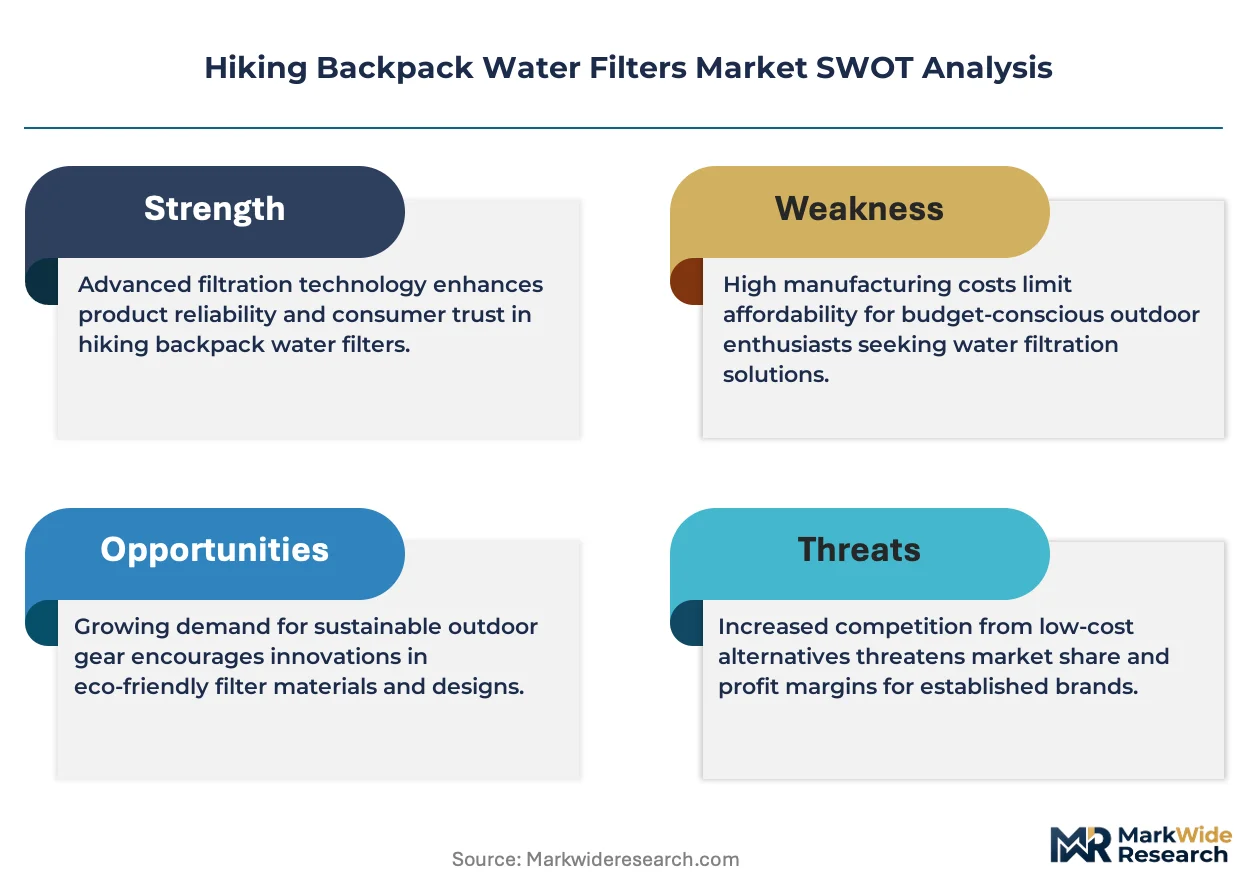
The split between premium and commodity tiers in hiking backpack water filters is hardening around certification depth and membrane longevity rather than flow rate alone. Sawyer Products leverages hollow-fiber technology to dominate the ultralight straw segment across Appalachian Trail corridors. Katadyn anchors its position through ceramic cartridge durability that appeals to extended expedition users. MSR competes on pump-system reliability in alpine environments where freeze-thaw cycles destroy lesser membranes.
Hiking backpack water filters are portable water purification devices employing hollow-fiber membranes, ceramic elements, ultraviolet LEDs, or activated carbon matrices to remove bacteria, protozoa, and viruses from untreated freshwater sources, typically processing between 0.5 and 4 liters per minute depending on mechanism. Straw filters occupy the highest volume tier due to sub-ounce packability that aligns with ultralight backpacking trends, though margin pools concentrate in ultraviolet filters where semiconductor costs create pricing power. Gravity filters sustain growth among basecamp and group scenarios where hands-free operation outweighs speed, while pump filters retain relevance in turbid water regions where pre-filtration extends element life.
EPA microbiological purifier standards and NSF/ANSI 53 certification frameworks govern product legitimacy in the United States market, forcing manufacturers to validate log-reduction claims through third-party laboratory testing. The EU's Drinking Water Directive and REACH substance restrictions shape material composition rules for brands distributing across European outdoor retail channels. Stakeholders must monitor evolving pathogen detection protocols and state-level wilderness access policies that directly influence replacement cartridge purchasing cycles.
Market Dynamics
Ultralight backpacking's gravitational pull toward sub-two-pound base weights is compressing filter form factors and forcing membrane manufacturers to sacrifice flow rate for packability, reshaping R&D priorities across the category.
Growth Catalysts
- EPA microbiological purifier standards:Third-party certification requirements under the EPA's Guide Standard validate log-reduction claims, creating legitimacy barriers that professionalize the competitive field and reward compliant manufacturers.
- Alpine lake access corridors:Pacific Northwest wilderness permit systems concentrate serious backpackers in regions where untreated surface water necessitates portable purification, driving replacement cartridge velocity.
- Hollow-fiber membrane advances:Improved pore-size consistency in polyethersulfone fibers enables lighter, more durable elements that extend field life without ceramic fragility.
Market Restraints
- Semiconductor supply concentration:Ultraviolet LED chip fabrication concentrates in East Asian foundries, exposing UV filter assemblers to geopolitical supply shocks and input cost volatility.
- Freeze-thaw membrane degradation:Residual water expansion in hollow-fiber elements destroys pore structure below 28°F, limiting reliable deployment in high-alpine environments without insulated storage protocols.
- REACH substance restrictions:EU chemical compliance frameworks constrain activated carbon sourcing and housing polymer selection, forcing reformulation cycles that delay European market entry.
Strategic Opportunities
- Basecamp gravity systems:Group-size filtration for guided expedition services remains underdeveloped relative to solo straw filters, offering margin expansion through volume-tiered SKUs.
- Thru-hiker subscription models:Appalachian and Pacific Crest Trail corridor retailers can capture recurring revenue via seasonal cartridge replacement programs tied to permit issuance calendars.
- UV-LED and graphene convergence:Emerging semiconductor-carbon composite electrodes promise simultaneous pathogen inactivation and heavy metal adsorption in single-unit designs.
Industry Challenges
- NSF/ANSI 53 certification timelines:Third-party laboratory validation for protozoa and virus log-reduction claims extends 14-18 months, compressing product launch windows against competitive pressure.
- Membrane integrity testing skill gaps:Field-serviceable filter maintenance requires consumer education on bubble-point testing and backflushing protocols that most retailers fail to deliver.
- Pre-filtration integration complexity:Turbid water regions demand sediment pre-filters that add pack weight and connection-point failure modes, complicating ultralight product positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hiking Backpack Water Filters Market |
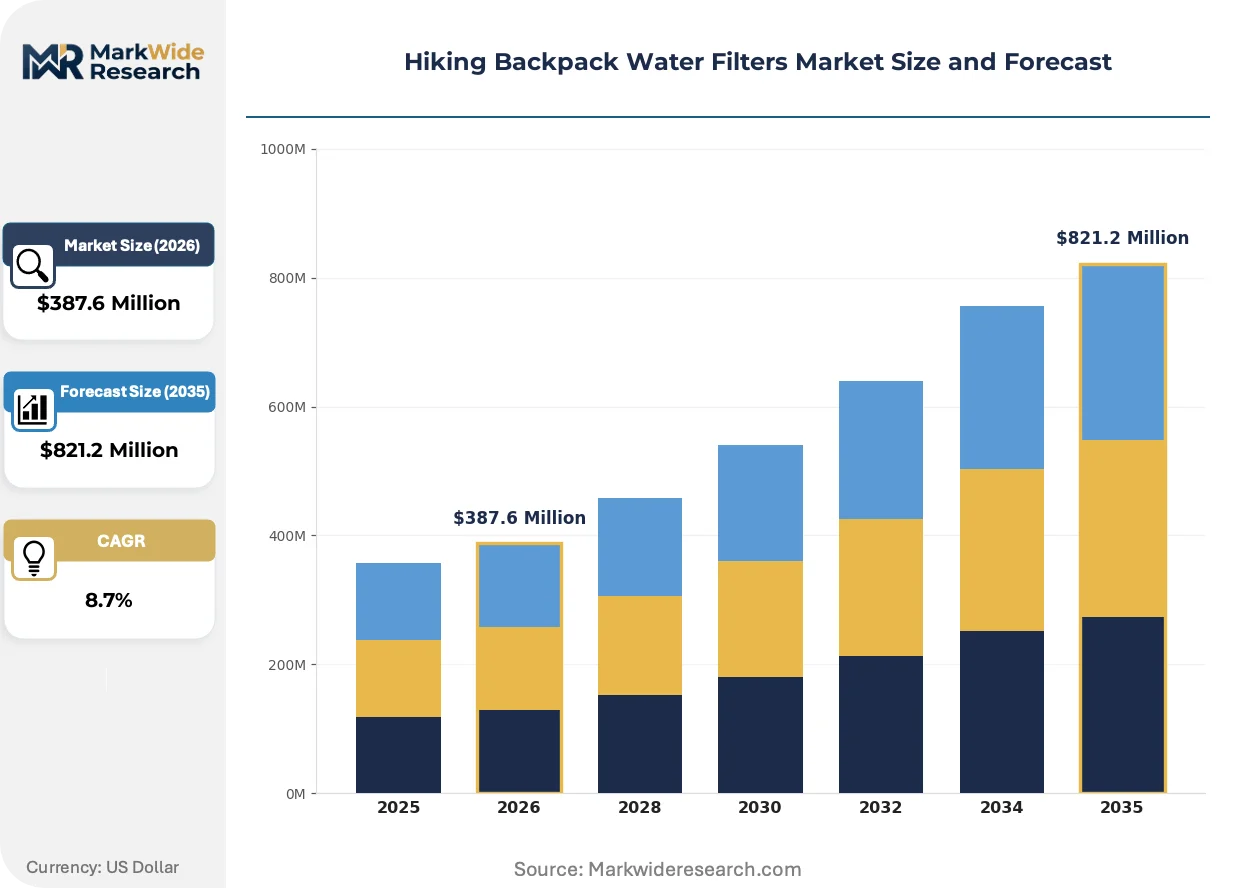
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gravity Filters, Pump Filters, Straw Filters, Ultraviolet Filters Filtration Capacity: 1 Liter, 5 Liters, 10 Liters, 15 Liters Usage Scenario: Camping, Backpacking, Emergency Preparedness, Recreational Hiking End User: Outdoor Enthusiasts, Preppers, Travelers, Survivalists |
| Companies Covered | Sawyer Products, Katadyn, MSR, Platypus, LifeStraw, HydraPak, Grayl, CNOC Outdoors, Lifestraw Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hiking Backpack Water Filters Market Trends and Innovations
Material science breakthroughs and regulatory tightening are compressing product development cycles while fragmenting buyer preferences across purification mechanisms, forcing manufacturers to defend multiple technology platforms simultaneously.
Ultraviolet LED arrays paired with optical flow sensors now deliver dose-calibrated pathogen inactivation without chemical residuals. Serious alpine users and international trekkers are adopting these systems fastest, prioritizing viral protection over sediment handling. UV semiconductor miniaturization is converging with power management chips to enable rechargeable, smartphone-integrated purification logging.
REACH substance restrictions and the EU Drinking Water Directive are tightening material composition rules for outdoor equipment sold through European retail channels. Manufacturers must now validate housing polymer safety and activated carbon sourcing through ECHA-registered supply chains. Ceramic and glass-fiber filter elements face the steepest compliance burden, pushing brands toward hollow-fiber platforms for EU distribution.
Expedition outfitters and guided services are consolidating procurement around certified filter fleets with centralized maintenance protocols, displacing individual hiker retail purchases. This buyer concentration shifts margin capture toward B2B service contracts with seasonal replacement guarantees. The Pacific Northwest and Colorado Rockies show this pattern most visibly, where permit-based access concentrates demand among commercial operators.
Hiking Backpack Water Filters Market Segmentation
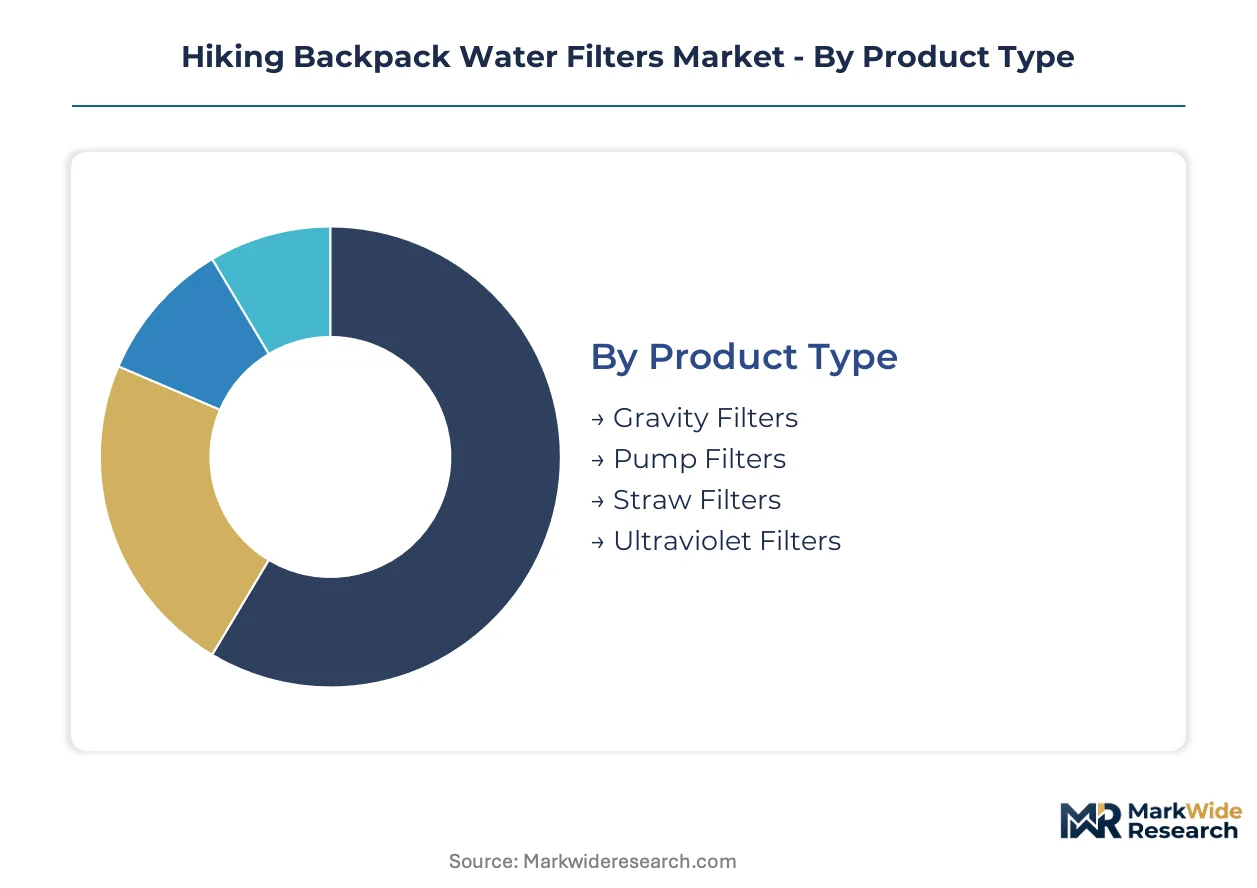
Segmentation in hiking backpack water filters reveals how purification priorities fragment across weight constraints, group size, and risk tolerance. Manufacturers must defend multiple technology platforms simultaneously as ultralight solo trekkers, guided expedition services, and emergency preppers demand incompatible form factors.
Product Type:
Customization versus standardization tensions peak in this category, with straw filters pushing extreme packability against gravity systems that sacrifice speed for hands-free operation.
- Gravity Filters:Polyethersulfone hollow-fiber membranes suspended in collapsible reservoirs process 1-4 liters per hour without pumping. Demand concentrates among guided expedition services in Colorado Rockies basecamps where group volume outweighs speed. Procurement contracts with seasonal replacement guarantees displace individual retail purchases.
- Pump Filters:Ceramic or glass-fiber elements with manual piston mechanisms excel in turbid water regions requiring pre-filtration. Alpine lake access corridors in Washington and Oregon sustain replacement cartridge velocity despite pack weight penalties.
- Straw Filters:Sub-ounce personal devices using single-stage hollow-fiber membranes align with Appalachian Trail ultralight trends.
- Ultraviolet Filters:UV-LED arrays with optical flow sensors deliver viral protection without chemical residuals.
Leading the category by volume: Straw Filters. Growing fastest: Ultraviolet Filters.
Filtration Capacity:
Volume tiers map directly to trip duration and group composition, with commercial operators driving procurement concentration at higher capacities.
- 1 Liter:Personal straw and squeeze systems dominate solo thru-hiker packouts where every ounce determines daily mileage.
- 5 Liters:Compact gravity configurations serve pair hiking and overnight camping in Pacific Northwest wilderness permit zones.
- 10 Liters:Expedition-grade pump and gravity hybrids address guided service fleets with centralized maintenance protocols.
- 15 Liters:Basecamp infrastructure for commercial operators displaces individual purchases through B2B service contracts.
Highest procurement concentration: 15 Liters via commercial contracts. Steepest expansion trajectory: 5 Liters among weekend backpackers.
Usage Scenario:
Scenario segmentation exposes divergent certification requirements, with emergency preparedness demanding EPA purifier validation that recreational hiking often bypasses.
- Camping:Car-accessible sites favor gravity systems where pack weight matters less than group throughput.
- Backpacking:Multi-day wilderness travel drives straw and pump filter adoption across Appalachian and Pacific Crest Trail corridors.
- Emergency Preparedness:EPA microbiological purifier standards govern procurement for household stockpiling and institutional resilience planning.
- Recreational Hiking:Day-trip convenience sustains bottle-integrated UV and straw segments despite lower per-unit margins.
Deepest margin pool: Emergency Preparedness. Gaining share fastest: Backpacking.
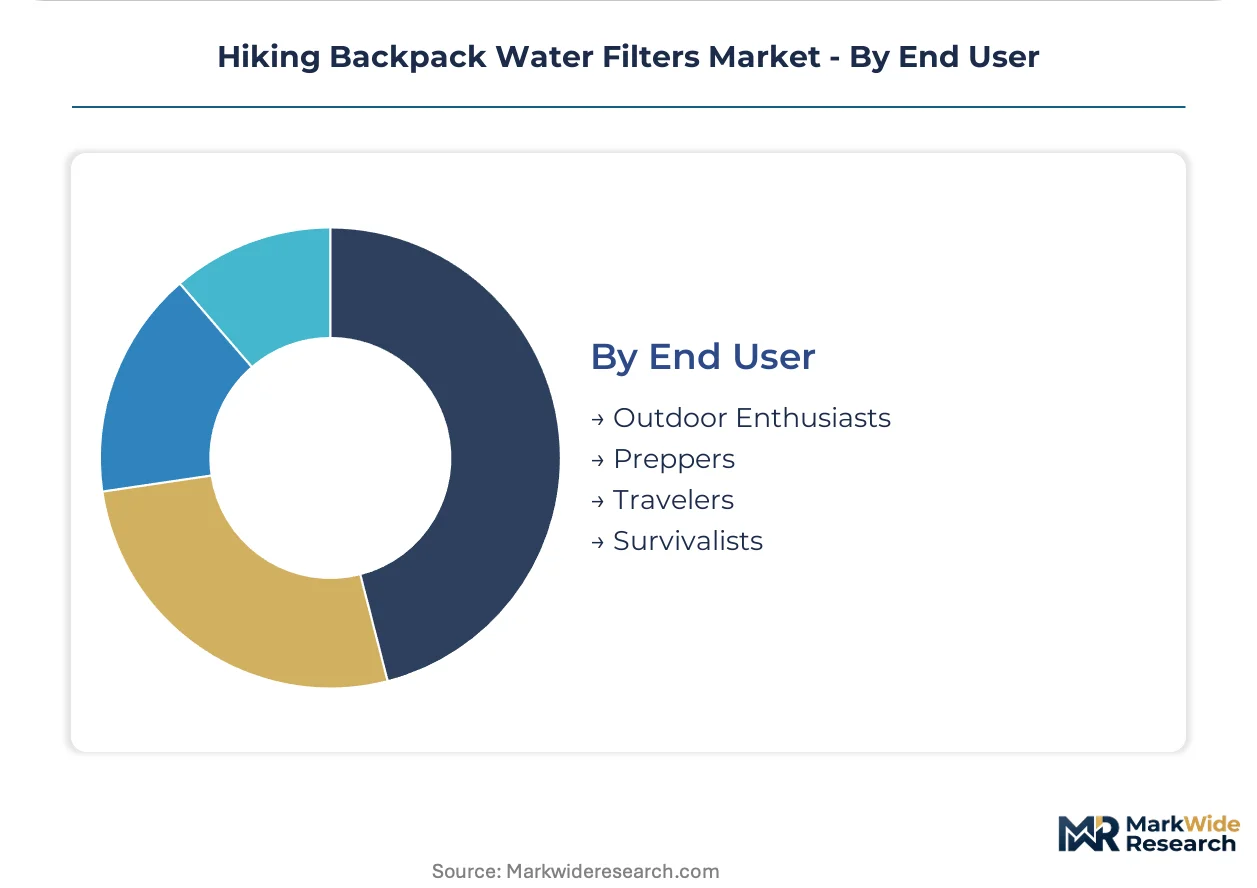
End User:
User archetypes fragment across risk perception and technical sophistication, from certification-demanding preppers to weight-obsessed thru-hikers.
- Outdoor Enthusiasts:Weekend and seasonal backpackers across alpine access regions drive replacement cartridge seasonality tied to permit issuance calendars.
- Preppers:Long-duration stockpiling demands ceramic durability and EPA validation over ultralight packability.
- Travelers:International trekkers prioritize UV viral protection in regions with questionable municipal infrastructure.
- Survivalists:Extended off-grid scenarios favor pump systems with field-serviceable components and indefinite cartridge life.
Largest addressable base: Outdoor Enthusiasts. Expanding most quickly: Travelers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boulder, Colorado anchors North American demand concentration for hiking backpack water filters, with trailhead retail clusters serving Continental Divide through-hikers and Rocky Mountain expedition outfitters.
United States
Pacific Northwest wilderness permit systems in Washington and Oregon concentrate serious backpackers where untreated alpine lake access necessitates portable purification. EPA microbiological purifier standards under the Guide Standard and Protocol govern product legitimacy and force third-party laboratory validation. Seattle-Tacoma retail corridors drive replacement cartridge velocity tied to seasonal permit issuance calendars.
Germany
Bavarian Alpine Club membership exceeding 1.5 million sustains expedition-grade filter procurement for hut-to-hut trekking routes. REACH substance restrictions and the EU Drinking Water Directive constrain activated carbon sourcing and housing polymer selection. Munich outdoor retail clusters push hollow-fiber platforms to avoid ceramic and glass-fiber compliance burdens.
Japan
Kanto region weekend mountaineers and Mt. Fuji climbing permit holders drive ultralight straw filter adoption. METI product safety standards and JIS quality certification frameworks shape import requirements for foreign manufacturers. Tokyo-Yokohama outdoor specialty retailers curate certified filter assortments for domestic alpine clubs.
Australia
New South Wales and Victoria national park backcountry permit systems generate concentrated demand for viral-protection UV systems. The Therapeutic Goods Administration (TGA) regulates water purification claims for devices marketed with health benefits. Sydney and Melbourne expedition outfitters service guided trips to Tasmania's South Coast Track and New Zealand's Te Araroa Trail.
Switzerland
Swiss Alpine Club hut networks and glacier trekking routes sustain ceramic cartridge durability preferences among extended expedition users. Swissmedic device regulations and EU market alignment requirements govern cross-border distribution. Zurich and Geneva outdoor retail clusters serve international trekkers transiting the Haute Route and Tour du Mont Blanc corridors.
Hiking Backpack Water Filters Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and membrane longevity rather than flow rate alone. The vendor base fragments across hollow-fiber membrane specialists, ceramic durability anchors, and UV semiconductor assemblers with divergent supply chain exposures. Three strategic archetypes dominate: ultralight straw specialists, expedition-grade pump system providers, and UV-LED viral protection innovators. Competitive moves concentrate on geographic expansion through European retail channel development and technology licensing for graphene-semiconductor convergence.
Within the hollow-fiber ultralight tier, Sawyer Products and CNOC Outdoors exemplify membrane miniaturization strategies that sacrifice flow rate for packability. Katadyn occupies a position in the expedition-grade ceramic segment where field-serviceable durability commands pricing power. MSR anchors the alpine reliability archetype, representing pump-system architectures engineered for freeze-thaw resilience.
| Leading Market Players |
|---|
| Sawyer Products |
| Katadyn |
| MSR |
| Platypus |
| LifeStraw |
| HydraPak |
| Grayl |
| CNOC Outdoors |
| Lifestraw Group |
| Others |
Pricing and Supply Chain Analysis
Expedition outfitter consolidation around certified filter fleets with centralized maintenance protocols is compressing margin capture toward B2B service contracts and forcing manufacturers to absorb longer replacement cycles into upfront pricing. This procurement concentration shifts supply chain priorities toward volume-tiered SKU production and seasonal inventory staging tied to permit issuance calendars in Washington and Oregon.
Pricing Analysis
Throughput-based pricing anchors the hiking backpack water filter market, with EPA microbiological purifier certification tier and membrane longevity separating premium from commodity tiers. Three-tier pricing structure across premium, standard, and economy levels reflects hollow-fiber membrane quality grades and field-serviceable component availability. Cost compression in the straw filter segment intensifies because ultralight packability demands sacrifice flow rate for membrane miniaturization. Weekend backpackers show highest price sensitivity, while guided expedition services prioritize certification depth over unit cost.
Supply Chain Analysis
UV-LED chip fabrication rests on East Asian foundries in Taiwan, South Korea, and Japan, exposing assemblers to geopolitical supply shocks. Hollow-fiber polyethersulfone membranes draw from German and US specialty polymer producers, while ceramic elements source from Swiss and Austrian mineral processors. Single-source vulnerability concentrates in semiconductor inputs for ultraviolet systems. Distribution runs through outdoor specialty retail clusters in Seattle-Tacoma, Munich, and Tokyo-Yokohama with seasonal replenishment tied to alpine access permit calendars.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hiking backpack water filters market operates as a cost-of-compliance story where EPA microbiological purifier standards under the Guide Standard and Protocol erect barrier-to-entry moats that reward third-party laboratory investment and penalize uncertified competitors.
For Market Incumbents: Anticipate margin pressure from graphene-semiconductor convergence technologies by deepening hollow-fiber membrane R&D partnerships and securing multi-year EPA certification renewals ahead of protocol updates. Ceramic cartridge specialists must defend expedition-grade positioning through field-serviceable durability claims that UV-LED systems cannot match. Vertical integration into polyethersulfone fiber production reduces input cost volatility from German specialty chemical suppliers. For New Entrants and Emerging Players: Enter via basecamp gravity systems for guided expedition services in Colorado Rockies and Pacific Northwest corridors, where procurement concentration displaces individual retail purchases and rewards volume-tiered B2B contracting. The 5-liter compact gravity segment among weekend backpackers shows lowest incumbent saturation. Go-to-market leverage rests on seasonal cartridge subscription models tied to wilderness permit issuance calendars. For Investors and Strategic Acquirers: The window for entry favors hollow-fiber membrane specialists with established EPA validation and European REACH compliance infrastructure. Long-term viability hinges on dual-technology platform defense across ultralight straw and UV-LED viral protection segments. Watch for inflection in Appalachian Trail corridor permit issuance velocity as early indicator of replacement cartridge demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EPA Certification Renewal Investment | Third-party laboratory validation under EPA Guide Standard secures legitimacy barriers against uncertified competitors. |
| Seasonal Subscription Model Launch | Cartridge replacement programs tied to Washington and Oregon permit calendars capture recurring revenue from thru-hikers. |
| Graphene-Semiconductor R&D Partnership | Composite electrode development promises simultaneous pathogen inactivation and heavy metal adsorption in single-unit designs. |
| European REACH Compliance Infrastructure | ECHA-activated carbon sourcing and housing polymer validation enable distribution through Munich outdoor retail channels. |
| Guided Expedition B2B Service Contract | Centralized maintenance protocols with seasonal replacement guarantees displace individual hiker retail purchases in Colorado Rockies. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with product managers at hollow-fiber membrane manufacturers, ceramic cartridge specialists, UV-LED assemblers, and outdoor specialty retail buyers. EPA Guide Standard documentation, NSF/ANSI 53 certification databases, and ECHA REACH substance registrations provided regulatory validation. Bottom-up triangulation across replacement cartridge velocity in Pacific Northwest permit corridors and top-down reconciliation against expedition outfitter procurement contracts established volume baselines.
Segmentation granularity modeled purification mechanism, filtration capacity tier, and usage scenario across the projection horizon, with separate treatment of commercial B2B contracts and individual retail channels. CAGRs derived from log-linear trend fitting to seasonal permit issuance patterns and replacement cycle assumptions. Forecast inputs incorporated hollow-fiber membrane pore-size consistency advances and UV-LED semiconductor miniaturization trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption or EPA protocol revision scenarios. Assumptions reflect current wilderness access policy stability and alpine lake water quality conditions. A small set of triggers—permit system overhauls, REACH substance restriction expansion, and graphene electrode commercialization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Sleeping Bag Market
Outdoor Gear
Hunting Boots Market
Outdoor Gear
Shoulder Strap Insulated Cooler Market
Outdoor Gear
Ice Axe Market
Outdoor Gear
Mexico Camping Equipment Market
Outdoor Gear
Deer Hunting Blinds Market
Outdoor Gear
Australia Camping Equipment Market
Outdoor Gear
Camp Fire Tripod Market
Outdoor Gear
Outdoor Camping Toilet Market
Outdoor Gear
Shared Umbrella Market
Outdoor Gear
Japan Camping Equipment Market
Outdoor Gear
Snow Chain Market
Outdoor Gear
Canoe Paddles Market
Outdoor Gear
Camping Cooler Market
Outdoor Gear
Fairway Mowers Market
Outdoor Gear
Japan Camping Tent Market