
 Diving Equipment Market | 2026-2036
Diving Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Diving Equipment Market Analysis
CE-certified performance-grade equipment is reorganizing purchasing patterns across the diving industry. Aqua Lung International leverages its integrated manufacturing footprint to sustain consistent supply of regulator systems to European and North American channels. Johnson Outdoors anchors its position through R&D intensity in thermal protection, while Scubapro differentiates via specialized buoyancy compensator architectures for technical diving applications.
Diving equipment encompasses self-contained underwater breathing apparatus, thermal protection garments, buoyancy control devices, and ancillary life-support gear engineered to sustain human operations at depth, with regulators typically rated for cold-water performance below ten degrees Celsius and dry suits constructed from compressed neoprene or membrane laminates to prevent hypothermia in extended exposures. The primary commercial purpose spans recreational tourism, professional marine construction, military special operations, and scientific research requiring reliable subsea mobility. Scuba regulators and buoyancy compensators command concentrated margin pools due to precision machining requirements and recurring service intervals, while wet suits face commoditization pressure from Asian manufacturing scale. End-user demand tilts toward recreational divers for volume but commercial and military segments for unit profitability and specification rigor.
EN 250 and CE marking frameworks govern European respiratory equipment standards, while the US Coast Guard and OSHA regulate commercial diving operations stateside; these bodies mandate periodic equipment inspection, training certification, and material traceability that elevate compliance costs but barrier entry for uncertified suppliers. ISO 6425 standards for dive watches and ISO 24801 training protocols further structure product development and market access across jurisdictions. Stakeholders must monitor evolving harmonization between regional certification regimes and the pace at which technical diving specifications migrate into mainstream recreational product lines.
Market Dynamics
Commercial diving operations in offshore oil and gas maintenance are expanding equipment procurement, while EN 250 breathing apparatus standards and updated CE marking requirements for personal protective equipment are tightening product certification thresholds across European supply chains.
Growth Catalysts
- Offshore energy maintenance:Aging North Sea and Gulf of Mexico infrastructure requires saturation diving systems for subsea pipeline inspection and repair, driving demand for closed-circuit rebreathers and hot-water suits rated for depths exceeding 100 meters.
- EN 250 respiratory standards:Updated European certification mandates for cold-water performance below ten degrees Celsius are accelerating replacement cycles for legacy first and second-stage regulators in recreational and professional channels.
- Southeast Asia dive tourism infrastructure:Indonesia, Thailand, and the Philippines are building professional training capacity and resort-based rental fleets, concentrating demand for entry-level buoyancy compensators and aluminum 80-cubic-foot cylinders.
Market Restraints
- Precision machining input costs:Titanium and marine-grade brass price volatility elevates bill-of-materials pressure for high-performance regulator manufacturers dependent on Swiss and Japanese component suppliers.
- Membrane dry suit supply concentration:Compressed neoprene and trilaminate fabric production clusters in Chinese and South Korean textile mills, creating single-source vulnerability for European and North American dry suit assemblers.
- CE marking friction:MDR transition timelines and notified body capacity constraints are extending certification intervals for personal protective equipment, delaying product launches by six to eighteen months.
Strategic Opportunities
- Technical diving specification migration:Sidemount and rebreather configurations developed for cave and wreck penetration are filtering into mainstream recreational lines, opening margin expansion for specialized buoyancy compensator architectures.
- Scientific research subsea mobility:Marine biology and oceanography programs in Australia and Norway are outfitting research vessels with modular diving systems supporting mixed-gas operations and extended bottom times.
- Direct-to-consumer channel development:Manufacturer-owned digital platforms are bypassing traditional dive shop networks for consumables and accessories, capturing higher attach rates for mask, fin, and snorkel bundles.
Industry Challenges
- Saturation diving medical certification:Commercial diving contractors face acute shortages of hyperbaric physicians and diving medical technicians qualified under OSHA and IMCA guidelines, constraining crew availability for deep-water projects.
- Legacy wet suit commoditization:Asian manufacturing scale has collapsed entry-level neoprene pricing, forcing brand holders to defend position through proprietary foam formulations or thermal lining technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diving Equipment Market |
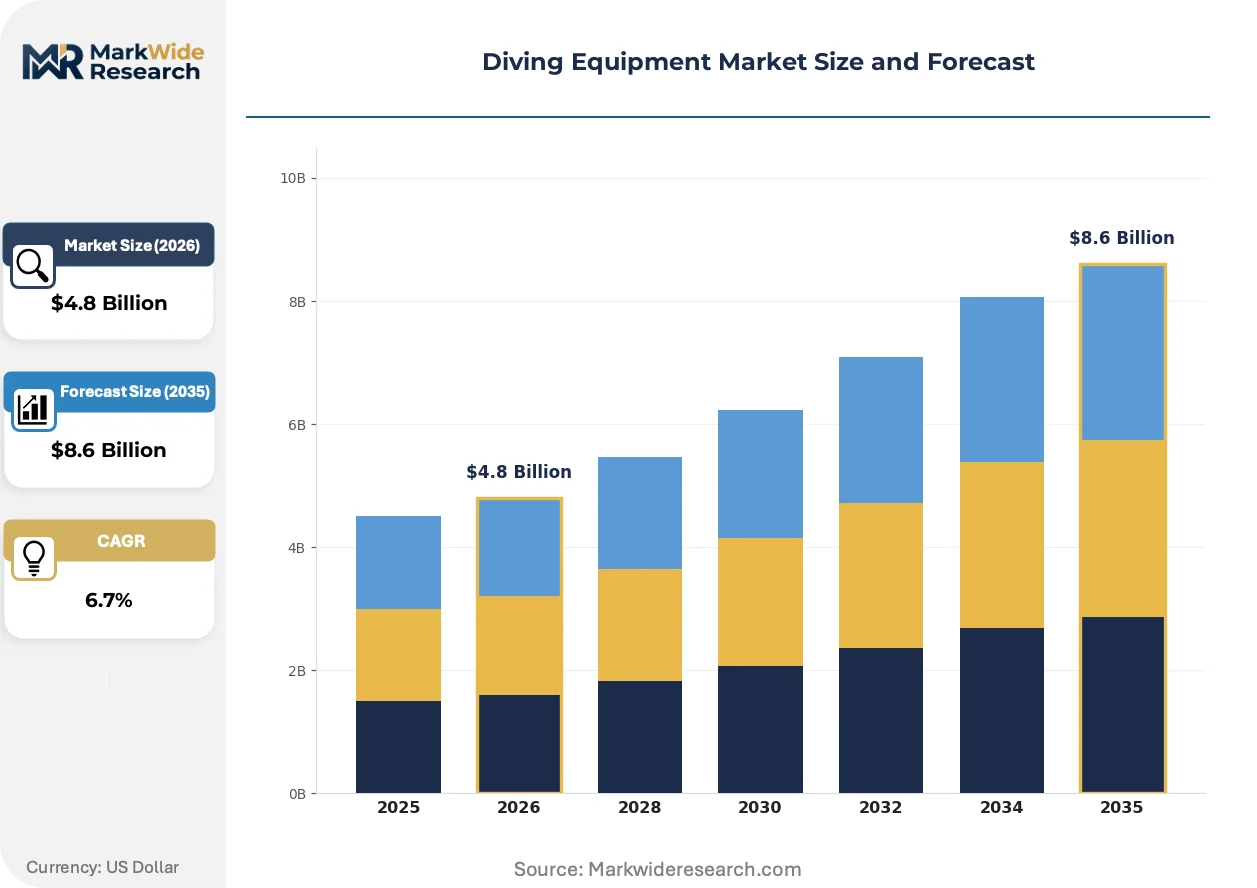
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Suits, Dry Suits, Scuba Regulators, Buoyancy Compensators End User: Recreational Divers, Commercial Divers, Military Divers, Research Institutions Water Type: Freshwater, Saltwater, Pool Diving, Cave Diving Distribution Channel: Specialty Stores, Online Retail, Wholesalers, Sports Equipment Shops |
| Companies Covered | Aqua Lung International, Johnson Outdoors, Mares, Cressi Sub, Huish Outdoors, Beuchat International, Scubapro, TUSA, Poseidon Diving Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diving Equipment Market Emerging Trajectories
Digital integration and advanced materials are reshaping equipment performance standards, while regulatory harmonization pressures and buyer behavior shifts are restructuring channel economics and certification priorities across recreational and professional segments.
Closed-circuit rebreather technology is fragmenting the technical diving equipment landscape. These systems recycle exhaled gas through chemical scrubbers and oxygen injection, extending no-decompression limits and reducing gas logistics for expedition divers and military special operations units. Adoption concentrates among cave penetration specialists and deep wreck explorers in Florida and the Mediterranean. The technology is fragmenting demand between traditional open-circuit regulators and integrated life-support platforms, compressing service revenue pools for conventional equipment retailers.
CE marking and MDR frameworks are tightening respiratory equipment traceability requirements in Europe. The updated regimes mandate batch-level material documentation and post-market surveillance reporting for breathing apparatus classified as personal protective equipment. Manufacturers serving the European Economic Area are restructuring quality management systems and supplier audit protocols to maintain notified body approvals. Dry suit and buoyancy compensator segments face accelerated compliance timelines as harmonized standards converge with marine safety directives.
Certification-driven preference shifts are altering equipment acquisition patterns among recreational divers. Training agencies including PADI and SSI are bundling equipment recommendations with course curricula, steering entry-level buyers toward specific regulator and buoyancy compensator configurations. Dive centers in Indonesia and Thailand are responding by aligning rental fleet compositions with agency equipment partnerships, compressing switching costs for first-time purchasers and locking in brand allegiance at certification stage.
Diving Equipment Market Segmentation
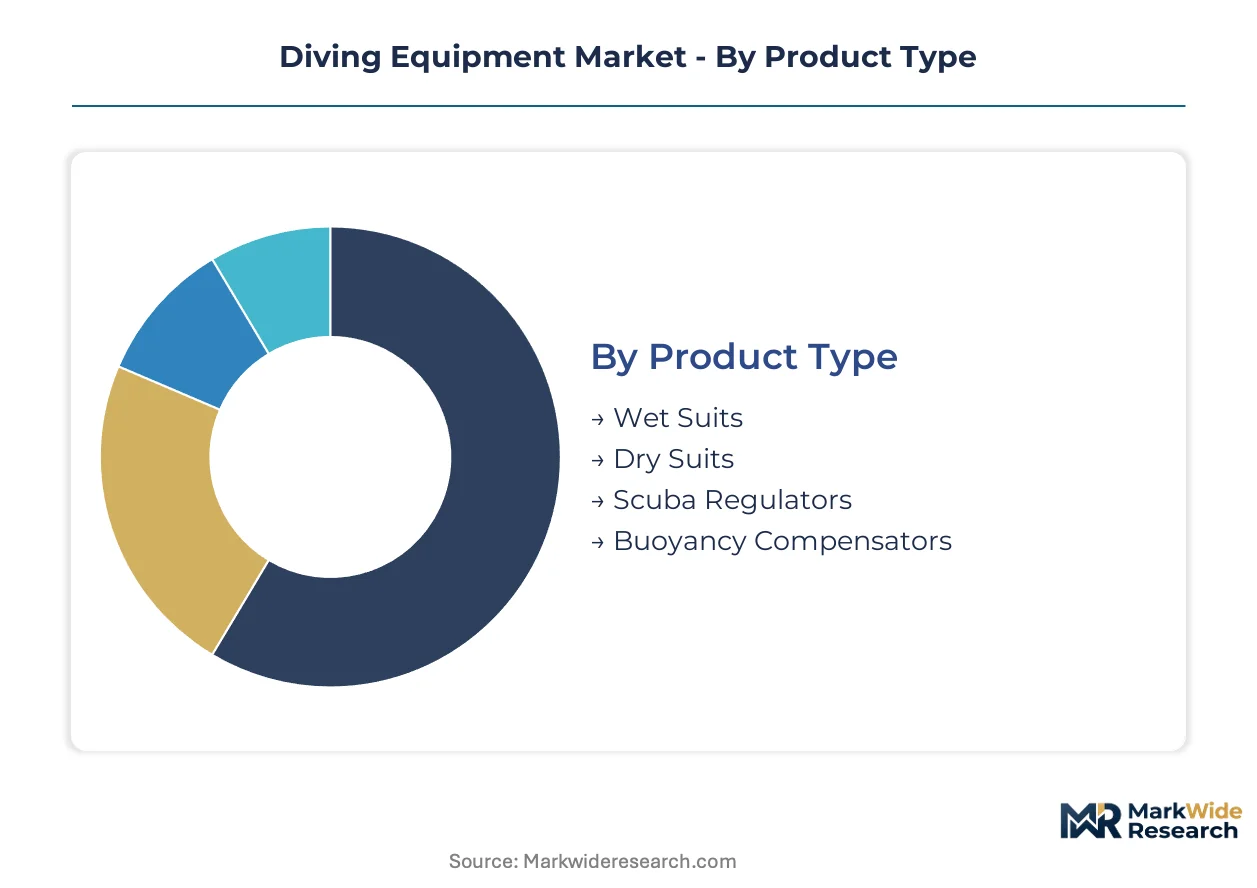
Equipment segmentation in diving markets channels procurement decisions through distinct certification requirements and end-use specifications. Product categories diverge sharply in margin structure, with precision-machined life-support equipment commanding premium positioning against commoditized thermal protection.
Product Type:
Channel economics favor different product mixes across specialty retail and direct-to-consumer platforms, with life-support equipment concentrating in certified dealer networks while accessories fragment across digital marketplaces.
- Scuba Regulators:Precision-machined first and second-stage assemblies control breathing gas delivery at depth, with titanium and marine-grade brass construction rated for cold-water performance below ten degrees Celsius. Demand concentrates in North Sea commercial operations and European recreational channels where EN 250 certification mandates are accelerating replacement cycles for legacy inventory.
- Dry Suits:Compressed neoprene and trilaminate membrane constructions prevent hypothermia during extended exposures, with hot-water suit variants supporting saturation diving below 100 meters. Procurement clusters around offshore oil and gas contractors in the Gulf of Mexico and Norwegian continental shelf where OSHA and IMCA medical protocols govern crew outfitting.
- Wet Suits:Entry-level neoprene thermal protection faces severe pricing pressure from Asian manufacturing scale, forcing brand differentiation through proprietary foam formulations.
- Buoyancy Compensators:Jacket and backplate-wing architectures manage diver trim and ascent control, with sidemount configurations gaining traction in technical diving applications.
By volume, wet suits lead. By growth pace, dry suits for commercial saturation diving are expanding most quickly.
End User:
Cost tier stratification separates specification-rigorous professional segments from price-sensitive recreational entry points, with military and research buyers demanding traceable material documentation.
- Commercial Divers:Saturation and surface-supplied diving contractors operate under OSHA and IMCA medical certification frameworks, requiring closed-circuit rebreathers and hot-water suits for pipeline inspection and subsea construction. Procurement concentrates among North Sea and Gulf of Mexico energy maintenance contractors facing acute shortages of hyperbaric physicians.
- Military Divers:Special operations units demand integrated life-support platforms with reduced acoustic and thermal signatures for covert insertion missions. Cave and wreck penetration specialists in Florida and the Mediterranean drive closed-circuit rebreather specification migration from military into technical recreational channels.
- Recreational Divers:Certification agency equipment partnerships steer entry-level buyers toward specific regulator and buoyancy compensator configurations, locking brand allegiance at training stage.
- Research Institutions:Marine biology and oceanography programs in Australia and Norway outfit research vessels with modular mixed-gas systems supporting extended bottom times.
Recreational divers dominate unit volume. Military and commercial segments capture highest per-unit profitability through specification rigor.
Water Type:
Application requirements dictate equipment durability standards, with corrosive saltwater exposure and abrasive cave environments demanding specialized material specifications.
- Saltwater:Marine-grade brass and titanium regulator components resist corrosion in tropical and temperate ocean environments where Indonesia, Thailand, and the Philippines are building dive tourism infrastructure.
- Cave Diving:Sidemount and rebreather configurations developed for Florida and Mediterranean penetration sites filter into mainstream recreational lines, opening margin expansion for specialized buoyancy compensator architectures.
- Freshwater:Reduced corrosion stress permits standard aluminum cylinder and regulator deployments in quarry and lake training sites.
- Pool Diving:Controlled environments support entry-level certification courses with minimal equipment specification requirements.
Saltwater applications generate highest equipment wear rates. Cave diving specifications are gaining share fastest as technical configurations migrate mainstream.
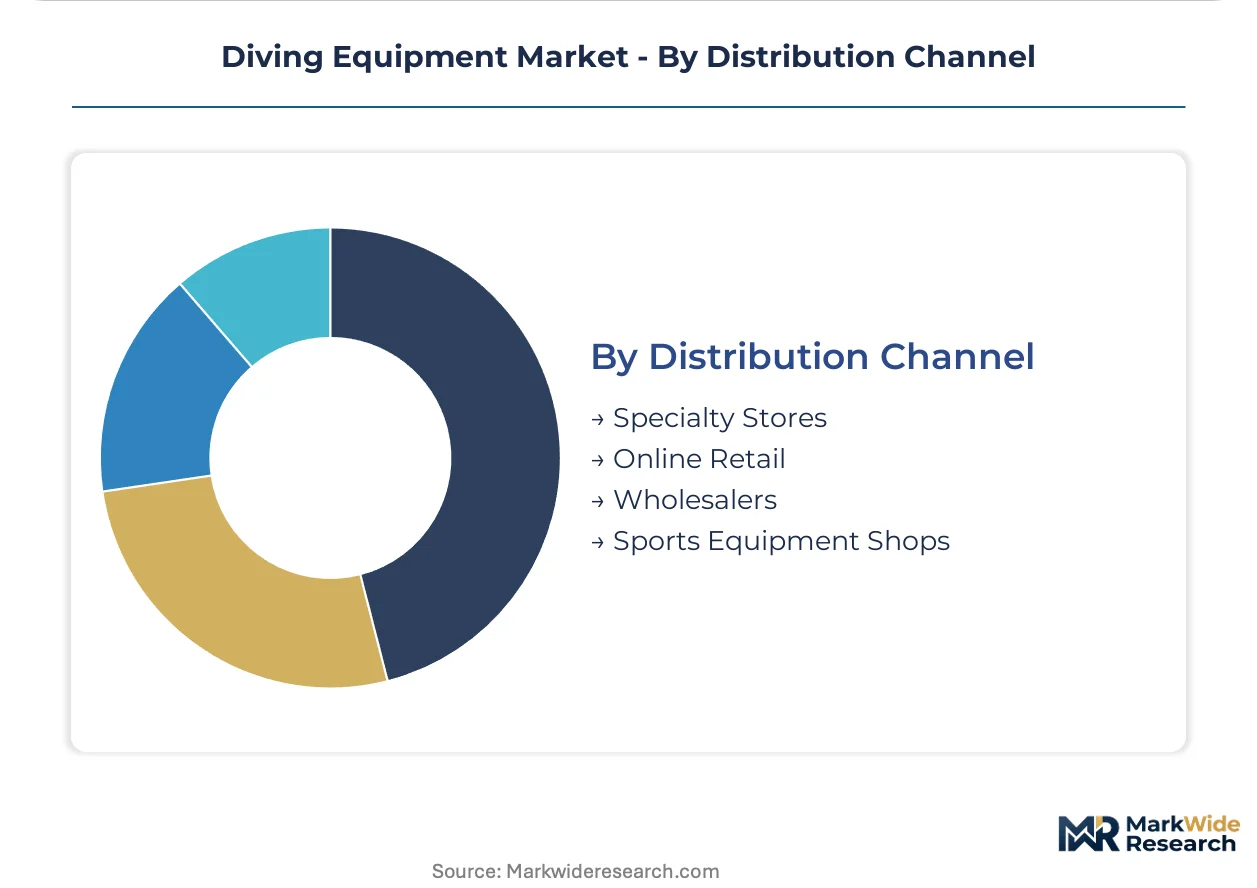
Distribution Channel:
Customer type and purchase occasion determine channel selection, with first-time buyers relying on instructor guidance while experienced divers migrate toward digital platforms.
- Specialty Stores:Certified dealer networks provide regulator service intervals and warranty support required for EN 250 and CE-marked life-support equipment, anchoring high-attachment sales of mask, fin, and snorkel bundles.
- Online Retail:Manufacturer-owned digital platforms bypass traditional dive shop networks for consumables and accessories, capturing higher margins on replacement parts and thermal protection.
- Wholesalers:Bulk procurement channels supply resort-based rental fleets in Southeast Asia with entry-level aluminum 80-cubic-foot cylinders and standardized buoyancy compensators.
- Sports Equipment Shops:Generalist retailers capture incidental snorkel and surface swim gear purchases with limited diving-specific technical support.
Specialty stores retain life-support equipment dominance. Online retail is climbing the fastest as direct-to-consumer platforms expand consumable attach rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component sourcing for precision-machined regulators clusters in Swiss and Japanese manufacturing basins, while finished equipment assembly concentrates in European and North American facilities serving distinct certification regimes. Demand generation follows dive tourism infrastructure buildouts and offshore energy maintenance schedules across four major national markets.
United States
Gulf of Mexico saturation diving contractors procure hot-water suits and closed-circuit rebreathers for pipeline inspection below 100 meters. OSHA commercial diving standards and Coast Guard regulations mandate periodic equipment inspection and material traceability. Houston anchors subsea service company headquarters, while Florida cave diving clusters drive technical configuration demand.
Germany
EN 250 cold-water regulator standards and updated CE marking under MDR frameworks accelerate replacement cycles for legacy breathing apparatus. The country's notified bodies handle personal protective equipment certification for European Economic Area access. Munich and Stuttgart host precision machining suppliers serving marine-grade brass and titanium component demand.
Indonesia
Bali and Raja Ampat dive tourism expansion concentrates demand for entry-level buoyancy compensators and rental fleet aluminum cylinders. The national government partners with PADI and SSI training agencies to build professional instructor capacity. Jakarta serves as distribution hub for Southeast Asian resort procurement.
Australia
Great Barrier Reef marine biology programs and Norwegian-collaborative oceanography vessels outfit modular mixed-gas systems for extended bottom times. The country's national safety regulator enforces equipment inspection protocols for scientific diving operations. Perth and Brisbane anchor research vessel outfitting clusters.
Norway
North Sea offshore energy maintenance drives saturation diving system procurement for aging infrastructure inspection. IMCA medical certification frameworks govern commercial diving contractor crew availability. Stavanger and Bergen concentrate subsea service company operations and hyperbaric medical facilities.
Diving Equipment Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the diving equipment landscape. Precision-machined life-support equipment concentrates margin pools among integrated manufacturers with captive regulator production, while thermal protection segments fragment across Asian contract manufacturers and brand holders defending position through proprietary formulations. Three archetypes dominate: vertically integrated European specialists with full regulator-to-suit portfolios, Asia-Pacific scale manufacturers supplying commoditized neoprene, and technical diving pure-plays commercializing military-derived rebreather architectures. Competitive dynamics center on CE marking certification speed and direct-to-consumer channel capture for consumables.
Within the integrated manufacturing tier, Aqua Lung International and Scubapro exemplify archetypes combining European regulatory compliance with broad product coverage. Johnson Outdoors occupies a position bridging recreational volume and specification-rigorous commercial segments. These three entities represent distinct strategic postures: Swiss-French heritage with global distribution networks, Italian technical specialization migrating military configurations mainstream, and American multi-brand portfolio management across thermal and life-support categories.
| Leading Market Players |
|---|
| Aqua Lung International |
| Johnson Outdoors |
| Mares |
| Cressi Sub |
| Huish Outdoors |
| Beuchat International |
| Scubapro |
| TUSA |
| Poseidon Diving Systems |
| Others |
Supply Flow & Price Mechanics
Ninety-day regulator component lead times from Swiss and Japanese precision machining basins concentrate pricing power among integrated manufacturers with captive titanium and marine-grade brass sourcing, while Asian wet suit assemblers face margin compression from neoprene spot market volatility. This inventory-to-pricing linkage rewards backward integration into component production and punishes brand holders dependent on single-source textile mills.
Pricing Analysis
EN 250 cold-water certification dictates the pricing tier structure across European recreational and professional channels, separating titanium-construction premium regulators from standard aluminum-brass configurations and entry-level rental fleet units. Price differentiation hinges on certification grade and after-sales service bundling, with CE marking friction under MDR timelines compressing margins for mid-tier suppliers awaiting notified body approval. Pricing pressure stems from Asian manufacturing scale in wet suits, forcing proprietary foam formulation investments to defend position. Commercial diving contractors exhibit lowest price sensitivity due to OSHA-mandated traceability requirements, while Southeast Asian resort operators drive volume at economy tiers.
Supply Chain Analysis
Strait of Malacca transit chokepoints expose membrane dry suit fabric shipments from Chinese and South Korean textile mills to logistics disruption, elevating inventory carrying costs for European and North American assemblers. Component sourcing draws from Switzerland and Japan for precision-machined regulator parts, China and South Korea for compressed neoprene and trilaminate membranes, and Italy and Germany for buoyancy compensator hardware. Single-source vulnerability concentrates in notified body capacity constraints extending CE certification intervals. Distribution runs through certified specialty dealer networks for life-support equipment, with manufacturer direct-to-consumer platforms capturing consumable and accessory attach rates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical diving specification migration fragments demand into specialized niches, creating white-space opportunities for entrants with rebreather and sidemount expertise while pressuring incumbents defending commoditized recreational volumes.
For Market Incumbents: Shield service revenue pools by accelerating regulator replacement cycle capture through EN 250 certification fast-tracking and captive aftermarket service network expansion. Counter closed-circuit rebreather displacement of conventional open-circuit equipment by integrating life-support platform architectures across recreational and technical lines. Deepen backward integration into titanium component machining to offset Swiss and Japanese supplier price volatility. For New Entrants and Emerging Players: CE marking fast-track partnerships with German notified bodies anchor European market access for specialized buoyancy compensator architectures targeting cave and wreck penetration segments. Southeast Asian dive tourism infrastructure buildouts in Indonesia and Thailand represent the most penetrable geography, with resort-based rental fleet procurement favoring standardized aluminum cylinder and entry-level buoyancy compensator bundles. Direct-to-consumer digital platforms bypass established dealer networks for mask, fin, and snorkel consumables. For Investors and Strategic Acquirers: Long-term, this sits as a certification-moat play because regulatory harmonization under EN 250, MDR, and OSHA frameworks elevates compliance costs that disproportionately burden sub-scale competitors. Target acquisition archetypes include technical diving pure-plays with military-derived rebreather intellectual property and European notified body relationships. Monitor IMCA hyperbaric physician certification rates as the inflection signal—acute shortages constrain commercial diving crew availability and equipment utilization.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Partnership | MDR transition timelines compress certification intervals for CE-marked breathing apparatus. |
| Direct-to-Consumer Platform Launch | Manufacturer-owned digital channels capture higher attach rates for mask, fin, and snorkel bundles. |
| Technical Diving Specification Migration | Sidemount and rebreather configurations from military channels filter into mainstream recreational lines. |
| Backward Integration into Component Machining | Captive titanium and marine-grade brass production offsets Swiss and Japanese supplier concentration. |
| Southeast Asian Distribution Hub Establishment | Jakarta and Bangkok anchor resort-based rental fleet procurement for Indonesia, Thailand, and Philippines. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EN 250 certification databases, OSHA incident reports, and IMCA operational guidelines, with bottom-up equipment unit estimates triangulated against top-down dive tourism expenditure flows. Primary interviews engaged commercial diving contractors, hyperbaric physicians, PADI course directors, and resort procurement managers across the United States, Germany, Indonesia, and Norway. Secondary sources included notified body approval registries, customs trade data for titanium and neoprene imports, and training agency certification statistics.
Segmentation dimensions modeled span product type, end user archetype, water application environment, and distribution channel, with growth trajectories derived from replacement cycle analysis under evolving regulatory standards across the projection horizon. Forecast inputs incorporated EN 250 cold-water performance mandate adoption curves, MDR notified body capacity constraints, and Southeast Asian dive tourism infrastructure buildout schedules. CAGRs reflect equipment procurement intensity per certified diver and commercial saturation diving project pipeline visibility.
Decision-makers should treat outputs as directional under assumptions of sustained offshore energy maintenance expenditure and stable CE marking harmonization timelines; material deviation would warrant model refresh. Specific risks include titanium price volatility, hyperbaric physician certification shortages constraining commercial crew availability, and MDR implementation delays extending product launch intervals. Revision becomes warranted when IMCA medical certification backlogs exceed twelve-month clearing thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Snow Chain Market
Outdoor Gear
Shared Umbrella Market
Outdoor Gear
Ice Axe Market
Outdoor Gear
Diving Regulator Market
Outdoor Gear
Beach Umbrella Market
Outdoor Gear
Sleeping Bag Market
Outdoor Gear
North America Robotic Lawn Mower Market
Outdoor Gear
Bicycle Bags and Bag Packs Market
Outdoor Gear
Canoe Paddles Market
Outdoor Gear
Rooftop Tent Market
Outdoor Gear
Camping Cooler Market
Outdoor Gear
Camping Gas Canister Market
Outdoor Gear
Singapore Camping Equipment Market
Outdoor Gear
Fairway Mowers Market
Outdoor Gear
Mexico Camping Equipment Market
Outdoor Gear
Europe Camping Equipment Market