
 Japan Camping Tent Market | 2026-2036
Japan Camping Tent Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Camping Tent Market Insights
Corporate retreat demand is pivoting toward lightweight expedition-grade shelters. Snow Peak leverages its heritage in titanium cookware to extend brand authority into premium tent lines. Montbell sustains R&D intensity through its Osaka-based design center, specializing in four-season alpine shelters. Coleman Japan dominates mass-market distribution through its control of big-box retail channels nationwide.
A camping tent is a portable, framed shelter constructed from waterproof fabrics such as ripstop nylon or silicone-coated polyester, supported by aluminum or carbon fiber poles, designed to protect occupants from precipitation, wind, and ultraviolet exposure during temporary outdoor habitation. Dome configurations occupy the largest volume share due to their structural simplicity and wind resistance, while geodesic designs command the highest margin pools among technical users. Tunnel shelters lead growth within the adventure expeditions application segment as Japanese alpine clubs prioritize weight-to-space efficiency for multi-day traverses.
METI guidelines for outdoor recreation infrastructure, JIS L 1091 flame-resistance standards for textile products, and the Consumer Affairs Agency's product safety labeling requirements collectively shape design specifications and market access for domestic manufacturers. PMDA oversight of insect-repellent treated fabrics adds compliance layers for tents marketed with integrated bug protection. Stakeholders must monitor how METI's next outdoor industry stimulus package redefines subsidy eligibility for domestically manufactured shelters.
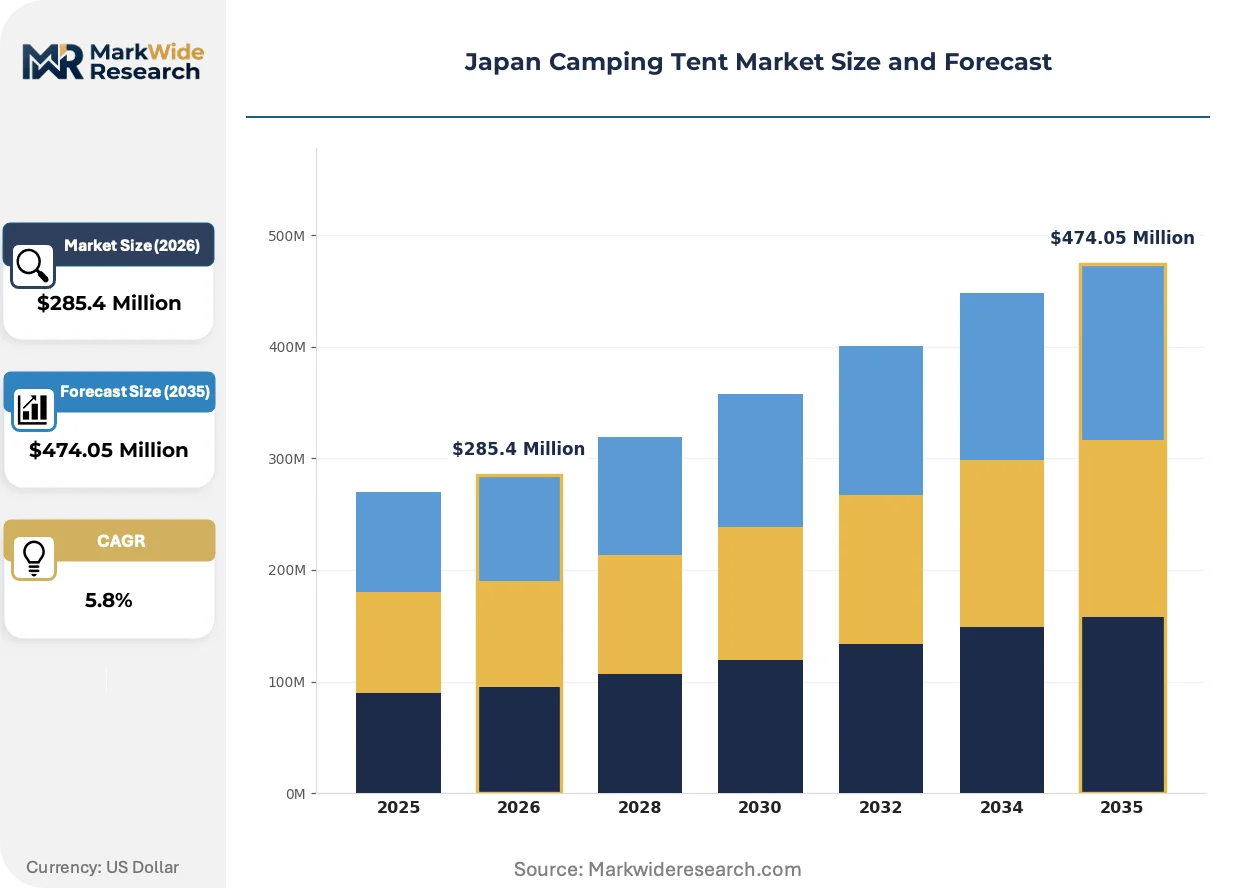
Market Dynamics
METI's outdoor recreation promotion policies are restructuring demand patterns across Japan's camping tent sector, channeling urban consumers toward mountain-adjacent prefectures while tightening compliance requirements for domestic manufacturers under JIS L 1091 flame-resistance standards.
Growth Catalysts
- Expedition-grade shelter demand:Corporate retreat planners now specify lightweight alpine-grade tents for team-building programs, compressing procurement cycles for technical shelters.
- METI infrastructure subsidies:The ministry's outdoor recreation stimulus directs public investment toward trailhead facilities, expanding accessible camping zones within two hours of Greater Tokyo.
- Ripstop nylon innovation:Silicone-coated variants with enhanced tear resistance are penetrating the solo leisure segment, replacing heavier polyester constructions.
Market Restraints
- Aluminum pole cost volatility:Aerospace-grade 7000-series aluminum supply concentrates among a limited supplier base, creating input price instability for mid-tier manufacturers.
- PMDA compliance layering:Insect-repellent fabric treatments trigger pharmaceutical device oversight, extending certification timelines and raising registration costs for integrated bug-protection tents.
- Carbon fiber substitution limits:Premium pole materials remain cost-prohibitive for mass-market lines, constraining weight reduction across standard dome configurations.
Strategic Opportunities
- Kyushu prefecture expansion:Underpenetrated volcanic terrain camping zones offer whitespace for distribution partnerships with regional outdoor retailers.
- Four-season alpine convergence:Integration of geodesic engineering with tunnel shelter space efficiency targets Japanese Alpine Club procurement specifications.
- Consumer Affairs Agency labeling streamlining:Proposed digital QR-code safety disclosure requirements would reduce packaging compliance costs for direct-to-consumer channels.
Industry Challenges
- Pattern-making talent scarcity:Technical designers capable of optimizing cut layouts for silicone-coated fabric waste reduction command premium compensation in Osaka and Tokyo manufacturing clusters.
- JIS L 1091 testing backlog:Third-party laboratory capacity constraints extend flame-resistance certification timelines, delaying seasonal product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Camping Tent Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dome, Tunnel, Cabin, Pop-Up, Geodesic, Teepee Material: Polyester, Nylon, Canvas, Oxford Cloth, Ripstop Fabric, PVC Application: Recreational Camping, Adventure Expeditions, Event Hospitality, Education Camps, Eco-Tourism, Survival Training End User: Outdoor Enthusiasts, Campgrounds, Youth Groups, Corporate Retreats, Tour Operators, Wildlife Researchers |
| Companies Covered | Big Agnes Japan, Naturehike Japan, Montbell, Lafuma Japan, Locus Gear, Snow Peak, Hilleberg Japan, Nigor Net, Coleman Japan, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Camping Tent Market Trends and Innovations
Fabric technology convergence with regulatory digitization and buyer behavior fragmentation is compressing traditional product lifecycles across Japan's camping tent supply base.
Silicone-impregnated ripstop nylon with integrated thermal reflective coatings is electrifying the four-season shelter category. Alpine expedition buyers and high-altitude guides are adopting these constructions at accelerated rates. The technology is compressing the performance gap between single-wall and double-wall designs, forcing established manufacturers to recalibrate R&D allocation.
METI's proposed outdoor industry stimulus revision tightens domestic manufacturing requirements for subsidy eligibility. Domestic tent producers must demonstrate in-country assembly and JIS-certified fabric sourcing to qualify. Technical shelter specialists with captive Osaka-based production facilities are repositioning supply chains to capture these incentives.
Multi-generational family units now specify modular tent systems with interconnecting canopy extensions through specialty outdoor retailers rather than mass-market channels. Specialty retailers in Saitama and Yamanashi prefectures are displacing big-box dominance for purchases above mid-tier price points. This rotation concentrates margin capture among curated-assortment distributors with technical staff expertise.
Japan Camping Tent Market Segmentation
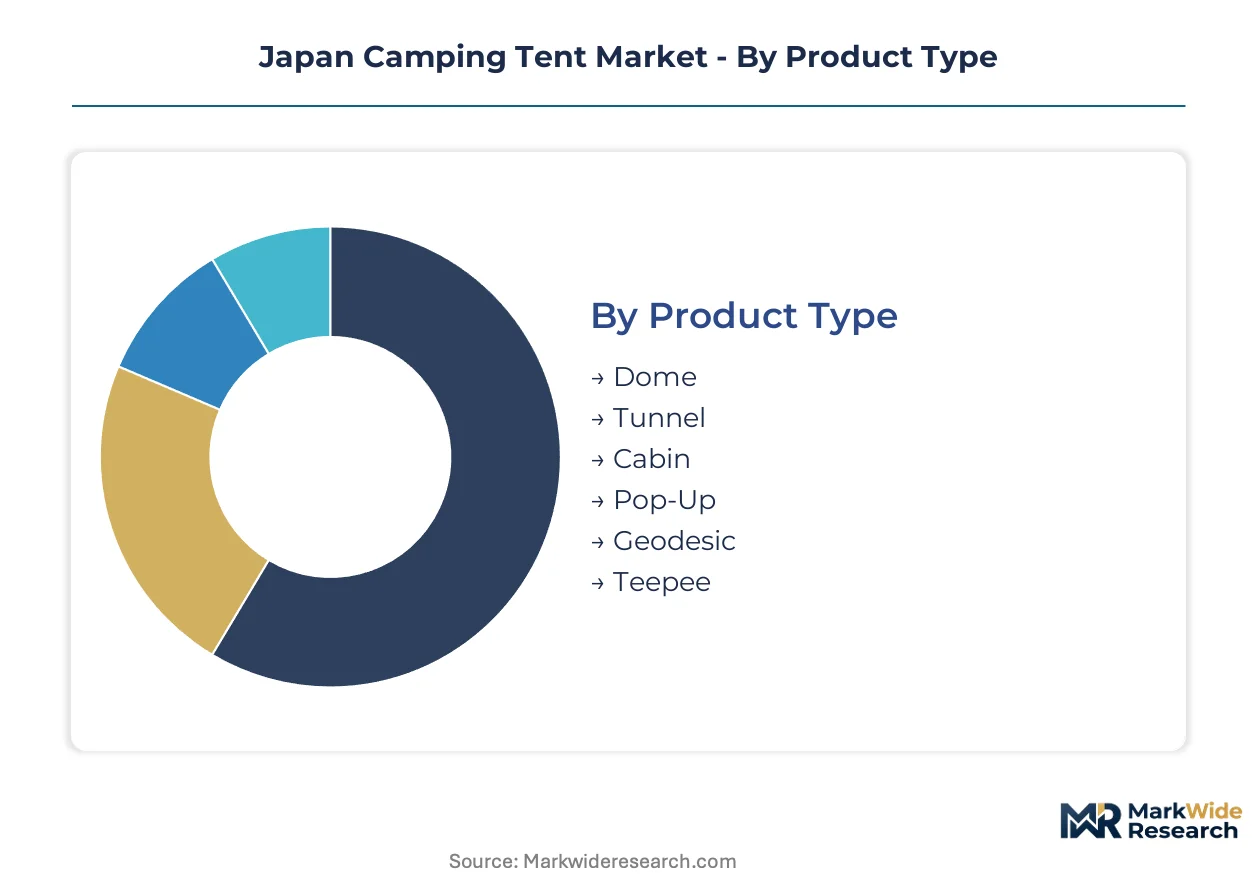
Japan's camping tent market segments reflect divergent compliance burdens across product architectures and use environments. METI infrastructure subsidies and JIS L 1091 flame-resistance standards create asymmetric certification costs that reshape competitive positioning within each category.
Product Type:
JIS L 1091 flame-resistance certification applies uniformly across all configurations, yet testing complexity varies with structural intricacy and pole-sleeve integration.
- Dome:Curved pole architecture creates self-supporting structures with minimal guyline dependency. Solo leisure campers in Saitama and Yamanashi prefectures favor these configurations for their wind resistance and rapid pitch times.
- Tunnel:Extended rectangular footprints maximize interior volume-to-weight ratios for multi-day alpine traverses. Japanese Alpine Club procurement specifications prioritize these designs for weight-to-space efficiency in volcanic terrain camping zones.
- Cabin:Near-vertical walls and standing-height clearance suit multi-generational family units seeking extended basecamp comfort. Greater Tokyo Area retailers report strongest demand for modular variants with interconnecting canopy extensions.
- Pop-Up:Pre-tensioned spring-pole mechanisms enable sub-minute deployment for casual recreational users. Limited structural load capacity restricts application to low-wind campground environments.
- Geodesic:Intersecting pole triangles distribute snow and wind loads across multiple stress points. Technical users accept premium pricing for four-season alpine shelters engineered to Osaka-based design specifications.
- Teepee:Single central pole with circular ground plans revives traditional silhouettes for eco-tourism operators. Fabric panels require specialized pattern-making to minimize silicone-coated ripstop nylon waste.
Dome configurations sit at the top of the volume ranking, with Tunnel shelters climbing the fastest.
Material:
Raw material selection determines JIS certification pathways, with synthetic polymers facing distinct flame-resistance testing protocols versus natural fiber constructions.
- Polyester:Polyurethane-coated variants dominate mass-market lines through cost-controlled supply chains. Big-box retail channels favor these constructions for price-sensitive entry-level buyers.
- Nylon:Silicone-impregnated ripstop variants with enhanced tear resistance penetrate the solo leisure segment. Aerospace-grade 7000-series aluminum pole compatibility drives specification in lightweight expedition-grade shelters.
- Canvas:Heavy cotton duck constructions with natural breathability suit extended-stay campground operators. Weight penalties limit adoption to vehicle-accessible camping zones.
- Oxford Cloth:Basket-weave polyester with thicker yarn counts resists abrasion in high-traffic event hospitality applications. Corporate retreat planners specify these for durability in repeated deployment cycles.
- Ripstop Fabric:Reinforced grid patterns prevent tear propagation in technical alpine environments. Integrated thermal reflective coatings compress the performance gap between single-wall and double-wall designs.
- PVC:Welded seam constructions deliver waterproof integrity for survival training scenarios with prolonged precipitation exposure. Stiffness and weight relegate application to institutional procurement.
Polyester captures the highest shipment volumes, while Ripstop Fabric gains share fastest among specialty retailers.
Application:
End-use environment dictates PMDA oversight layers, with insect-repellent fabric treatments triggering pharmaceutical device compliance in specific outdoor recreation contexts.
- Recreational Camping:Weekend leisure use in designated campgrounds within two hours of Greater Tokyo. METI trailhead facility subsidies expand accessible zones for family and solo campers.
- Adventure Expeditions:Multi-day traverses across volcanic terrain requiring four-season shelter performance. Alpine club procurement cycles compress for lightweight tunnel and geodesic configurations.
- Event Hospitality:Temporary accommodation for festivals and corporate gatherings. Rapid deployment and climate control integration drive specification in Kyushu prefecture expansion zones.
- Education Camps:School and youth group programs with standardized equipment procurement. Durability and simplified maintenance outweigh weight considerations in institutional buying.
- Eco-Tourism:Low-impact shelters for wildlife observation and nature immersion. Teepee and canvas constructions align with experiential positioning in underpenetrated regional markets.
- Survival Training:Military and civilian preparedness programs demanding extreme-condition reliability. PVC and reinforced ripstop constructions dominate this specification-intensive segment.
Recreational Camping anchors volume demand, with Adventure Expeditions showing the steepest expansion trajectory.
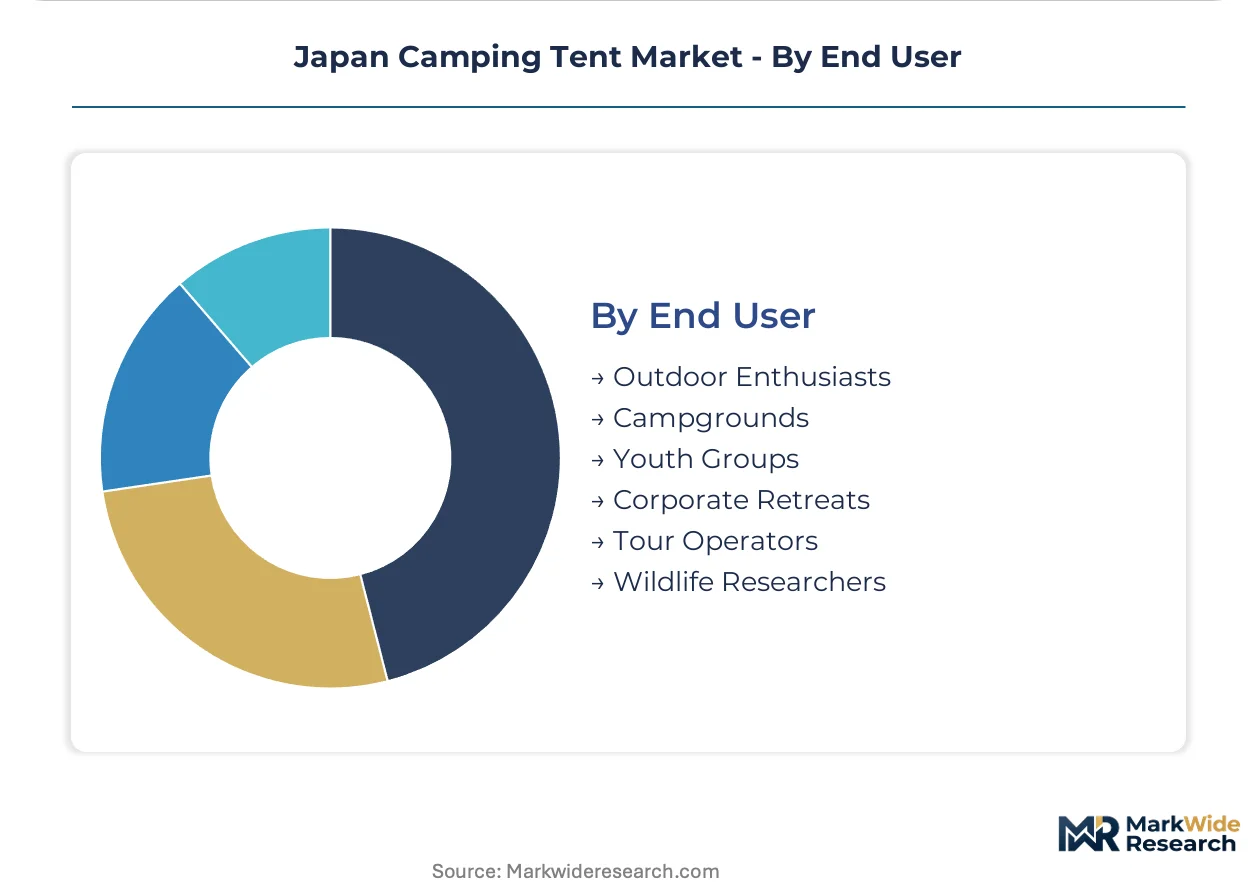
End User:
Buyer sophistication and procurement scale create tiered pricing structures across consumer, institutional, and commercial segments.
- Outdoor Enthusiasts:Individual consumers researching technical specifications through specialty retailers. Staff expertise in Saitama and Yamanashi prefecture stores displaces big-box dominance above mid-tier price points.
- Campgrounds:Fixed-site operators purchasing durable cabin and dome inventories for rental programs. Volume procurement leverages direct manufacturer relationships.
- Youth Groups:School and scouting organizations with standardized equipment mandates. Education camp applications prioritize durability over weight optimization.
- Corporate Retreats:Team-building program planners now specifying lightweight expedition-grade shelters. Procurement cycles compress as alpine-grade specifications displace recreational-grade alternatives.
- Tour Operators:Multi-day package providers requiring reliable inventory for repeated client exposure. Event hospitality and eco-tourism applications demand rapid deployment capabilities.
- Wildlife Researchers:Scientific fieldwork teams needing extended-stay shelters in remote locations. Survival training specifications overlap with specialized weatherproofing requirements.
Outdoor Enthusiasts represent the largest addressable base, with Corporate Retreats expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Tokyo anchors demand concentration for Japan's camping tent sector, with metropolitan consumers accessing mountain trailheads within two hours driving procurement patterns across adjacent prefectures.
Kanto/Tokyo
Solo leisure campers and multi-generational families drive retail volume through specialty retailers in Saitama and Yamanashi prefectures. METI trailhead facility subsidies expand accessible camping zones within the two-hour access perimeter. Manufacturing clusters in eastern Tokyo bay areas supply mass-market distribution channels.
Kansai/Osaka
Technical shelter specialists concentrate R&D capabilities in Osaka-based design centers specializing in four-season alpine constructions. JIS L 1091 flame-resistance certification timelines create competitive bottlenecks for regional manufacturers. Pattern-making talent scarcity commands premium compensation across the manufacturing cluster.
Kyushu
Underpenetrated volcanic terrain camping zones offer whitespace for distribution partnerships with regional outdoor retailers. Event hospitality applications drive rapid deployment specifications for festival and corporate gathering infrastructure. Regional retailers displace big-box dominance for purchases above mid-tier price points.
Chubu/Nagoya
Corporate retreat planners specify lightweight expedition-grade shelters for team-building programs across mountain-adjacent prefectures. PMDA oversight of insect-repellent treated fabrics adds compliance layers for integrated bug-protection tents. Aerospace-grade aluminum supply chains concentrate among limited supplier bases creating input volatility.
Hokkaido
Extended-stay campground operators favor durable cabin and dome inventories for rental programs in vehicle-accessible zones. Snow load specifications drive geodesic engineering adoption among technical users. Regional procurement cycles compress as alpine-grade specifications displace recreational-grade alternatives.
Japan Camping Tent Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers recalibrate R&D allocation between mass-market lines and technical alpine offerings. The vendor base fragments across three structural tiers: heritage outdoor brands with captive production, specialty technical fabricators with design-center capabilities, and mass-market distributors controlling big-box retail channels. Two strategic archetypes define competitive positioning: Osaka-based R&D specialists optimizing silicone-coated fabric constructions, and Tokyo-proximate manufacturers leveraging METI subsidy eligibility. M&A activity concentrates among regional outdoor retailers seeking curated-assortment positioning, while capacity expansion focuses on domestic assembly lines qualifying for infrastructure stimulus.
Within the heritage brand tier, Snow Peak and Montbell exemplify divergent approaches to technical shelter authority, with the former extending titanium cookware heritage into premium tent lines and the latter sustaining R&D intensity through captive Osaka-based design centers. Coleman Japan occupies a position anchoring mass-market distribution through nationwide big-box retail channel control. These three companies represent the spectrum from expedition-grade engineering to volume-driven accessibility.
| Leading Market Players |
|---|
| Big Agnes Japan |
| Naturehike Japan |
| Montbell |
| Lafuma Japan |
| Locus Gear |
| Snow Peak |
| Hilleberg Japan |
| Nigor Net |
| Coleman Japan |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists with captive Osaka-based production facilities anchor supply behavior and pricing discipline through in-house pattern-making capabilities and direct control over silicone-coated fabric sourcing. Their integration buffers margin pressure from aerospace-grade aluminum volatility while METI domestic manufacturing subsidies reward qualifying assembly lines with cost offsets that compress retail price points for technical shelters.
Pricing Analysis
Distributor margin layers concentrate pricing power among curated-assortment specialty retailers in Saitama and Yamanashi prefectures, where staff expertise commands premium positioning above big-box channels. Three-tier pricing structure across premium, standard, and economy levels separates geodesic alpine shelters from dome configurations and entry-level pop-up designs. Cost compression in mid-tier polyester constructions is intensifying because polyurethane-coated fabric supply chains face input volatility from petroleum derivatives. Corporate retreat planners show least price sensitivity for expedition-grade specifications, while solo leisure campers in Greater Tokyo drive volume through economy-tier procurement.
Supply Chain Analysis
Single-source vulnerability sits with China-dominated silicone-coated ripstop nylon weaving capacity and South Korea-controlled carbon fiber precursor supply. Raw material dependencies center on aerospace-grade 7000-series aluminum from Japan's limited smelter base, Taiwanese ripstop fabric finishing, and domestic JIS-certified flame-resistant coating applicators. Tariff exposure runs through cross-border fabric shipments subject to METI origin-verification requirements. Distribution runs through big-box retail channels for mass-market lines and specialty outdoor retailers for technical alpine specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in premium-tier technical shelters as silicone-impregnated fabric innovation compresses single-wall versus double-wall performance gaps and justifies price elevation. Cost-down drivers from domestic assembly qualification for METI subsidies further widen profitability bands for Osaka-based manufacturers with captive production.
For Market Incumbents: Deepen backward integration into JIS-certified fabric finishing to defend against emerging Chinese direct-to-consumer entrants with subsidized logistics. Prioritize certification investment in PMDA-compliant insect-repellent treatments to capture corporate retreat procurement cycles before compliance layering extends to recreational segments. Channel control through specialty retailer exclusivity agreements in underpenetrated Kyushu prefectures anchors volume defense. For New Entrants and Emerging Players: Eco-tourism operators seeking teepee and canvas constructions for volcanic terrain camping zones represent the most penetrable buyer archetype with minimal incumbent technical shelter overlap. Kyushu prefecture distribution partnerships with regional outdoor retailers offer whitespace entry with lower big-box channel conflict. Direct-to-consumer digital QR-code safety disclosure positioning aligns with Consumer Affairs Agency labeling streamlining proposals. For Investors and Strategic Acquirers: Valuations sit cheapest among pattern-making talent-scarce technical fabricators with Osaka-based design centers and unexploited domestic assembly capacity. Long-term viability over the projection horizon hinges on METI subsidy eligibility capture and four-season alpine convergence R&D positioning. Watch JIS L 1091 testing laboratory capacity expansion as the signal for seasonal product launch timing normalization and working capital efficiency inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into JIS-Certified Fabric Finishing | Captures METI subsidy eligibility while insulating margin from petroleum derivative volatility. |
| Four-Season Alpine Convergence R&D Investment | Targets Japanese Alpine Club procurement specifications with geodesic-tunnel hybrid engineering. |
| Kyushu Prefecture Distribution Partnership | Displaces big-box dominance in underpenetrated volcanic terrain camping zones. |
| PMDA-Compliant Insect-Repellent Treatment Certification | Extends addressable market into integrated bug-protection tent segments with compliance layering. |
| Digital QR-Code Safety Disclosure Platform | Aligns with Consumer Affairs Agency labeling streamlining to reduce packaging compliance costs. |
Research Methodology
Coverage spans Kanto, Kansai, Kyushu, Chubu, and Hokkaido regions, with primary inputs from each combining structured interviews with product development directors at technical shelter specialists, procurement leads at corporate retreat planning firms, category buyers at specialty outdoor retailers, and compliance officers navigating JIS L 1091 certification pathways. Secondary validation draws from METI outdoor recreation infrastructure disclosures, Consumer Affairs Agency product safety labeling databases, PMDA pharmaceutical device registration filings, and Japanese Alpine Club equipment procurement specifications. Bottom-up shipment data triangulates against top-down retail audit coverage across big-box and specialty channels.
Rate-of-change decomposition separates volume drivers from value mix shifts across the analysis window. Segmentation dimensions modeled include product architecture, material construction, end-use application, and buyer procurement scale. CAGRs derive from historical shipment trajectories adjusted for METI stimulus timing and alpine club procurement cycle compression. Industry-specific forecast inputs incorporate JIS certification backlog duration estimates and aerospace-grade aluminum spot price elasticity assumptions.
Underlying measurement precision varies by segment; recreational camping and dome configurations carry tighter precision than adventure expeditions and geodesic engineering due to established retail audit coverage. Forecasts reflect assumptions about subsidy eligibility continuity, laboratory capacity expansion, and input material price normalization that could revise trajectories if METI policy shifts or supply chain disruptions persist. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Camping Gas Canister Market
Outdoor Gear
South Korea Camping Equipment Market
Outdoor Gear
Mexico Camping Equipment Market
Outdoor Gear
Ice Axe Market
Outdoor Gear
Trail Running Bags Market
Outdoor Gear
Outdoor Camping Toilet Market
Outdoor Gear
Rechargeable Camping Gear Market
Outdoor Gear
Europe Camping Equipment Market
Outdoor Gear
Australia Camping Equipment Market
Outdoor Gear
Shoulder Strap Insulated Cooler Market
Outdoor Gear
Japan Camping Equipment Market
Outdoor Gear
Shared Umbrella Market
Outdoor Gear
Professional Gear Bags Market
Outdoor Gear
Wheeled Insulated Cooler Market
Outdoor Gear
US Backpacks Market
Outdoor Gear
Snow Chain Market