
 Global Automatic Mower Market | 2026-2036
Global Automatic Mower Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automatic Mower Market Analysis
The EU Green Deal is hardening product requirements for outdoor power equipment, forcing manufacturers to eliminate gasoline-dependent systems and prioritize electrified platforms. Husqvarna Group leverages its Automower ecosystem to sustain channel dominance across Nordic and Central European retail networks. Deere & Company anchors its position through precision agriculture expertise that extends into commercial turf management systems. Robert Bosch GmbH competes on sensor integration and manufacturing scale in its European production footprint.
An automatic mower is a battery-powered, self-propelled machine that navigates grass surfaces through GPS, boundary wire, or vision-based positioning systems without human steering, typically cutting widths between 18 and 36 centimeters for residential and commercial turf maintenance. Robotic lawn mowers occupy the largest revenue pool as premium residential buyers in Western Europe trade up from basic push models. App-controlled mowers represent the fastest-expanding technology segment as smartphone integration becomes standard across mid-tier and high-end product lines. Lithium-ion batteries dominate the power architecture, displacing nickel-metal hydride and lead acid alternatives across all but entry-level price bands.
The EPA regulates small engine emissions in the United States, while the EU F-Gas Regulation and REACH framework constrain battery supply chains and chemical compositions for equipment sold in Europe. Japan's METI enforces energy efficiency standards that shape product development priorities for manufacturers targeting East Asian markets. Stakeholders must monitor how divergent battery recycling mandates across the United States, Germany, and Japan reshape cost structures and supplier qualification requirements.
Market Dynamics
Battery chemistry advances and EU Green Deal emissions mandates are compressing gasoline-powered equipment lifecycles while expanding electrified platform requirements across residential and commercial turf management segments.
Growth Catalysts
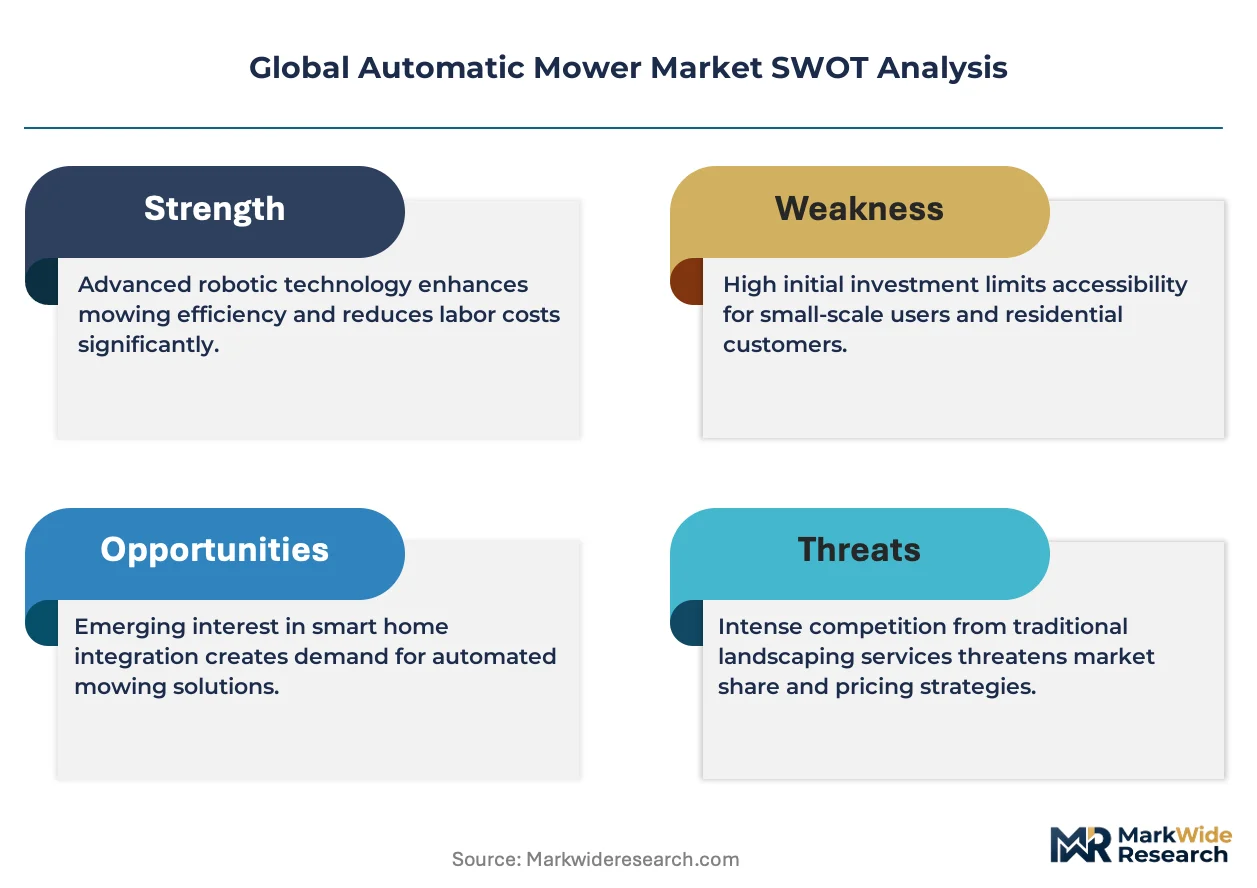
- EU Green Deal Phase-Out:The EU Green Deal mandates elimination of fossil fuel-dependent outdoor power equipment, creating regulatory pull for battery-electric automatic mowers across Germany, France, and Nordic markets.
- Lithium-Ion Energy Density Gains:Solid-state and silicon-anode battery architectures are extending runtime per charge, reducing recharge frequency for suburban properties exceeding 2,000 square meters.
- Japan's Aging Workforce:METI labor shortage projections for groundskeeping roles are accelerating autonomous equipment procurement by municipal golf courses and commercial landscaping contractors.
Market Restraints
- Cobalt and Lithium Price Volatility:Raw material cost swings for cathode-active materials are compressing gross margins for manufacturers without long-term offtake agreements with Chilean or Australian mining operations.
- Boundary Wire Installation Friction:Residential buyer reluctance to trench or peg perimeter wiring limits adoption velocity among rental property owners and seasonal homeowners.
- REACH Chemical Compliance:ECHA substance restrictions on specific electrolyte additives and flame retardants are extending product recertification timelines for equipment sold in European Economic Area markets.
Strategic Opportunities
- Vision-Based Navigation:Camera-and-AI positioning systems are eliminating boundary wire dependency, opening penetration potential in rental housing and multi-tenant residential complexes.
- US Inflation Reduction Act Credits:Domestic content and clean energy manufacturing tax incentives are reshaping North American production location decisions for battery pack assembly.
- Commercial Turf as-a-Service:Subscription-based autonomous mowing contracts for corporate campuses and municipal parks are shifting capex-to-opex models for facility managers.
Industry Challenges
- Embedded Software Talent Scarcity:Shortages in robotic path-planning and sensor fusion engineering are constraining firmware update velocity and autonomous feature roadmaps.
- Multi-Standard Certification Burden:Simultaneous FCC Part 15, CE marking, and METI electrical safety approvals are lengthening product launch cycles by 8-14 months for global platform designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automatic Mower Market |
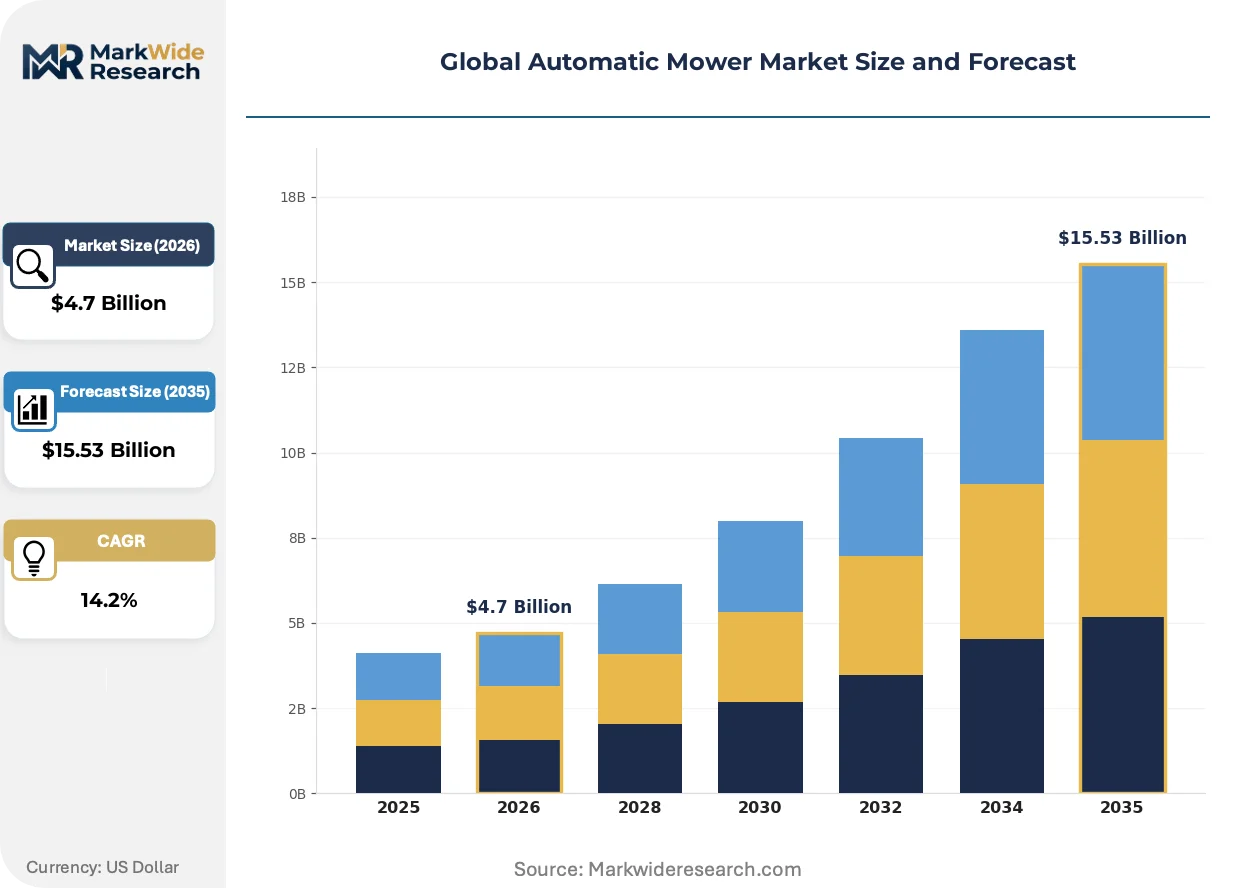
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Lawn Mowers, Robotic Garden Mowers, High-End Models, Basic Models End User: Residential Users, Commercial Landscapers, Golf Courses, Public Parks Technology: GPS-Enabled Mowers, Sensor-Based Mowers, App-Controlled Mowers, Autonomous Units Battery Type: Lithium-Ion, Lead Acid, Nickel-Metal Hydride, Others |
| Companies Covered | Husqvarna Group, Robert Bosch GmbH, Deere & Company, STIGA S.p.A., Honda Motor Co., Ltd., Robomow Friendly House, Worx, AL-KO, Belrobotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automatic Mower Market Emerging Trajectories
Three concurrent shifts are restructuring competitive advantage: sensor fusion architectures are consolidating positioning technologies, regulatory frameworks are hardening chemical and emissions requirements, and procurement patterns are fragmenting across direct-to-consumer and professional-channel pathways.
RTK-GPS and visual SLAM fusion is unifying satellite and camera-based positioning into single-chip navigation modules. Premium residential buyers in Germany and the Netherlands are specifying these hybrid systems for complex garden geometries with tree cover. This unification is compressing the price premium between wire-free and boundary-dependent product tiers.
The EU F-Gas Regulation and REACH framework are constraining refrigerant and electrolyte chemistries for battery thermal management systems. Manufacturers must reformulate coolant loops and phase-change materials to maintain operating temperature ranges. Commercial-grade equipment with extended duty cycles faces the steepest compliance redesign requirements.
Facility managers at US corporate campuses are unbundling equipment ownership from maintenance service, preferring autonomous mowing subscriptions with guaranteed uptime clauses. This consumption-pattern shift is displacing traditional dealer-finance lease structures. The model is most visible in Texas and Florida where year-round turf growth sustains continuous service contracts.
Global Automatic Mower Market Segmentation
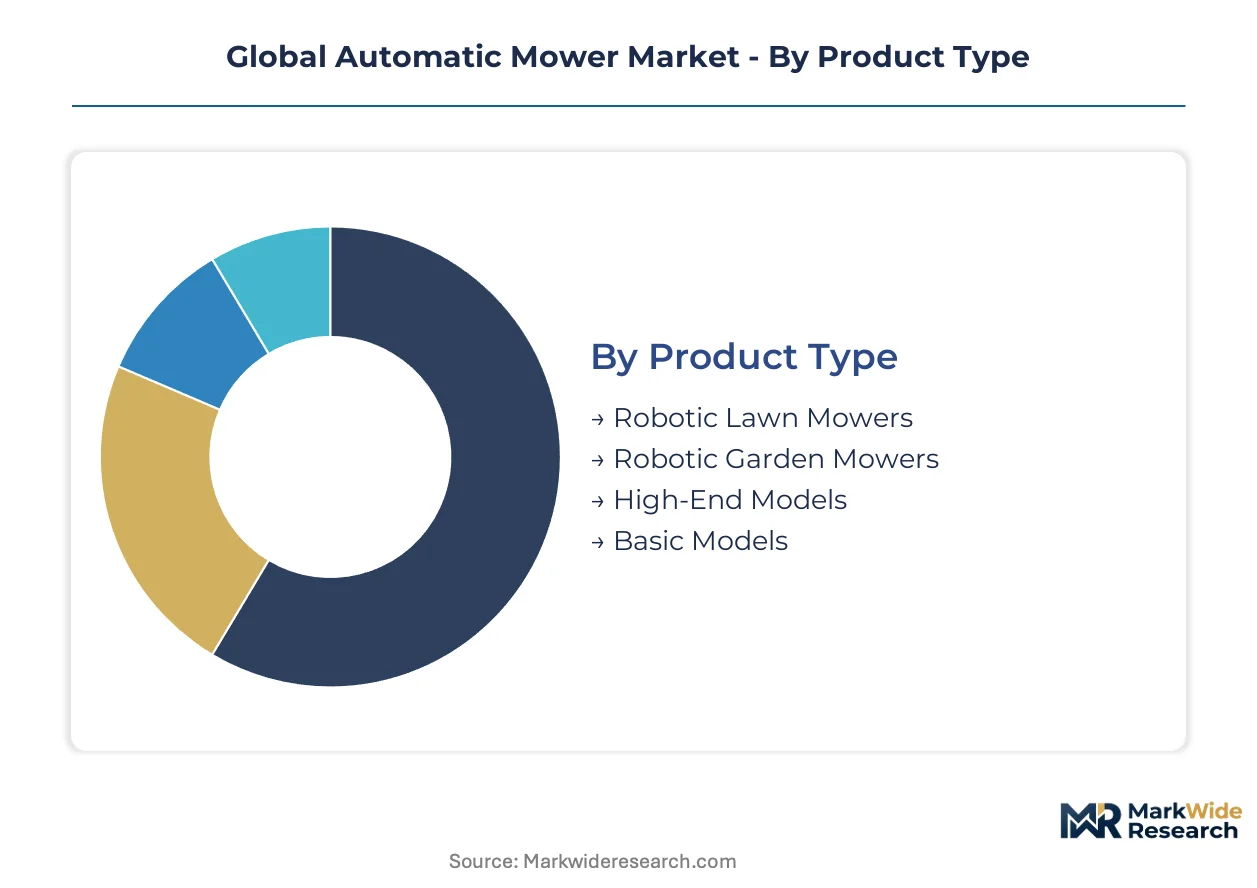
Automatic mower segmentation reveals how battery architecture, navigation systems, and buyer economics partition demand across suburban households and commercial turf operations. Product configuration choices directly determine addressable property size, maintenance frequency, and total cost of ownership for end-users.
Product Type:
Standalone robotic units dominate residential installations where perimeter mapping operates independently of other garden equipment, while embedded mower modules integrate into broader smart-landscape management platforms for estate properties.
- Robotic Lawn Mowers:Self-contained units with integrated charging stations and weather-resistant housings cut grass surfaces between 500 and 5,000 square meters. Demand concentrates in Germany and the Netherlands where compact suburban lots favor automated maintenance over manual equipment ownership.
- Robotic Garden Mowers:Multi-terrain platforms handle slopes exceeding 35 percent and navigate around flower beds, ornamental borders, and tree root systems. Adoption accelerates among UK and French homeowners with irregular garden geometries requiring adaptive path planning.
- High-End Models:Premium-tier systems with RTK-GPS accuracy and cellular connectivity for remote diagnostics.
- Basic Models:Entry-price wire-dependent units targeting rental properties and seasonal residences.
Robotic lawn mowers lead volumes today; robotic garden mowers are gaining share fastest.
End User:
Cost-tier stratification separates capital-intensive commercial procurement from household discretionary spending, with facility managers prioritizing uptime guarantees over purchase price.
- Residential Users:Individual homeowners operating units on private property with direct smartphone control and minimal technical support requirements. German and Swedish buyers drive replacement cycles as first-generation units from the early 2010s reach end-of-life.
- Commercial Landscapers:Contract maintenance firms deploying fleet-managed equipment across multiple client sites with centralized scheduling and performance monitoring. US landscaping services in Texas and Florida adopt subscription-based autonomous mowing to reduce labor cost exposure.
- Golf Courses:Precision-turf operations requiring sub-centimeter cutting height consistency across fairways and roughs.
- Public Parks:Municipal procurement with extended tender cycles and sustainability compliance mandates.
Residential users anchor current revenue; commercial landscapers are climbing the fastest.
Technology:
Application-specific navigation architectures determine property suitability, with satellite-dependent systems requiring open sky visibility while sensor-fusion platforms operate under tree canopy.
- App-Controlled Mowers:Smartphone-integrated platforms enabling remote start, scheduling adjustment, theft alerts, and firmware updates over Wi-Fi or cellular networks. Mid-tier buyers across Japan and the United States treat app connectivity as a baseline requirement rather than premium feature.
- GPS-Enabled Mowers:Satellite-positioning systems with RTK correction achieving 2-centimeter positional accuracy for systematic coverage patterns without boundary wires. Adoption spreads across Australian and Canadian rural properties where wire installation costs exceed equipment purchase price.
- Sensor-Based Mowers:Ultrasonic and bump-detection collision avoidance for obstacle-rich environments.
- Autonomous Units:Fully self-directed operation with minimal human intervention beyond seasonal blade replacement.
GPS-enabled mowers hold the largest installed base; app-controlled mowers show the steepest expansion trajectory.
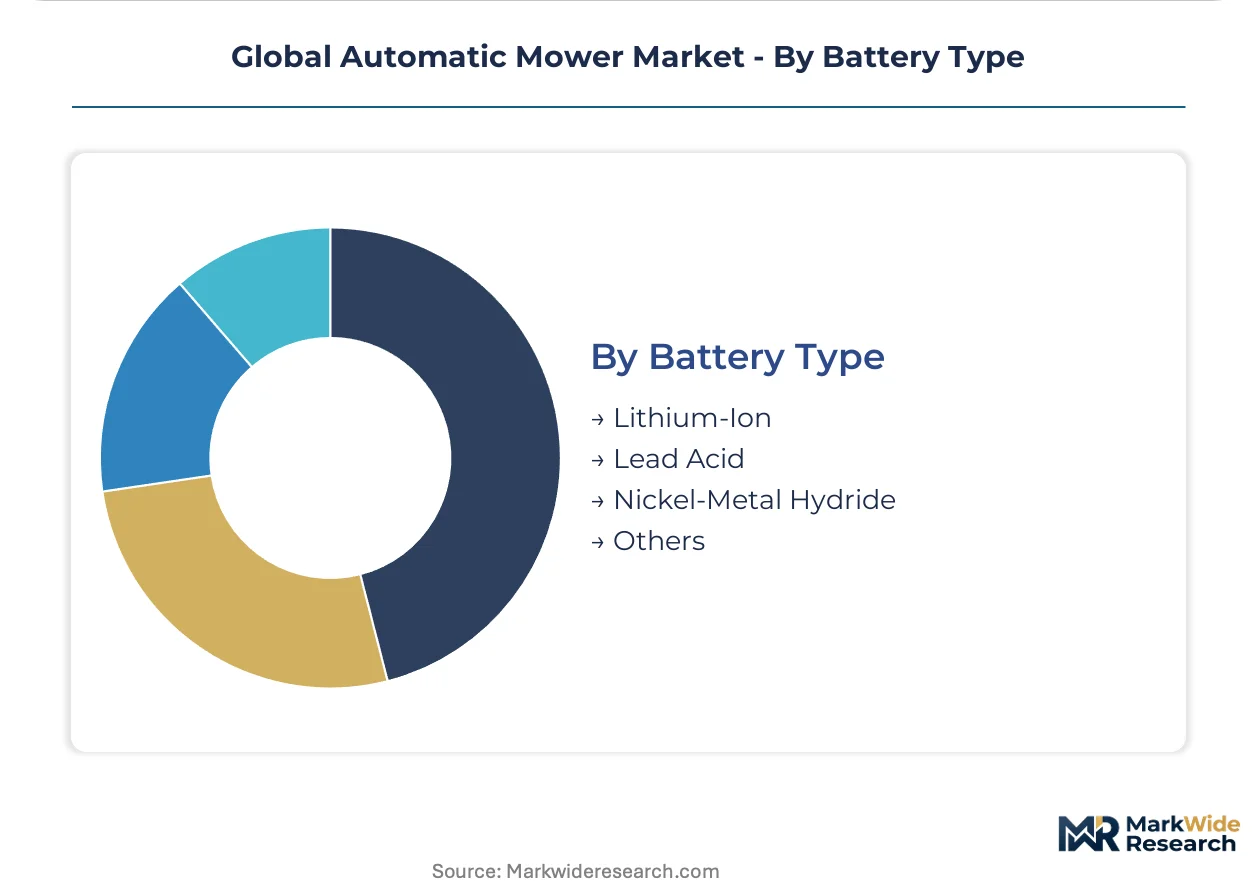
Battery Type:
Margin structure varies sharply across cell chemistries, with energy density premiums commanding price separation while mature technologies compete on manufacturing scale.
- Lithium-Ion:Rechargeable cells with 150-250 watt-hour per kilogram energy density enabling 90-minute runtimes and 60-minute recharge cycles. EU Green Deal emissions rules and REACH chemical compliance are accelerating lithium-ion displacement of legacy alternatives across all price tiers.
- Nickel-Metal Hydride:Intermediate-density cells with moderate cycle life and reduced environmental disposal concerns versus lead acid. Japanese manufacturers maintain limited production for domestic market entry-level models where METI efficiency standards permit.
- Lead Acid:Flooded and AGM variants with high surge current capability but 3-5x weight penalty versus lithium alternatives.
- Others:Emerging solid-state and sodium-ion architectures in pre-commercial validation.
Lithium-ion batteries dominate current shipments; nickel-metal hydride retains residual share in price-sensitive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering talent and Japanese precision manufacturing clusters anchor automatic mower development, while suburban expansion across North America and European regulatory pressure concentrate demand in specific national markets.
Germany
Suburban homeowners in Bavaria and Baden-Württemberg drive replacement demand as first-generation units age out. The EU Green Deal and REACH framework mandate battery-electric platforms, eliminating gasoline alternatives. Stuttgart and Munich host development centers where precision agriculture expertise migrates into commercial turf systems.
United States
Texas and Florida landscaping contractors adopt subscription-based autonomous mowing to offset labor shortages. EPA small engine emissions rules compress gasoline equipment lifecycles. Dallas-Fort Worth and Orlando metropolitan clusters concentrate commercial fleet procurement for year-round turf maintenance contracts.
Japan
METI labor shortage projections accelerate municipal golf course procurement of autonomous groundskeeping equipment. Domestic energy efficiency standards shape product specifications for East Asian markets. Nagoya and Osaka industrial corridors integrate sensor fusion engineering with precision manufacturing capabilities.
United Kingdom
Irregular garden geometries across suburban London and Southeast England favor adaptive path-planning systems. ECHA substance restrictions on electrolyte additives extend product recertification timelines. Cambridge technology cluster advances vision-based navigation modules for wire-free residential installations.
Netherlands
Compact suburban lots in Randstad metropolitan areas favor automated maintenance over manual equipment ownership. CE marking and EU F-Gas Regulation constrain battery thermal management system designs. Eindhoven region manufacturing bases supply sensor-integrated platforms to Central European retail networks.
Global Automatic Mower Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the automatic mower value chain, creating a tiered structure where integrated manufacturers control upstream cell production while specialized developers focus on navigation firmware. The vendor base spans three strategic archetypes: diversified outdoor power equipment conglomerates, automotive-tier sensor integrators, and pure-play robotics specialists. Dominant competitive moves include strategic partnerships for solid-state battery sourcing and geographic expansion through direct-to-consumer channel buildouts.
Within the diversified equipment tier, Husqvarna Group and Deere & Company exemplify manufacturers leveraging precision agriculture expertise into adjacent turf management applications. Robert Bosch GmbH occupies a position bridging automotive sensor integration with European manufacturing scale. These three entities represent distinct strategic postures: Nordic channel dominance, commercial fleet systems, and component-scale production respectively.
| Leading Market Players |
|---|
| Husqvarna Group |
| Robert Bosch GmbH |
| Deere & Company |
| STIGA S.p.A. |
| Honda Motor Co., Ltd. |
| Robomow Friendly House |
| Worx |
| AL-KO |
| Belrobotics |
| Others |
Supply Flow & Price Mechanics
EU Green Deal mandates eliminating fossil fuel-dependent outdoor power equipment are forcing battery-electric platform transitions that compress legacy equipment pricing while elevating lithium-ion cell procurement premiums across German and Nordic retail networks.
Pricing Analysis
Equipment ownership unbundling from maintenance service defines the dominant pricing split. Subscription-based autonomous mowing contracts with guaranteed uptime clauses command premium positioning in Texas and Florida commercial markets. Three-tier pricing structure across premium, standard, and economy levels separates RTK-GPS wire-free systems from app-connected mid-tier units and basic boundary-wire models. Price erosion runs through entry-level tiers as Chinese manufacturers scale lithium-ion pack assembly. Residential homeowners in Germany exhibit highest price sensitivity; US commercial landscapers prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Robotics engineering talent scarcity in Stuttgart and Eindhoven manufacturing corridors is constraining firmware development velocity and extending product launch timelines. Cell production concentrates in China, South Korea, and Japan; navigation module assembly centers on Germany and the Netherlands. The supply chain draws from Chilean lithium carbonate, Australian spodumene concentrate, and Taiwanese semiconductor foundries. Single-source vulnerability in solid-state battery electrolyte sourcing threatens premium-tier production scaling. Distribution runs through Nordic retail networks, North American landscaping service channels, and Japanese municipal procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automatic mower market functions as a regulatory compounder where EU Green Deal phase-out deadlines create irreversible demand inflection for battery-electric platforms across European Economic Area markets.
For Market Incumbents: Cement channel dominance through captive lithium-ion cell supply agreements with Australian and Chilean mining operations. Lock in long-term offtake contracts before commodity volatility intensifies. Defend against pure-play robotics specialists by accelerating RTK-GPS and visual SLAM fusion roadmaps in Stuttgart development centers. For New Entrants and Emerging Players: The mid-tier price-point gap between premium RTK-GPS systems and economy wire-dependent units offers white-space penetration in UK rental housing and French multi-tenant residential complexes. Target vision-based navigation modules eliminating boundary wire installation friction. Pursue direct-to-consumer channel buildouts bypassing established Nordic retail networks. For Investors and Strategic Acquirers: Asymmetric upside sits with sensor fusion engineering specialists holding path-planning IP and automotive-tier manufacturing partnerships. Five-to-ten year viability hinges on solid-state battery commercialization timelines and regulatory enforcement consistency. Watch EU F-Gas Regulation recertification timelines as inflection indicator for incumbent redesign cost burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Battery Partnership | Secures next-generation energy density for premium wire-free platforms targeting German estate properties. |
| Vision-Based Navigation Acquisition | Eliminates boundary wire dependency opening rental housing penetration in UK and French markets. |
| Commercial Subscription Service Launch | Captures US landscaping contractor demand shifting from equipment ownership to guaranteed uptime models. |
| EU Green Deal Compliance Certification | Accelerates product recertification timelines ahead of REACH electrolyte additive restrictions. |
| Direct-to-Consumer Channel Expansion | Bypasses Nordic retail concentration capturing price-sensitive residential buyers through digital platforms. |
Methodological Framework
Bottom-up residential and commercial procurement modeling reconciled against top-down cell production and navigation module shipment tracking forms the analytical core. Primary interviews with outdoor power equipment product managers, lithium-ion procurement leads at cell manufacturers, landscaping service operations directors, and municipal golf course groundskeeping supervisors combined with secondary validation against EU ECHA substance restriction filings, EPA small engine emissions databases, Japanese METI efficiency standard disclosures, and customs trade data for lithium carbonate and spodumene concentrate flows. Triangulation across these sources resolves demand-side adoption patterns against supply-side capacity constraints.
Input-output matrices map battery chemistry configurations, navigation system architectures, and end-user procurement models against regional regulatory frameworks and property size distributions. Segmentation dimensions span product type, technology tier, battery architecture, and buyer category across the projection horizon. CAGRs derive from installed base replacement cycles, first-time adoption curves, and average selling price trajectory modeling. Forecast inputs incorporate EU Green Deal enforcement timelines, solid-state battery commercialization readiness, and METI labor shortage projections for groundskeeping roles.
Caveats apply where lithium and cobalt price volatility, REACH chemical compliance redesign requirements, or multi-standard certification timeline extensions could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and battery chemistry transition pacing. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Japan Camping Tent Market
Outdoor Gear
Professional Gear Bags Market
Outdoor Gear
China Camping Tent Market
Outdoor Gear
Camping Gas Canister Market
Outdoor Gear
Hunting Boots Market
Outdoor Gear
Shoulder Strap Insulated Cooler Market
Outdoor Gear
Wheeled Insulated Cooler Market
Outdoor Gear
Inflatable Tents Market
Outdoor Gear
Rechargeable Camping Gear Market
Outdoor Gear
Sleeping Bag Market
Outdoor Gear
Singapore Camping Equipment Market
Outdoor Gear
New Zealand Camping Equipment Market
Outdoor Gear
Ice Axe Market
Outdoor Gear
North America and Europe Leaf Blower Market
Outdoor Gear
Deer Hunting Blinds Market
Outdoor Gear
Crash Pads Market