
 Spain Camping Equipment Market | 2026-2036
Spain Camping Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Camping Equipment Market Insights
EU Green Deal compliance is repositioning the cost-of-entry calculus for camping equipment manufacturers seeking Spanish market access. Decathlon leverages its vertically integrated supply chain to absorb certification costs while maintaining mass-market price points. Columbia Sportswear Company anchors its Iberian presence through specialty retail partnerships in Madrid and Barcelona. Big Agnes specializes in ultralight tent architectures that align with Spain's growing thru-hiking segment along the GR footpath network.
Spain camping equipment encompasses portable shelter systems, sleep systems, load-bearing gear, and field cooking apparatus engineered from technical textiles and lightweight alloys for temporary outdoor habitation. Nylon ripstop fabrics with silicone elastomer coatings achieve hydrostatic resistance exceeding 1,500 millimeters while maintaining packability below two liters for backpacking tents. Tents dominate current revenue flows due to replacement cycles tied to UV degradation in Mediterranean climates, while cooking gear registers the fastest structural expansion as campground electrification lags in remote Spanish natural parks. Online Retail channels capture growing share through Garmin's GPS-integrated trip planning ecosystems that bundle hardware with route-recommended gear configurations.
Spain's Ministry for the Ecological Transition enforces REACH-aligned chemical restrictions on tent flame retardants and waterproofing agents, compelling reformulation of polyurethane coatings. The EU F-Gas Regulation phases down hydrofluorocarbon-based insulation foams in sleeping bag production, redirecting R&D toward recycled synthetic fills. Stakeholders must monitor how Andalusia's new protected-area camping permits affect seasonal inventory planning for rental-oriented equipment pools.
Market Dynamics
Spain's camping equipment sector is restructuring around the EU Green Deal's chemical compliance mandates, which force polyurethane coating reformulation and redirect R&D budgets toward REACH-aligned flame retardant alternatives.
Growth Catalysts
- Pyrenees Trail Infrastructure:Catalonia's alpine lodge network expansion drives year-round demand for four-season tent architectures and ultralight sleep systems.
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon-based insulation foams accelerates development of recycled synthetic fills in sleeping bag production.
- Coastal Certification Pressure:Environmental certification requirements from Spain's tourism boards expand procurement budgets for domestic campground operators seeking compliant gear.
Market Restraints
- Technical Textile Input Costs:Silicone elastomer-coated nylon ripstop fabrics face price volatility from petrochemical feedstock fluctuations.
- Supply Concentration Risk:Technical textile weaving capacity clusters in Asian manufacturing hubs, creating lead time exposure for Spanish distributors.
- Regulatory Friction:REACH-aligned chemical restrictions on waterproofing agents compel costly reformulation cycles for tent manufacturers.
Strategic Opportunities
- Andalusian Protected-Area Permits:New seasonal camping authorization systems create rental-oriented equipment pool demand in southern Spain's natural parks.
- GPS-Integrated Trip Planning:Route-recommended gear configurations bundled with navigation hardware open direct-to-consumer channel expansion.
- Remote Campground Electrification Gaps:Field cooking apparatus gains share as Spanish natural parks lag in electrical infrastructure deployment.
Industry Challenges
- Certification Timeline Compression:Spain's Ministry for the Ecological Transition accelerates chemical restriction enforcement, compressing product recertification windows.
- Technical Talent Scarcity:Formulation chemistry expertise for bio-based waterproofing coatings remains concentrated among a narrow specialist workforce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Camping Equipment Market |
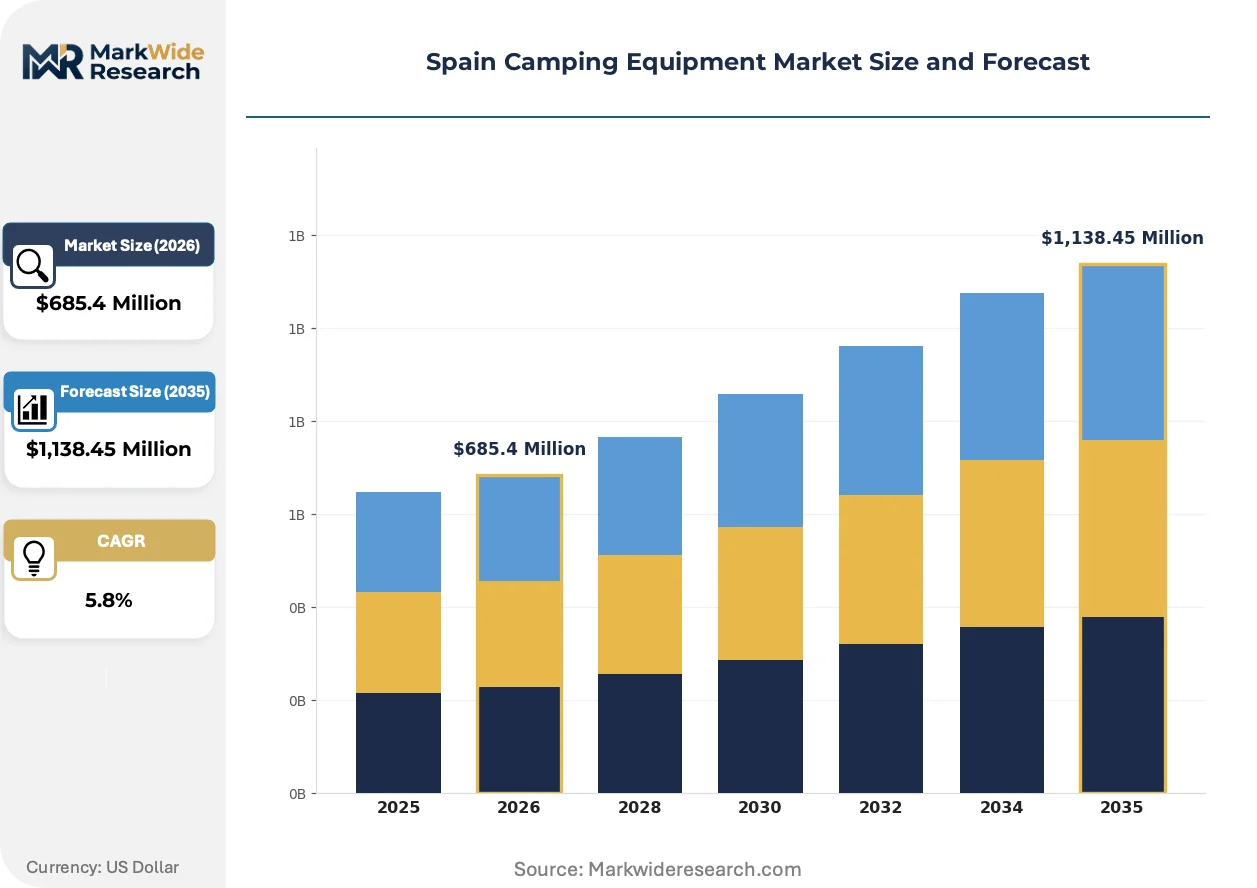
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tents, Sleeping Bags, Backpacks, Cooking Gear End User: Outdoor Enthusiasts, Families, Backpackers, Campgrounds Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale Material: Nylon, Polyester, Aluminum, Wood |
| Companies Covered | Columbia Sportswear Company, Johnson Outdoors, The North Face, VF Corporation, Big Agnes, Decathlon, REI Co-op, Garmin, Patagonia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Camping Equipment Market Trends and Innovations
Material science breakthroughs and regulatory chemistry mandates are converging to reshape product architectures across Spanish camping equipment, with implications for manufacturing cost structures and competitive positioning.
Solar-integrated tent fabrics with embedded photovoltaic threads are electrifying shelter system functionality, enabling device charging without separate panel carriage. Thru-hikers along the GR footpath network adopt these architectures fastest, compressing demand for traditional battery bank accessories.
Spain's Ministry for the Ecological Transition enforces REACH-aligned restrictions on tent flame retardants and waterproofing agents, compelling polyurethane coating reformulation. Sleeping bag manufacturers redirect R&D toward recycled synthetic fills as the EU F-Gas Regulation phases down hydrofluorocarbon-based insulation foams.
Garmin's GPS-integrated trip planning ecosystems bundle hardware with route-recommended gear configurations, shifting purchase journeys from retail floor to pre-trip digital planning stages. This channel compression is most visible among Catalonia's Pyrenees corridor visitors, where alpine lodge networks coordinate with platform partners for equipment provisioning.
Spain Camping Equipment Market Segmentation
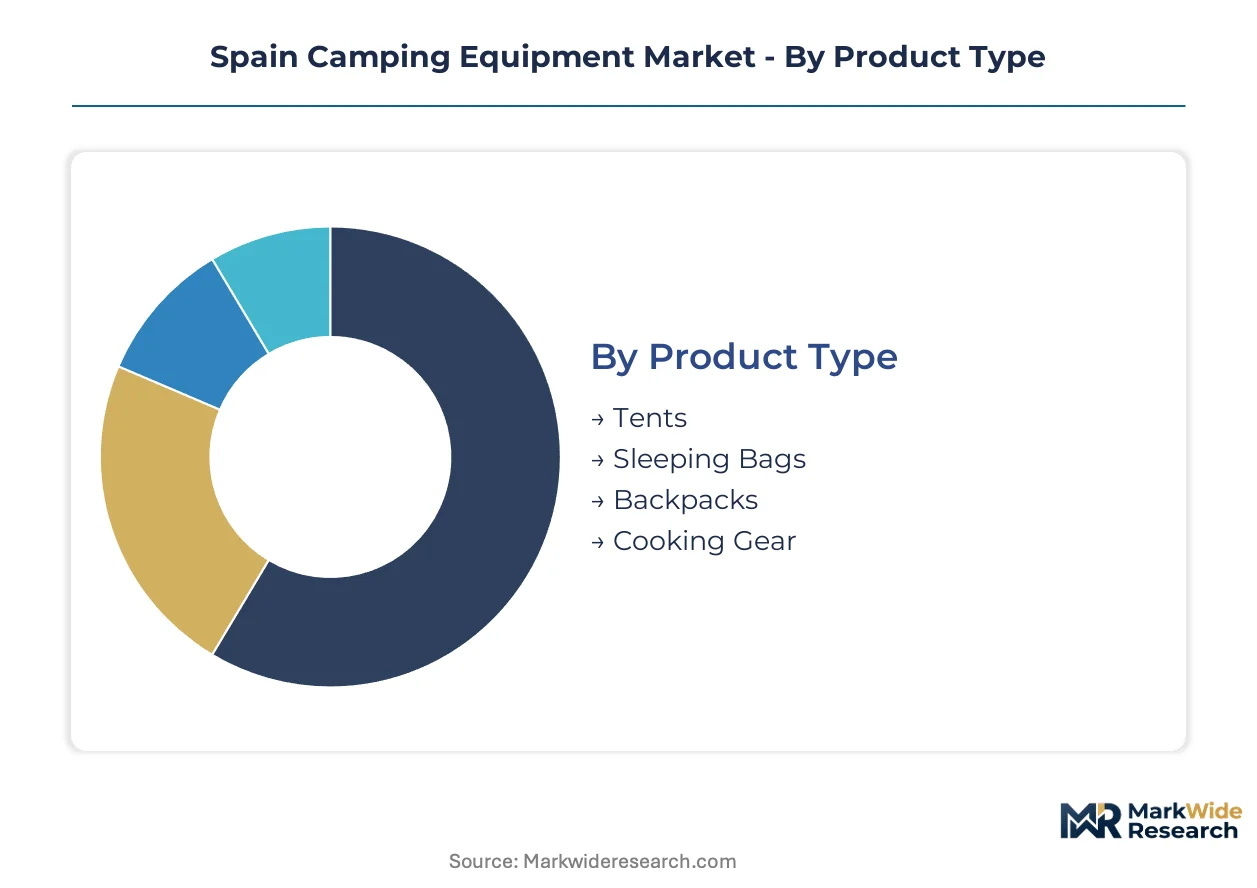
Spain's camping equipment market segments along four distinct axes that reflect divergent procurement patterns across Catalonia's alpine corridors and Andalusia's coastal parks. Each dimension captures different trade-offs between technical performance, regulatory compliance, and channel economics that shape manufacturer positioning.
Product Type:
Technical specification hierarchies separate mass-market commodity tiers from performance-oriented architectures engineered for Mediterranean UV exposure and Pyrenees alpine conditions.
- Tents:Nylon ripstop fabrics with silicone elastomer coatings achieve hydrostatic resistance exceeding 1,500 millimeters while maintaining packability below two liters. Replacement cycles in Spain's high-UV coastal zones compress to three-to-four-year intervals, anchoring recurring revenue for domestic distributors serving campground operators.
- Cooking Gear:Portable stove systems and field cooking apparatus engineered from lightweight aluminum alloys address electrification gaps in remote Spanish natural parks. Demand concentrates among thru-hikers traversing the GR footpath network where resupply logistics favor compact fuel-based systems over electric alternatives.
- Sleeping Bags:Synthetic and down-filled thermal systems face reformulation pressure from EU F-Gas Regulation phase-downs of hydrofluorocarbon-based insulation foams.
- Backpacks:Load-bearing systems with internal frame architectures distribute weight across hip belts for multi-day Pyrenees traverse requirements.
Tents lead on scale through replacement-driven recurring demand; cooking gear leads on momentum through infrastructure gap exploitation.
End User:
Application intensity and trip duration create divergent equipment durability requirements across Spain's outdoor recreation ecosystem.
- Campgrounds:Domestic operators in Catalonia and Andalusia expand procurement budgets to meet tightened environmental certification requirements from regional tourism boards. Bulk purchasing of compliant shelter systems and cooking apparatus concentrates through specialty retail partnerships in Madrid and Barcelona.
- Backpackers:Ultralight-focused thru-hikers along Spain's GR footpath network prioritize weight-to-performance ratios in tent and sleep system selection. Gear configurations increasingly integrate with GPS-integrated trip planning platforms that bundle route recommendations with hardware provisioning.
- Outdoor Enthusiasts:Weekend recreationists in Pyrenees alpine zones drive seasonal demand spikes for four-season architectures.
- Families:Multi-person shelter systems with partitioned sleeping compartments dominate car-camping segments in coastal protected areas.
Campgrounds lead on scale through certification-mandated procurement cycles; backpackers lead on momentum through digital channel integration.
Distribution Channel:
Channel economics reflect divergent customer acquisition costs and technical consultation requirements across Spain's fragmented retail landscape.
- Online Retail:Route-recommended gear configurations bundled with navigation hardware shift purchase journeys from physical retail to pre-trip digital planning stages. Garmin's GPS-integrated ecosystems capture growing share among Pyrenees corridor visitors where alpine lodge networks coordinate platform partnerships.
- Specialty Stores:Technical consultation for tent specification and sleep system temperature rating drives foot traffic in Madrid and Barcelona flagship locations. Columbia Sportswear Company anchors Iberian presence through these channels for high-consideration purchases.
- Supermarkets:Mass-market price points for entry-level camping equipment serve impulse purchase and family vacation preparation segments.
- Wholesale:Bulk procurement relationships supply domestic campground operators with compliant gear inventories ahead of seasonal demand windows.
Specialty stores lead on scale through high-consideration technical purchases; online retail leads on momentum through trip-planning ecosystem integration.
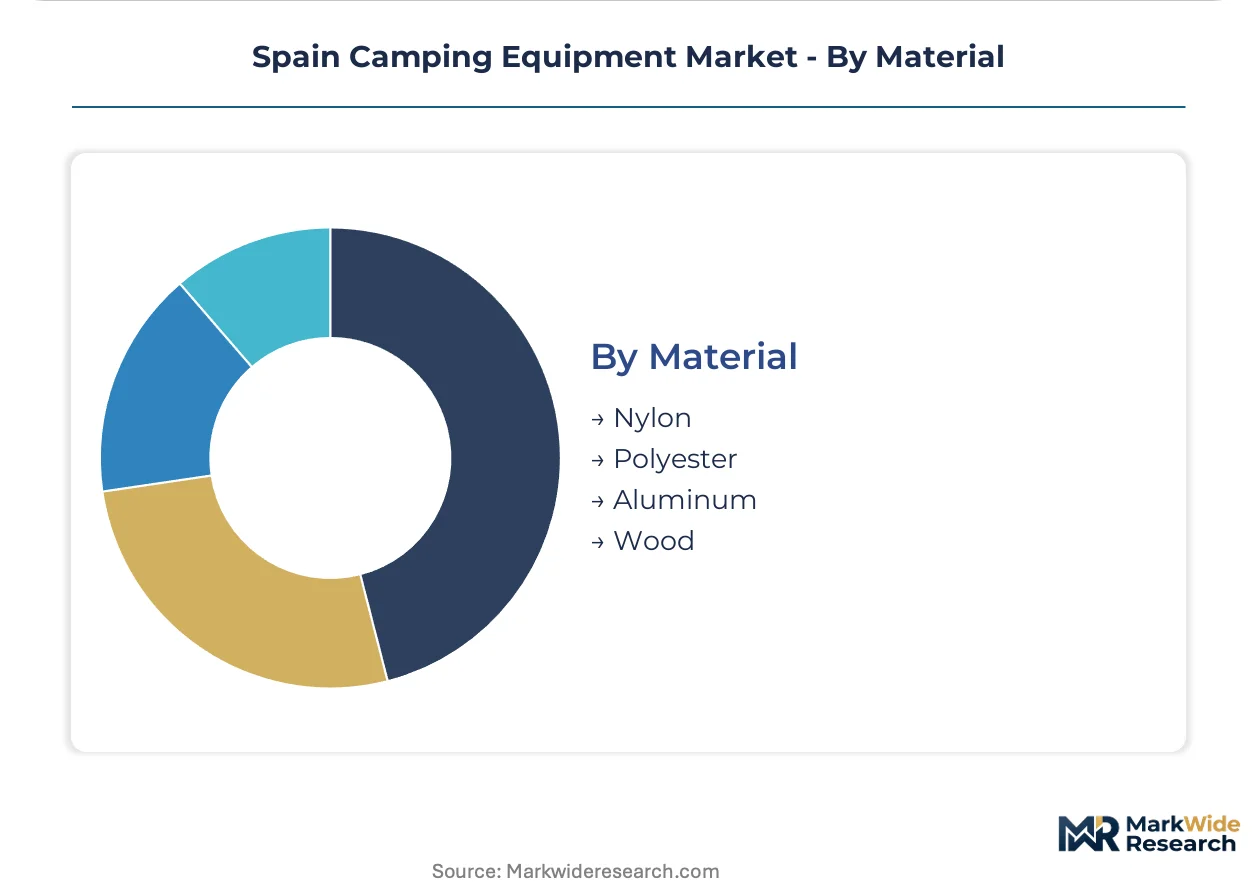
Material:
Supply concentration and REACH-aligned chemical restrictions reshape cost structures and formulation R&D priorities across technical textile inputs.
- Nylon:Ripstop weaving with silicone elastomer coatings dominates tent and backpack fabrication for strength-to-weight optimization. Petrochemical feedstock volatility creates margin pressure for Spanish distributors dependent on Asian manufacturing hub supply.
- Aluminum:Lightweight alloy poles and cookware components balance durability against packability for thru-hiking applications. Recycling infrastructure development in Catalonia creates closed-loop sourcing opportunities for tent pole manufacturers.
- Polyester:Alternative synthetic fabrics compete on cost for entry-level shelter systems in price-sensitive family segments.
- Wood:Traditional camp furniture and cooking implements serve rustic campground aesthetic requirements in protected-area permit zones.
Nylon leads on scale through technical performance dominance; aluminum leads on momentum through circular economy infrastructure development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized textile engineers and polymer chemists concentrate in Catalonia's industrial corridor, anchoring Spain's technical camping equipment manufacturing base.
Catalonia
Pyrenees alpine lodge networks and GR footpath trail infrastructure drive year-round demand for four-season tent architectures and ultralight sleep systems. The regional government enforces environmental certification requirements that expand procurement budgets for compliant gear. Barcelona anchors specialty retail partnerships where technical consultation drives high-consideration purchases.
Madrid
Central Spain's outdoor recreation clusters concentrate weekend demand for car-camping equipment and family-oriented shelter systems. The Ministry for the Ecological Transition coordinates REACH-aligned chemical restrictions affecting tent flame retardant formulations. Flagship specialty retail locations in the capital serve as distribution nodes for domestic campground operators.
Andalusia
Protected-area camping permits in southern Spain's natural parks create seasonal demand for rental-oriented equipment pools. Regional tourism boards tighten coastal environmental certification requirements for overnight facilities. Seville and Málaga serve as logistics hubs for cooking gear distribution where campground electrification gaps persist.
Basque Country
Coastal trail networks and maritime recreation drive demand for corrosion-resistant aluminum cookware and weather-resistant shelter systems. Regional industrial policy supports recycling infrastructure development for tent pole circular economy initiatives. Bilbao anchors manufacturing partnerships for lightweight alloy component fabrication.
Valencia
Mediterranean coastal tourism and mountain interior access create dual-season equipment demand across family and backpacker segments. The regional administration implements EU F-Gas Regulation compliance monitoring for sleeping bag insulation foam phase-downs. Valencia's port infrastructure supports import logistics for Asian technical textile supply chains.
Spain Camping Equipment Market Competitive Landscape
The competitive structure tilts toward vertically integrated mass-market specialists with captive supply chains capable of absorbing certification costs. Mid-tier technical specialists compete on ultralight architectures and GPS-integrated trip planning ecosystems. Two dominant competitive moves define current positioning: strategic partnerships with alpine lodge networks for equipment provisioning, and portfolio diversification into solar-integrated shelter fabrics with embedded photovoltaic functionality.
Among mass-market retailers with integrated supply chains, Decathlon exemplifies the cost-absorption archetype through in-house production of REACH-compliant gear at accessible price points. Columbia Sportswear Company and Big Agnes occupy positions on the technical-specialist vector, with the former anchoring Iberian presence through specialty retail partnerships and the latter representing ultralight tent architecture expertise aligned with Spain's thru-hiking segment.
| Leading Market Players |
|---|
| Columbia Sportswear Company |
| Johnson Outdoors |
| The North Face |
| VF Corporation |
| Big Agnes |
| Decathlon |
| REI Co-op |
| Garmin |
| Patagonia |
| Others |
Pricing and Supply Chain Analysis
REACH-aligned chemical restrictions on tent flame retardants and waterproofing agents compel Spanish manufacturers to reformulate polyurethane coatings, forcing supply chains toward certified bio-based alternatives and compressing margins across mid-tier producers unable to absorb certification costs.
Pricing Analysis
Bundled route-recommended gear configurations through GPS-integrated trip planning platforms command premium positioning against unbundled retail purchases, with three-tier pricing structure across premium, standard, and economy levels differentiating on certification grade and after-sales service inclusion. Price differentiation stems from EU Green Deal compliance tier and volume scale of procurement by domestic campground operators. Pricing pressure intensifies in the standard tier as Decathlon's vertically integrated supply chain absorbs certification costs at mass-market price points. Family car-camping segments exhibit highest price sensitivity, while thru-hikers along the GR footpath network prioritize weight-to-performance ratios over absolute cost.
Supply Chain Analysis
Certification gating through Spain's Ministry for the Ecological Transition restricts supplier qualification to REACH-aligned coating formulators and flame-retardant specialists, compressing the approved vendor base. Technical textile weaving capacity concentrates in China, Vietnam, and Taiwan, with silicone elastomer-coated nylon ripstop fabrics and recycled synthetic insulation fills drawing from petrochemical and post-consumer waste feedstocks respectively. Single-source vulnerability runs through Asian manufacturing hubs for technical textile inputs. Distribution runs through specialty retail partnerships in Madrid and Barcelona for high-consideration purchases, while online retail channels capture growing share through trip-planning ecosystem integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's camping equipment market functions as a stable compounder anchored by replacement-driven tent demand cycles and regulatory-mandated procurement upgrades across domestic campground operators.
For Market Incumbents: Deepen backward integration into REACH-compliant coating formulation to defend margin position against certification cost compression, while expanding captive supply of recycled synthetic fills to hedge EU F-Gas Regulation phase-down exposure. Prioritize alpine lodge network partnerships in Catalonia's Pyrenees corridor to lock in year-round equipment provisioning contracts. For New Entrants and Emerging Players: Alpine lodge networks represent the most penetrable channel partner type for equipment provisioning contracts, particularly where GPS-integrated trip planning platforms coordinate bundled gear configurations. Target Andalusia's protected-area camping permit zones for rental-oriented equipment pool deployment, leveraging seasonal demand concentration in southern Spain's natural parks where campground electrification gaps persist. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty coating formulators possessing REACH-aligned bio-based waterproofing expertise, given technical talent scarcity and compressed recertification timelines. The five-to-ten year viability window favors acquisition targets with established alpine lodge network partnerships and solar-integrated shelter fabric R&D pipelines. Monitor Andalusia's seasonal camping authorization system expansion as the key inflection indicator for rental equipment pool demand.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Coating Reformulation | Spain's Ministry for the Ecological Transition mandates polyurethane coating reformulation, compressing product recertification windows for tent manufacturers. |
| Alpine Lodge Network Partnership | Catalonia's Pyrenees corridor lodge expansion creates captive equipment provisioning channels with year-round demand visibility. |
| Recycled Synthetic Fill Development | EU F-Gas Regulation phase-down of hydrofluorocarbon-based insulation foams redirects sleeping bag R&D toward post-consumer waste feedstocks. |
| GPS-Integrated Trip Planning Integration | Garmin's route-recommended gear configuration bundling shifts purchase journeys from retail floor to pre-trip digital planning stages. |
| Solar-Integrated Shelter Fabric Launch | Embedded photovoltaic thread architectures electrify tent functionality for thru-hikers along Spain's GR footpath network. |
Research Methodology
Bottom-up campground operator procurement modeling reconciled against top-down technical textile import tracking forms the analytical core of this study. Primary interviews with gear procurement managers at domestic campground operators, specialty retail buyers in Madrid and Barcelona, polymer chemists at coating formulators, and alpine lodge network coordinators were cross-validated against secondary sources including Spain's Ministry for the Ecological Transition enforcement notices, EU F-Gas Regulation implementation documents, ECHA REACH restriction updates, and customs records for technical textile imports.
Input-output matrices map demand-side segmentation across product type, end user, distribution channel, and material against supply-side capacity clusters in Asian manufacturing hubs and European formulation specialists. Modeled dimensions include tent architecture seasonality ratings, sleep system temperature specifications, and certification compliance tiers. CAGRs were derived through trajectory analysis of replacement cycle compression and regulatory mandate timing across the projection horizon, with specific weighting applied to Pyrenees trail infrastructure investment pipelines and Andalusian protected-area permit system expansion schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH enforcement acceleration and petrochemical feedstock volatility. Forecasts reflect documented assumptions regarding campground electrification gap persistence and alpine lodge network partnership stability. A model refresh is warranted upon material change in EU F-Gas Regulation phase-down timelines or Andalusia's seasonal camping authorization system coverage expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Shared Umbrella Market
Outdoor Gear
Snow Chain Market
Outdoor Gear
Beach Umbrella Market
Outdoor Gear
Inflatable Tents Market
Outdoor Gear
Artificial Grass Turf Market
Outdoor Gear
South Korea Camping Equipment Market
Outdoor Gear
Trail Running Bags Market
Outdoor Gear
Rooftop Tent Market
Outdoor Gear
Fairway Mowers Market
Outdoor Gear
Outdoor Camping Toilet Market
Outdoor Gear
Camp Fire Tripod Market
Outdoor Gear
Japan Camping Equipment Market
Outdoor Gear
Professional Gear Bags Market
Outdoor Gear
Mexico Camping Equipment Market
Outdoor Gear
Germany Camping Equipment Market
Outdoor Gear
Rechargeable Camping Gear Market