
 Cordless Garden Equipment Market | 2026-2036
Cordless Garden Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Cordless Garden Equipment Market Analysis
Lithium-ion battery chemistry is consolidating its position as the dominant power source across cordless garden equipment, displacing nickel-cadmium and lead-acid alternatives through superior energy density and cycle life. Husqvarna AB leverages its European manufacturing footprint to sustain premium positioning in professional-grade battery systems. STIHL Holding AG & Co. KG anchors its competitive stance through specialized dealer networks that control aftermarket service revenue. Makita Corporation extends its industrial power-tool expertise into garden applications, occupying a distinct niche among trade-oriented buyers.
Cordless garden equipment comprises battery-powered outdoor maintenance tools designed for vegetation management, typically operating at voltages from 18V to 80V with brushless motor architectures and interchangeable battery platforms. These systems eliminate direct emissions during operation while reducing noise signatures below 75 decibels, serving residential consumers, commercial landscapers, and institutional groundskeepers. Lawn mowers lead product-type revenue due to high unit values and replacement frequency among suburban households. Lithium-ion battery technology captures the fastest expansion within power-source segments as manufacturers standardize platform ecosystems across multiple tool categories. Commercial end users concentrate margin pools through fleet-purchase contracts and multi-year service agreements.
The EPA enforces Tier 4 and evolving small-engine emissions standards that tighten compliance costs for gasoline-powered alternatives, while the EU Green Deal and F-Gas Regulation collectively restrict fossil fuel equipment procurement in public landscaping contracts. OSHA noise-exposure limits reinforce demand for quieter battery systems in commercial settings where worker-safety compliance carries enforcement weight. Stakeholders must monitor regulatory acceleration timelines and battery-platform interoperability standards as decisive variables for fleet-investment planning and competitive positioning.
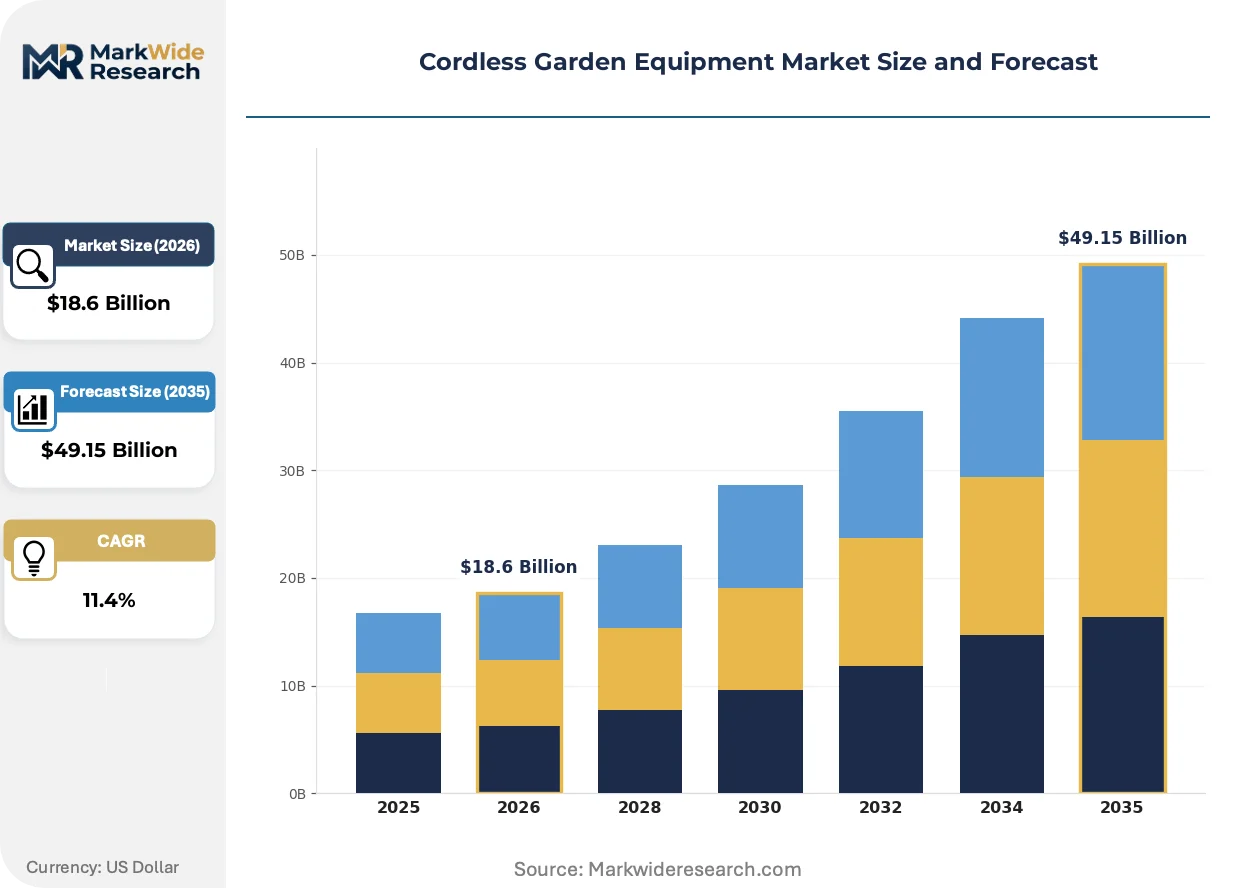
Market Dynamics
Battery-platform standardization is compressing equipment replacement cycles as manufacturers lock residential and commercial buyers into proprietary ecosystems spanning mowers, trimmers, and blowers.
Growth Catalysts
- EPA Tier 4 Standards:Tightening small-engine emissions compliance raises gasoline equipment costs, accelerating trade-in cycles toward battery alternatives among US landscaping contractors.
- Lithium-Ion Energy Density Gains:Cell chemistry improvements extend runtime per charge, enabling 80V platforms to replace gas-powered commercial mowers on single-battery duty cycles.
- German Municipal Mandates:Public procurement contracts in Berlin and Munich now specify zero-emission equipment, forcing fleet conversions among groundskeeping services.
Market Restraints
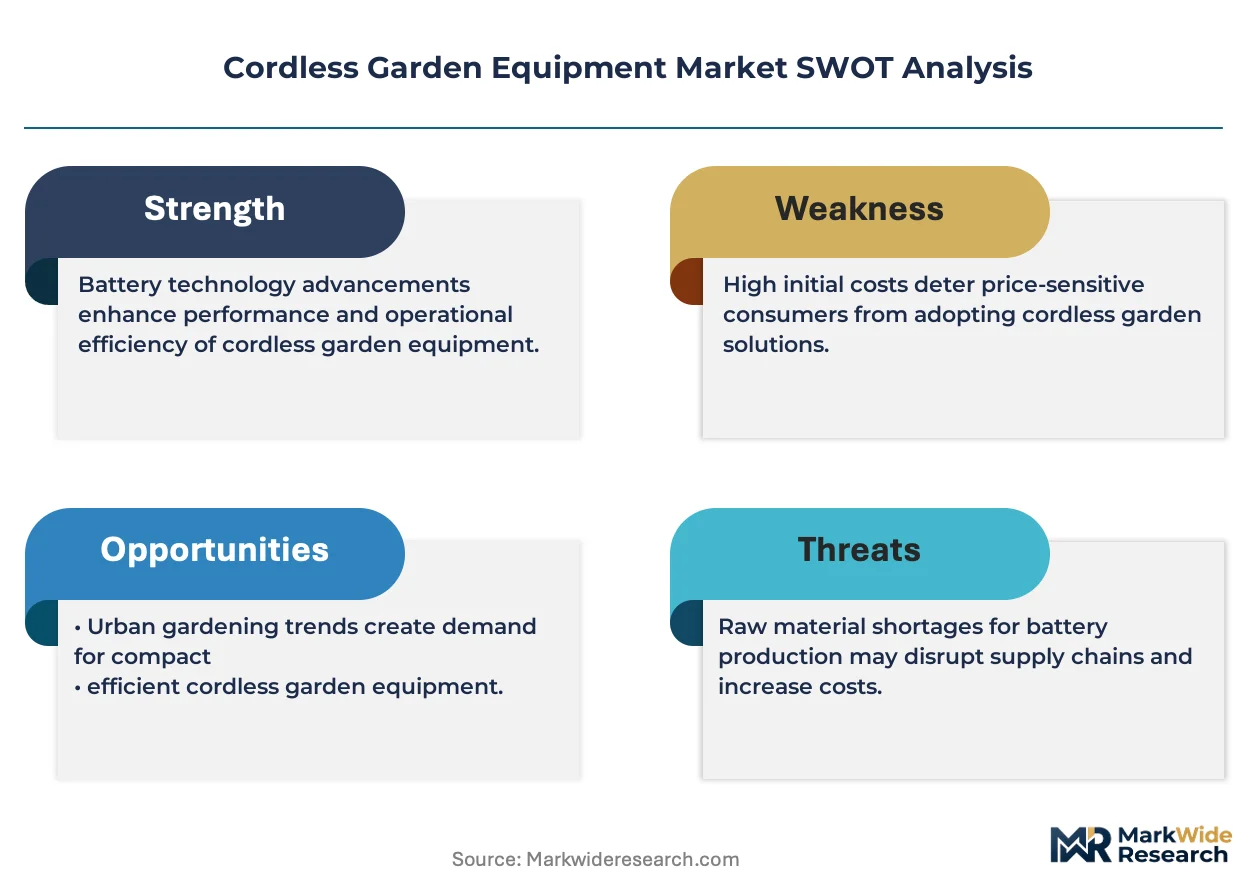
- Cobalt Supply Concentration:DRC-dominant mining for battery cathodes creates price volatility and ESG compliance burdens for cell manufacturers.
- Interoperability Friction:Proprietary battery mounts across DeWalt, EGO, and Ryobi platforms prevent cross-brand usage, fragmenting replacement demand.
- Cold-Weather Performance Degradation:Lithium-ion capacity loss below freezing limits year-round deployment in Nordic and North American markets.
Strategic Opportunities
- EU Green Deal Acceleration:The F-Gas Regulation and fossil fuel phase-out timeline create guaranteed replacement demand across European municipal fleets through 2035.
- Robotics Convergence:Autonomous navigation stacks from robotic vacuums are integrating into perimeter-wire-free lawn mowers for residential estates.
- Direct-to-Contractor Platforms:Bypassing dealer networks through manufacturer-owned fleet-leasing portals captures recurring revenue from commercial landscapers.
Industry Challenges
- Battery Technician Scarcity:Dealer service departments lack certified staff for cell diagnostics and thermal management repairs, extending equipment downtime.
- Certification Timeline Compression:UL 2595 and IEC 62841-4 safety standards for battery-powered outdoor equipment require retesting with each platform revision.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cordless Garden Equipment Market |
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $49.15 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lawn Mowers, Hedge Trimmers, Leaf Blowers, Chainsaws Battery Technology: Lithium-Ion, Nickel-Cadmium, Lead-Acid, Others End User: Residential, Commercial, Landscaping, Golf Courses Distribution Channel: Online Retail, Home Improvement Stores, Specialty Stores, Garden Centers |
| Companies Covered | Husqvarna AB, STIHL Holding AG & Co. KG, Deere & Company, The Toro Company, Stanley Black & Decker, Inc., Makita Corporation, Greenworks Tools, Ryobi, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cordless Garden Equipment Market Emerging Trajectories
Intelligent power management and connectivity layers are transforming cordless equipment from standalone tools into networked assets with predictive maintenance and usage-analytics capabilities.
Brushless motor architectures paired with gallium-nitride power electronics are integrating into premium 80V platforms, enabling higher torque density without thermal throttling. Commercial landscapers in Germany and California are adopting these systems for all-day mowing operations. The technology is integrating fleet telematics that track blade hours and battery health, compressing traditional maintenance intervals.
The EU F-Gas Regulation and national fossil fuel bans in the Netherlands and Belgium are prohibiting gasoline equipment purchases by public entities from 2025 onward. Landscaping contractors dependent on municipal contracts must convert fleets ahead of enforcement deadlines. Battery-powered ride-on mowers face the steepest compliance pressure given their historical diesel dominance in parks maintenance.
Subscription-based equipment access is displacing outright purchase among mid-sized landscaping operations in France and the United Kingdom. Manufacturers retain ownership while charging per-acre or per-hour usage fees, bundling maintenance and battery replacement. This model concentrates most visibly in urban contract services where capital constraints and seasonal cash flow volatility favor operational expenditure structures.
Cordless Garden Equipment Market Segmentation
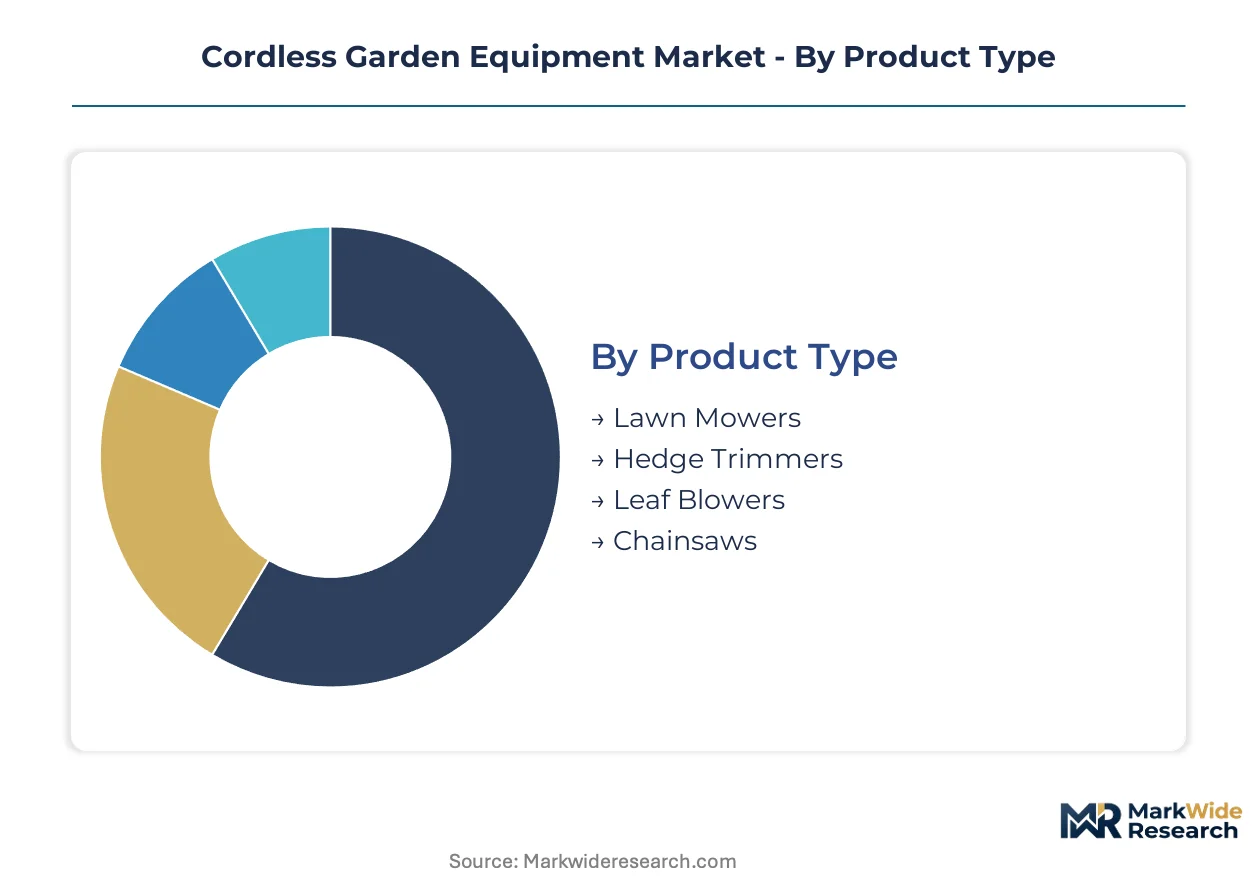
Cordless garden equipment manufacturers configure product portfolios around four decisive dimensions: equipment category, power source chemistry, buyer operational scale, and route-to-market architecture. Each segmentation axis carries distinct margin profiles, replacement cycle dynamics, and regulatory exposure that shape capital allocation across the value chain.
Product Type:
Supply concentration in motor and blade fabrication favors manufacturers with captive metalworking capacity, compressing margins for outsourced assemblers.
- Lawn Mowers:Ride-on and walk-behind configurations dominate unit economics through high battery platform values and suburban household replacement frequency. German municipal procurement mandates and California air quality districts are accelerating fleet conversions among groundskeeping contractors.
- Leaf Blowers:Handheld and backpack variants generate the steepest expansion trajectory within residential segments, driven by noise-ordinance enforcement in US cities and EU Green Deal phase-out timelines for two-stroke engines.
- Hedge Trimmers:Pole and handheld formats serve precision trimming applications with shorter duty cycles.
- Chainsaws:Professional arborist and residential pruning segments demand differentiated torque profiles and safety certifications.
Today's leader: Lawn Mowers. Tomorrow's challenger: Leaf Blowers.
Battery Technology:
Cost tier stratification in cell chemistry directly determines equipment pricing floors and platform interoperability constraints.
- Lithium-Ion:NMC and LFP cathode formulations deliver 150-500 Wh/kg energy density with 500-1500 cycle life, enabling 80V commercial platforms. EPA Tier 4 compliance costs for gasoline alternatives and EU F-Gas Regulation enforcement are displacing legacy power sources fastest in this segment.
- Nickel-Cadmium:Legacy 18V-36V platforms persist in price-sensitive residential replacement markets.
- Lead-Acid:Entry-level ride-on mowers and institutional fleet purchases absorb remaining demand.
- Others:Solid-state and sodium-ion prototypes target cold-weather performance gaps in Nordic markets.
Lithium-Ion commands current volume. Solid-state prototypes threaten tomorrow's chemistry hierarchy.
End User:
Application intensity separates buyers by duty-cycle demands, warranty expectations, and fleet-standardization requirements.
- Residential:Suburban homeowners drive platform ecosystem lock-in through multi-tool battery compatibility, with German and US households leading per-capita equipment ownership.
- Commercial:Landscaping contractors concentrate margin pools through multi-unit fleet purchases and service-contract bundling.
- Landscaping:Municipal and institutional groundskeepers face EU Green Deal and EPA emissions compliance deadlines.
- Golf Courses:Precision-mowing specifications and noise-abatement requirements favor premium 80V ride-on configurations.
Commercial buyers anchor current profitability. Residential households are gaining share fastest.
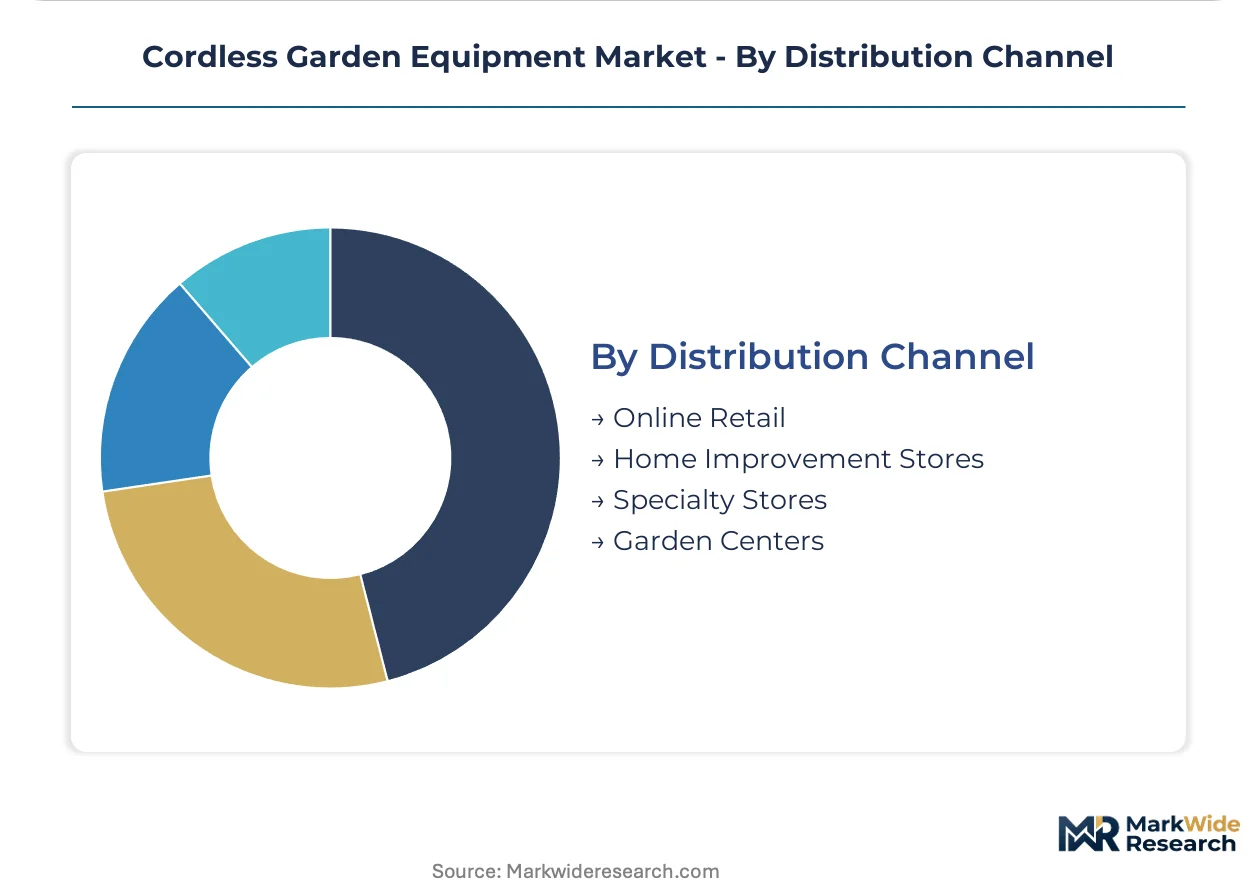
Distribution Channel:
Customer type dictates channel preference, with trade buyers resisting direct-to-consumer migration.
- Online Retail:Amazon and manufacturer-direct portals capture residential accessory and battery replacement demand.
- Home Improvement Stores:Home Depot and Lowe's aggregate suburban DIY volume through private-label and national brand placement.
- Specialty Stores:STIHL and Husqvarna dealer networks control professional-grade equipment sales and aftermarket service revenue.
- Garden Centers:Seasonal retail locations serve hobbyist gardeners with lower-duty-cycle equipment.
Specialty dealers defend professional share. Online platforms challenge in residential batteries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's municipal procurement mandates anchor European demand acceleration for zero-emission groundskeeping equipment. Battery platform standardization and fleet conversion contracts concentrate commercial investment across suburban and institutional segments.
United States
Landscaping contractors in California and Florida drive commercial fleet replacements as EPA Tier 4 compliance costs erode gasoline equipment margins. OSHA noise-exposure enforcement in urban markets reinforces battery system preference among groundskeeping employers. Dallas-Fort Worth and Phoenix metropolitan clusters concentrate dealer network expansion for professional-grade platforms.
Germany
Berlin and Munich municipal contracts now mandate zero-emission equipment, forcing fleet conversions among public groundskeeping services. The EU Green Deal and F-Gas Regulation accelerate phase-out timelines for fossil fuel procurement. Stuttgart's industrial corridor hosts manufacturing facilities supplying 80V commercial platforms across Central European markets.
United Kingdom
Subscription-based equipment access gains traction among mid-sized landscaping operations facing seasonal cash flow constraints. National fossil fuel restrictions for public procurement take effect ahead of broader EU timelines. London's urban contract services lead per-acre leasing model adoption for battery-powered ride-on mowers.
France
Residential estate owners in Île-de-France and Provence-Alpes-Côte d'Azur adopt autonomous perimeter-wire-free lawn mowers. National regulations align with EU Green Deal enforcement schedules for municipal fleet conversion. Lyon and Bordeaux metropolitan areas concentrate specialty dealer networks serving premium consumer segments.
China
Manufacturing scale advantages position domestic producers to supply battery platforms for export markets. Dual carbon goals and provincial air quality enforcement tighten small-engine equipment restrictions in Yangtze River Delta manufacturing zones. Shenzhen and Dongguan industrial clusters concentrate cell chemistry R&D for cold-weather performance improvements.
Cordless Garden Equipment Market Vendor Landscape
Global majors compete with regional champions across battery platform ecosystems and dealer network density. The vendor base separates into three tiers: integrated manufacturers with captive cell supply, specialized outdoor power equipment firms with proprietary service networks, and diversified industrial conglomerates leveraging cross-category battery compatibility. Strategic moves concentrate on platform lock-in through multi-tool interoperability and fleet leasing portal development.
Within the specialized outdoor power tier, Husqvarna AB and STIHL Holding AG & Co. KG exemplify dealer-centric distribution models that capture aftermarket service revenue. Makita Corporation occupies a position bridging industrial power-tool expertise into garden applications for trade-oriented buyers. These three anchors represent distinct competitive archetypes: European manufacturing footprint leverage, specialized service network control, and cross-category platform extension.
| Leading Market Players |
|---|
| Husqvarna AB |
| STIHL Holding AG & Co. KG |
| Deere & Company |
| The Toro Company |
| Stanley Black & Decker, Inc. |
| Makita Corporation |
| Greenworks Tools |
| Ryobi |
| Robert Bosch GmbH |
| Others |
Supply Flow & Price Mechanics
EU Green Deal procurement mandates gate qualified supply and premium-tier pricing access for cordless garden equipment manufacturers, restricting municipal contract eligibility to producers with certified zero-emission platforms and captive battery assembly capacity. This regulatory filter concentrates pricing power among integrated firms while compressing margins for outsourced assemblers dependent on commodity cell sourcing.
Pricing Analysis
Input-cost pass-through from lithium-ion cathode materials dominates equipment pricing dynamics, with NMC cell volatility feeding directly into 80V platform price adjustments. Three-tier pricing structure across premium, standard, and economy levels separates professional-grade dealer networks from mass retail private-label offerings, with certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in entry-level residential tiers is intensifying because Chinese manufacturers are flooding 18V-36V replacement markets with LFP alternatives. Commercial landscaping contractors show least price sensitivity due to fleet-standardization requirements and multi-year service contracts, while suburban DIY homeowners concentrate margin pressure through seasonal promotional purchasing.
Supply Chain Analysis
Domestic-content mandates in EU public procurement contracts are reshaping sourcing patterns, requiring European final assembly for municipal fleet eligibility and redirecting cell pack integration from Asian facilities to Stuttgart and Lyon industrial corridors. Manufacturing concentration centers on China for cathode active materials, South Korea for cell fabrication, and Germany for pack assembly and platform integration. The supply chain draws from cobalt concentrates originating in the Democratic Republic of Congo, lithium carbonate from Chile and Australia, and rare earth permanent magnets from China. Single-source vulnerability in DRC cobalt creates price volatility and ESG compliance exposure for tier-one manufacturers. Distribution runs through three distinct channels: manufacturer-direct fleet leasing portals for commercial contractors, specialized dealer networks for professional-grade equipment, and mass retail for residential replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cordless garden equipment represents a margin-expansion story as solid-state battery prototyping drives premium-tier repositioning and cobalt-free cathode chemistries unlock cost-down trajectories in mid-market segments.
For Market Incumbents: Deepen backward integration into cell pack assembly to defend against Chinese manufacturers flooding European replacement markets with uncertified platforms. Lock municipal fleet contracts through Berlin and Munich procurement pre-qualification while expanding certified service technician training to capture aftermarket revenue pools. Battery-platform standardization across multi-tool ecosystems remains the critical defensive lever against modular competitors. For New Entrants and Emerging Players: Direct-to-contractor leasing portals offer the most penetrable white-space target, bypassing entrenched dealer networks that STIHL and Husqvarna control. Target mid-sized French and UK landscaping operations facing seasonal cash flow constraints with per-acre usage models rather than capital purchase. Autonomous perimeter-wire-free lawn mowers for residential estates present a second entry vector through robotics convergence. For Investors and Strategic Acquirers: Roll-up economics work for regional battery-platform specialists because EU Green Deal enforcement timelines guarantee replacement demand through municipal fleet conversions. Battery-platform interoperability standards and fleet telematics capabilities constitute the critical viability signals across the medium-term horizon. Acquisition targets should demonstrate captive cell supply agreements or certified European assembly capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Interchangeable 80V ecosystems across mowers, trimmers, and blowers lock commercial buyers into proprietary replacement cycles. |
| Backward Integration into Cell Assembly | Captive pack production in Stuttgart industrial corridor secures EU Green Deal procurement eligibility and margin control. |
| Direct-to-Contractor Leasing Portals | Manufacturer-owned fleet access models capture recurring revenue from landscaping contractors facing capital constraints. |
| Autonomous Navigation Integration | Robotic vacuum technology stacks enable perimeter-wire-free residential mowers in French and German estate markets. |
| Certified Service Network Expansion | Dealer technician training for cell diagnostics captures aftermarket revenue and defends against independent repair competition. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with municipal procurement officers, commercial landscaping fleet managers, dealer network service heads, and battery platform engineers with secondary validation against EPA enforcement disclosures, EU F-Gas Regulation implementation timelines, and customs trade data for lithium-ion cell imports. SEC filings from listed equipment manufacturers, UL certification registries for battery-powered outdoor equipment, and IEA clean technology deployment reports provided additional triangulation anchors. Bottom-up unit shipment modeling and top-down value chain sizing converged through iterative stakeholder feedback.
Comparable-period anchoring established baseline reference points from pre-regulatory enforcement phases through active EU Green Deal implementation, enabling trajectory calibration across the projection horizon. Segmentation dimensions modeled include equipment category, battery chemistry formulation, end-user operational scale, and distribution channel architecture, with additional granularity on municipal versus private procurement status. CAGRs derived from fitted growth curves incorporating replacement cycle compression, fleet conversion mandates, and platform ecosystem lock-in effects. Key forecast inputs encompassed lithium carbonate price trajectories and cold-weather performance degradation curves for Nordic market penetration assumptions.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook for premium-tier pricing and regional market share distribution. Forecasts reflect embedded assumptions regarding regulatory enforcement timelines, raw material supply continuity, and battery-platform interoperability standardization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Wheeled Insulated Cooler Market
Outdoor Gear
Rechargeable Camping Gear Market
Outdoor Gear
Global Automatic Mower Market
Outdoor Gear
Deer Hunting Blinds Market
Outdoor Gear
Europe Camping Equipment Market
Outdoor Gear
Canoe Paddles Market
Outdoor Gear
Snow Chain Market
Outdoor Gear
UK Camping Equipment Market
Outdoor Gear
Camping Equipment Market
Outdoor Gear
Inflatable Tents Market
Outdoor Gear
Picnic Coolers Market
Outdoor Gear
Camping Equipment and Furniture Market
Outdoor Gear
China Camping Tent Market
Outdoor Gear
Rooftop Tent Market
Outdoor Gear
China Camping Equipment Market
Outdoor Gear
Camping Gas Canister Market