
 Cardiometabolic Drugs Market | 2026-2036
Cardiometabolic Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiometabolic Drugs Market Outlook
Multi-target receptor pharmacology is reconfiguring how cardiometabolic therapies achieve glycemic control, weight reduction, and cardiovascular risk mitigation within single molecular architectures. Novo Nordisk A/S dominates the GLP-1 peptide engineering space with manufacturing scale that few competitors can replicate. Eli Lilly & Company differentiates through dual GIP/GLP-1 receptor agonism, a mechanism that extends therapeutic reach beyond conventional incretin pathways. Boehringer Ingelheim International GmbH anchors the SGLT2 inhibitor segment with established heart failure indications that create durable prescriber loyalty.
Cardiometabolic drugs comprise pharmaceutical agents targeting the interconnected pathophysiology of type 2 diabetes, atherosclerotic cardiovascular disease, chronic kidney disease, and obesity, typically formulated as small molecules, peptides, or biologics with defined molecular weights, receptor binding affinities, and half-lives engineered for once-daily to once-weekly dosing. These agents modulate metabolic substrates, vascular tone, or inflammatory cascades to reduce myocardial infarction, stroke, and heart failure hospitalization. The therapy area dimension shows obesity emerging as the fastest-expanding indication as payers recalibrate coverage for weight-management pharmacotherapy. Injectable delivery modes command premium positioning due to peptide stability requirements, while oral formulations in the SGLT2 inhibitor class sustain volume leadership in hypertension and dyslipidemia combination regimens.
The FDA and EMA jointly shape cardiometabolic drug development through cardiovascular outcomes trial mandates that lengthen approval timelines but elevate evidence standards for label claims. The FDA's Division of Metabolism and Endocrinology Products enforces glycemic efficacy benchmarks, while the EMA's Committee for Medicinal Products for Human Use evaluates renal and hepatic safety profiles under centralized marketing authorization procedures. Stakeholders must monitor how CMS national coverage determinations for obesity pharmacotherapy will reshape hospital versus homecare distribution channels and pharmacy benefit design.
Market Dynamics
Medicare coverage determinations for obesity pharmacotherapy are compressing hospital formularies toward outpatient dispensing models, forcing manufacturers to reconfigure distribution networks around pharmacy benefit managers rather than institutional procurement channels.
Growth Catalysts
- GLP-1 Receptor Engineering:Peptide half-life extension technologies enable once-weekly dosing that improves adherence in chronic disease management. Hospital systems are expanding outpatient injection clinics to capture this demand.
- EMA Adaptive Licensing:The European Medicines Agency's framework accelerates conditional approvals for combination therapies targeting residual cardiovascular risk. This compresses development timelines for fixed-dose cardiometabolic products.
- Chronic Kidney Disease Bundling:United States nephrology practices are integrating SGLT2 inhibitors into disease management protocols. Dialysis chains now mandate these agents in pre-dialysis patient pathways.
Market Restraints
- Peptide Manufacturing Concentration:Active pharmaceutical ingredient production for GLP-1 agonists clusters in Denmark and select contract manufacturing sites. Supply disruption at any major facility creates allocation cascades across multiple brands.
- Cardiovascular Outcomes Trial Mandates:FDA requirements for large-scale safety studies add years to development timelines. Small molecule programs face particular pressure as trial costs exceed available venture funding.
- Oral Bioavailability Limitations:Degradation in gastric environments constrains peptide delivery to injection routes. Patient preference for oral administration sustains demand for less efficacious small molecule alternatives.
Strategic Opportunities
- Sub-Saharan Africa Penetration:Type 2 diabetes prevalence is accelerating in Nigeria and Kenya without commensurate access to cardiometabolic agents. Partnerships with national health insurance schemes create first-mover positioning.
- Continuous Glucose Monitor Integration:Closed-loop systems combining real-time glucose sensing with automated insulin delivery are converging with cardiometabolic drug protocols. Device manufacturers seek pharmaceutical partners for bundled reimbursement.
- IRA Price Negotiation Exclusions:The Inflation Reduction Act exempts certain orphan indications and small biotech products from Medicare price controls. Development programs targeting rare cardiometabolic subtypes retain pricing flexibility.
Industry Challenges
- Peptide Chemist Scarcity:Large-scale solid-phase synthesis expertise concentrates at a handful of academic centers and incumbent manufacturers. Recruitment competition drives compensation inflation above general pharmaceutical benchmarks.
- Cold Chain Integrity:Temperature excursions during last-mile distribution degrade peptide stability. Last-mile logistics providers lack validated infrastructure for patient home delivery of refrigerated injectables.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiometabolic Drugs Market |
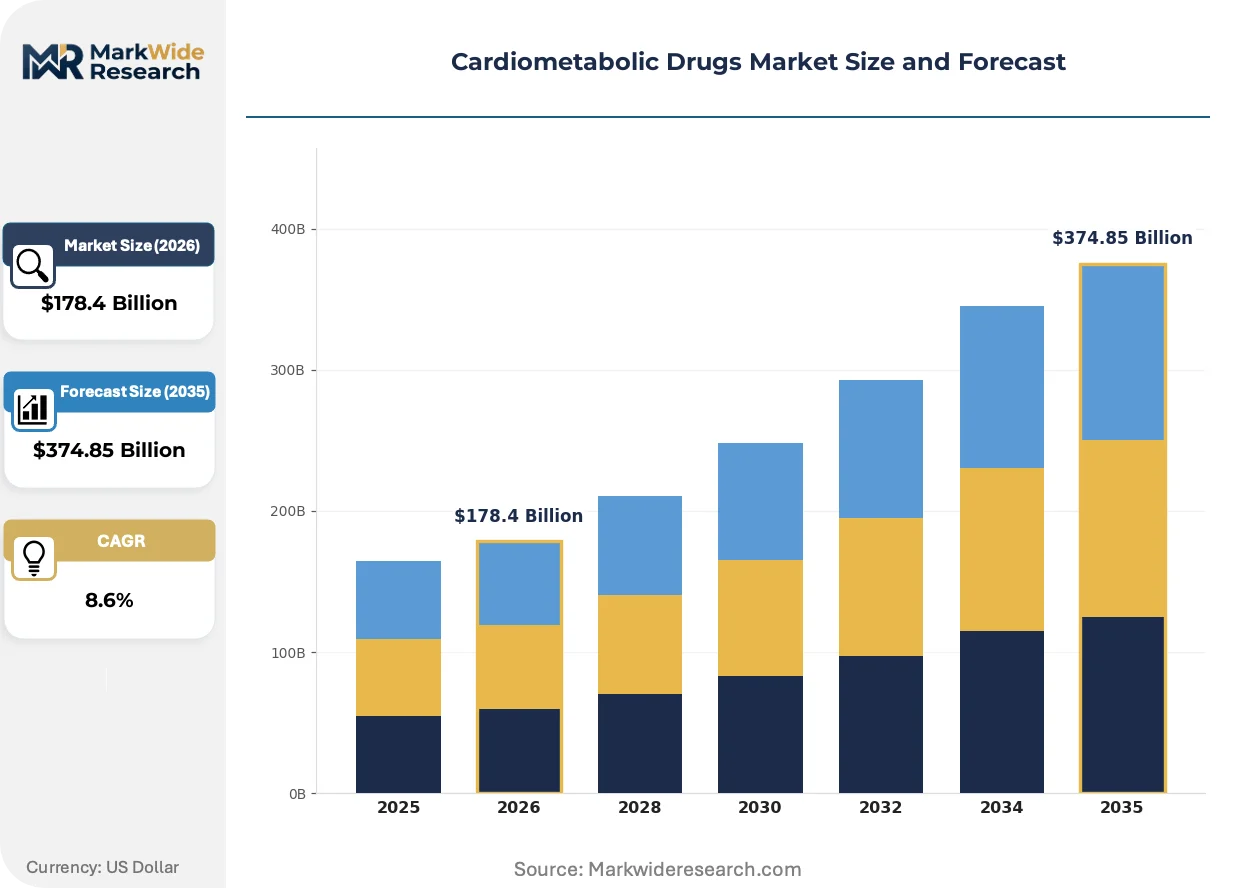
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $374.85 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GLP-1 Agonists, SGLT2 Inhibitors, Beta-Blockers, Statins End User: Clinics, Hospitals, Pharmacies, Homecare Delivery Mode: Injectable, Oral, Transdermal, Inhalation Therapy Area: Diabetes, Hypertension, Dyslipidemia, Obesity |
| Companies Covered | AstraZeneca plc, Boehringer Ingelheim International GmbH, Novo Nordisk A/S, Bayer AG, Merck & Co., Inc., Eli Lilly & Company, Novartis AG, Gilead Sciences Inc, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiometabolic Drugs Market Strategic Shifts
Digital biomarker integration is redefining how cardiometabolic efficacy gets measured, with continuous monitoring data increasingly substituting for periodic laboratory assessments in regulatory submissions and payer negotiations.
Computational protein design is virtualizing the discovery of multi-receptor agonists with optimized binding profiles. Biotechnology firms are adopting these platforms to compress lead optimization cycles from years to months. The structural consequence is a pipeline shift toward engineered peptides with receptor selectivity profiles unattainable through natural sequence variation.
REACH authorization requirements for novel chemical entities are forcing reformulation of small molecule cardiometabolic agents. The European Chemicals Agency's persistent bioaccumulation assessments now trigger additional environmental fate studies before marketing approval. Manufacturers with legacy portfolios in the SGLT2 inhibitor class face retrospective compliance obligations that divert regulatory affairs resources from new product filings.
Hospital purchasing coalitions are consolidating formulary decision authority across integrated delivery networks. Procurement committees now mandate cardiovascular outcomes data for tier placement, displacing traditional glycemic efficacy thresholds. This concentration is most visible in United States markets where Catholic health systems and for-profit chains have standardized preferred drug lists across hundreds of facilities.
Cardiometabolic Drugs Market Segmentation
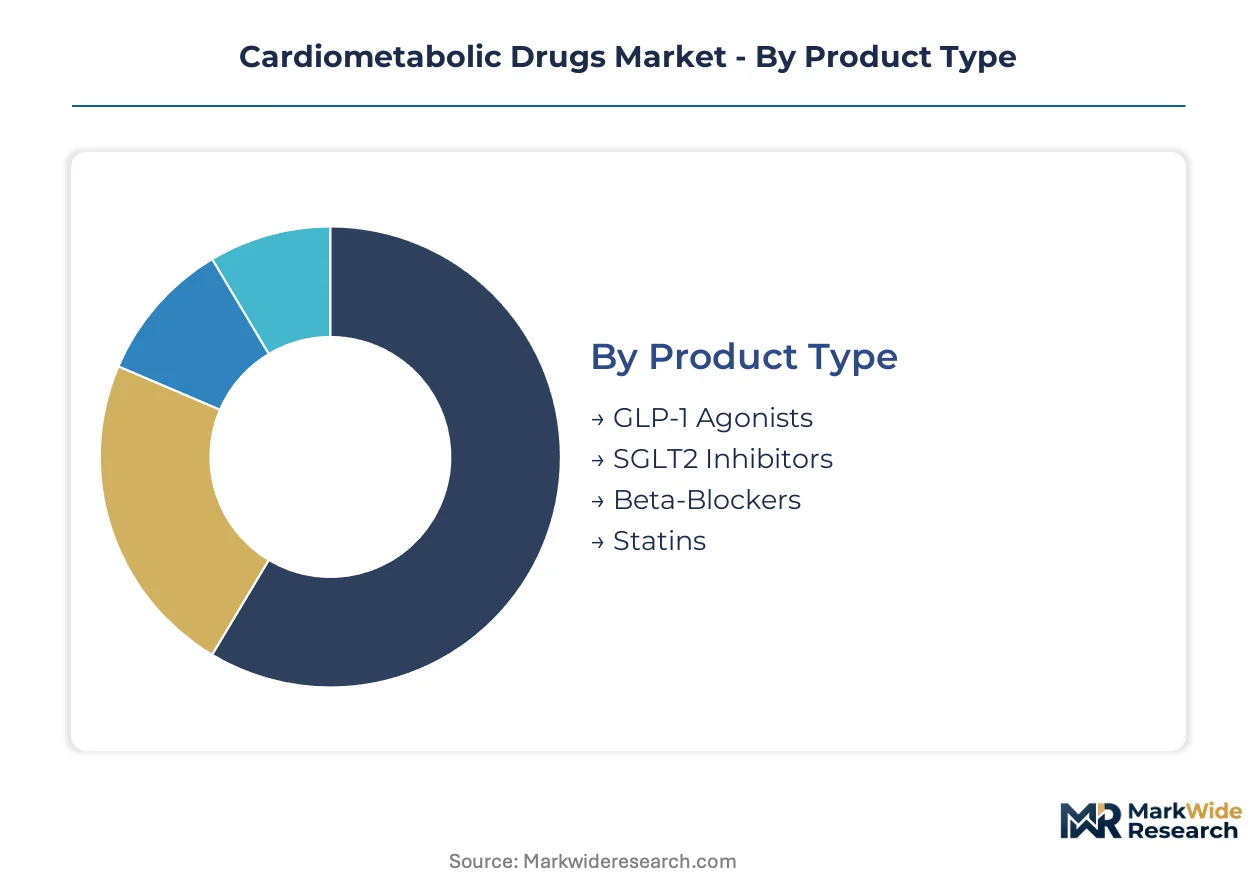
Cardiometabolic drug development and commercialization follow distinct technical and clinical pathways that segment the market into specialized competitive arenas. Each dimension—molecular class, care setting, administration route, and disease indication—carries unique regulatory requirements, pricing structures, and prescriber behaviors that shape strategic positioning.
Product Type:
Peptide engineering and small-molecule chemistry create divergent cost structures and manufacturing barriers across therapeutic classes.
- GLP-1 Agonists:Engineered peptide sequences with extended half-lives require recombinant production in microbial or mammalian systems. Demand concentrates in United States obesity management protocols where Medicare coverage expansion is reallocating hospital budgets toward outpatient injection therapies.
- SGLT2 Inhibitors:Small-molecule glucosuric agents with established heart failure indications command durable formulary placement. United States nephrology practices in dialysis chains now mandate these agents for pre-dialysis patients, creating institutional purchasing concentration.
- Beta-Blockers:Mature cardiovascular agents with generic commoditization pressure.
- Statins:Lipid-lowering mainstays facing pricing compression from biosimilar competition.
The dominant share belongs to SGLT2 Inhibitors, while GLP-1 Agonists is closing the gap fastest.
End User:
Site-of-care economics and reimbursement mechanics determine procurement authority and volume concentration.
- Clinics:Outpatient endocrinology and cardiology practices manage chronic dosing regimens with established patient panels. United States specialty clinics in metropolitan clusters handle complex titration protocols for multi-receptor agonists.
- Hospitals:Acute care settings initiate therapy during cardiovascular events or diabetes-related admissions. Formulary committees at integrated delivery networks in the United States now require cardiovascular outcomes data for tier placement.
- Pharmacies:Retail and specialty dispensing channels handle maintenance prescriptions with pharmacy benefit manager contracting.
- Homecare:Patient self-administration models supported by nursing services for injection training.
Hospital systems retain the largest procurement volume, though Clinics is expanding most quickly as outpatient chronic disease management protocols proliferate.
Delivery Mode:
Patient adherence profiles and cold-chain requirements differentiate route economics and competitive moats.
- Injectable:Subcutaneous peptide delivery via prefilled pens or syringes demands refrigerated distribution. Cold-chain integrity failures during last-mile logistics in the United States degrade stability and create patient safety liabilities.
- Oral:Small-molecule tablets and capsules sustain preference in hypertension and dyslipidemia combination regimens. United States payers favor oral step-therapy protocols before authorizing injectable escalation.
- Transdermal:Patch-based absorption for select cardiovascular agents with steady-state pharmacokinetics.
- Inhalation:Pulmonary delivery routes for experimental metabolic interventions.
Injectable formats command premium positioning, yet Oral administration retains volume leadership through payer step-therapy designs.
Therapy Area:
Disease-specific regulatory pathways and evidence requirements create distinct approval timelines and label expansion opportunities.
- Obesity:Pharmacologic weight management has shifted from cosmetic to metabolic indication with cardiovascular risk reduction claims. United States Medicare national coverage determinations are reshaping prescribing patterns and pharmacy benefit design.
- Diabetes:Glycemic control remains the foundational indication with cardiovascular outcomes trial requirements for label claims. FDA Division of Metabolism and Endocrinology Products enforces efficacy benchmarks that lengthen development timelines.
- Hypertension:Blood pressure reduction with combination therapy protocols.
- Dyslipidemia:Lipid modification with statin adjunct or alternative positioning.
Diabetes holds established revenue concentration, while Obesity is gaining share fastest as payers recalibrate coverage for weight-management pharmacotherapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems and pharmacy benefit managers concentrate procurement authority in the United States, while European markets fragment across national reimbursement schemes. Manufacturing scale advantages cluster in Denmark and Switzerland. Emerging markets in Sub-Saharan Africa present access expansion opportunities for established manufacturers.
United States
Medicare national coverage determinations for obesity pharmacotherapy are reallocating hospital budgets toward outpatient injection therapies. The FDA's Division of Metabolism and Endocrinology Products enforces cardiovascular outcomes trial mandates that lengthen development timelines. Integrated delivery networks in Texas and Florida now mandate cardiovascular outcomes data for tier placement across hundreds of facilities.
Germany
EMA centralized marketing authorization procedures evaluate renal and hepatic safety profiles for cardiometabolic agents seeking European market entry. The EMA's Committee for Medicinal Products for Human Use applies adaptive licensing frameworks that accelerate conditional approvals for combination therapies. Pharmaceutical clusters in Baden-Württemberg and Bavaria host contract manufacturing sites for peptide active pharmaceutical ingredients.
Denmark
Recombinant peptide production concentrates manufacturing gravity for GLP-1 receptor agonists in Copenhagen-area biologics facilities. Danish regulatory alignment with EMA procedures enables synchronized European and United States submission strategies. The Øresund Region anchors engineering expertise for large-scale solid-phase synthesis that few competitor sites can replicate.
Switzerland
Swissmedic marketing authorization procedures attract headquarters operations for multinational cardiometabolic portfolios. Basel and Zurich host research concentrations in SGLT2 inhibitor chemistry and cardiovascular outcomes trial design. Swiss pricing negotiations with health technology assessment bodies establish reference points for neighboring European markets.
India
CDSCO regulatory pathways for biosimilar cardiometabolic agents are accelerating as domestic diabetes prevalence expands. CDSCO manufacturing facility inspections enforce data integrity standards for export-oriented production. Hyderabad and Ahmedabad clusters specialize in active pharmaceutical ingredient synthesis for small-molecule cardiovascular agents serving regulated markets.
Cardiometabolic Drugs Market Competitive Environment
Channel-controlling players compete with product-specialist players across differentiated archetypes. Large-cap pharmaceutical incumbents leverage manufacturing scale and cardiovascular outcomes trial infrastructure to defend formulary positioning. Mid-tier specialists concentrate on single-molecule excellence or regional market penetration. Competitive moves center on peptide engineering licensing agreements and nephrology practice integration partnerships that secure institutional purchasing commitments.
Among European-headquartered innovators, Novo Nordisk A/S and Boehringer Ingelheim International GmbH exemplify divergent strategic positioning. Novo Nordisk A/S occupies the peptide engineering archetype with manufacturing concentration that creates supply-side moats. Boehringer Ingelheim International GmbH anchors the SGLT2 inhibitor segment through nephrology practice integration. Eli Lilly & Company represents the dual-receptor agonist approach that extends therapeutic reach beyond conventional incretin pathways.
| Leading Market Players |
|---|
| AstraZeneca plc |
| Boehringer Ingelheim International GmbH |
| Novo Nordisk A/S |
| Bayer AG |
| Merck & Co., Inc. |
| Eli Lilly & Company |
| Novartis AG |
| Gilead Sciences Inc |
| Sanofi |
| Others |
Value Chain & Pricing Dynamics
Danish biologics manufacturing concentration for GLP-1 peptide active pharmaceutical ingredients positions Novo Nordisk and select contract manufacturers as gatekeepers to downstream margin pools in United States obesity pharmacotherapy. Hospital systems and pharmacy benefit managers now absorb cost pass-throughs from this upstream bottleneck through formulary tier adjustments and patient access restrictions.
Pricing Analysis
Cost-plus contracts with peptide API producers index to fermentation batch yields and chromatography purification costs, creating transparency gaps that manufacturers exploit for margin protection. Pricing stratifies across branded GLP-1 agonists, authorized generics, and compounded alternatives with differentiation driven by cardiovascular outcomes data depth and Medicare coverage status. Cost compression in the oral small-molecule tier is intensifying as SGLT2 inhibitors face therapeutic substitution pressure. Price sensitivity concentrates among uninsured and underinsured patient populations in United States Medicaid expansion states, while commercially insured cohorts show relative inelasticity.
Supply Chain Analysis
Contract manufacturing for GLP-1 peptides clusters at Lonza sites in Switzerland and Vetter facilities in Germany alongside Danish incumbent capacity. Production draws from recombinant microbial expression systems, solid-phase synthesis resins, and sterile fill-finish infrastructure. Single-source vulnerability at any major peptide API facility triggers allocation cascades across multiple brands. Distribution runs through cold-chain logistics providers with validated last-mile infrastructure for refrigerated injectables reaching specialty pharmacies and hospital outpatient clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cardiometabolic drugs market represents a high-growth disruption as Medicare coverage expansion for obesity pharmacotherapy reconfigures prescribing economics and channel flows. FDA cardiovascular outcomes trial mandates compress development timelines for combination therapies while elevating evidence thresholds.
For Market Incumbents: Build manufacturing scale moats through captive peptide API capacity in Denmark or Switzerland to defend against biosimilar entrants and supply disruption. Secure nephrology practice integration partnerships that institutionalize SGLT2 inhibitor protocols in dialysis chains. Expand outpatient injection clinic networks to capture Medicare reimbursement shifts away from hospital-based dispensing. For New Entrants and Emerging Players: Sub-Saharan Africa diabetes prevalence acceleration in Nigeria and Kenya offers first-mover positioning before national health insurance scheme maturation. Target oral small-molecule development programs that bypass cold-chain infrastructure requirements and peptide chemist scarcity constraints. Pursue licensing agreements with continuous glucose monitor manufacturers for closed-loop system bundling. For Investors and Strategic Acquirers: Capital is best deployed toward dual-receptor agonist platforms with cardiovascular outcomes data generation capability across the analysis window. Acquisition candidates with EMA adaptive licensing experience and nephrology prescriber relationships command strategic premiums. Monitor CMS national coverage determination timelines as the critical inflection signal for obesity pharmacotherapy demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Peptide Manufacturing Scale-Up | Captive API production in Denmark insulates against Lonza allocation bottlenecks. |
| Cardiovascular Outcomes Trial Advancement | FDA-mandated safety studies secure tier placement at United States integrated delivery networks. |
| Nephrology Practice Integration | Dialysis chain protocols for SGLT2 inhibitors create institutional purchasing lock-in. |
| Continuous Glucose Monitor Partnership | Device bundling with Eli Lilly or Novo Nordisk enables automated insulin delivery convergence. |
| Sub-Saharan Africa Licensing Agreement | National health insurance partnerships in Kenya establish pre-generic market positioning. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA Division of Metabolism and Endocrinology Product filings, EMA centralized marketing authorization procedures, CMS national coverage determination records, and ClinicalTrials.gov protocol registries. Drug development executives, regulatory affairs leads, formulary directors at Catholic health systems, hospital procurement managers, and payer access specialists provided qualitative input. Bottom-up prescription volume modeling triangulates against top-down epidemiological prevalence projections.
Forecast inputs encompass patient population segmentation by therapy line, dosage form differentiation between injectable and oral administration routes, regional regulatory cluster effects from FDA versus EMA pathways, and cardiovascular outcomes trial completion timelines. Modeled dimensions include molecular class, care setting economics, delivery mode adherence profiles, and disease indication expansion trajectories. CAGRs derive from epidemiological trend extrapolation, reimbursement elasticity estimates, and manufacturing capacity expansion schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese biosimilar manufacturers or IRA price negotiation expansions would shift outcomes. Regulatory approval delays at FDA or EMA, peptide API facility contamination events, and Medicare coverage restriction reversals constitute primary revision risks. Quarterly review of CMS national coverage determination dockets and EMA adaptive licensing decisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Oral Vaccines Market
Pharmaceuticals
Trulicity Market
Pharmaceuticals
Gemcitabine HCL Market
Pharmaceuticals
Buprenorphine and Naloxone Market
Pharmaceuticals
Large Molecule Contract Development and Manufacturing Organization Market
Pharmaceuticals
Pregnenolone Market
Pharmaceuticals
Fibromyalgia Antidepressant Market
Pharmaceuticals
Enbrel Market
Pharmaceuticals
Global Acetazolamide Market
Pharmaceuticals
Global Autogenous Vaccines Market
Pharmaceuticals
Global Online Pharmacy Market
Pharmaceuticals
Long-Acting Insulin Market
Pharmaceuticals
Lithuania Pharmaceutical Market
Pharmaceuticals
Czech Republic Pharmaceutical Market
Pharmaceuticals
Respiratory Virus Vaccines Market
Pharmaceuticals
Short-Acting Insulin Market