
 Online Weld Seam Quality Monitoring Test Systems for Steel Pipelines Market | 2026-2036
Online Weld Seam Quality Monitoring Test Systems for Steel Pipelines Market Size, Share, and Industry Trends Forecast 2026-2036
Online Weld Seam Quality Monitoring Test Systems for Steel Pipelines Market Insights
Leasing-based deployment models for inline inspection crawlers and fixed weld monitoring stations are reshaping competitive dynamics in pipeline quality assurance. Xiris Automation leverages its specialized optical inspection architecture to sustain premium positioning among automated welding integrators. ScanMaster Systems anchors its presence through deep ultrasonic expertise serving European pipeline fabricators. FOERSTER competes via magnetic flux leakage systems that dominate German-speaking industrial corridors.
Online weld seam quality monitoring test systems for steel pipelines comprise real-time sensor arrays, data acquisition hardware, and analytical software that detect discontinuities in longitudinal, spiral, and girth welds during or immediately after the welding process. These systems typically operate at inspection speeds of 0.5 to 5 meters per minute, capturing defects such as lack of fusion, porosity, and cracks before pipes enter hydrostatic testing or field burial. Ultrasonic testing systems lead installed capacity due to proven detection reliability in thick-wall line pipe, while laser profilometry segments expand fastest as automated mills adopt seam geometry verification for API 5L compliance. Oil transmission applications concentrate the largest revenue pool, though gas distribution networks represent the fastest-growing demand channel as methane leak regulations tighten.
PHMSA integrity management rules in the United States, EU Pressure Equipment Directive requirements, and API 5L/ISO 3183 weld quality standards collectively mandate traceable, repeatable inspection documentation that drives system replacement cycles. The EPA's methane emissions reduction framework and emerging EU hydrogen pipeline adaptation codes further expand mandatory inspection scope beyond traditional oil and gas fluids. Stakeholders must monitor regulatory divergence between North American performance-based standards and European prescriptive certification regimes when configuring product roadmaps for cross-border deployment.
Market Dynamics
PHMSA's integrity management rules are compressing replacement cycles for legacy inspection hardware as pipeline operators face documented compliance deadlines. The regulatory pressure is forcing capital redeployment toward real-time weld monitoring systems that generate traceable audit trails.
Growth Catalysts
- API 5L weld quality standards:Mandatory traceable inspection documentation under API 5L and ISO 3183 protocols is accelerating system upgrades across North American transmission corridors. Operators cannot defer replacement without risking certification lapses.
- Ultrasonic testing reliability:Proven defect detection in thick-wall line pipe is concentrating demand in Permian Basin gathering systems and Alberta oil sands export routes where wall thickness exceeds 25 millimeters.
- EPA methane emissions framework:Expanded mandatory inspection scope beyond traditional oil and gas fluids is pulling gas distribution networks into compliance-driven procurement cycles.
Market Restraints
- Specialized sensor supply concentration:High-frequency ultrasonic transducers and precision laser profilometry components depend on German and Japanese precision manufacturing clusters, creating single-source vulnerability.
- Capital intensity of inline crawler systems:Magnetic flux leakage crawlers require substantial upfront investment that mid-tier pipeline fabricators cannot absorb without leasing structures.
- Regulatory divergence friction:North American performance-based standards and European prescriptive certification regimes force dual product configurations, elevating engineering overhead for cross-border vendors.
Strategic Opportunities
- Hydrogen pipeline adaptation codes:Emerging EU hydrogen infrastructure standards will mandate modified inspection protocols for embrittlement-sensitive welds, opening retrofit demand across German and Dutch transmission networks.
- Leasing-based deployment models:Fixed weld monitoring stations and inline inspection crawlers delivered as operational expenditures are unlocking mid-market pipeline operators previously excluded by capital constraints.
- Laser profilometry-UT convergence:Automated mills are adopting hybrid seam geometry verification systems that combine laser surface mapping with subsurface ultrasonic validation for single-pass compliance documentation.
Industry Challenges
- Certified NDT technician scarcity:Pipeline operators face extended recruitment timelines for ASNT Level II ultrasonic inspectors capable of interpreting real-time weld data streams.
- Legacy SCADA integration complexity:New sensor arrays must interface with decades-old data acquisition architectures in established mill environments, stretching commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Weld Seam Quality Monitoring Test Systems for Steel Pipelines Market |
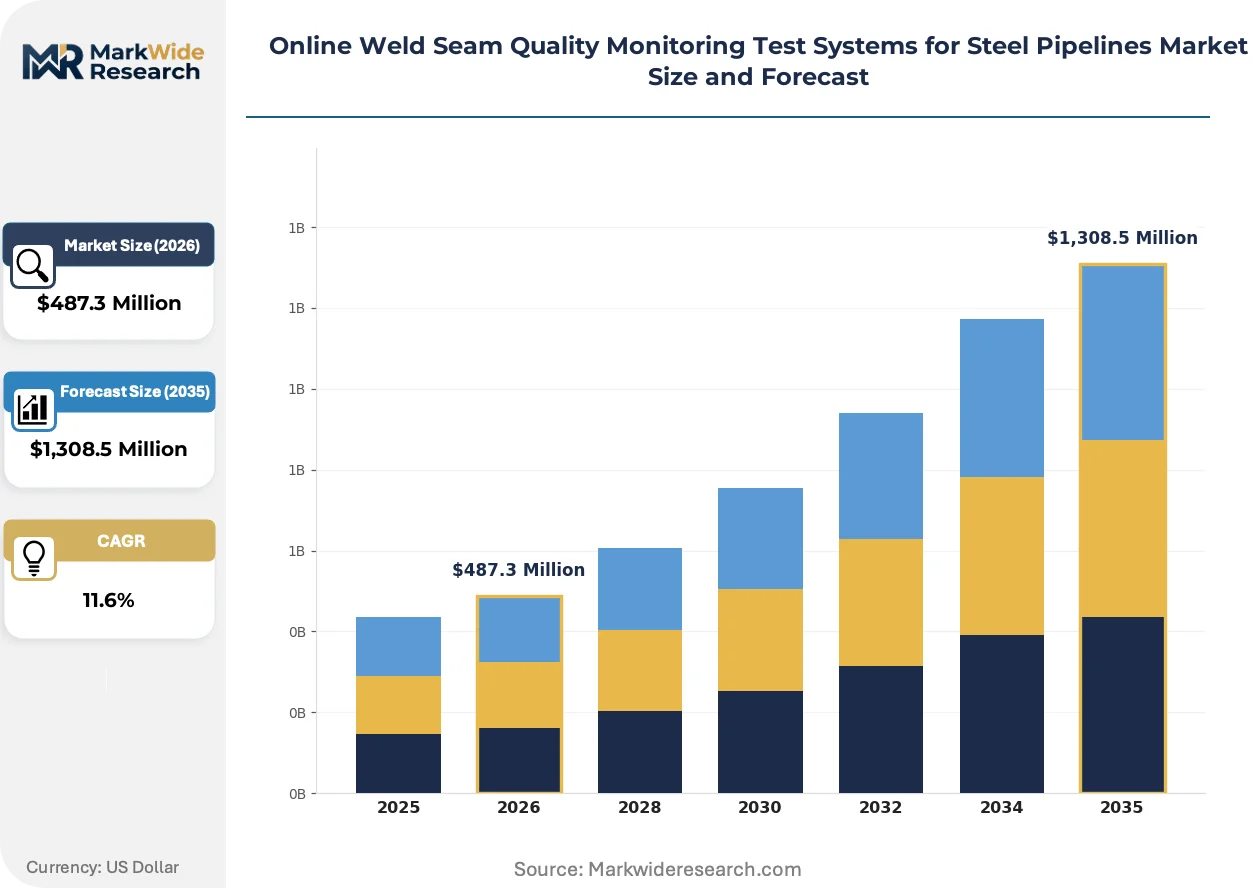
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,308.5 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Ultrasonic Testing, Radiographic Testing, Magnetic Particle Testing, Eddy Current Testing, Visual Inspection Technology: Laser Profilometry, Acoustic Emission, Thermography, Vibration Analysis, X-Ray Imaging Application: Oil Transmission, Gas Distribution, Water Supply, Chemical Transport, Power Generation End User: Pipeline Operators, Inspection Agencies, Construction Firms, Quality Assurance Labs, Engineering Consultants |
| Companies Covered | Xiris Automation, ScanMaster Systems (IRT), Blue Star Industrial Solutions, Evident, FOERSTER, Magnetic Analysis Corporation, Precitec, ESAB, Micro-Epsilon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Weld Seam Quality Monitoring Test Systems for Steel Pipelines Market Trends and Innovations
Real-time sensor fusion is collapsing the gap between inline inspection and mill-floor quality assurance. Vendors are racing to embed predictive analytics directly at the weld head.
Phased-array ultrasonic testing is digitizing defect characterization workflows by capturing full volumetric weld maps rather than line-scan snapshots. Automated pipe mills in the US Gulf Coast and Rotterdam port complexes are adopting these systems at replacement cycle points. The technology is digitizing quality documentation into machine-readable formats that feed directly into operator integrity management databases.
EU Pressure Equipment Directive recasts are tightening conformity assessment procedures for pipeline components sold into European economic area markets. Fabricators must now demonstrate continuous process control rather than batch sampling compliance. German and Austrian pipeline constructors are responding by mandating supplier certification to EN ISO 17640 for ultrasonic examination of welds.
Service unbundling is fragmenting traditional hardware-software bundles as operators demand modular procurement. Leasing structures for inspection crawlers are displacing outright purchase in North American shale corridors where capital discipline prevails. The Permian Basin and Alberta oil sands exhibit the most pronounced shift toward operational expenditure treatment of quality monitoring assets.
Online Weld Seam Quality Monitoring Test Systems for Steel Pipelines Market Segmentation
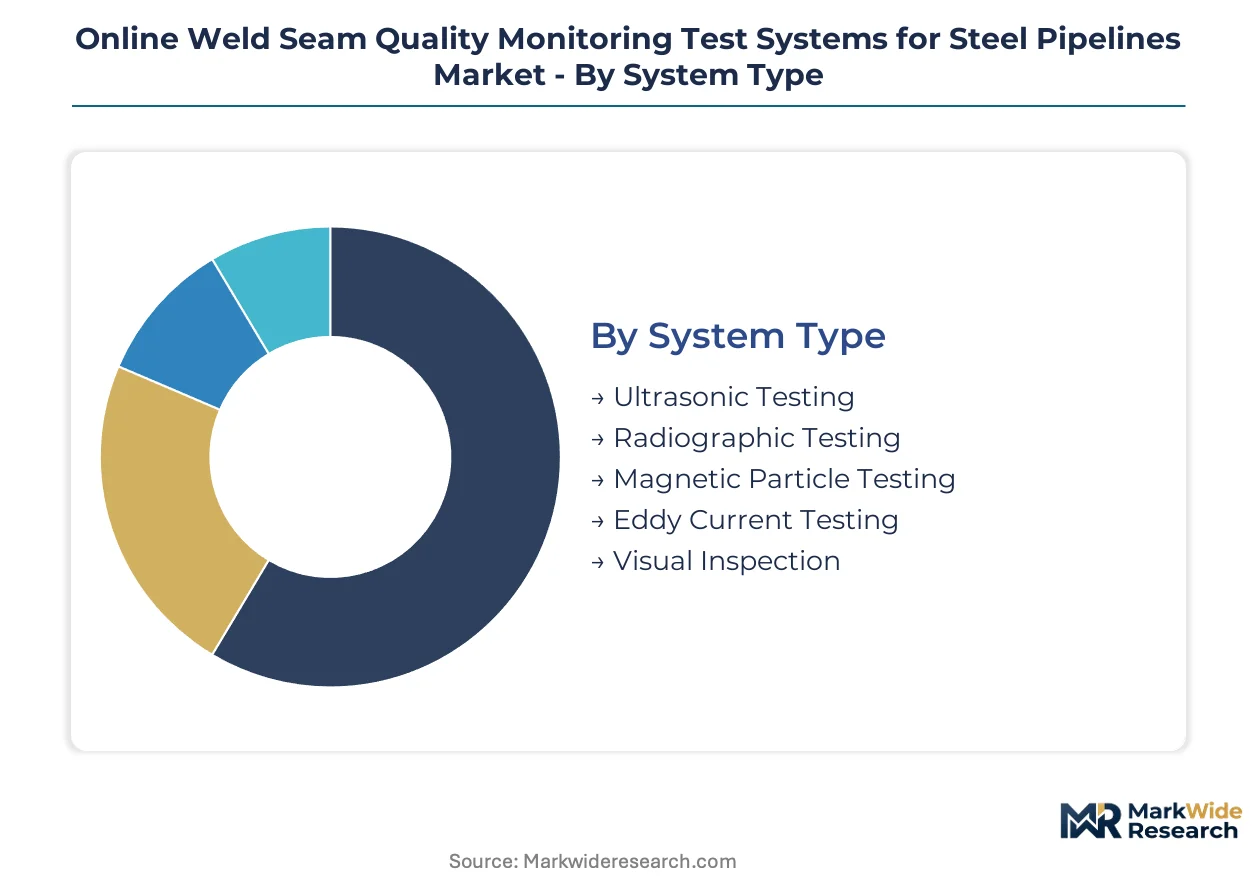
Weld seam monitoring systems serve distinct operational contexts across pipeline fabrication and in-service inspection. Segment boundaries reflect divergent technical requirements, capital deployment patterns, and regulatory compliance obligations that shape procurement decisions.
System Type:
The use-case spectrum spans from real-time mill-floor quality gates to post-construction integrity verification in buried infrastructure.
- Ultrasonic Testing:Phased-array systems emit high-frequency sound waves to map volumetric discontinuities in thick-wall line pipe. Demand concentrates in Permian Basin gathering systems and Alberta oil sands export routes where wall thickness exceeds 25 millimeters and API 5L compliance documentation is mandatory.
- Radiographic Testing:X-ray and gamma-ray systems capture permanent defect records for girth weld acceptance. Pipeline operators facing PHMSA audit scrutiny deploy these systems for traceable documentation of critical seam joints in hazardous liquid transmission corridors.
- Magnetic Particle Testing:Surface-breaking crack detection for field repair scenarios and fabrication yard spot checks.
- Eddy Current Testing:Conductivity-based inspection for thin-wall tubular products in downstream processing equipment.
- Visual Inspection:Operator-assisted optical verification for seam geometry and surface finish compliance.
The dominant share belongs to Ultrasonic Testing, while Radiographic Testing is closing the gap fastest through digitization of defect characterization workflows.
Technology:
Cost tier stratification separates capital-intensive sensor fusion platforms from single-modality inspection tools.
- Laser Profilometry:Non-contact surface mapping systems measure seam height, width, and alignment against API 5L geometric tolerances. Automated mills in the US Gulf Coast and Rotterdam port complexes adopt these for single-pass compliance documentation.
- Acoustic Emission:Passive stress-wave monitoring for crack propagation detection during hydrostatic testing.
- Thermography:Infrared thermal mapping for insulation defect location in heated product pipelines.
- Vibration Analysis:Mechanical resonance monitoring for weld integrity in dynamic loading environments.
- X-Ray Imaging:Real-time radioscopic systems for automated girth weld inspection in pipeline construction spreads.
Laser Profilometry commands premium positioning among automated welding integrators, with X-Ray Imaging expanding most quickly through service unbundling and leasing structures.
Application:
Volume concentration tracks hydrocarbon infrastructure investment cycles and utility regulatory enforcement intensity.
- Oil Transmission:Crude and refined product pipelines require continuous seam monitoring for leak prevention and spill liability mitigation.
- Gas Distribution:Methane leak regulations under EPA frameworks are pulling municipal utilities and interstate transmission operators into compliance-driven procurement cycles.
- Water Supply:Potable water transmission lines face AWWA quality standards for weld integrity in pressure-rated steel mains.
- Chemical Transport:Corrosive product pipelines demand enhanced defect detection for stress-corrosion cracking susceptibility.
- Power Generation:Steam and feedwater piping in thermal plants requires high-reliability seam monitoring for cycling fatigue resistance.
Oil Transmission retains the largest revenue pool, though Gas Distribution networks are gaining share fastest as methane emissions frameworks tighten inspection scope.
End User:
Customer type determines procurement authority, technical specification depth, and payment structure preferences.
- Pipeline Operators:Asset-owning companies with direct regulatory accountability for integrity management and audit trail maintenance.
- Inspection Agencies:Third-party NDT service providers delivering certified examination reports under ASNT and EN ISO 9712 protocols.
- Construction Firms:Pipeline installation contractors requiring mill-floor and field weld verification for client acceptance.
- Quality Assurance Labs:Independent testing facilities supporting fabrication yard certification and dispute resolution.
- Engineering Consultants:Design and integrity assessment firms specifying inspection protocols for new construction and rehabilitation projects.
Pipeline Operators control the dominant procurement volume, while Inspection Agencies are expanding their technology ownership fastest through crawler fleet investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PHMSA integrity management rules in the United States are compressing replacement cycles for legacy inspection hardware, forcing capital redeployment toward real-time weld monitoring systems that generate traceable audit trails. Pipeline operators across multiple jurisdictions face documented compliance deadlines that accelerate procurement of automated quality assurance equipment.
United States
Permian Basin gathering systems drive concentrated demand for ultrasonic testing deployments where wall thickness exceeds 25 millimeters. EPA methane emissions frameworks pull gas distribution networks into compliance-driven procurement cycles. Houston-Gulf Coast corridor fabricators adopt phased-array systems at replacement cycle points for API 5L compliance documentation.
Germany
Magnetic flux leakage systems dominate German-speaking industrial corridors serving pipeline fabricators. EU Pressure Equipment Directive recasts tighten conformity assessment procedures requiring continuous process control. Ruhr Valley and Bavarian industrial clusters mandate supplier certification to EN ISO 17640 for ultrasonic examination of welds.
Canada
Alberta oil sands export routes concentrate demand for thick-wall line pipe inspection exceeding 25 millimeter specifications. Federal and provincial pipeline regulators align with API standards for traceable inspection documentation. Calgary-Edmonton corridor operators expand inspection budgets as integrity management rules tighten for hazardous liquid lines.
China
Automated pipe mills adopt hybrid seam geometry verification systems combining laser surface mapping with subsurface ultrasonic validation. GB standards and MIIT industrial policies mandate quality documentation for domestic pipeline infrastructure. Yangtze River Delta manufacturing clusters deploy real-time sensor arrays for longitudinal and spiral weld monitoring.
Netherlands
Rotterdam port complex fabricators adopt laser profilometry systems for single-pass compliance documentation. Emerging EU hydrogen pipeline adaptation codes will mandate modified inspection protocols for embrittlement-sensitive welds. Dutch and German transmission networks prepare retrofit demand as hydrogen infrastructure standards crystallize.
Online Weld Seam Quality Monitoring Test Systems for Steel Pipelines Market Competitive Landscape
Channel-controlling players compete with product-specialist players across differentiated technology vectors. The vendor base stratifies between automated welding integrators with premium optical architectures and ultrasonic specialists with deep NDT expertise. Two strategic archetypes dominate: inspection technology originators with sensor fusion capabilities and industrial automation conglomerates with mill-floor integration scale. Competitive moves concentrate on leasing structure innovation and hybrid modality convergence rather than pure hardware displacement.
Specialists in optical inspection architectures include Xiris Automation, which occupies a position among automated welding integrators, and ScanMaster Systems, a representative of deep ultrasonic expertise serving European pipeline fabricators. FOERSTER anchors the magnetic flux leakage segment within German-speaking industrial corridors. These three exemplify how technology-specific positioning shapes competitive differentiation in a market where regulatory compliance documentation requirements elevate system reliability over pure cost competition.
| Leading Market Players |
|---|
| Xiris Automation |
| ScanMaster Systems (IRT) |
| Blue Star Industrial Solutions |
| Evident |
| FOERSTER |
| Magnetic Analysis Corporation |
| Precitec |
| ESAB |
| Micro-Epsilon |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on German and Japanese precision manufacturing clusters for high-frequency ultrasonic transducers and laser profilometry components determines both pricing tier spreads and supply chain shape. Pipeline operators and fabricators face elevated procurement risk as these specialized sensors anchor system performance, compressing margins for mid-tier buyers while premium integrators capture certification-grade premiums.
Pricing Analysis
Certification level creates the primary spread across EN ISO 17640, API 5L, and EU Pressure Equipment Directive compliance tiers. Three-tier pricing structure across premium, standard, and economy levels reflects audit-trail depth, sensor fusion capability, and after-sales service bundling. Cost compression in the economy tier is intensifying because mid-market pipeline fabricators cannot absorb capital-intensive inline crawler systems without leasing structures. Municipal utilities in gas distribution networks exhibit highest price sensitivity due to constrained procurement budgets, while Permian Basin operators demonstrate lowest sensitivity given spill liability exposure and PHMSA audit scrutiny.
Supply Chain Analysis
Extended payment terms from European fabricators to German and Japanese component suppliers are becoming standard as capital discipline tightens across North American shale corridors. High-frequency ultrasonic transducers, precision laser profilometry arrays, and phased-array electronics draw from concentrated manufacturing bases in Germany, Japan, and select US defense-adjacent suppliers. Single-source vulnerability for piezoelectric ceramic substrates creates exposure to export control friction and logistics chokepoints in precision optics corridors. Distribution runs through automated welding integrators, third-party NDT service providers, and direct mill-floor deployments by original equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation between North American performance-based standards and European prescriptive certification regimes is fragmenting competitive space, creating niche opportunities for modality-specialist vendors and regional compliance experts.
For Market Incumbents: Build switching-cost moats through embedded predictive analytics at the weld head and legacy SCADA integration capabilities. Xiris Automation and ScanMaster Systems should deepen ultrasonic-optical sensor fusion R&D to preempt hybrid modality convergence. Certification investment in EN ISO 17640 and API 5L parallel compliance protects against regulatory divergence friction eroding cross-border margins. For New Entrants and Emerging Players: Pursue leasing-based deployment models for fixed weld monitoring stations in mid-market pipeline fabricators previously excluded by capital constraints. Alberta oil sands export routes and Dutch hydrogen pipeline retrofit programs represent the most penetrable geographies given emerging adaptation codes. Go-to-market positioning as operational expenditure partners rather than capital equipment vendors unlocks procurement authority at construction firms and quality assurance labs. For Investors and Strategic Acquirers: PHMSA integrity management rule recasts and EU hydrogen pipeline adaptation code finalization reshape the acquisition landscape toward inspection technology originators with sensor fusion capabilities. Long-term viability favors vendors with demonstrated mill-floor integration scale and regulatory documentation automation. Watch for ASNT Level II technician scarcity forcing acquisition premiums for training-capable NDT service platforms as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Phased-Array Ultrasonic Platform Integration | Captures full volumetric weld maps for API 5L digitized compliance documentation in Gulf Coast fabricators. |
| Leasing Structure Innovation | Converts capital expenditure barriers into recurring revenue streams across Permian Basin gathering operators. |
| Hybrid Modality Convergence | Combines laser profilometry seam geometry with subsurface ultrasonic validation for single-pass certification. |
| Hydrogen Pipeline Certification Pathway | Positions systems for embrittlement-sensitive weld inspection under emerging EU hydrogen infrastructure standards. |
| SCADA Integration Partnership | Reduces commissioning complexity with decades-old data acquisition architectures in established mill environments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with pipeline integrity managers, NDT service directors, automated welding integrators, and PHMSA compliance officers. Secondary validation drew from API standards documentation, PHMSA enforcement data, EU Pressure Equipment Directive recast texts, and SEC filings of publicly traded pipeline operators. Bottom-up equipment deployment tracking and top-down infrastructure investment analysis were triangulated against regulatory deadline schedules.
Calibration against historical replacement cycle timing and regulatory compliance expenditure patterns shaped projections across the analysis window. Segmentation dimensions modeled include system type, technology modality, application fluid, end-user procurement authority, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating Permian Basin drilling intensity, Alberta oil sands export capacity additions, and EU hydrogen pipeline retrofit timelines as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in steel commodity pricing, North American-European exchange rate volatility, or pipeline construction financing availability would shift the trajectory. Forecasts reflect documented assumptions regarding PHMSA rule enforcement intensity and EU hydrogen code crystallization timing. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Production Testing Market
Test and Measurement
Miniature Atomic Clock Market
Test and Measurement
Water Leakage Tester Market
Test and Measurement
5G Testing Devices Market
Test and Measurement
Portable Appliance Tester (PAT) Market
Test and Measurement
Universal Testing Machine Market
Test and Measurement
Inline Metrology Market
Test and Measurement
RFID Tester Market
Test and Measurement
Non-Destructive Testing Market
Test and Measurement
Global Laser Tracker Market
Test and Measurement
Shock Data Logger Market
Test and Measurement
Global NVH Testing Market
Test and Measurement
Calorimeters Market
Test and Measurement
Test Rig Market
Test and Measurement
Power Semiconductor Wafer-Level Reliability Test Equipment Market
Test and Measurement
Backside Power Delivery Network (BPDN) Analysis Test Equipment Market