
 Global 5G Test Equipment Market | 2026-2036
Global 5G Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global 5G Test Equipment Market Analysis
Direct sales channels for 5G test equipment is rewriting how vendors reach telecommunications providers and system integrators. Keysight Technologies leverages its calibration laboratories to sustain long-term service contracts with tier-one operators. Rohde & Schwarz anchors European demand through its conformance testing portfolios for Sub-6 GHz and mmWave bands. Anritsu competes aggressively in Asian markets with compact field-testing platforms designed for dense urban deployment schedules.
5G test equipment comprises specialized instrumentation for validating radio frequency performance, protocol compliance, and network throughput across new radio specifications operating from 600 MHz to 100 GHz. These systems employ vector signal analyzers with modulation analysis bandwidths exceeding 2 GHz to characterize beamforming performance in massive MIMO arrays, serving the essential purpose of certifying base stations and user equipment before commercial network integration. Signal analyzers command the largest revenue pool given their centrality to spectrum clearance and interference hunting, while mmWave testers represent the fastest-expanding technology segment as operators densify high-band coverage. Field testing applications generate disproportionate capital allocation compared with laboratory environments, reflecting carrier urgency to reduce time-to-market for 5G standalone networks.
The FCC governs equipment authorization through its Office of Engineering and Technology, mandating specific emission limits that shape test protocol requirements for US-bound hardware. ETSI in Europe and China's MIIT enforce divergent conformance frameworks, compelling manufacturers to maintain region-specific calibration routines and software loadouts. Stakeholders must monitor spectrum reallocation proceedings in multiple jurisdictions, as mid-band refarming decisions directly alter the addressable test case portfolios vendors must support.
Market Dynamics
Millimeter-wave densification is forcing equipment refresh cycles as carriers validate beamforming arrays across 28 GHz and 39 GHz bands before commercial activation.
Growth Catalysts
- Spectrum Auction Momentum:The FCC's mid-band auction framework in the United States is compelling operators to expand field-testing fleets. Equipment vendors benefit from mandated pre-deployment validation protocols.
- Massive MIMO Rollouts:Base station manufacturers require vector signal analyzers with modulation bandwidths exceeding 2 GHz. This specification pull sustains demand for high-performance instrumentation.
- South Korea Deployment Schedules:Aggressive base station buildouts by Korean operators concentrate capital allocation in field-testing applications rather than laboratory environments.
Market Restraints
- Calibration Supply Concentration:Specialized mmWave calibration services concentrate in Germany and the United States, creating geographic bottlenecks for Asian equipment purchasers.
- Input Cost Volatility:Indium phosphide substrates for high-frequency semiconductors experience price swings that compress margins on premium signal analyzer lines.
- Regulatory Fragmentation:Divergent ETSI, FCC, and MIIT conformance frameworks force manufacturers to maintain parallel software loadouts and calibration routines.
Strategic Opportunities
- India Spectrum Liberalization:TRAI's proposed mmWave band assignments for enterprise private networks create demand for localized test equipment distribution.
- Automotive V2X Integration:Convergence between 5G NR and C-V2X protocols opens validation contracts with tier-one automotive suppliers entering connected vehicle programs.
- Open RAN Disaggregation:Multi-vendor interoperability testing requirements generate service contract opportunities beyond traditional hardware sales channels.
Industry Challenges
- RF Engineering Talent Scarcity:Millimeter-wave circuit design expertise concentrates in a narrow pool of specialists, constraining vendor R&D expansion timelines.
- Certification Timeline Compression:Accelerated base station deployment schedules compress the window for completing MIIT and FCC equipment authorization procedures.
- Legacy Protocol Coexistence:Test platforms must simultaneously validate 5G NR, LTE fallback, and non-3GPP IoT protocols, multiplying software complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 5G Test Equipment Market |
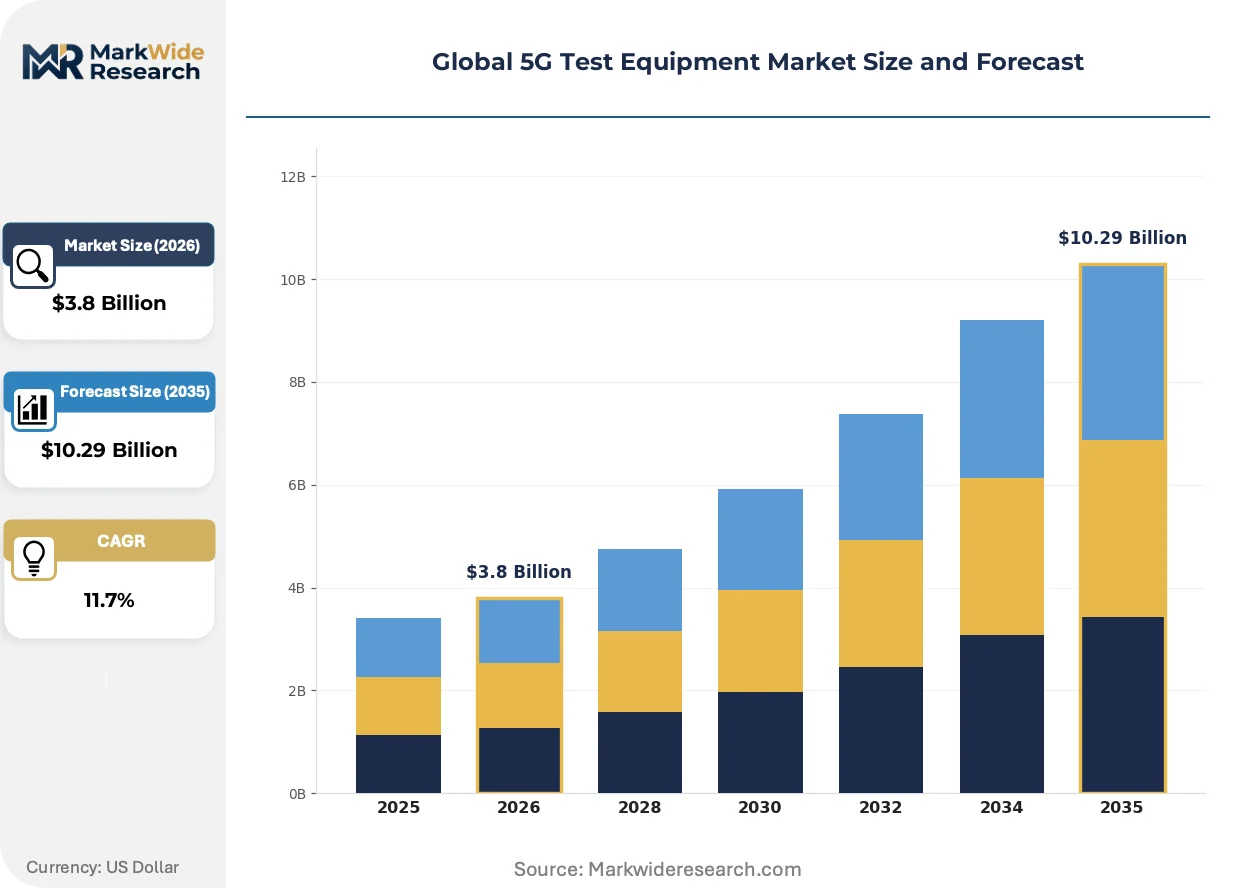
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Network Testers, Signal Analyzers, Protocol Analyzers, Collaboration Tools Technology: Sub-6 GHz, mmWave, Massive MIMO, Integrated Application: Field Testing, Laboratory Testing, R&D, Performance Optimization End User: Telecommunications Providers, System Integrators, Enterprises, Government Agencies |
| Companies Covered | Keysight Technologies, Rohde & Schwarz, Anritsu, VIAVI Solutions, Spirent Communications, Tektronix, National Instruments, EXFO Inc., Teradyne Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 5G Test Equipment Market Emerging Trajectories
Cloud-native test orchestration is compressing capital deployment models as operators shift from owned instrumentation to subscription-based validation services.
Software-defined radio architectures are digitizing hardware functions previously executed by discrete analog components. Network equipment manufacturers adopt these platforms for rapid protocol updates without physical swaps. This digitization is collapsing the traditional boundary between laboratory and field-testing equipment categories.
China's MIIT licensing regime is tightening emission limit enforcement for base station equipment entering commercial networks. Manufacturers must demonstrate compliance across expanded temperature and humidity ranges. Sub-6 GHz test portfolios face the steepest recalibration burden under these expanded environmental test matrices.
Telecommunications providers are unbundling after-sales service contracts from initial hardware purchases. System integrators and direct vendor relationships now compete for multi-year calibration and software maintenance agreements. This pattern concentrates in South Korea and Japan, where operators prioritize uptime guarantees over capital ownership.
Global 5G Test Equipment Market Segmentation
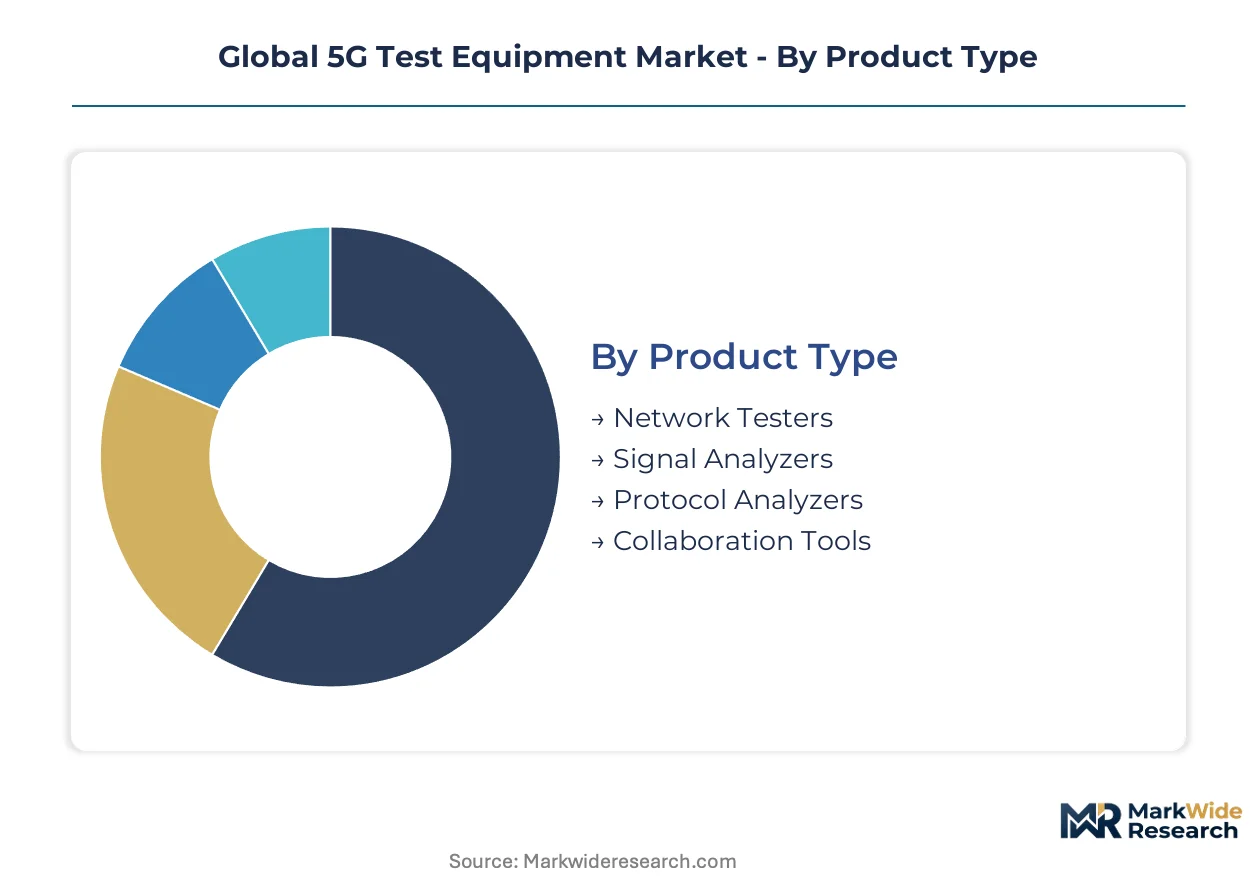
5G test equipment segmentation reveals how capital allocation splits between laboratory precision and field deployment urgency. Equipment specifications diverge sharply across frequency bands, with mmWave validation demanding fundamentally different instrumentation than Sub-6 GHz conformance testing.
Product Type:
Cost tier stratification separates high-frequency signal analyzers from portable network testers and software-centric protocol tools.
- Signal Analyzers:Vector signal analyzers with modulation bandwidths exceeding 2 GHz characterize beamforming performance in massive MIMO arrays. South Korean operators deploy these for pre-commercial base station validation, driven by aggressive 28 GHz rollout schedules.
- Network Testers:Portable platforms integrate spectrum clearance and interference hunting capabilities for field technicians. Demand concentrates with telecommunications providers in dense urban corridors where beam alignment verification cannot wait for laboratory cycles.
- Protocol Analyzers:Software-defined platforms validate 5G NR signaling conformance against 3GPP specifications.
- Collaboration Tools:Cloud-native orchestration layers coordinate distributed test fleets across multi-site deployment programs.
Signal analyzers hold installed capacity. Network testers are rotating up the share rankings.
Technology:
Application requirements split the market between proven Sub-6 GHz infrastructure and emerging mmWave densification programs.
- mmWave:Test systems for 28 GHz and 39 GHz bands validate beamforming arrays under FCC emission limits. Field testing applications in the United States consume disproportionate capital as carriers densify high-band coverage before commercial activation.
- Massive MIMO:Specialized instrumentation measures spatial multiplexing performance across 64T64R and 128T128R antenna configurations. China's MIIT licensing regime tightens environmental test matrices for these arrays, expanding calibration burdens.
- Sub-6 GHz:Mature test portfolios support mid-band refarming across 3.5 GHz and 2.5 GHz assignments.
- Integrated:Multi-band platforms consolidate Sub-6 GHz and mmWave validation to reduce equipment refresh cycles.
Sub-6 GHz holds installed capacity. mmWave is rotating up the share rankings.
Application:
Customer urgency determines whether capital flows to controlled laboratory environments or accelerated field validation.
- Field Testing:Portable analyzers and drive-test platforms certify beam alignment and handover performance under live network conditions. South Korean operators prioritize these applications over laboratory environments to compress time-to-market for standalone 5G networks.
- R&D:Pre-standardization testing supports 3GPP release evolution and proprietary feature development. Equipment manufacturers in Germany and the United States maintain captive R&D labs for next-generation massive MIMO prototyping.
- Laboratory Testing:Controlled chambers execute conformance protocols against ETSI and FCC emission frameworks.
- Performance Optimization:Post-deployment tuning addresses coverage gaps and interference sources in operational networks.
Field testing holds installed capacity. R&D is rotating up the share rankings.
End User:
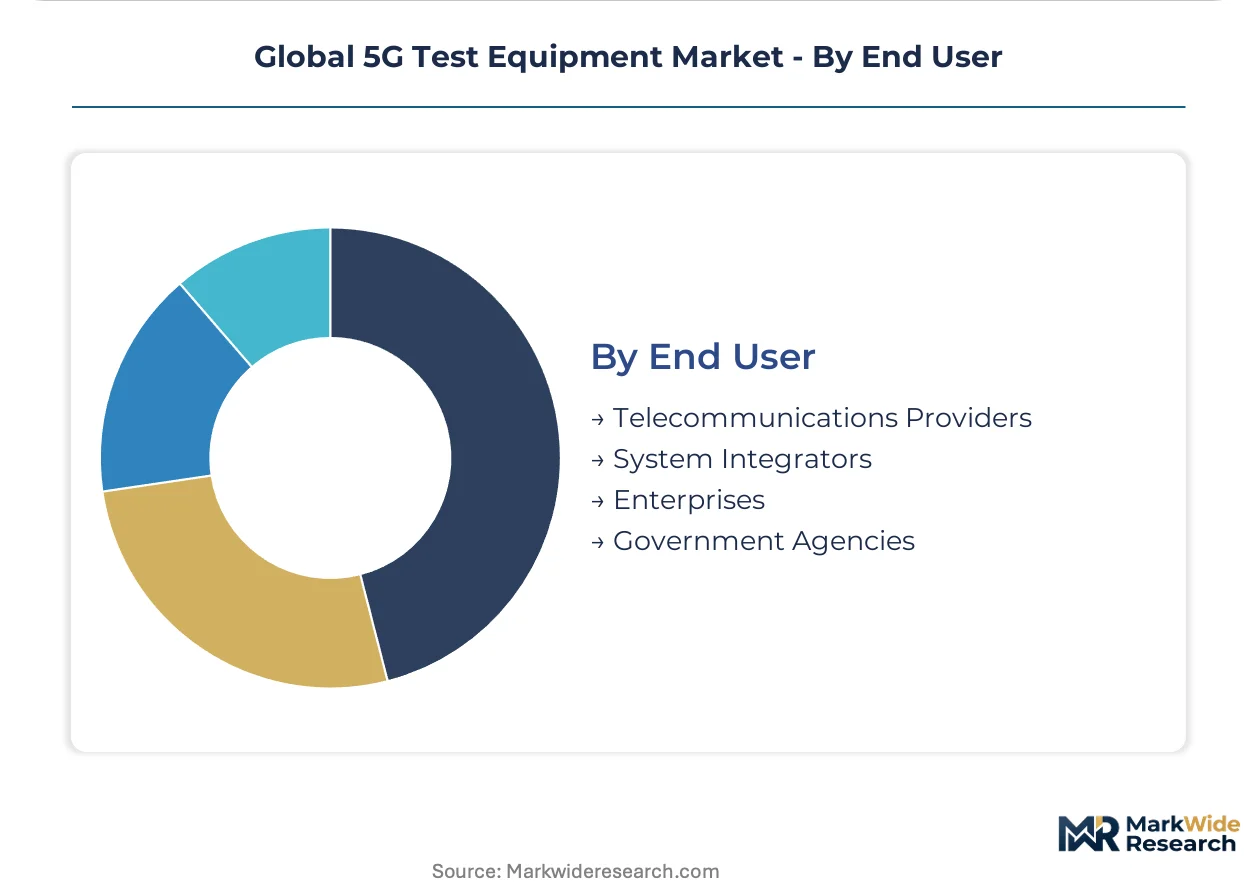
Procurement authority separates capital-rich telecommunications providers from contract-driven system integrators and emerging enterprise adopters.
- Telecommunications Providers:Tier-one operators in South Korea, the United States, and Japan own the largest installed bases of 5G test equipment. Direct vendor relationships and multi-year calibration contracts sustain Keysight Technologies and Rohde & Schwarz service revenues.
- System Integrators:Contract validation services for Open RAN disaggregation and multi-vendor interoperability testing. These intermediaries gain share as network equipment manufacturers unbundle hardware from deployment services.
- Enterprises:Private 5G network adopters in manufacturing and logistics require localized test capabilities.
- Government Agencies:Spectrum regulators and defense programs acquire specialized instrumentation for monitoring and secure communications validation.
Telecommunications providers hold installed capacity. System integrators are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment pricing power tilts toward German and US calibration hubs, while Asian purchasers absorb freight premiums and extended lead times for millimeter-wave validation systems.
United States
FCC spectrum auctions for 28 GHz and 39 GHz bands drive carrier capital allocation toward field-testing fleets. The FCC's Office of Engineering and Technology mandates specific emission limits that shape test protocol requirements for domestic hardware. Silicon Valley clusters concentrate cloud-native test orchestration development, while Boston-area labs prototype next-generation massive MIMO arrays.
China
MIIT licensing regimes tighten environmental test matrices for base station equipment entering commercial networks. China's MIIT enforces expanded temperature and humidity compliance ranges that recalibrate Sub-6 GHz portfolios. Shenzhen and Beijing house the densest concentrations of protocol analyzer development for 3GPP conformance validation.
South Korea
Aggressive 28 GHz rollout schedules by tier-one operators prioritize field testing over laboratory environments to compress time-to-market. The MFDS spectrum framework accelerates equipment authorization timelines for standalone 5G networks. Seoul Capital Area clusters drive demand for compact portable analyzers serving dense urban beam alignment verification.
Germany
ETSI conformance frameworks anchor European demand for Sub-6 GHz and mmWave validation portfolios. Rohde & Schwarz calibration laboratories sustain long-term service contracts with regional operators. Munich and Stuttgart industrial corridors concentrate vector signal analyzer production for 2 GHz-plus modulation bandwidth specifications.
Japan
METI industrial policy supports R&D pre-standardization testing for 3GPP release evolution. Japanese operators unbundle after-sales service contracts from initial hardware purchases, prioritizing uptime guarantees. Tokyo-Osaka corridors concentrate multi-year calibration and software maintenance agreement competition between system integrators and direct vendor relationships.
Global 5G Test Equipment Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying discrete instrumentation modules. The vendor base concentrates around three tiers: full-stack test platform providers, signal analyzer specialists, and software-defined protocol tool developers. Strategic archetypes include calibration-anchored service contractors, field-portable equipment specialists, and cloud-native orchestration layer providers. Competitive moves center on multi-year service contract unbundling from hardware sales and geographic expansion of calibration laboratory networks.
Within the full-stack platform tier, Keysight Technologies and Rohde & Schwarz exemplify calibration-anchored service contractors sustaining long-term operator relationships. Anritsu occupies a position among field-portable equipment specialists competing in Asian deployment corridors. These three entities represent distinct geographic anchoring patterns: US-based, German-based, and Japanese-based competitive positioning.
| Leading Market Players |
|---|
| Keysight Technologies |
| Rohde & Schwarz |
| Anritsu |
| VIAVI Solutions |
| Spirent Communications |
| Tektronix |
| National Instruments |
| EXFO Inc. |
| Teradyne Inc. |
| Others |
Supply Flow & Price Mechanics
Munich and Stuttgart industrial corridors anchor European vector signal analyzer production, concentrating 2 GHz-plus modulation bandwidth capacity and feeding pricing power downstream to calibration-anchored service contractors. German and US calibration hubs command premium positioning while Asian purchasers absorb freight premiums and extended lead times for millimeter-wave validation systems.
Pricing Analysis
Configured-to-order pricing for massive MIMO test platforms commands spreads over standard signal analyzer configurations, with customization premiums widening for FCC and MIIT environmental test matrix compliance. Equipment vendors deploy subscription-based SaaS-tiered pricing for cloud-native test orchestration layers, while transactional per-unit sales dominate portable field-testing platforms. Price differentiation hinges on certification grade—ISO 17025 calibration tiers separate premium instrumentation from economy field units—and geographic delivery cost, with Indium phosphide substrate volatility compressing margins on premium lines. Telecommunications providers in South Korea and Japan show lowest price sensitivity, prioritizing uptime guarantees and multi-year calibration contracts over capital ownership.
Supply Chain Analysis
Supplier-financing facilities from German calibration laboratories extend payment terms for Asian equipment purchasers, easing working capital strain on field-testing fleet expansions. Manufacturing concentrates in Germany, the United States, and Japan, with vector signal analyzer production anchored in Munich-Stuttgart corridors and protocol analyzer development clustering in Silicon Valley and Shenzhen. Indium phosphide substrates, high-frequency semiconductors, and precision RF components draw from specialized foundries, creating single-source vulnerability for mmWave instrumentation modules. Distribution runs through direct vendor relationships with tier-one operators and system integrators, with unbundled service contracts now competing for multi-year calibration and software maintenance agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open RAN disaggregation is reconfiguring platform economics, with multi-vendor interoperability requirements fragmenting procurement authority from single-stack vendors to distributed system integrators and test orchestration layers.
For Market Incumbents: Build calibration-laboratory network moats to lock in long-term service contracts with tier-one operators facing compressed MIIT and FCC certification timelines. Expand captive capacity for Indium phosphide substrate sourcing to buffer margin compression from input cost volatility. Defensive positioning against cloud-native orchestration entrants requires anchoring software maintenance agreements to hardware refresh cycles, particularly in South Korean and Japanese markets where uptime guarantees dominate procurement criteria. For New Entrants and Emerging Players: India's TRAI spectrum liberalization for enterprise private networks offers underpenetrated white-space for localized test equipment distribution partnerships. Automotive V2X validation contracts present a second penetrable entry point, with tier-one suppliers entering connected vehicle programs requiring 5G NR and C-V2X protocol convergence testing. A software-defined radio go-to-market angle bypasses capital-intensive hardware manufacturing, enabling rapid protocol updates without physical swaps to capture R&D and field-testing substitution demand. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors field-portable equipment specialists with compact platform portfolios aligned to dense urban deployment schedules. Long-term viability rests on capturing calibration service revenue streams rather than transactional hardware margins, with 5G-Advanced and 6G pre-standardization activity extending replacement cycles. Signal to watch: MIIT emission limit enforcement tightening and ETSI-FCC harmonization progress, either of which would recalibrate addressable test case portfolios and vendor competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Network Expansion | Keysight Technologies and Rohde & Schwarz sustain long-term operator relationships through German and US hub density. |
| Cloud-Native Test Orchestration Platform Launch | Silicon Valley clusters compress capital deployment models for operators shifting from owned instrumentation to subscription validation. |
| Automotive V2X Validation Partnership | Tier-one automotive suppliers entering connected vehicle programs open 5G NR and C-V2X protocol convergence contracts. |
| India Distribution Channel Establishment | TRAI's proposed mmWave band assignments for enterprise private networks create localized test equipment demand. |
| Open RAN Interoperability Certification Program | Multi-vendor testing requirements generate service contract opportunities beyond traditional hardware sales channels. |
Methodological Framework
Initial hypotheses were tested against primary input from RF engineering directors at base station manufacturers, telecommunications provider network deployment leads, calibration laboratory operations managers, and regulatory affairs specialists at test equipment vendors, and refined through secondary validation. Primary interviews combined with FCC equipment authorization filings, ETSI conformance framework documentation, MIIT licensing regime updates, and 3GPP release specifications. Bottom-up triangulation across product type, technology, application, and end user segmentation dimensions was cross-checked against top-down macroeconomic and spectrum auction flow assumptions.
Demand-supply balance framing anchored the analytical framework across the analysis window, with equipment refresh cycle timing, carrier capital expenditure patterns, and regulatory authorization timelines as core demand drivers. Segmentation dimensions modeled include product type tier, frequency band technology, field versus laboratory application, and procurement authority by end user. CAGRs were derived from installed base rotation analysis and replacement cycle compression factors, with Indium phosphide substrate cost trajectories and spectrum reallocation proceedings as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native orchestration entrants or automotive V2X specialists would shift outcomes beyond modeled ranges. Forecasts reflect assumptions regarding calibration service contract unbundling velocity and Open RAN disaggregation penetration. Macroeconomic deviation, regulatory harmonization acceleration, or millimeter-wave beamforming technology breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Micro Ohmmeter Market
Test and Measurement
Pump Testers Market
Test and Measurement
Electromagnetic Compatibility Test Equipment and Testing Services Market
Test and Measurement
Solar Clamp Meter Market
Test and Measurement
Field Inspection Tester Market
Test and Measurement
Fiber Optic Test Equipment (FOTE) Market
Test and Measurement
Global Laser Tracker Market
Test and Measurement
Online Weld Seam Quality Monitoring Test Systems for Steel Pipelines Market
Test and Measurement
Eddy Current Testing Market
Test and Measurement
Global Conductivity Meters Market
Test and Measurement
Force Gauge Market
Test and Measurement
Industrial X-Ray Inspection System Market
Test and Measurement
Failure Analysis Equipment Market
Test and Measurement
Test and Measurement Sensors Market
Test and Measurement
Dosimeter Market
Test and Measurement
Diamond Tester Market