
 Continuous Level Measurement Market | 2026-2036
Continuous Level Measurement Market Size, Share, and Industry Trends Forecast 2026-2036
Continuous Level Measurement Market Analytics
Process industries are unwinding their reliance on manual dipstick and sight-glass methods as continuous digital monitoring becomes the default specification. Water treatment utilities now specify non-contact radar instruments for clarifier and digester applications, a shift that Endress+Hauser leverages through its guided wave radar portfolio. Siemens anchors European chemical sector demand with integrated level-to-control system architectures. VEGA Grieshaber specializes in 80-GHz radar transmitters that penetrate foam and vapor layers that disable ultrasonic alternatives.
Continuous level measurement encompasses instruments that track material height or volume in tanks, silos, and vessels without process interruption, typically operating via microwave, ultrasonic, or hydrostatic pressure principles with accuracy specifications reaching ±1 millimeter in critical custody-transfer applications. Radar sensors dominate margin pools in oil and gas storage terminals where high-temperature hydrocarbon vapors destroy capacitance probes. Ultrasonic instruments retain cost advantages in ambient water and wastewater applications where foam suppression is manageable. Guided wave radar technology is displacing magnetostrictive sensors in hygienic food processing lines where CIP cycles degrade mechanical float mechanisms.
EPA mandates under the Clean Air Act push petroleum refineries toward sealed tank emission controls that require continuous level data for vapor recovery unit optimization. IEC 61508 functional safety standards compel sensor redundancy in chemical reactor applications, tightening vendor qualification thresholds. FDA 21 CFR Part 11 compliance for electronic records shapes food and pharmaceutical batch documentation requirements. Buyers must weigh total cost of ownership against calibration intervals when specifying instruments for remote upstream installations where technician access is constrained.
Market Dynamics
Petroleum refineries face EPA Clean Air Act mandates that compel sealed tank vapor recovery systems, forcing wholesale replacement of mechanical gauges with continuous digital instruments that feed real-time level data into emission control infrastructure.
Growth Catalysts
- EPA Emission Mandates:US petroleum storage terminals must install continuous monitoring for vapor recovery unit optimization, eliminating manual dipstick methods entirely.
- IEC 61508 Functional Safety:Chemical reactor applications now require redundant sensor architectures, tightening vendor qualification thresholds and locking in premium instrument specifications.
- 80-GHz Radar Penetration:Advanced microwave frequencies cut through foam and vapor layers that disable ultrasonic alternatives, opening digester and clarifier applications in water treatment.
Market Restraints
- Semiconductor Component Volatility:Radar transceiver chip supply concentrates in Taiwan and South Korea, exposing lead times to geopolitical friction and foundry allocation cycles.
- Technical Limitation in Cryogenic Service:Ultrasonic transducers fail below minus forty degrees Celsius, excluding LNG storage and aerospace fuel tank applications.
- REACH Compliance Burden:European chemical registration requirements add eighteen to twenty-four month certification timelines for new transmitter materials entering EU markets.
Strategic Opportunities
- India Water Infrastructure:Central government smart city initiatives specify non-contact radar for sewage treatment plants, creating first-mover advantage for vendors establishing local calibration facilities.
- Battery Electrolyte Monitoring:Lithium-ion gigafactories need corrosion-resistant level instruments for hydrofluoric acid tanks, an application barely served by incumbent hydrostatic suppliers.
- Edge Computing Convergence:Integration of radar transmitters with on-device analytics reduces SCADA dependency, enabling predictive maintenance contracts in remote upstream oil installations.
Industry Challenges
- Functional Safety Engineering Shortage:SIL certification expertise concentrates among aging specialists in Germany and Switzerland, constraining project execution timelines for complex chemical installations.
- Legacy System Integration Friction:Brownfield refineries run 4-20mA analog loops that resist digital HART protocol upgrades, forcing expensive signal converter deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuous Level Measurement Market |
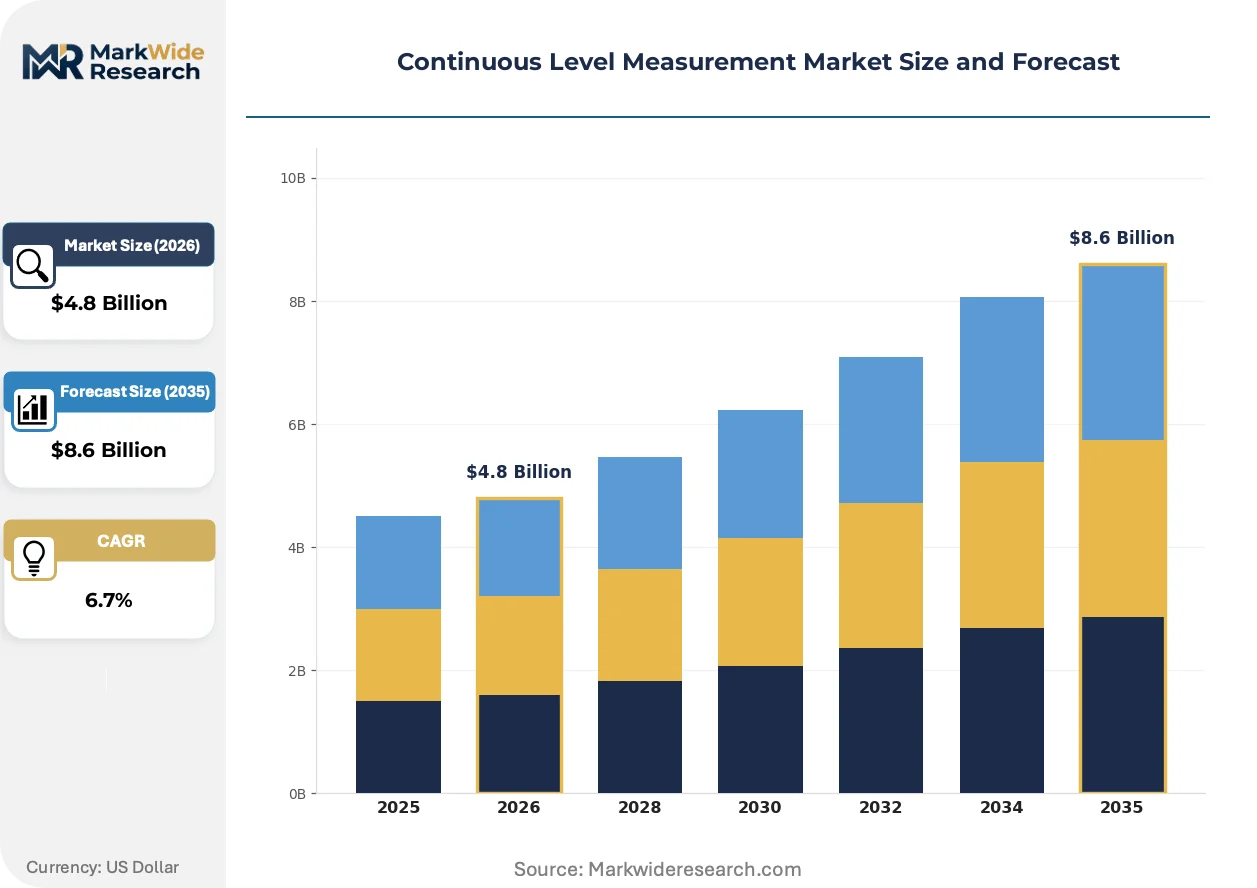
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitance Sensors, Ultrasonic Sensors, Radar Sensors, Magnetostrictive Sensors Technology: Guided Wave Radar, Non-contact Radar, Hydrostatic Pressure, Optical Measurement Application: Water Treatment, Oil & Gas, Food Processing, Chemicals End User: Utilities, Manufacturing, Mining, Agriculture |
| Companies Covered | Emerson Electric, Endress+Hauser, Siemens, ABB, Honeywell International, AMETEK, Yokogawa Electric, VEGA Grieshaber, KROHNE Messtechnik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuous Level Measurement Market Evolving Landscape
Sensor architecture is compressing toward chip-scale integration while regulatory pressure hardens documentation requirements, reshaping how vendors compete on total cost of ownership rather than hardware price alone.
Silicon-based radar-on-chip modules are miniaturizing 80-GHz frequency generation onto single-die transceivers, collapsing transmitter housing dimensions by two-thirds. Food and pharmaceutical processors adopt these compact units for hygienic vessels where CIP spray balls demand minimal intrusion. The technology is miniaturizing instrument footprints below two-inch nozzle sizes, opening tank designs previously reserved for capacitance probes.
REACH authorization lists now restrict perfluorinated compounds in radar antenna coatings, forcing reformulation of hydrophobic surfaces that prevent product buildup. German chemical manufacturers face eighteen-month material requalification cycles. Instrument suppliers with pre-validated alternative coatings capture specification locks in European pharmaceutical and fine chemical procurement.
Buyers now unbundle hardware procurement from calibration service contracts, compressing switching costs and intensifying aftermarket competition. Water utilities in the US Great Lakes region lead this shift, separating transmitter purchase from five-year metrology agreements. Distributors respond with certified mobile calibration labs that challenge manufacturer service organizations.
Continuous Level Measurement Market Segmentation
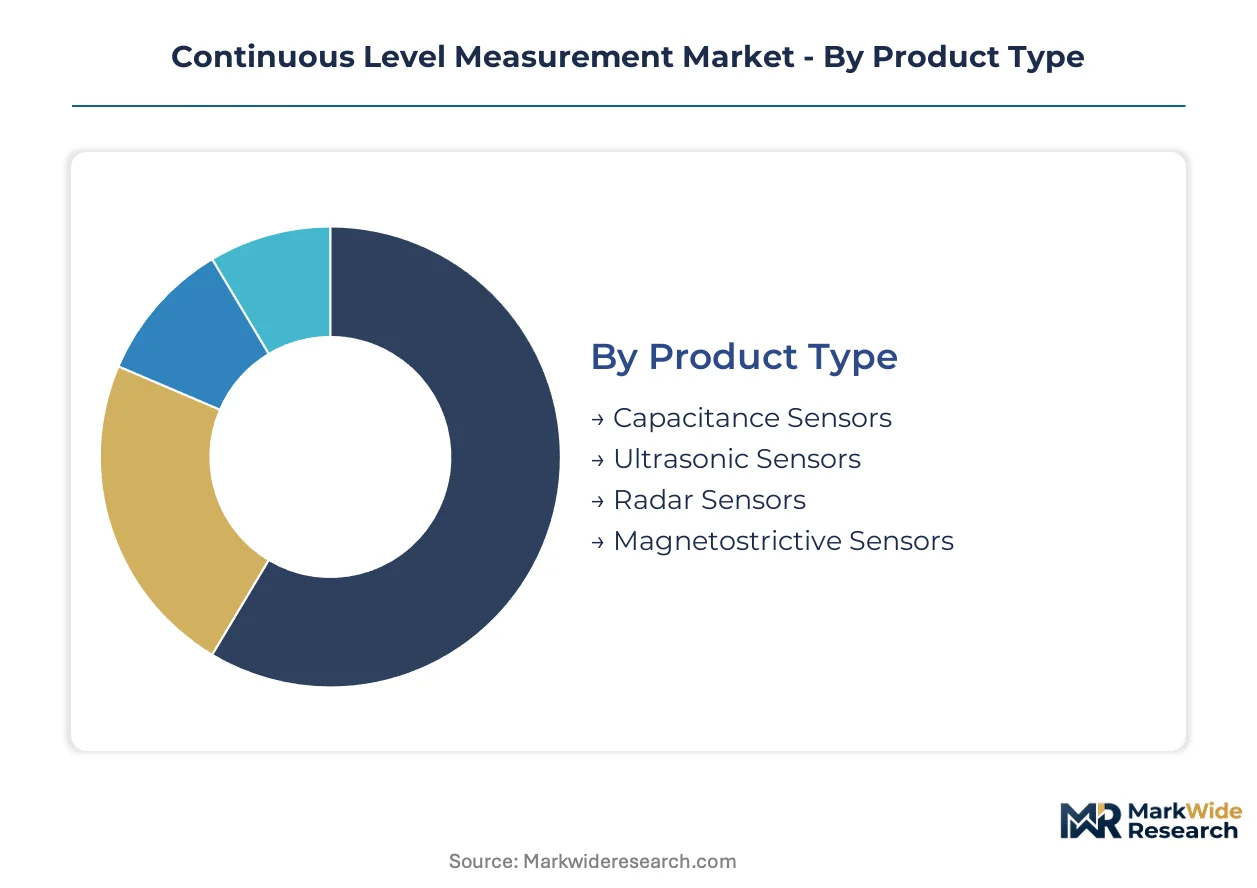
Technology selection in continuous level measurement follows application-specific constraints around temperature extremes, foam interference, and hygiene requirements. Procurement patterns diverge sharply between capital-intensive process industries and cost-sensitive municipal utilities.
Product Type:
Radar and ultrasonic sensors dominate distributor stocking programs, while capacitance and magnetostrictive variants move primarily through direct specification engineering.
- Radar Sensors:Microwave-based transmitters operate at 80-GHz frequencies that penetrate hydrocarbon vapors and foam layers. Petroleum refineries in Texas and Louisiana specify these for sealed tank vapor recovery systems mandated under EPA Clean Air Act rules.
- Ultrasonic Sensors:Acoustic pulse-echo devices offer lower unit economics for ambient liquid applications. Water treatment utilities across the US Great Lakes region deploy these for clarifier level monitoring where foam suppression remains manageable.
- Capacitance Sensors:Dielectric measurement probes suit conductive liquid storage in chemical tank farms.
- Magnetostrictive Sensors:Float-driven position sensing retains niche use in legacy fuel storage installations.
By volume, ultrasonic sensors lead. By growth pace, radar sensors are expanding most quickly.
Technology:
Margin structures vary substantially across these four approaches, with non-contact radar commanding premium pricing against commoditized hydrostatic alternatives.
- Non-contact Radar:Free-space microwave transmission eliminates mechanical intrusion. German chemical manufacturers favor these for reactor vessels where REACH compliance restricts coating materials in antenna assemblies.
- Guided Wave Radar:Probe-guided microwave signals concentrate energy for interface detection. Food processors adopt compact chip-scale versions for hygienic vessels with CIP spray ball clearance constraints.
- Hydrostatic Pressure:Submerged transducers convert liquid head to electrical signals. Mining slurry applications in Western Australia specify these for thickened tailings monitoring.
- Optical Measurement:Laser-based time-of-flight instruments serve specialized solids level applications in cement silos.
By installed base, hydrostatic pressure dominates. By specification momentum, guided wave radar is gaining share fastest.
Application:
Regulatory intensity shapes procurement patterns, with oil and gas and chemicals facing the most stringent continuous monitoring mandates.
- Oil & Gas:Storage terminal operators require SIL-certified redundancy for custody transfer measurement. EPA emission controls force replacement of mechanical gauges with digital instruments feeding vapor recovery optimization systems.
- Chemicals:Reactor level monitoring demands IEC 61508 functional safety compliance. European producers face eighteen-month material requalification cycles under REACH authorization lists.
- Water Treatment:Municipal utilities specify non-contact instruments for digester and clarifier applications. Indian smart city initiatives create first-mover opportunities for vendors establishing local calibration infrastructure.
- Food Processing:Hygienic design requirements favor compact radar units that withstand CIP cycles.
By revenue concentration, oil and gas leads. By expansion trajectory, water treatment is climbing the fastest.
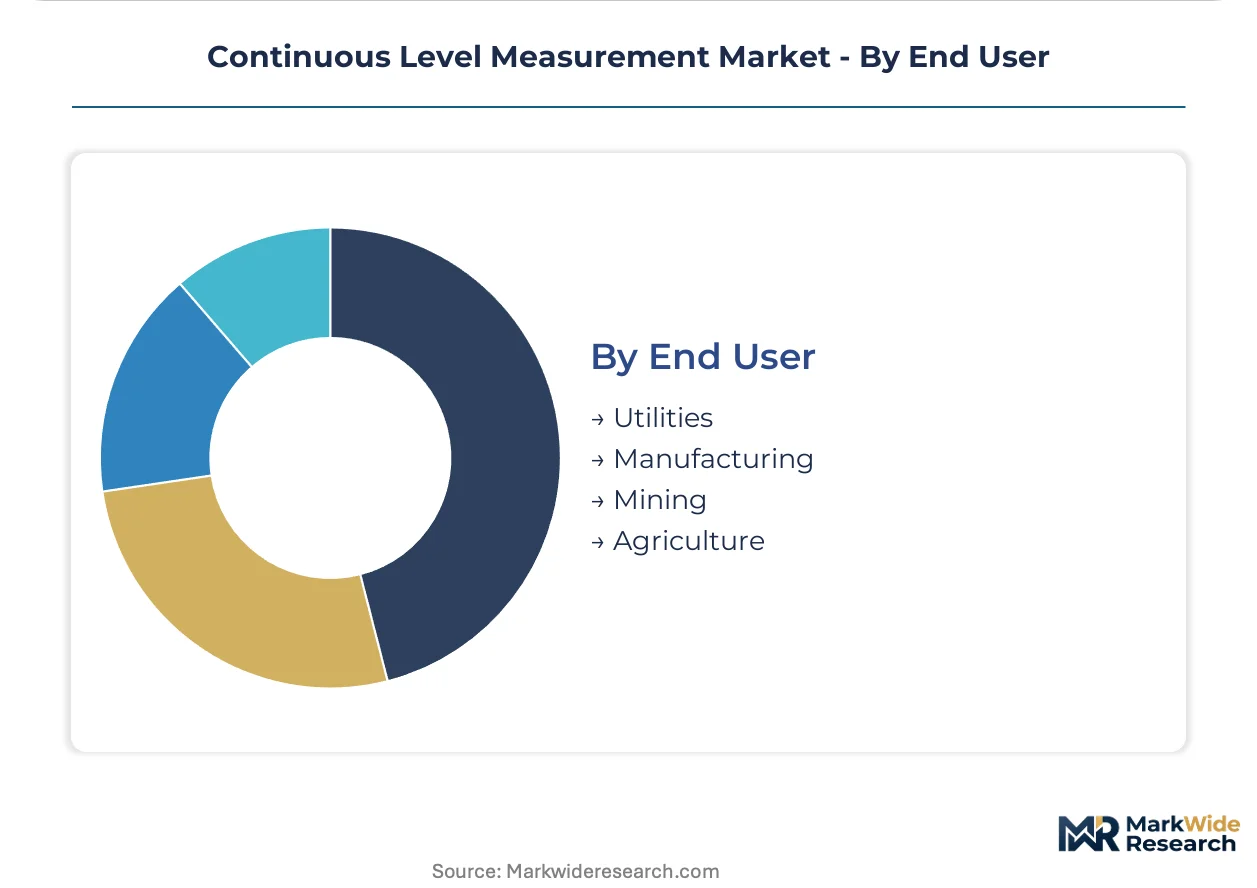
End User:
Utility procurement increasingly unbundles hardware from service contracts, compressing switching costs and intensifying aftermarket competition.
- Utilities:Water and wastewater authorities drive volume demand with standardized specifications. US Great Lakes utilities now separate transmitter purchase from five-year metrology agreements.
- Manufacturing:Process industries integrate level data into DCS architectures for batch control. Battery gigafactories need corrosion-resistant instruments for hydrofluoric acid electrolyte tanks.
- Mining:Remote upstream installations constrain technician access and extend calibration intervals.
- Agriculture:Grain silo monitoring represents a price-sensitive segment with limited digital integration requirements.
By unit shipments, utilities lead. By technology upgrade intensity, manufacturing is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel's petrochemical corridor drives North American instrumentation demand as refineries modernize emission monitoring infrastructure. German precision engineering clusters anchor European supply chains. Indian smart city water infrastructure creates emerging specification opportunities.
United States
EPA Clean Air Act mandates compel petroleum storage terminals across Texas and Louisiana to replace mechanical gauges with continuous digital instruments. Vapor recovery unit optimization requires real-time level data feeds. The Houston Ship Channel's refinery corridor concentrates demand for SIL-certified radar transmitters.
Germany
REACH authorization lists restrict perfluorinated compounds in radar antenna coatings, forcing eighteen-month material requalification cycles. IEC 61508 functional safety standards tighten vendor qualification thresholds for chemical reactor applications. Endress+Hauser and VEGA Grieshaber anchor the Freiburg-Stuttgart precision instrumentation cluster serving European process automation buyers.
India
Central government smart city initiatives specify non-contact radar for sewage treatment plants in rapidly urbanizing metros. Municipal water utilities drive volume procurement for clarifier and digester level monitoring. First-mover advantage accrues to vendors establishing local calibration facilities in Maharashtra and Gujarat industrial corridors.
China
Dual carbon goals accelerate petrochemical facility upgrades requiring sealed tank emission controls. National environmental standards push refineries toward continuous monitoring architectures. Yangtze River Delta chemical processing hubs concentrate demand for corrosion-resistant level instruments in battery electrolyte and specialty chemical applications.
United Arab Emirates
ADNOC's downstream expansion and strategic petroleum reserve infrastructure sustain demand for custody-transfer grade measurement. High-temperature hydrocarbon storage applications favor radar technologies over capacitance alternatives. Dubai and Abu Dhabi industrial zones anchor Gulf Cooperation Council procurement for oil and gas terminal automation.
Continuous Level Measurement Market Competitive Landscape
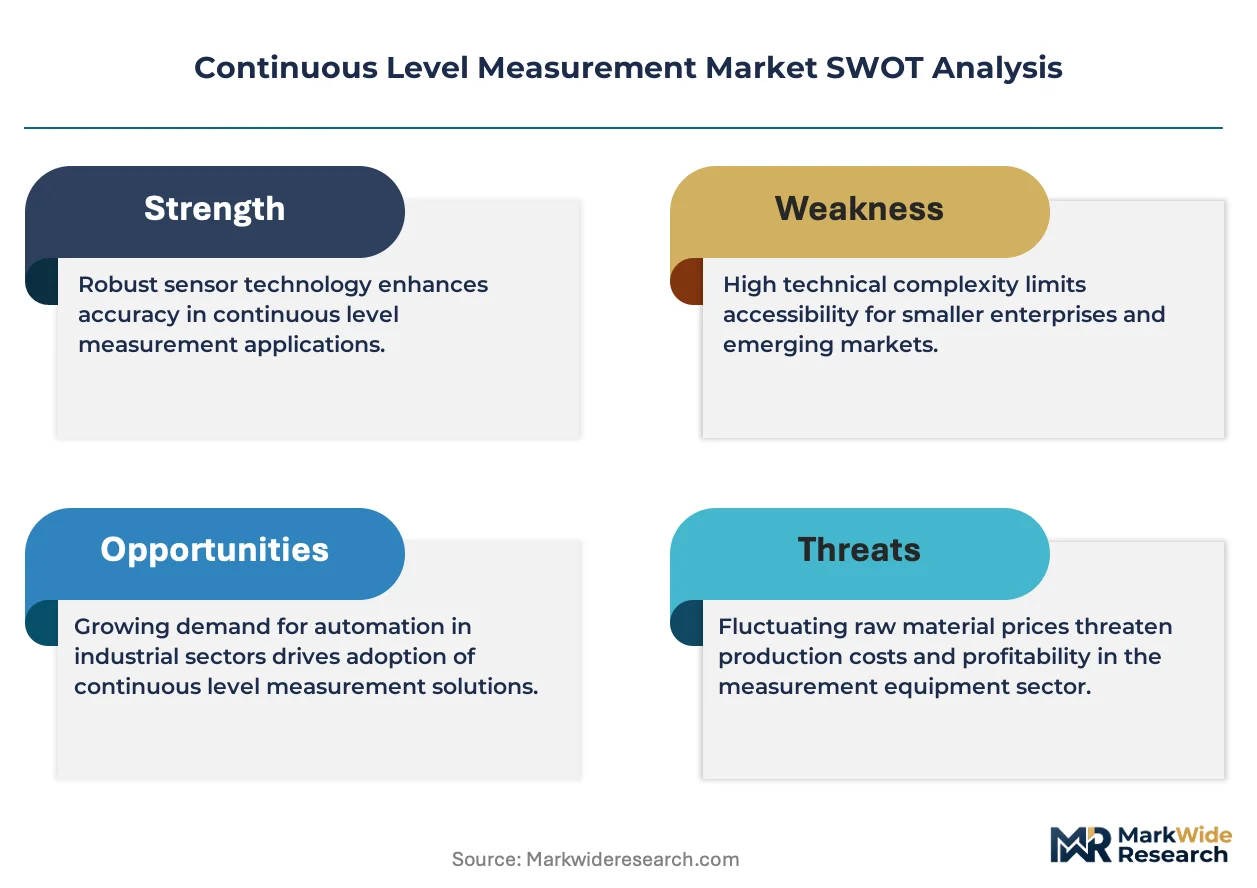
Concentration sits with diversified industrial conglomerates that leverage cross-divisional sensor portfolios. The vendor base spans three structural tiers: integrated automation platforms, specialized measurement technology firms, and regional instrumentation distributors. Competitive positioning hardens around functional safety certification depth, calibration service network density, and edge computing integration capabilities. Capacity expansion and strategic technology licensing represent the dominant competitive moves as vendors secure radar-on-chip supply agreements.
Among German precision engineering specialists, Endress+Hauser GmbH+Co. KG and VEGA Grieshaber KG occupy positions exemplifying the measurement-focused archetype, while Siemens AG represents the integrated automation platform tier. Emerson Electric Co. anchors the North American diversified industrial segment. These entities exemplify competitive positioning through geographic origin clustering and organizational structure differentiation rather than homogeneous product-line overlap.
| Leading Market Players |
|---|
| Emerson Electric |
| Endress+Hauser |
| Siemens |
| ABB |
| Honeywell International |
| AMETEK |
| Yokogawa Electric |
| VEGA Grieshaber |
| KROHNE Messtechnik |
| Others |
Value Network & Pricing Analysis
IEC 61508 functional safety certification gates both supplier qualification and price differentiation simultaneously, forcing vendors to absorb eighteen-month SIL validation cycles while petroleum refineries pay premiums for redundant sensor architectures that manual alternatives cannot satisfy.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates SIL-certified radar transmitters for custody-transfer applications from basic ultrasonic units for municipal water monitoring. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying because water utilities now unbundle hardware procurement from calibration contracts. Municipal buyers across the US Great Lakes region exhibit the highest price sensitivity, while oil and gas terminal operators accept premium positioning for vapor recovery compliance.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for radar transceiver modules sourced from Taiwan and South Korea. Manufacturing concentrates in Germany, Switzerland, and China, with final assembly drawing from silicon-based radar-on-chip components, specialty antenna coatings, and precision machined housings. Single-source vulnerability sits with Taiwan foundries producing 80-GHz transceiver dies. Distribution runs through authorized distributors with certified calibration capabilities serving brownfield refinery corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Clean Air Act enforcement is accelerating displacement of mechanical gauges, creating a high-growth disruption window for vendors with sealed tank emission control architectures.
For Market Incumbents: Fortify SIL certification depth and service network density against emerging chip-scale radar specialists. Prioritize backward integration into radar-on-chip supply agreements to secure transceiver allocation. Expand calibration infrastructure in the Houston Ship Channel and German chemical corridors to lock in long-term metrology contracts.
For New Entrants and Emerging Players: Lead with corrosion-resistant level instruments for lithium-ion battery electrolyte tanks, an application barely served by incumbent hydrostatic suppliers. Target Indian smart city water infrastructure with local calibration partnerships in Maharashtra and Gujarat. Pursue direct specification engineering with municipal utilities rather than distributor stocking programs.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across radar-on-chip manufacturing as foundry allocation tightens. Long-term viability favors vendors with captive semiconductor supply or pre-validated REACH-compliant coating formulations. Watch for EPA enforcement intensity in Texas and Louisiana as the signal for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Radar-on-Chip Supply Agreement | Secures Taiwan foundry allocation for 80-GHz transceiver modules ahead of competitor lock-in. |
| REACH-Compliant Coating Pre-Validation | Captures specification locks in German pharmaceutical procurement before eighteen-month requalification cycles conclude. |
| Mobile Calibration Lab Deployment | Challenges manufacturer service organizations in US Great Lakes water utility accounts. |
| Edge Computing Integration | Reduces SCADA dependency for predictive maintenance contracts in remote upstream oil installations. |
| Local Calibration Facility Buildout | Captures first-mover advantage in Indian smart city sewage treatment plant specifications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads at petroleum refineries, chemical manufacturers, and water treatment utilities. Secondary validation drew from EPA enforcement databases, IEC certification registries, customs trade data, and SEC filings of diversified industrial conglomerates. Bottom-up unit demand estimates and top-down market sizing were triangulated against distributor stocking patterns and project pipeline tracking.
Across the projection horizon, the analytical framework modeled technology type, application vertical, end-user procurement pattern, and regional regulatory cluster. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic indicators and capital expenditure trajectories. Forecast inputs incorporated EPA mandate implementation timelines, REACH authorization list expansions, and foundry capacity allocation cycles for radar transceiver components.
Forecasts assume regulatory continuity in EPA Clean Air Act enforcement and REACH authorization procedures; material policy shifts would require re-modeling. Semiconductor supply disruptions, geopolitical friction in Taiwan Strait logistics, or accelerated IEC 61508 revision cycles could compress or extend replacement timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Europe Nondestructive Testing Equipment Market
Test and Measurement
Stability Test Chamber Market
Test and Measurement
Environmental Test Chambers Market
Test and Measurement
Digital Inspection Tools Market
Test and Measurement
Test Benches Market
Test and Measurement
Dew Point Apparatus Market
Test and Measurement
Radiation Effects Testing Market
Test and Measurement
Automated Optical Inspection Market
Test and Measurement
Ceramic Tester Market
Test and Measurement
Hearing Aid and True Wireless Earbud Acoustic Performance Test Systems Market
Test and Measurement
Power Electronics GaN and SiC Device Reliability Test Systems Market
Test and Measurement
EMC Shielding and Test Equipment Market
Test and Measurement
Industrial Direct Radiography Market
Test and Measurement
Medical-Grade Flexible Electronics Bending and Fatigue Test Systems Market
Test and Measurement
Over-The-Air (OTA) Testing Market
Test and Measurement
Tensile Testers Market