
 Digital Weighing Machine Market | 2026-2036
Digital Weighing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Weighing Machine Market Outlook
Asset-light leasing models for precision weighing equipment are reshaping competitive dynamics in the digital weighing machine sector. Mettler-Toledo International Inc. leverages its service-contract infrastructure to lock in recurring revenue from pharmaceutical clients. A&D Company, Limited anchors its position through deep specialization in analytical balances for Japanese laboratory markets. Rice Lake Weighing Systems competes aggressively on floor-scale customization for North American agricultural cooperatives.
A digital weighing machine integrates load-cell or strain-gauge transducers with analog-to-digital conversion circuitry to measure mass with resolutions from 0.01 milligrams in analytical grades to 50,000 kilograms in industrial truck scales, serving quality control, trade settlement, and regulatory compliance functions across commercial and industrial settings. Industrial scales command the deepest margin pools where calibration-certification bundling protects pricing power, while kitchen scales face commoditization pressure from unbranded Asian electronics assemblers. Strain-gauge technology dominates volume shipments but capacitive sensing is gaining traction in hygienic food-contact applications where hermetic sealing prevents contamination ingress.
National Type Evaluation Program (NTEP) certification in the United States and OIML R76 compliance in Europe constrain market access for uncertified manufacturers while creating service-revenue opportunities for incumbents with accredited calibration laboratories. China's SAMR enforces periodic verification mandates for trade-use scales, reinforcing replacement-cycle predictability in that jurisdiction. Buyers should scrutinize cloud-connectivity architectures and API interoperability as distributed manufacturing sites demand real-time weight-data integration into ERP and MES platforms.
Market Dynamics
Strain-gauge-to-capacitive sensor migration and ISO 9001-aligned calibration mandates are compressing replacement cycles while fragmenting procurement authority between plant engineers and centralized quality departments.
Growth Catalysts
- Export-grade traceability rules:Food processing plants across Southeast Asia are deploying precision-weighing infrastructure to satisfy destination-market documentation requirements.
- SAMR periodic verification mandates:China's State Administration for Market Regulation enforces scheduled recertification for trade-use scales, creating predictable hardware refresh demand.
- Biologics batch-control workflows:Pharmaceutical manufacturers in China's manufacturing corridor are installing cleanroom-grade analytical balances to support cell-culture process control.
Market Restraints
- Semiconductor input cost volatility:Load-cell ADC chip pricing fluctuates with foundry capacity allocation, squeezing margin on mid-range industrial platforms.
- Calibration-laboratory concentration:Accredited metrology services cluster in Germany, the United States, and Japan, extending lead times for Brazilian and South Korean end-users.
- Capacitive sensing temperature drift:Hermetic food-contact scales suffer accuracy degradation across freeze-thaw cycles, limiting deployment in cold-chain applications.
Strategic Opportunities
- Cloud-native ERP integration:Distributed manufacturing sites in Mexico and Vietnam are demanding API-first weighing platforms that stream tare-corrected data directly into SAP and Oracle MES layers.
- Asset-light leasing models:Pharmaceutical and food-processing buyers are shifting from capex purchase to service-contract structures that bundle hardware, calibration, and software updates.
- RoHS and REACH alignment:European environmental compliance is creating specification pull for lead-free load-cell alloys and halogen-free PCB substrates.
Industry Challenges
- Metrology technician scarcity:Certified calibration specialists are concentrated in legacy industrial regions, complicating field-service coverage for remote mining and agricultural installations.
- NTEP-to-OIML dual certification timelines:Manufacturers targeting both United States and European trade markets face sequential approval processes that extend product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Weighing Machine Market |
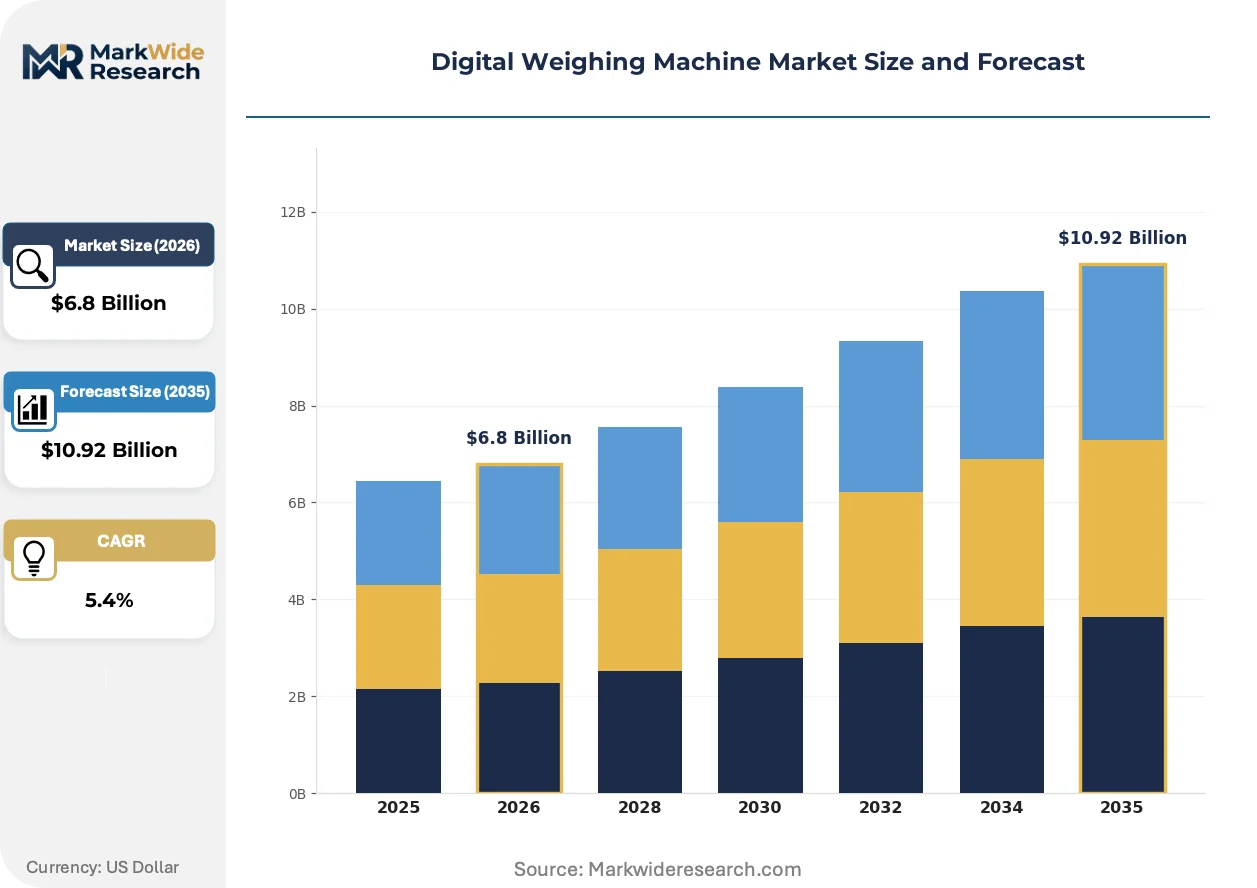
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Scales, Kitchen Scales, Industrial Scales, Floor Scales End User: Retailers, Food Industry, Healthcare Providers, Logistics Companies Technology: Load Cell, Strain Gauge, Capacitive, Electromechanical Application: Commercial Use, Home Use, Laboratory Use, Specialty Applications |
| Companies Covered | Mettler-Toledo International Inc., A&D Company, Limited, Kern & Sohn GmbH, Fairbanks Scales Inc., Shimadzu Corporation, Rice Lake Weighing Systems, Adam Equipment Ltd., Doran Scales, Inc., Avery Weigh-Tronix, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Weighing Machine Market Strategic Shifts
Capacitive sensing architectures and cloud-native data pipelines are redrawing the boundary between weighing hardware and plant-level software infrastructure.
Capacitive load-cell technology eliminates strain-gauge drift through hermetic sealing and differential capacitance measurement. Pharmaceutical fill-finish lines and aseptic food-packaging operations are adopting these sensors for continuous 24-hour runs without recalibration interruption. This is collapsing the historical trade-off between hygienic design and measurement stability that forced buyers to choose between stainless-steel strain gauges with frequent service intervals or less accurate mechanical alternatives.
REACH substance restrictions and RoHS recast directives are prohibiting lead-based solder and cadmium-plated components in European-market scales. Manufacturers are reformulating load-cell alloys and migrating to tin-silver-copper solder joints. Analytical balance producers serving German and Swiss laboratory markets are absorbing higher material costs while marketing extended service-life guarantees as compensating value.
Quality departments are consolidating weighing-equipment procurement authority away from individual plant engineers. Centralized category management teams in multinational food and pharmaceutical corporations are standardizing on single-vendor platforms with global service contracts. This concentration is most visible in North American agricultural cooperatives and Southeast Asian seafood exporters, where headquarters-level technical specifications now override local equipment preferences.
Digital Weighing Machine Market Segmentation
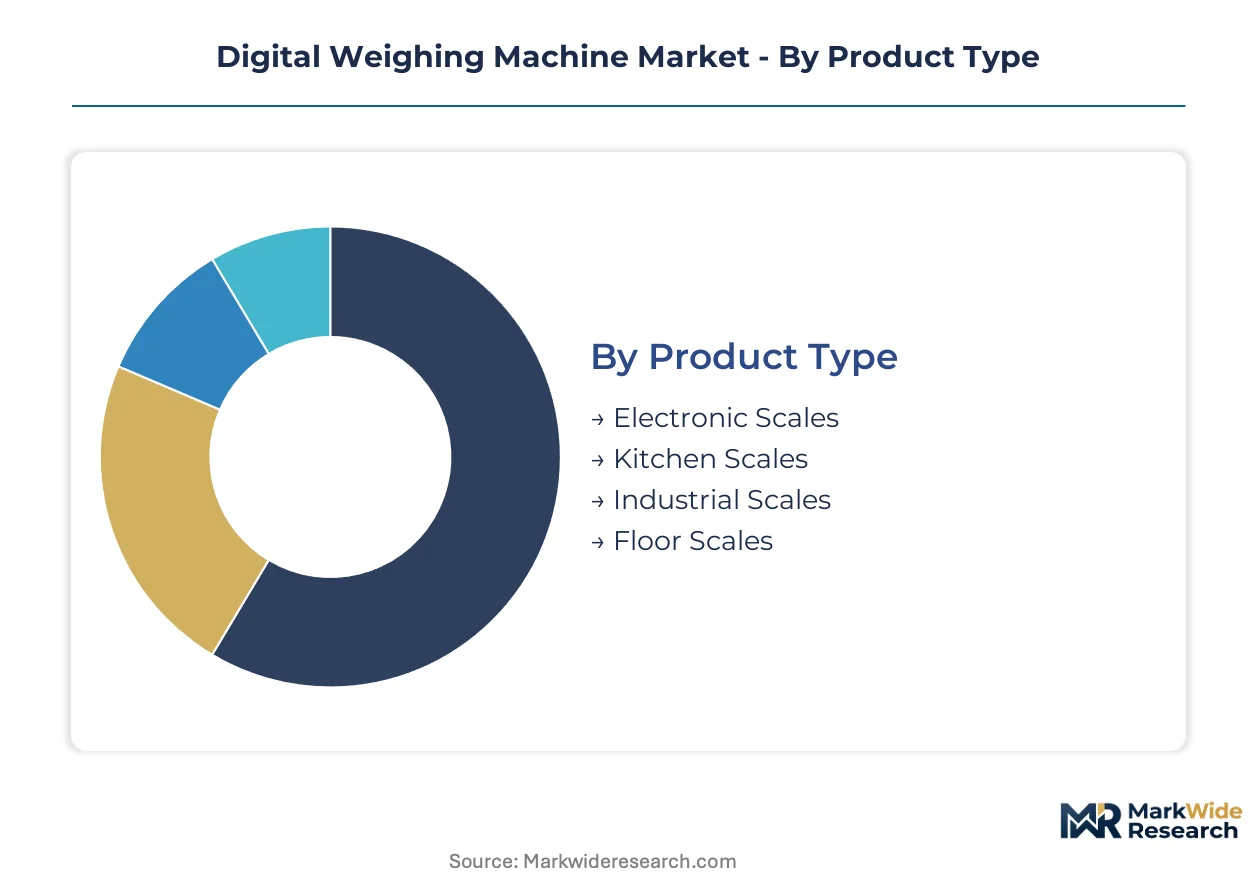
Segmentation in the digital weighing machine market reveals how procurement authority splits between plant engineers seeking durability and quality departments demanding traceability. Each dimension—product type, end user, technology, and application—carries distinct margin profiles and certification requirements that shape vendor positioning.
Product Type:
The use-case spectrum spans domestic convenience through heavy-haul industrial measurement, with certification bundling determining profitability at each tier.
- Industrial Scales:These platforms integrate hermetically sealed load cells and stainless-steel platforms rated for washdown environments. Demand concentrates in Brazilian food processing corridors where ANVISA mandates ISO 9001-aligned calibration documentation for export certification.
- Floor Scales:Pit-mounted and portable configurations handle palletized goods up to 50,000 kilograms with NTEP-certified trade settlement accuracy. North American agricultural cooperatives are standardizing on API-connected units that stream tare-corrected data into ERP systems.
- Electronic Scales:General-purpose platforms serve retail checkout and light commercial environments with strain-gauge transducers.
- Kitchen Scales:Battery-powered consumer units face commoditization pressure from unbranded Asian electronics assemblers.
Established volume favors floor scales; emerging adoption favors industrial scales with cloud-native connectivity.
End User:
Customer type determines whether procurement prioritizes capital efficiency or compliance documentation, with service-contract bundling varying sharply across sectors.
- Healthcare Providers:Cleanroom-grade analytical balances with 0.01-milligram resolution support biologics batch-control workflows. China's pharmaceutical manufacturing corridor is deploying these units under NMPA guidelines for cell-culture process validation.
- Food Industry:Hygienic designs with hermetic sealing prevent contamination ingress during aseptic packaging operations. Southeast Asian seafood exporters are upgrading precision-weighing infrastructure to satisfy destination-market traceability rules.
- Retailers:Trade-legal scales require SAMR verification in China and OIML R76 compliance in Europe.
- Logistics Companies:Dimensioning and weighing systems integrate with warehouse management platforms for freight billing.
Healthcare providers command premium pricing through calibration-certification bundling; food industry buyers are shifting fastest toward asset-light leasing structures.
Technology:
Sensor architecture dictates the trade-off between measurement stability and environmental resilience, with migration patterns reshaping component supply chains.
- Strain Gauge:Metal-foil resistive elements bonded to deforming substrates dominate volume shipments through mature manufacturing economics. German and South Korean calibration mandates are steering procurement toward certified digital platforms with documented traceability chains.
- Capacitive:Differential capacitance measurement eliminates drift through hermetic sealing, enabling continuous 24-hour runs without recalibration interruption. Pharmaceutical fill-finish lines are adopting these sensors where freeze-thaw temperature stability has improved.
- Load Cell:Integrated transducer-and-conditioning modules serve mid-range industrial platforms.
- Electromechanical:Lever-and-pivot mechanical designs persist in legacy installations and explosive-atmosphere environments.
Strain gauge retains installed-base dominance; capacitive architectures are gaining share fastest in hygienic food-contact applications.
Application:
Deployment context determines whether specifications prioritize precision, durability, or connectivity integration with plant-level software infrastructure.
- Laboratory Use:Analytical balances with electromagnetic force restoration achieve microgram resolution for formulation and quality control. Swiss and German laboratory markets are absorbing higher material costs from RoHS and REACH compliance while marketing extended service-life guarantees.
- Specialty Applications:Explosion-proof, high-temperature, and radioactive-environment scales serve mining and chemical processing with custom engineering. Remote installations face metrology technician scarcity that complicates field-service coverage.
- Commercial Use:Trade settlement scales require national type approval and periodic verification.
- Home Use:Consumer-grade kitchen and bathroom scales operate outside regulatory compliance frameworks.
Laboratory use sustains margin concentration through certification complexity; specialty applications represent the steepest expansion trajectory as process industries automate hazardous-area operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR verification mandates and ISO 9001-aligned calibration requirements are steering procurement patterns across major industrial economies. The analysis traces demand concentration through five national markets where regulatory enforcement and export-grade traceability rules are reshaping equipment refresh cycles.
China
Pharmaceutical manufacturers in the Yangtze River Delta corridor are installing cleanroom-grade analytical balances for biologics batch-control workflows. SAMR enforces periodic verification mandates for trade-use scales, creating predictable hardware replacement demand. Shanghai and Suzhou pharmaceutical clusters are absorbing premium-grade equipment under NMPA cell-culture process validation guidelines.
Germany
REACH substance restrictions and RoHS recast directives are prohibiting lead-based solder in laboratory-grade balances. German calibration laboratories anchor European metrology service capacity, extending influence over Brazilian and South Korean end-user certification timelines. Bavaria and Baden-Württemberg precision engineering clusters are reformulating load-cell alloys to maintain market access.
United States
North American agricultural cooperatives are standardizing on API-connected floor scales that stream tare-corrected data into ERP systems. NTEP certification requirements constrain market access for uncertified manufacturers while creating service-revenue opportunities for incumbents with accredited calibration laboratories. Midwest grain handling facilities and California food processing plants are consolidating procurement authority under headquarters-level technical specifications.
Brazil
ANVISA mandates ISO 9001-aligned calibration documentation for export certification in food processing corridors. Strain-gauge technology upgrades are compressing replacement cycles as plants modernize precision-weighing infrastructure. São Paulo state meatpacking and poultry processing clusters are deploying hermetically sealed industrial scales to satisfy destination-market traceability rules.
Japan
Japanese laboratory markets sustain deep specialization in analytical balances with 0.01-milligram resolution. METI-aligned quality standards and JIS certification requirements protect domestic equipment preferences against lower-cost imports. Osaka and Tokyo metropolitan laboratory clusters are absorbing higher material costs from environmental compliance while marketing extended service-life guarantees.
Digital Weighing Machine Market Competitive Environment
On the supply side, the industry is consolidating around three distinct capability tiers. Premium-tier vendors bundle calibration-certification services with hardware to protect margin pools in pharmaceutical and laboratory segments. Mid-range industrial specialists compete on floor-scale customization and API connectivity for agricultural and logistics end-users. Volume-tier assemblers face commoditization pressure in consumer kitchen scales where unbranded Asian electronics dominate shelf space. Strategic moves center on asset-light leasing model expansion and cloud-native ERP integration partnerships.
Within the premium-tier service-contract segment, Mettler-Toledo International Inc. and A&D Company, Limited exemplify divergent geographic anchoring strategies. Mettler-Toledo occupies a position emphasizing recurring revenue infrastructure across pharmaceutical client bases. A&D Company, Limited represents deep specialization in analytical balances for domestic Japanese laboratory markets. Rice Lake Weighing Systems sits within the mid-range customization tier, competing on floor-scale adaptation for North American agricultural cooperatives. These three entities illustrate how vendor archetypes align with distinct procurement authority splits between plant engineers and centralized quality departments.
| Leading Market Players |
|---|
| Mettler-Toledo International Inc. |
| A&D Company, Limited |
| Kern & Sohn GmbH |
| Fairbanks Scales Inc. |
| Shimadzu Corporation |
| Rice Lake Weighing Systems |
| Adam Equipment Ltd. |
| Doran Scales, Inc. |
| Avery Weigh-Tronix, LLC |
| Others |
Value Chain & Pricing Dynamics
Chinese load-cell ADC foundries and Japanese strain-gauge substrate suppliers anchor upstream concentration, feeding margin pools into calibration-certification bundling downstream where pharmaceutical and laboratory buyers absorb premium pricing for documented traceability chains.
Pricing Analysis
Certification level creates the primary spread between ISO 9001-aligned calibration tiers and uncertified commodity platforms. Three-tier pricing structure across premium, standard, and economy levels bundles hardware with metrology service contracts at the top, while mid-range industrial scales compete on API connectivity customization. Price erosion runs through consumer kitchen scales where unbranded Asian electronics assemblers eliminate brand premiums. Food processing buyers in Southeast Asia show highest price sensitivity; pharmaceutical quality departments in China's Yangtze River Delta corridor show least.
Supply Chain Analysis
Hon Hai Precision Industry and Flex hold contract-manufacturing capacity for digital weighing machine electronics assembly. Component sourcing draws from China for load-cell ADC chips, Japan for high-precision strain-gauge substrates, and Germany for calibration-grade reference masses. Single-source vulnerability concentrates in hermetic sealing ceramics for capacitive sensors. Distribution runs through authorized metrology service partners who bundle installation with periodic recertification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capacitive sensing displacement of strain-gauge architectures and cloud-native ERP integration mandates are compressing replacement cycles and redrawing competitive boundaries in this high-growth disruption.
For Market Incumbents: Entrench calibration-certification infrastructure as the primary defensive moat against emerging capacitive-sensing specialists. Expand accredited laboratory footprints into Brazil and South Korea to capture ANVISA and ISO 9001-aligned verification demand. Deepen backward integration into hermetic sealing ceramics to secure capacitive sensor supply chains against single-source concentration risk. For New Entrants and Emerging Players: Mid-market food processing facilities in Vietnam and Mexico represent the most penetrable entry point for API-first weighing platforms without legacy service-contract encumbrance. Target agricultural cooperatives seeking tare-corrected ERP data streams as beachhead accounts. Lead with SaaS-tiered pricing that bundles hardware, calibration, and software updates to match shifting procurement preferences. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native weighing platform development, reducing barrier-to-entry for software-centric entrants. Long-term viability favors vendors with captive calibration laboratory networks spanning multiple regulatory jurisdictions. Watch capacitive sensor temperature-stability improvements as the signal indicating accelerated strain-gauge displacement in pharmaceutical fill-finish applications.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Network Expansion | ANVISA and SAMR verification mandates in Brazil and China create service-revenue capture opportunities for accredited incumbents. |
| Capacitive Sensor Technology Migration | Hermetic sealing eliminates drift in pharmaceutical aseptic packaging where 24-hour continuous runs are standard. |
| Cloud-Native ERP Integration Partnership | SAP and Oracle MES layer connectivity addresses distributed manufacturing demand in Mexico and Vietnam. |
| Asset-Light Leasing Model Rollout | Service-contract structures align with pharmaceutical and food-processing procurement shifts away from capex purchase. |
| RoHS and REACH Compliance Reformulation | Lead-free load-cell alloys and halogen-free PCB substrates protect European market access under recast directives. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with plant engineers, quality department heads, metrology laboratory directors, and OEM procurement managers; and secondary validation through SAMR verification records, OIML R76 certification databases, NTEP conformity assessments, and SEC filings from listed equipment vendors. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Forecast inputs include strain-gauge versus capacitive sensor adoption curves, ISO 9001-aligned calibration mandate enforcement timelines, and cloud-connectivity penetration in food processing and pharmaceutical verticals. Segmentation dimensions span product type, end user, technology architecture, and application context. CAGRs were derived from installed-base replacement cycles and net new deployment trajectories.
Stress conditions across semiconductor input cost volatility, calibration-laboratory capacity constraints, and capacitive sensor temperature-drift limitations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory enforcement shifts or technology substitution inflection. Quarterly review of NTEP-to-OIML dual certification timelines and cloud-API standardization progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Digital Thickness Gauge Market
Test and Measurement
Compression Testing Machines Market
Test and Measurement
Active Dosimeter Market
Test and Measurement
Flying Probe Testing for PCB Assembly Market
Test and Measurement
Automated Optical Inspection (AOI) System Market
Test and Measurement
Precision Measuring Tools Market
Test and Measurement
5G Testing Equipment Market
Test and Measurement
Continuous Friction Tester Market
Test and Measurement
Height Measurement Devices Market
Test and Measurement
Metrology Software Market
Test and Measurement
Automated Optical Inspection (AOI) Equipment Market
Test and Measurement
Wireless Network Test Equipment Market
Test and Measurement
Optical Fiber Network Latency and Time Synchronization Test Equipment Market
Test and Measurement
Destructive Testing Market
Test and Measurement
MEMS and Sensor Performance and Reliability Test Equipment Market
Test and Measurement
Edge Computing Enclosure Environmental Stress Test Equipment Market