
 Canning Labels Market | 2026-2036
Canning Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Canning Labels Market Outlook
Artisanal food producers is unwinding the historical dominance of mass-market grocery private labels in canning label procurement. Avery Dennison leverages its adhesive science portfolio to serve craft beverage makers with temperature-resistant formulations. CCL Industries anchors its position through backward integration into film extrusion for metal can decoration. Constantia Flexibles competes via specialized aluminum-label lines for acidic food applications.
Canning labels are pressure-sensitive or heat-transfer substrates engineered to withstand retort sterilization, pH extremes, and condensation cycles while maintaining barcode scannability and brand legibility. Paper label stock retains cost leadership in dry-goods segments, though plastic and thermal transfer substrates are capturing share in wet-food and beverage applications where moisture resistance governs shelf-life compliance. The finish dimension stratifies across premium, standard, and economy tiers, with metallic and transparent films commanding margin pools in personal care and premium beverage cans while matte finishes dominate commodity food categories.
FDA migration testing protocols and EU REACH substrate restrictions shape material selection and supplier qualification timelines for canning label manufacturers. EPA guidelines on volatile organic compound emissions from adhesive curing processes further constrain domestic production economics in the United States. Stakeholders must monitor evolving extended producer responsibility frameworks for packaging substrates across multiple jurisdictions to anticipate compliance cost reallocations.
Market Dynamics
REACH substrate migration limits are compressing formulation flexibility for European canning label producers while specialty food demand pulls premium substrate adoption upward. The resulting tension between compliance cost accumulation and margin expansion from metallic finishes defines current competitive positioning.
Growth Catalysts
- Retort-resistant adhesives:Temperature-stable formulations enable craft beverage makers to enter shelf-stable segments previously blocked by sterilization failure. Adoption concentrates in Germany's Rhine-Ruhr packaging cluster.
- EU EPR frameworks:Extended producer responsibility mandates for packaging substrates accelerate recyclable film development. Producers qualifying early capture preferential supplier status with multinational food brands.
- Acidic food specialization:Aluminum-label lines for tomato and citrus applications address pH-driven adhesive degradation. Demand from Mediterranean canneries drives substrate innovation cycles.
Market Restraints
- Petrochemical volatility:Polypropylene and polyester resin prices swing with crude oil benchmarks. Label converters lack pricing power to pass input spikes through to consolidated food retail buyers.
- Adhesive curing emissions:EPA volatile organic compound guidelines constrain solvent-based adhesive production in the United States. Water-based alternatives sacrifice line speed and bond strength.
- Film extrusion concentration:Backward integration by major decorators limits independent label producers' supply security. Captive film capacity concentrates among three North American and European players.
Strategic Opportunities
- India FSSAI compliance:Food safety standardization creates first-mover advantage for substrate suppliers pre-qualifying migration-tested stocks. Domestic canning growth outpaces label supply maturity.
- Digital print convergence with metallization:Cold foil and inkjet hybrid systems enable short-run premium decoration. Craft distilleries and regional breweries adopt for seasonal and limited-release SKUs.
- China dual carbon goals:Carbon intensity targets for packaging materials favor lightweight film substrates over paperboard alternatives. Export-oriented canneries face buyer pressure for verified low-carbon labels.
Industry Challenges
- Migration testing timelines:FDA qualification protocols for new adhesive chemistries extend 18-24 months. Product development cycles misalign with seasonal procurement windows.
- Legacy press integration:Digital workflow adoption requires retrofitting analog flexographic lines. Smaller converters defer capital commitment amid technology uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canning Labels Market |
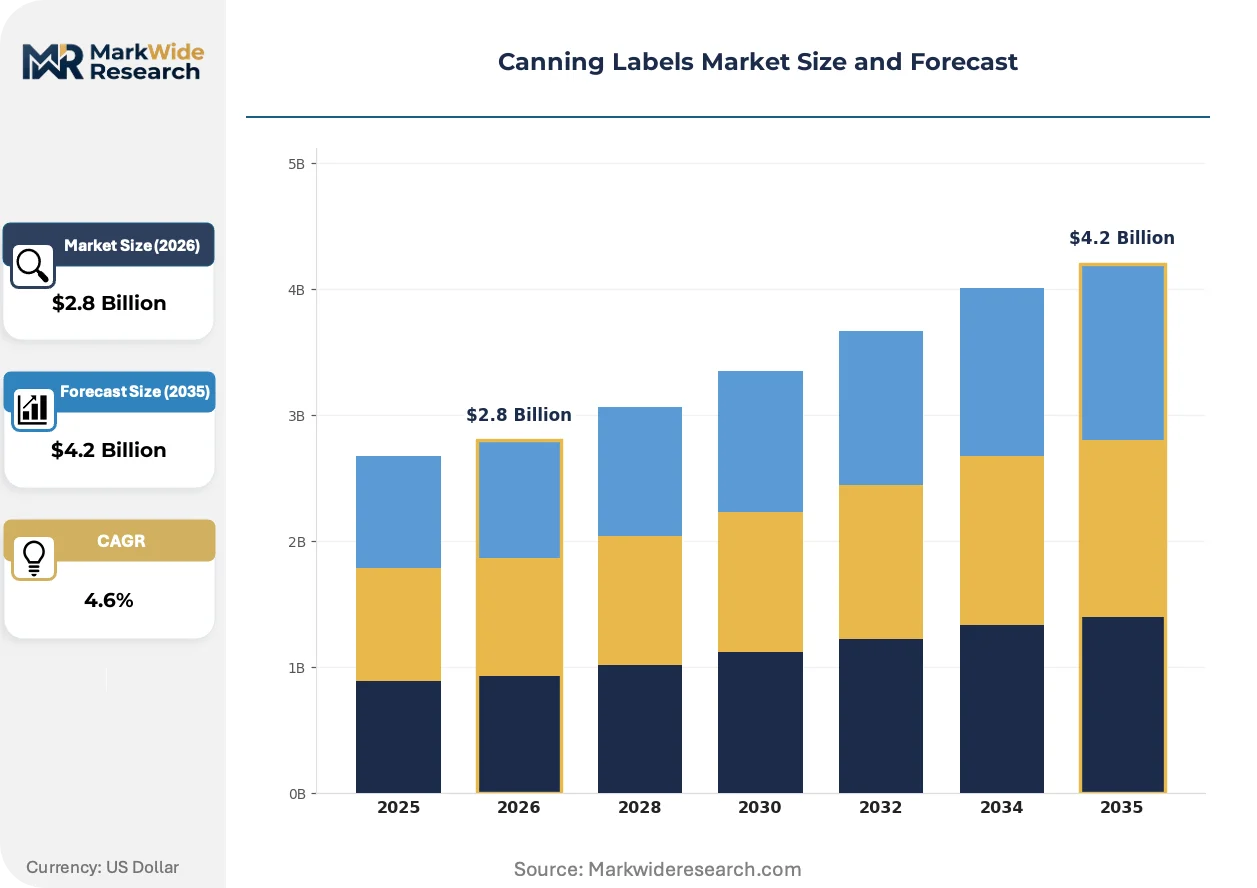
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Label Type: Paper, Plastics, Thermal Transfer, Adhesive Application: Food Products, Beverages, Personal Care, Chemicals Size: Small, Medium, Large, Custom Finish: Matte, Glossy, Transparent, Metallic |
| Companies Covered | Avery Dennison, CCL Industries, Constantia Flexibles, Berry Global, UPM-Kymmene, 3M Company, Lintec, Bemis, Henkel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canning Labels Market Strategic Shifts
Digital decoration technologies and regulatory chemistry constraints are simultaneously expanding design possibility and narrowing material choice. The resulting innovation landscape favors suppliers with dual competence in print systems and polymer science.
Water-based barrier coatings are decomposing the historical moisture-resistance advantage of plastic substrates in wet-food applications. Mid-size canneries in Spain and Portugal are adopting coated paper stocks for legumes and vegetables to satisfy retailer plastic-reduction commitments. The technology is decomposing volume concentration among synthetic film suppliers by enabling paper mills to recapture share in segments they had abandoned.
REACH Annex XVII restrictions on Substances of Very High Concern are forcing reformulation of legacy adhesive activators used in heat-transfer decoration. German and French label producers face accelerated substance substitution timelines with limited qualified alternatives. Acidic food and infant nutrition segments bear the highest compliance burden due to migration limit stringency.
Consolidated food manufacturers are compressing supplier bases to secure volume pricing and technical service depth. Single-source arrangements with decorators capable of substrate-to-print integration are displacing fragmented procurement across separate film, adhesive, and print vendors. The shift is most advanced in Benelux and Nordic markets where retailer concentration amplifies buyer leverage.
Canning Labels Market Segmentation
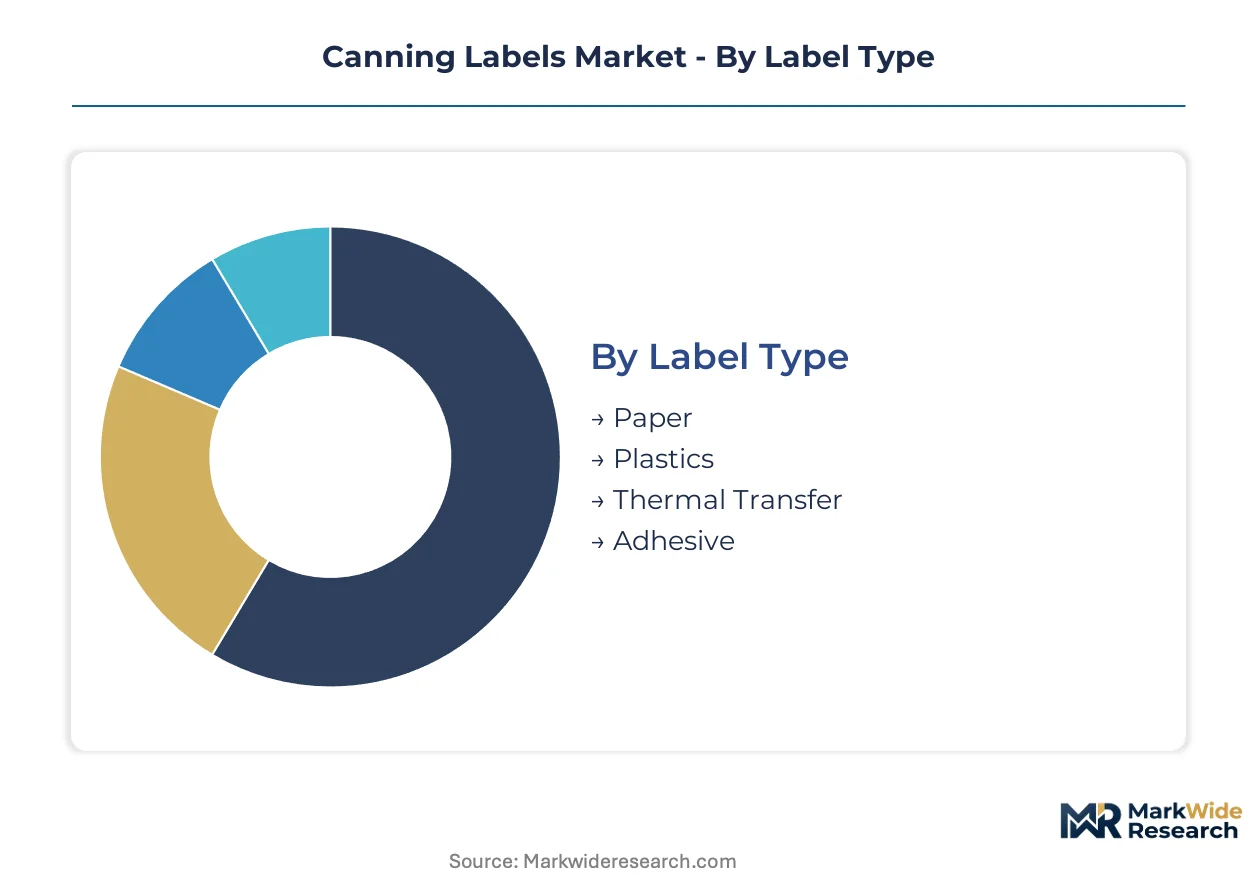
Segmentation in canning labels reveals how substrate chemistry and sterilization requirements fragment procurement patterns across food, beverage, and industrial end-uses. Material substitution pressures and regulatory migration limits reshape competitive boundaries between paper and synthetic alternatives.
Label Type:
Paper substrates face intensifying substitution pressure from moisture-resistant films in wet-food segments, while thermal transfer materials capture share in craft beverage applications requiring variable data printing.
- Paper:Cellulose-based stocks with clay coatings dominate dry-goods categories including legumes, grains, and powdered mixes. Cost leadership persists in Germany's Rhine-Ruhr packaging cluster where commodity food producers prioritize unit economics over moisture resistance. REACH substrate migration limits are accelerating coated paper development for acidic food compatibility.
- Plastics:Polypropylene and polyester films deliver moisture barrier performance essential for retort sterilization cycles in wet-food and beverage cans. Mediterranean canneries in Spain and Portugal drive polypropylene adoption for tomato and citrus applications where pH extremes degrade paper adhesives.
- Thermal Transfer:Ribbon-based imaging systems enable batch coding and variable data on-demand for craft distilleries and seasonal SKUs.
- Adhesive:Pressure-sensitive and heat-activated formulations determine bond integrity through condensation cycles and sterilization protocols.
Paper retains volume leadership; plastics hold the steepest expansion curve as wet-food applications displace legacy stocks.
Application:
Cost tier differentiation separates commodity food procurement from premium beverage and personal care decoration where metallic finishes command margin premiums.
- Food Products:Canned vegetables, legumes, soups, and ready-meals constitute the foundational demand base with procurement concentrating among consolidated retail buyers. Benelux and Nordic markets exhibit advanced supplier consolidation toward single-source decorators capable of substrate-to-print integration.
- Beverages:Craft beer, cider, and spirits producers drive premium substrate adoption with temperature-resistant adhesives enabling shelf-stable distribution. Germany's craft beverage makers anchor demand for retort-resistant metallic finishes in the Rhine-Ruhr cluster.
- Personal Care:Aerosol and tin-plate containers for cosmetics and grooming products require specialized aluminum-label lines.
- Chemicals:Industrial and agricultural chemical cans demand solvent-resistant adhesives and UV-stable substrates for outdoor storage conditions.
Food Products anchor procurement volume; Beverages generate the fastest margin expansion through premium finish adoption.
Size:
Volume concentration in standard formats contrasts with custom dimensions serving regional brands and private label differentiation strategies.
- Small:Single-serve and sample-size cans for specialty condiments and beverage trial packs require precision die-cutting and short-run digital workflows.
- Medium:Standard retail formats dominate grocery and mass-market channels with procurement scale driving converter consolidation.
- Large:Foodservice and institutional cans for restaurants and catering operations prioritize durability over decoration sophistication.
- Custom:Non-standard dimensions enable brand differentiation in premium segments with digital print convergence supporting economical short runs.
Medium formats command procurement volume; Custom sizes are expanding most quickly alongside digital decoration adoption.
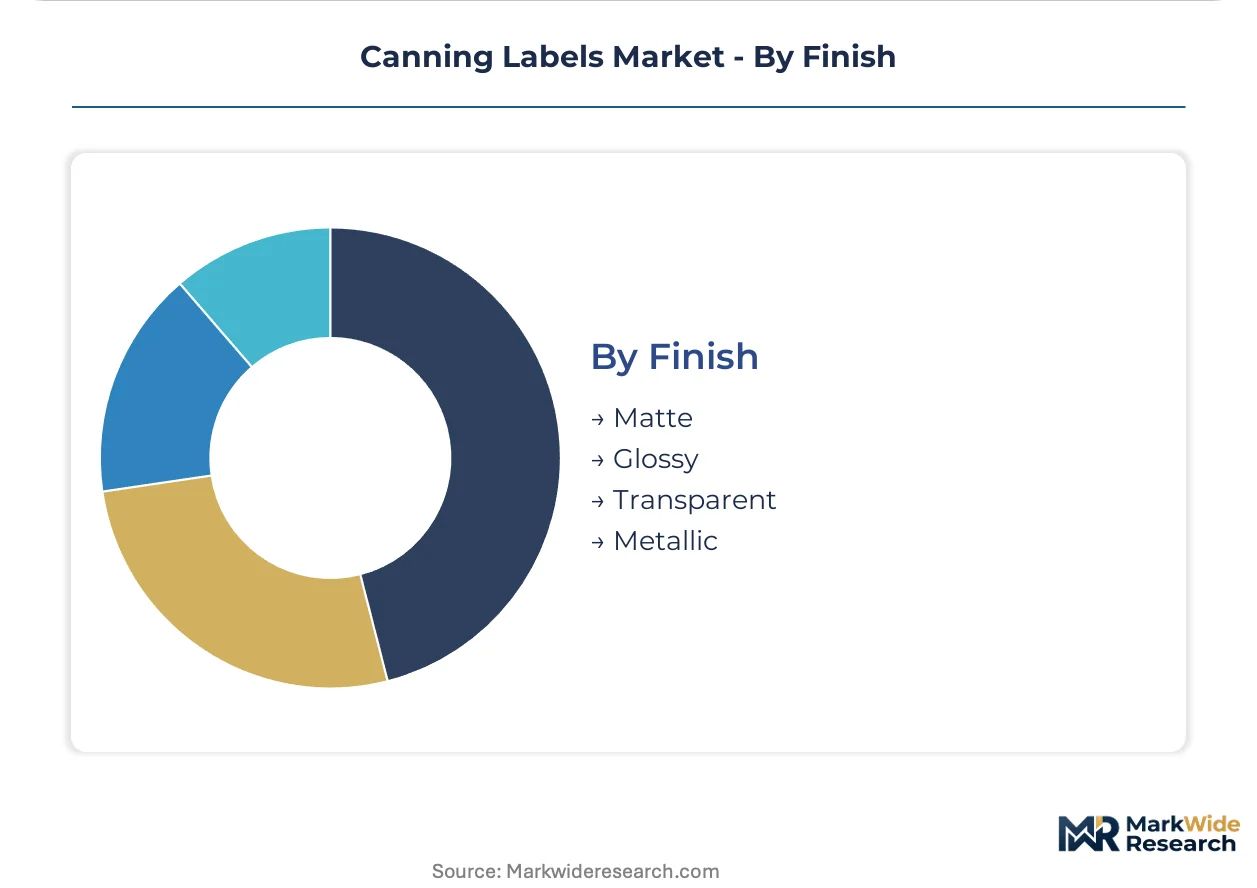
Finish:
Margin stratification across finish tiers reflects the divergence between commodity food economics and premium brand positioning in beverage and personal care segments.
- Matte:Non-reflective coatings dominate economy-tier food applications where legibility and cost control supersede shelf impact. Matte paper stocks retain preference in dry-goods segments across Benelux retail channels.
- Glossy:High-sheen varnishes enhance color saturation for mainstream beverage and food brands competing for retail visibility.
- Transparent:Clear film substrates enable no-label look aesthetics in premium water and beverage categories. Transparent plastics face EPR framework pressure for recyclable film development qualification.
- Metallic:Cold foil and metallized films command premium positioning in craft spirits, cosmetics, and gift-oriented food cans. Metallic finishes concentrate demand in Germany's specialty beverage cluster where temperature-resistant formulations enable sterilization compliance.
Matte finishes retain volume leadership; Metallic coatings follow the steepest expansion trajectory driven by craft beverage premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consolidated food retail buyers in Germany, the United States, and China concentrate procurement volume for canning labels, while craft beverage makers in secondary clusters pull premium substrate adoption.
Germany
Specialty food producers and craft beverage makers drive demand for temperature-resistant metallic finishes. REACH Annex XVII restrictions on Substances of Very High Concern force accelerated adhesive reformulation timelines. The Rhine-Ruhr packaging cluster anchors production for retort-resistant labels serving acidic food applications.
United States
Consolidated grocery retail chains and mass-market private label programs dominate procurement scale. EPA volatile organic compound guidelines constrain solvent-based adhesive curing processes in domestic production. Midwest converters face water-based alternative adoption trade-offs between compliance and line efficiency.
China
Export-oriented canneries face buyer pressure for verified low-carbon label substrates under dual carbon goals. SAMR packaging material standards and carbon intensity targets favor lightweight film alternatives. The Yangtze River Delta concentration serves seafood and vegetable processing for European and North American markets.
India
Domestic canning growth for ready-to-eat meals and processed vegetables outpaces label supply maturity. FSSAI food safety standardization creates first-mover advantage for substrate suppliers pre-qualifying migration-tested stocks. Maharashtra and Gujarat packaging corridors attract pre-qualified international film suppliers.
Spain
Mediterranean canneries for tomato and citrus applications drive polypropylene adoption against pH-driven adhesive degradation. EU EPR frameworks for packaging substrates accelerate recyclable film qualification requirements. Valencia and Murcia processing clusters adopt coated paper stocks for legume segments under retailer plastic-reduction commitments.
Canning Labels Market Competitive Environment
Player mix skews toward diversified materials conglomerates with captive film capacity and specialized decorators with substrate-to-print integration capabilities. Three tiers structure competitive positioning: multinational adhesive and film suppliers, integrated label converters with backward extrusion control, and regional digital print specialists serving short-run craft segments. Dominant competitive moves include capacity consolidation through acquisition and qualification racing for regulatory compliance in REACH and FDA jurisdictions.
Among diversified materials conglomerates, Avery Dennison, CCL Industries, and Constantia Flexibles occupy positions spanning adhesive science, film extrusion, and specialized aluminum-label production. Avery Dennison exemplifies the adhesive-centric archetype with temperature-resistant formulation capabilities. CCL Industries represents integrated converters with backward control over film supply. Constantia Flexibles anchors specialized positioning in acidic food and metallic finish segments. These three collectively illustrate the competitive tension between scale-driven substrate security and premium specialization in sterilization-compliant decoration.
| Leading Market Players |
|---|
| Avery Dennison |
| CCL Industries |
| Constantia Flexibles |
| Berry Global |
| UPM-Kymmene |
| 3M Company |
| Lintec |
| Bemis |
| Henkel |
| Others |
Value Chain & Pricing Dynamics
FDA migration testing protocols gate both supplier qualification timelines and price differentiation tiers simultaneously. REACH Annex XVII restrictions on Substances of Very High Concern compress formulation flexibility while metallic finish premiums expand margin pools for compliant producers.
Pricing Analysis
Cost-plus contracts with polypropylene resin indexation dominate procurement between label converters and consolidated food retail buyers. Three-tier pricing structure across premium, standard, and economy levels separates metallic finishes for craft beverages from matte paper stocks for commodity legumes. Cost compression in economy tiers is intensifying because captive film capacity concentrates among three North American and European players. Mass-market grocery private labels exhibit highest price sensitivity; specialty food producers demonstrate lowest sensitivity due to brand positioning requirements.
Supply Chain Analysis
Rhine-Ruhr petrochemical feedstock corridors constitute a chokepoint for European adhesive precursor supply. Germany, the United States, and China anchor production concentration for retort-resistant formulations. Raw material dependencies draw from polypropylene resin, polyester film substrates, and solvent-based adhesive activators. Single-source vulnerability runs through backward-integrated decorators with captive extrusion lines. Distribution runs through single-source arrangements with substrate-to-print integrators displacing fragmented vendor procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
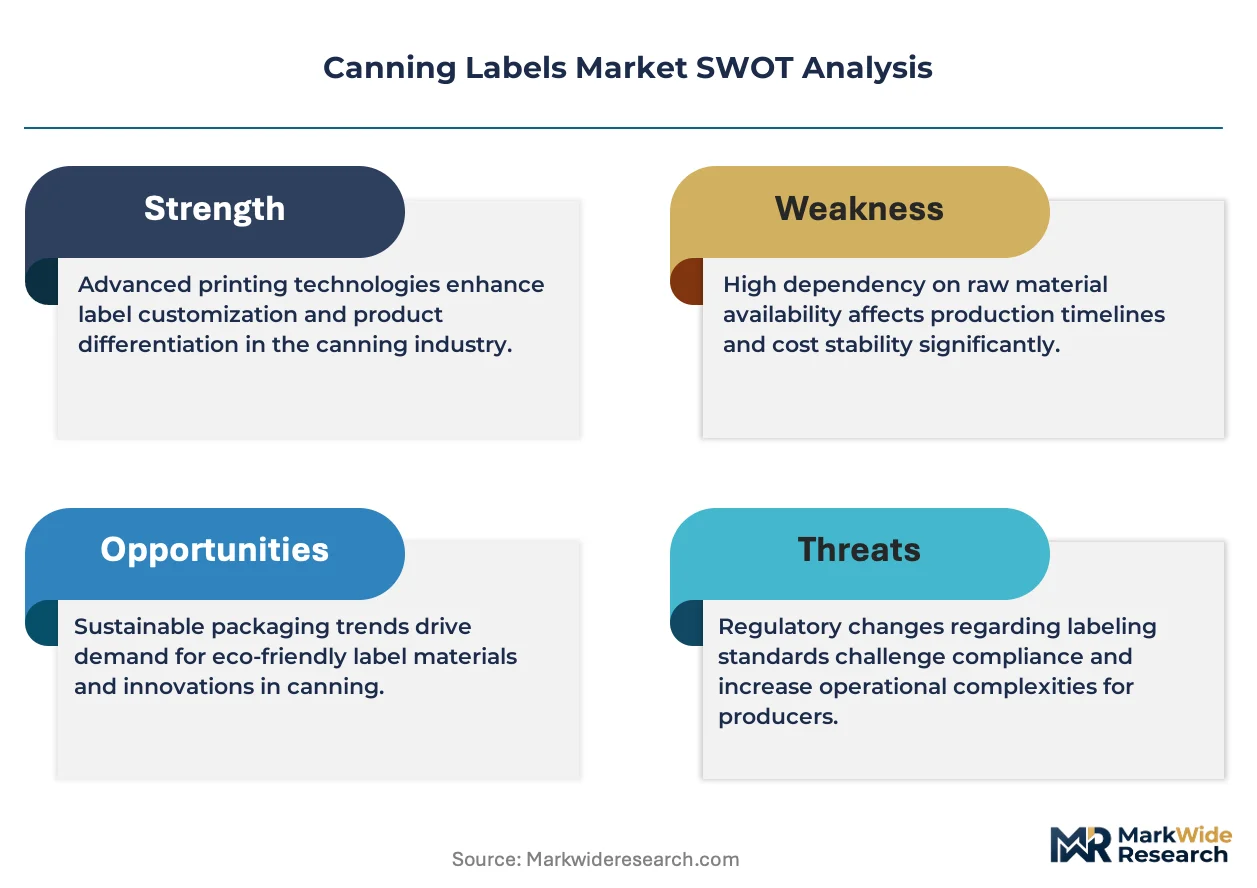
This market functions as a defensive-moat story anchored in regulatory entrenchment. FDA and REACH qualification timelines create switching costs that protect incumbent positions against rapid displacement.
For Market Incumbents: Consolidate supplier relationships through backward integration into film extrusion or adhesive formulation capabilities. Capture preferential status with multinational food brands by pre-qualifying REACH-compliant stocks before Annex XVII substance substitution deadlines. Threat from digital print specialists is accelerating in short-run craft segments; counter through capacity addition in Germany's Rhine-Ruhr cluster for temperature-resistant metallic finishes. For New Entrants and Emerging Players: Short-run digital decoration services for seasonal craft distilleries represent a service-layer gap where incumbents under-serve with analog flexographic legacy lines. Target regional breweries and limited-release SKU producers in Mediterranean canneries for first commercial traction. Go-to-market angle centers on cold foil and inkjet hybrid systems enabling metallization without volume minimums. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across recyclable film development lines as EU EPR frameworks mandate substrate qualification. Long-term viability favors decorators with substrate-to-print integration spanning five-to-ten year compliance windows. Acquisition target archetype: mid-size converters with FDA pre-qualified adhesive portfolios and underutilized digital press capacity. Signal to watch: migration-tested stock pre-qualification velocity in India FSSAI jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive polypropylene supply secures margin control against petrochemical volatility swings. |
| REACH Annex XVII Pre-Qualification | Early substance substitution compliance captures preferential supplier status with Benelux retailers. |
| Digital Print Convergence Investment | Cold foil hybrid systems unlock craft beverage short-run premium decoration economics. |
| India FSSAI Migration Testing | Pre-qualified substrate stocks establish first-mover positioning in domestic canning growth corridors. |
| Recyclable Film Development | EPR framework qualification secures volume pricing with consolidated multinational food brands. |
Study Parameters
Desk research of FDA migration testing protocols, ECHA REACH substance restriction databases, and customs trade data preceded structured interviews with label converter plant managers, procurement leads at consolidated food retail chains, adhesive formulation R&D directors, and digital print system integration specialists. Primary fieldwork across Germany's Rhine-Ruhr cluster, Spain's Valencia processing corridor, and India's Maharashtra packaging belt validated secondary estimates. Bottom-up unit economics triangulated against top-down market sizing from trade association disclosures.
Variance decomposition across substrate type, finish tier, application segment, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume build-ups incorporating sterilization compliance adoption curves and craft beverage premiumization rates. Forecast inputs included polypropylene resin price elasticity coefficients and digital press installation trajectories in European converter bases.
Forecasts assume regulatory continuity in FDA migration testing protocols and REACH Annex XVII restriction schedules; material policy shifts would require re-modeling of supplier qualification timelines and adhesive reformulation costs. Practitioners should keep alternative scenarios live as EU EPR framework implementation timelines and India FSSAI standardization enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Ripeness Indicator Labels Market
Labels
Label Applicator Market
Labels
Barcode Label Market
Labels
In-Mold Labeling (IML) Market
Labels
Hot Melt Glue Labeler Market
Labels
Oxygen Indicator Labels Market
Labels
Domed Labels Market
Labels
Wrap Around Labels Market
Labels
APAC on-Demand Color Labels Market
Labels
Tags Market
Labels
Shrink and Stretch Sleeve Labels Market
Labels
Global Laminated Labels Market
Labels
Cut and Stack Labels Market
Labels
Coated Wet Glue Label Market
Labels
Holographic Scratch-Off Labels Market
Labels
Self-Adhesive Labels Market