
 Ship Searchlight Market | 2026-2036
Ship Searchlight Market Size, Share, and Industry Trends Forecast 2026-2036
Ship Searchlight Market Analysis
IMO's revised maritime safety standards is repositioning demand toward high-intensity LED searchlight systems with enhanced beam precision. Den Haan Rotterdam leverages its Dutch manufacturing heritage to dominate European commercial vessel retrofits. WISKA Hoppmann & Mulsow anchors its position through specialized cable and lighting integration for harsh marine environments. Perko sustains competitive relevance via extensive distribution across North American workboat operators.
Ship searchlights are high-performance marine lighting fixtures engineered to project concentrated beams across distances exceeding one nautical mile, typically housed in corrosion-resistant aluminum or marine-grade stainless steel enclosures with IP67 or higher ingress protection. Their primary purpose is to illuminate navigational hazards, support man-overboard recovery, and enable nighttime identification of vessels or coastal landmarks. LED type segments now lead volume as harbor operators and offshore support fleets prioritize energy efficiency and reduced maintenance intervals against halogen legacy stock. Application demand concentrates in marine navigation where port authorities mandate compliance with COLREGS visibility requirements, while search and rescue represents the fastest-growing segment as coast guard agencies expand rapid-response fleet capabilities.
IMO SOLAS conventions, COLREGS visibility standards, and IEC 60598-2-5 luminaire specifications collectively define product certification pathways and market access thresholds for marine lighting manufacturers. The US Coast Guard enforces additional compliance through its Navigation and Vessel Inspection Circulars, while ECHA REACH restrictions on hazardous substances constrain material choices for European suppliers. Stakeholders must monitor divergence between flag-state certification regimes and emerging cybersecurity requirements for remote-controlled searchlight installations.
Market Dynamics
LED technology migration is compressing replacement cycles across commercial and naval fleets as operators prioritize energy efficiency and reduced maintenance intervals over legacy halogen systems.
Growth Catalysts
- SOLAS Compliance Mandates:IMO's revised maritime safety standards require high-intensity LED searchlight systems with enhanced beam precision, forcing fleet-wide retrofits among commercial vessel operators.
- Coast Guard Fleet Expansion:Offshore patrol and rapid-response vessel procurement in Norway, South Korea, and the United States is accelerating searchlight demand for search and rescue applications.
- LED Technology Maturation:Harbor operators and offshore support fleets now specify solid-state lighting for its extended operational lifespan and reduced power draw against conventional arc sources.
Market Restraints
- Aluminum Input Volatility:Corrosion-resistant marine-grade enclosures face cost pressure from fluctuating aluminum alloy prices and specialized coating material shortages.
- Certification Fragmentation:Divergence between US Coast Guard Navigation and Vessel Inspection Circulars, IEC 60598-2-5 specifications, and flag-state regimes creates redundant testing burdens for manufacturers.
- Optical Component Concentration:Precision lens and reflector supply concentrates among German and Japanese specialty optics houses, exposing lead time risks.
Strategic Opportunities
- Unmanned Surface Vessel Integration:Autonomous patrol craft development in Norway and Singapore creates demand for remote-controlled searchlight installations with cybersecurity-hardened command interfaces.
- Arctic Navigation Requirements:Russian Northern Sea Route traffic growth and Canadian icebreaker fleet renewal specify extreme-temperature LED systems with enhanced thermal management.
- Modular Retrofit Kits:Port authorities in Rotterdam and Singapore are procuring drop-in LED conversion packages to extend legacy fixture service life without full replacement.
Industry Challenges
- Marine Electrical Engineering Talent Scarcity:Specialized expertise in IP67+ sealing design and salt spray corrosion mitigation remains concentrated among aging workforce cohorts in Northern European maritime clusters.
- Legacy System Integration Complexity:Bridge control interface standardization lags behind LED fixture capabilities, forcing custom protocol adaptations for mixed-vessel fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ship Searchlight Market |
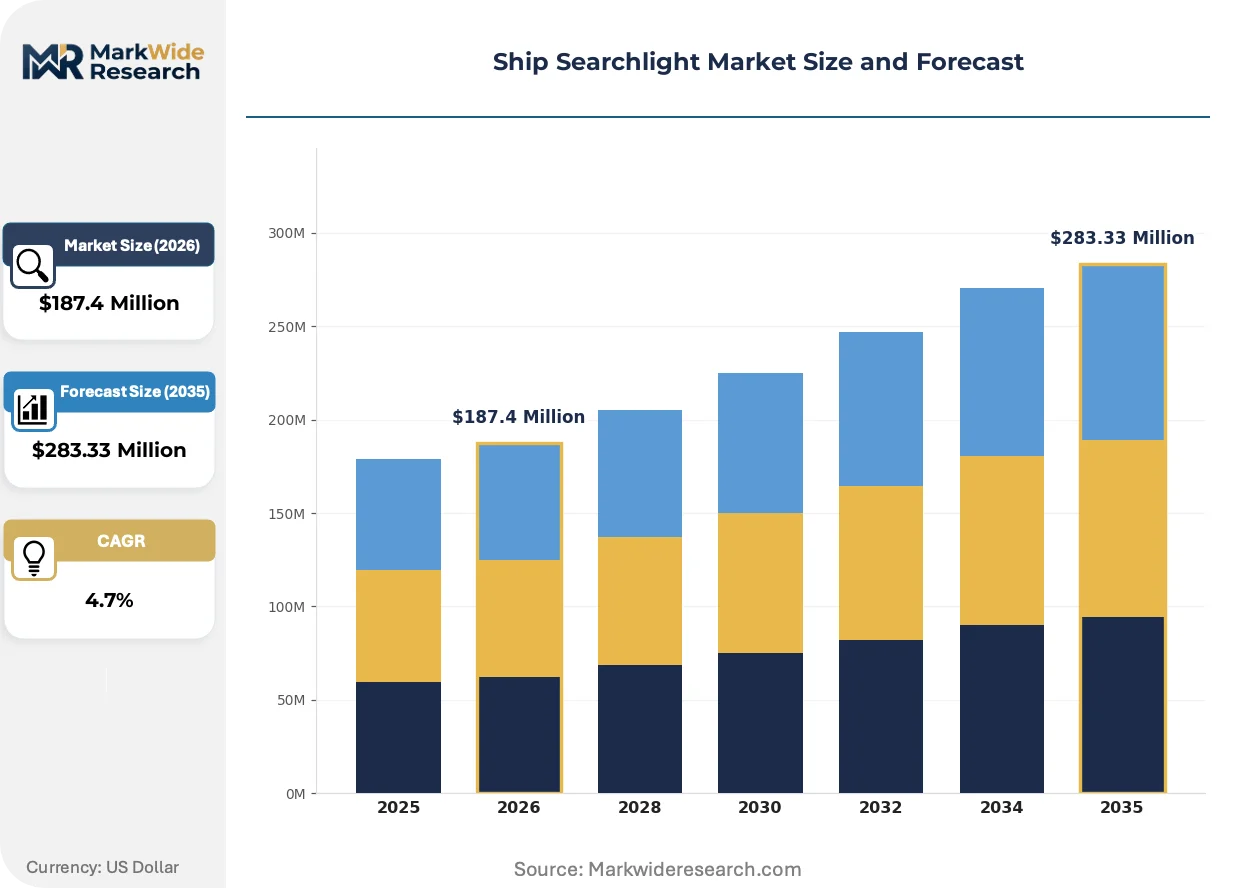
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $283.33 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: LED, Halogen, Xenon, Others Application: Marine Navigation, Search and Rescue, Surveillance, Signal Communication Installation: Deck Mount, Mounting Pole, Remote Control, Portable Power Rating: 100W, 300W, 500W, 1000W |
| Companies Covered | Den Haan Rotterdam, Perko, WISKA Hoppmann & Mulsow, Luminell, Aqua Signal, TRANBERG, Hella Marine, Jay Tech Engineering, The Carlisle & Finch Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ship Searchlight Market Emerging Trajectories
Active beam steering and networked lighting control are displacing fixed-position mechanical searchlight architectures across modern vessel designs.
High-density LED arrays with precision collimation optics are rewriting performance expectations for marine illumination. Offshore supply vessel operators in the North Sea are specifying these systems for man-overboard recovery operations. The technology is compressing acceptable beam divergence standards from 3 degrees to sub-1 degree specifications.
EU ECHA REACH restrictions on hazardous substances are constraining phosphor and thermal interface material choices for European suppliers. Manufacturers must reformulate LED packages to eliminate restricted substance categories while maintaining lumen output. German and Dutch producers are accelerating in-house material qualification programs to maintain CE marking compliance.
Fleet operators are consolidating searchlight procurement under vessel lifecycle management contracts rather than spot replacement purchasing. Major harbor authorities in Long Beach and Hamburg now bundle lighting assets into multi-year facility maintenance agreements. This pattern is most visible among municipal port operators with dedicated capital planning departments.
Ship Searchlight Market Segmentation
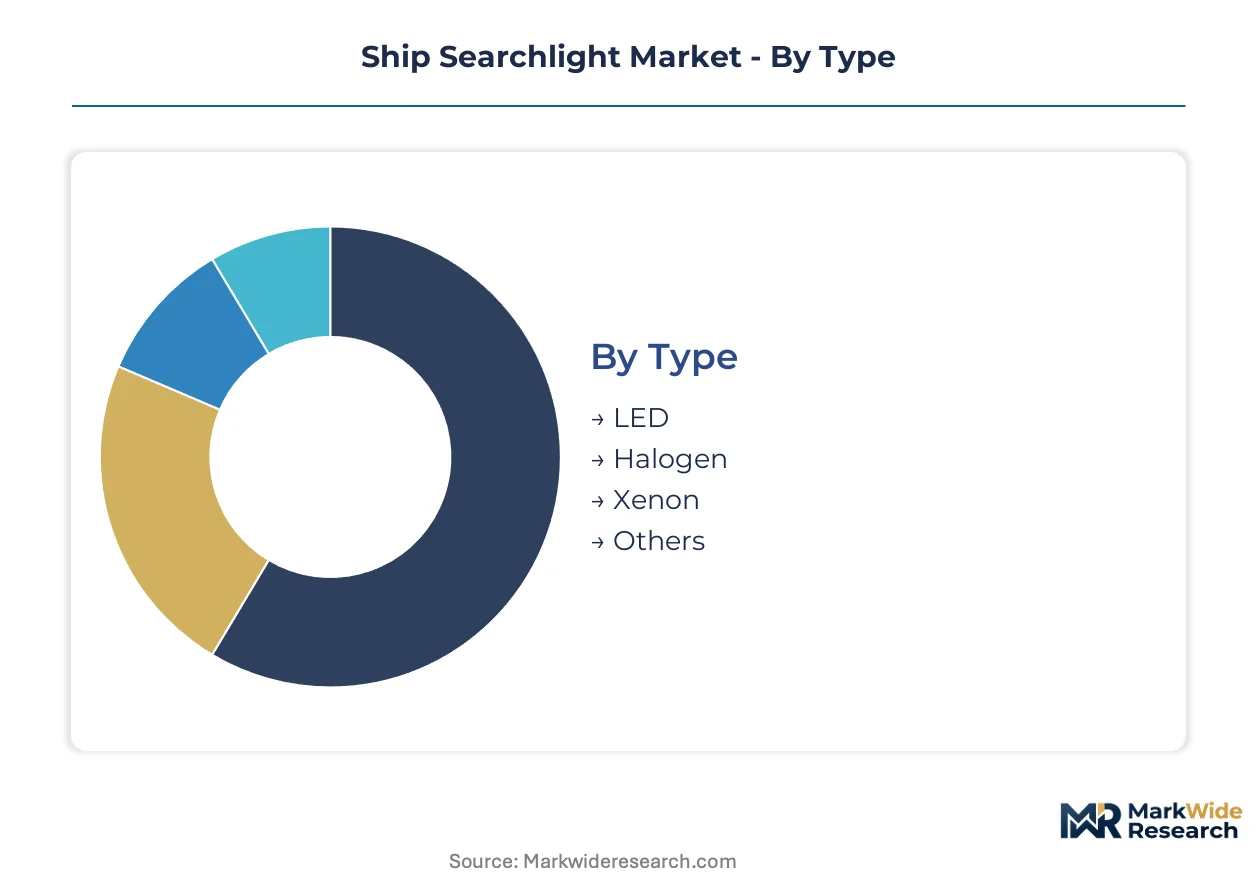
Ship searchlight procurement patterns diverge sharply across vessel types and operational profiles. Technology specifications, mounting configurations, and power requirements each create distinct commercial pathways for manufacturers and fleet operators.
Type:
LED arrays with precision collimation optics now dominate new-build specifications across commercial and naval fleets.
- LED:Solid-state emitters with sub-1 degree beam divergence and 50,000+ hour operational lifespan. Harbor authorities in Rotterdam and Singapore specify these for COLREGS compliance upgrades, driven by energy efficiency mandates and reduced maintenance intervals.
- Halogen:Tungsten-halogen filament sources housed in corrosion-resistant aluminum reflector assemblies. Legacy fleet operators in Greece and Turkey continue procurement for cost-constrained retrofits, though replacement cycles are compressing.
- Xenon:High-intensity discharge arc lamps delivering exceptional candela output for long-range identification. Coast guard agencies in Norway and South Korea specify these for offshore patrol vessels requiring illumination beyond two nautical miles.
- Others:Includes incandescent and metal halide legacy stock, plus experimental laser-illumination prototypes under evaluation by research institutions.
Mature deployment sits with Halogen. Newer deployment is concentrated in LED.
Application:
Operational use cases determine beam precision requirements, control interface complexity, and regulatory certification pathways.
- Marine Navigation:Fixed-position fixtures meeting IMO visibility standards for vessel identification and hazard illumination. Port state control inspections in Long Beach and Hamburg enforce strict compliance, driving replacement demand among aging commercial fleets.
- Search and Rescue:Rapid-response systems with active beam steering and thermal imaging integration. Coast guard fleet expansion in the United States and South Korea is accelerating procurement for man-overboard recovery operations.
- Surveillance:Covert-capable systems with dimming protocols and infrared augmentation. Naval border patrol vessels in Singapore and Norway specify these for littoral security missions.
- Signal Communication:Morse-capable fixtures with precise flash timing for bridge-to-bridge coordination. Remains standard equipment on deep-sea merchant vessels under SOLAS Chapter V requirements.
Volume concentration rests with Marine Navigation. Steepest expansion trajectory belongs to Search and Rescue.
Installation:
Physical mounting topology dictates enclosure sealing requirements, cable routing complexity, and bridge integration protocols.
- Deck Mount:Direct surface attachment to vessel superstructure with IP67+ sealing and shock-resistant gasketing. Offshore supply vessels in the North Sea specify these for heavy-weather reliability.
- Mounting Pole:Elevated pedestal installations maximizing beam clearance above deck obstructions. Tugboat and pilot vessel operators in Rotterdam favor this configuration for harbor maneuvering visibility.
- Remote Control:Networked installations with joystick or software-defined positioning interfaces. Unmanned surface vessel programs in Norway and Singapore are driving demand for cybersecurity-hardened command protocols.
- Portable:Battery-powered or deck-socket units for emergency backup and auxiliary illumination. Fishing fleet operators in Iceland and Alaska maintain these as regulatory-required spares.
Established fleet penetration centers on Deck Mount. Emerging procurement is concentrating in Remote Control.
Power Rating:
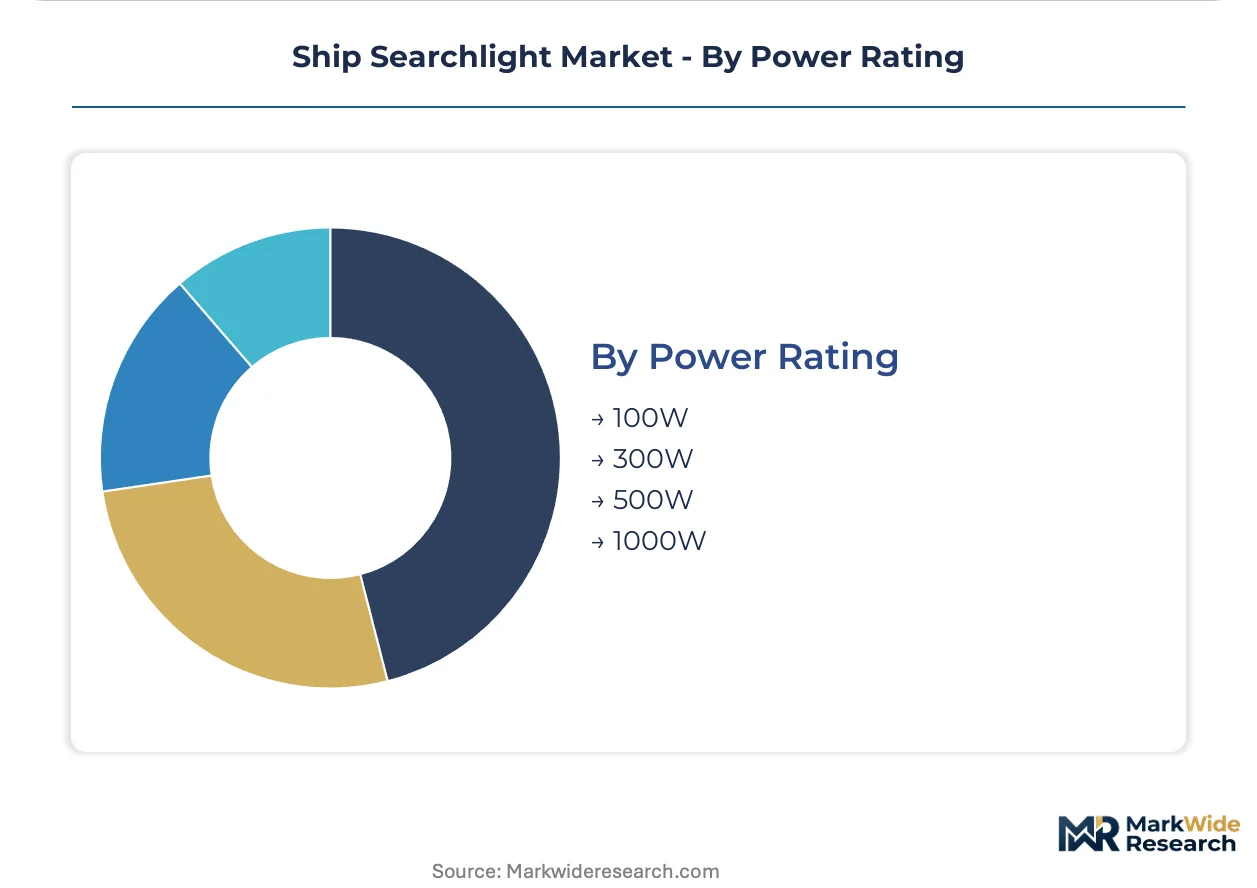
Wattage specifications correlate directly with throw distance, thermal management requirements, and electrical system integration complexity.
- 100W:Compact LED fixtures for small craft and auxiliary lighting. Leisure vessel manufacturers in Italy and Florida specify these for yacht tender illumination.
- 300W:Mid-range systems balancing output with power draw for coastal patrol and workboat applications. Dominates retrofit programs among municipal harbor authorities.
- 500W:High-output configurations for offshore support and medium-range search operations. Icebreaker fleet renewal in Canada specifies these with enhanced thermal management for Arctic conditions.
- 1000W:Maximum-intensity installations for long-range identification and military signaling. Naval destroyer programs in South Korea and the United States require these with active stabilization mounts.
Procurement volume clusters at 300W. Specification escalation is most visible at 1000W.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam anchors European commercial vessel retrofit activity, while South Korean shipyards and Norwegian offshore patrol programs concentrate naval procurement. Demand clusters in port modernization corridors where COLREGS enforcement drives replacement cycles.
United States
Coast Guard fleet expansion and commercial harbor renewal in Long Beach accelerate LED searchlight procurement. US Coast Guard Navigation and Vessel Inspection Circulars mandate enhanced beam precision standards. Pacific Northwest workboat operators consolidate retrofit purchasing under lifecycle management contracts.
Norway
Arctic icebreaker fleet renewal and unmanned surface vessel programs drive extreme-temperature LED specifications. Norwegian Maritime Authority enforces SOLAS Chapter V visibility compliance for offshore supply fleets. Stavanger and Bergen harbor clusters specialize in man-overboard recovery system integration.
South Korea
Naval destroyer programs and coast guard rapid-response vessel construction concentrate demand at 1000W power ratings. Korean Register certification requirements align with IEC 60598-2-5 luminaire specifications. Busan-Ulsan shipbuilding corridor dominates new-build searchlight integration for export vessels.
Germany
Precision optics supply concentration and ECHA REACH material compliance constrain European supplier choices. Germanischer Lloyd certification pathways mandate hazardous substance elimination in LED thermal interfaces. Hamburg port authority bundles lighting assets into multi-year facility maintenance agreements.
Singapore
Littoral security missions and unmanned patrol craft development drive remote-controlled searchlight demand. Maritime and Port Authority of Singapore enforces cybersecurity-hardened command protocols for networked installations. Jurong shipyard cluster specializes in modular LED retrofit kit deployment.
Ship Searchlight Market Vendor Landscape
The competitive structure tilts toward specialized marine lighting manufacturers with heritage corrosion engineering capabilities. Tier concentration separates Dutch and German precision optics houses from North American distribution-focused operators. Three archetypes dominate: heritage European fabricators with in-house sealing expertise, Nordic specialists in extreme-environment thermal management, and integrated marine electrical suppliers leveraging cable and control synergies. Capacity expansion and strategic technology licensing represent the dominant competitive moves as players address LED thermal interface material constraints.
Among heritage European fabricators, Den Haan Rotterdam occupies a position exemplifying Dutch manufacturing heritage in commercial vessel retrofits. WISKA Hoppmann & Mulsow represents the integrated marine electrical archetype through specialized cable and lighting integration capabilities. Perko anchors the North American distribution-focused tier with extensive workboat operator reach.
| Leading Market Players |
|---|
| Den Haan Rotterdam |
| Perko |
| WISKA Hoppmann & Mulsow |
| Luminell |
| Aqua Signal |
| TRANBERG |
| Hella Marine |
| Jay Tech Engineering |
| The Carlisle & Finch Company |
| Others |
Supply Flow & Price Mechanics
London Metal Exchange aluminum alloy price indices cascade through marine lighting supply chains into three distinct procurement tiers. Harbor authorities in Rotterdam and Singapore absorb premium pricing for SOLAS-certified LED systems with sub-1 degree beam precision, while Greek and Turkish retrofit operators trade off certification grade against unit economics.
Pricing Analysis
Outcome-based pricing tied to operational uptime and maintenance interval guarantees anchors premium tier structures. Three-tier pricing separates IMO-certified navigation systems from commercial workhorse fixtures and economy harbor auxiliary units. Cost compression in the economy tier intensifies as aluminum input volatility and German optics house lead time premiums squeeze margin structures. Municipal port operators with lifecycle management contracts exhibit lowest price sensitivity; independent fishing fleet buyers in Iceland and Alaska demonstrate highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with precision lens and reflector supply concentrated among German and Japanese specialty optics houses. Aluminum alloy extrusion and marine-grade coating production centers on Germany, South Korea, and the Netherlands. LED thermal interface materials and phosphor formulations draw from constrained European supplier pools subject to ECHA REACH substance restrictions. Tariff exposure on Chinese-sourced electronic driver components threatens cost stability across mid-tier fixture assembly. Distribution runs through integrated marine electrical suppliers and specialized ship chandler networks serving drydock retrofit corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized marine-grade sealing expertise scarcity props pricing power among heritage European fabricators. Capacity bottlenecks in IP67+ thermal management engineering constrain rapid supply expansion.
For Market Incumbents: Deploy certification-first positioning to lock in SOLAS Chapter V retrofit mandates before emerging Asian LED assemblers achieve IEC 60598-2-5 compliance. Deepen in-house production of corrosion-resistant aluminum enclosures to offset alloy price volatility. Capture Norwegian and Canadian icebreaker fleet renewal through extreme-temperature thermal management R&D investment. For New Entrants and Emerging Players: Direct-to-shipyard digital procurement platforms offer lowest-friction entry into modular LED retrofit kit segments. Target Singapore and Rotterdam harbor authorities with cybersecurity-hardened remote control integration for unmanned surface vessel programs. White-space concentration sits with drop-in conversion packages extending legacy halogen fixture service life without full bridge control replacement. For Investors and Strategic Acquirers: Distressed-cycle entries favor Nordic extreme-environment specialists with captive thermal engineering talent in Stavanger and Bergen clusters. Five-to-ten year viability hinges on unmanned vessel integration contract flow rather than spot replacement demand. Monitor Norwegian Maritime Authority unmanned patrol craft procurement timelines as inflection signal for remote-controlled searchlight installation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Optics | German and Japanese lens house acquisition reduces lead time exposure for collimation components. |
| Arctic Thermal Management Certification | Canadian icebreaker and Russian Northern Sea Route specifications open extreme-temperature premium tier. |
| Cybersecurity-Hardened Remote Control Development | Singapore Maritime and Port Authority protocols create compliance barrier for unhardened competitors. |
| Modular Retrofit Kit Platform Launch | Rotterdam and Hamburg port authority maintenance contracts favor drop-in LED conversion economics. |
| Lifecycle Management Contract Consolidation | Pacific Northwest workboat operator bundling patterns shift procurement from spot replacement to multi-year agreements. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this ship searchlight market assessment. Primary interviews with marine electrical procurement managers, shipyard integration engineers, coast guard fleet planners, and harbor authority maintenance directors combined with IMO SOLAS convention documentation, IEC luminaire specifications, and flag-state certification registries. Bottom-up vessel fleet analysis and top-down maritime safety equipment spending triangulation validated segment-level estimates.
Granularity-level modeling distinguished LED, halogen, and xenon technology types across marine navigation, search and rescue, surveillance, and signal communication applications. Installation topology, power rating tiers, and geographic procurement clusters were projected across the analysis window. CAGRs derived from fleet renewal cycle timing, regulatory compliance deadline clustering, and unmanned vessel program acceleration curves. Aluminum alloy price trajectory assumptions and optics house capacity utilization informed cost structure projections.
The model holds under steady regulatory enforcement intensity and aluminum supply normalization; deviation in IMO SOLAS revision timing or German-Japanese optics export restrictions would shift replacement cycle assumptions. Forecasts reflect documented assumptions on fleet age profiles and port state control inspection stringency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Offshore Autonomous Underwater Vehicle (AUV) Market
Marine
China Controllable Pitch Marine Propeller Market
Marine
Yacht Shell Doors Market
Marine
Autonomous Underwater Vehicle (AUV) Market
Marine
Marine Stabilizers Market
Marine
Global Foldable Inflatable Boats Market
Marine
Buoys and Beacon Market
Marine
Autonomous Ships Market
Marine
Marine Chronometers Market
Marine
Electric Boat Market
Marine
Marine Bearings Market
Marine
North Sea Offshore Support Vessels Market
Marine
Marine and Marine Management Software Market
Marine
Marine Lighting Market
Marine
Global Maritime Information Market
Marine
Marine Base Steering Gear Market