
 Ice Cream Market | 2026-2036
Ice Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Cream Market Intelligence
India's dairy processing corridor is reshaping competitive dynamics in frozen desserts. Unilever leverages its Hindustan Unilever infrastructure to dominate South Asian distribution networks. Nestlé sustains R&D intensity in reduced-sugar formulations across European and Latin American markets. Froneri International Limited anchors premium positioning through specialized gelato and super-premium licensing agreements.
Ice cream is a frozen dairy or plant-based emulsion typically containing minimum ten percent milkfat, aerated through continuous freezing to overrun levels between twenty and one hundred percent, and stabilized for texture and shelf-life; it serves as a mass-market refreshment product and premium indulgence vehicle across retail and foodservice channels. Dairy-free alternatives represent the fastest-growing structural pocket as oat and coconut bases displace traditional formulations among lactose-intolerant and flexitarian consumers. Artisanal segments command disproportionate margin pools through small-batch production and localized flavor innovation, while regular ice cream remains the volume anchor in emerging market supermarkets.
FDA standards of identity, EFSA additive authorizations, and FSSAI dairy certification requirements collectively govern ingredient disclosure, pathogen thresholds, and nutritional labeling across major producing jurisdictions. These frameworks elevate compliance costs for exporters while creating preferential access for domestic manufacturers with established laboratory and cold-chain credentials. Stakeholders must monitor evolving plant-based labeling disputes and carbon-footprint disclosure obligations as procurement criteria for retail buyers tighten.
Market Dynamics
Clean-label mandates from EFSA and evolving FDA dairy standards are compressing formulation flexibility while simultaneously opening premium positioning for compliant manufacturers. This regulatory tightening acts as the central structural force reshaping competitive dynamics across frozen dessert value chains.
Growth Catalysts
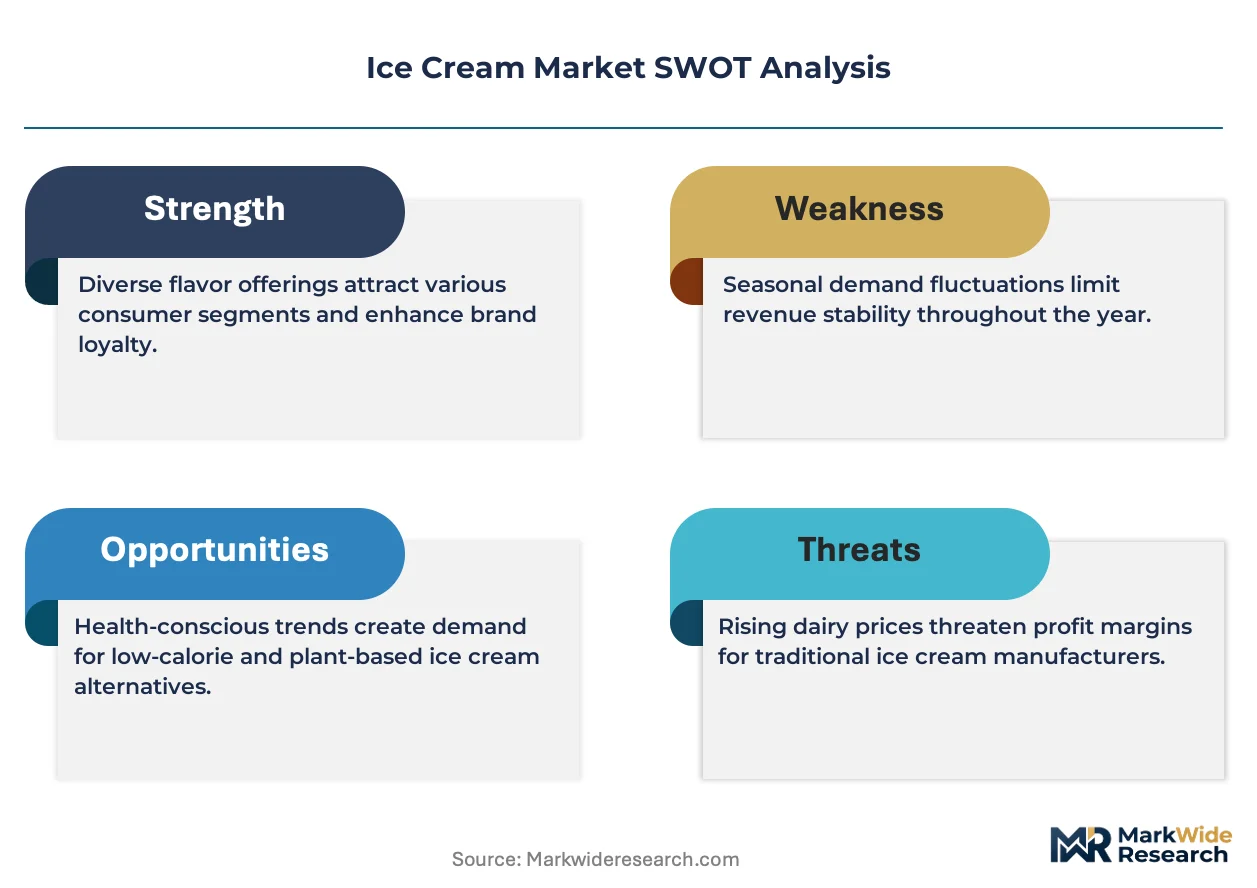
- FSSAI dairy certification expansion:India's tightening food safety protocols are legitimizing organized retail channels for frozen desserts, accelerating formal sector penetration in South Asian markets.
- Oat base technology maturation:Advanced enzymatic processing is eliminating texture defects in plant-based formulations, unlocking lactose-intolerant consumer segments previously unreachable.
- Southeast Asian middle-class expansion:Urban household formation in Vietnam, Indonesia, and the Philippines is creating concentrated demand pockets for packaged frozen indulgence products.
Market Restraints
- Butterfat supply volatility:Dairy commodity price swings tied to New Zealand and EU production cycles destabilize input cost forecasting for premium formulations.
- Cold-chain infrastructure gaps:Last-mile refrigeration deficiencies in tier-two Indian cities and Indonesian archipelago markets cap distribution reach for temperature-sensitive stock-keeping units.
- EFSA additive authorization delays:Novel stabilizer and emulsifier approvals now require eighteen-to-twenty-four-month safety dossier reviews, slowing reformulation pipelines.
Strategic Opportunities
- Thailand's underpenetrated foodservice channel:Independent gelateria and café formats in Bangkok and Chiang Mai corridors present white-space expansion for artisanal positioning.
- EU Green Deal carbon-footprint disclosure:Early compliance with emerging procurement criteria creates preferential access to sustainability-focused retail buyers in German and Dutch markets.
- Direct-to-consumer subscription models:Monthly delivery platforms bypass traditional retail slotting constraints while capturing recurring revenue from indulgence-seeking urban households.
Industry Challenges
- Food technologist talent scarcity:Formulation expertise spanning dairy chemistry and plant-protein functionality remains concentrated among a narrow cohort of European and North American specialists.
- Legacy equipment retrofit costs:Continuous freezers designed for dairy emulsions require substantial modification to handle high-viscosity oat and coconut bases without overrun degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Cream Market |
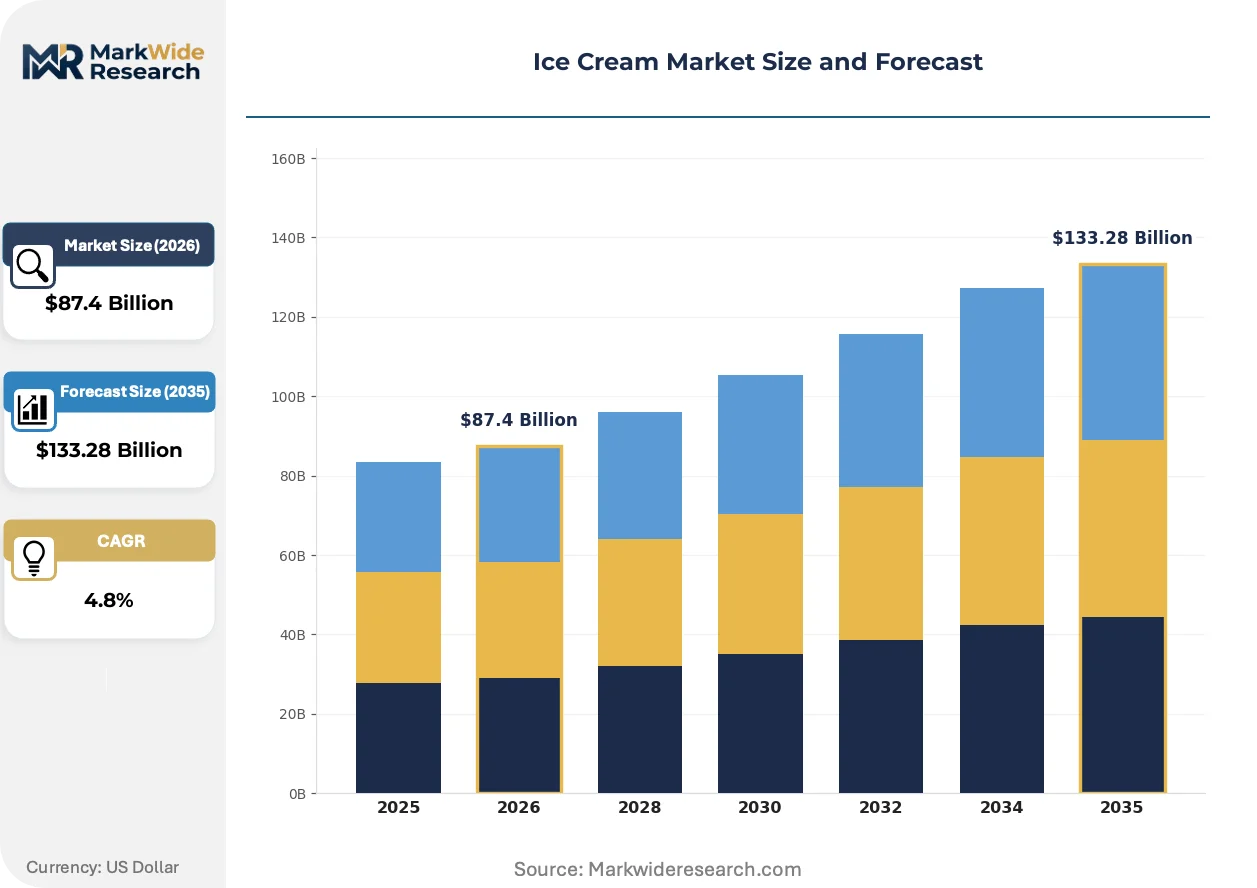
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $133.28 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Low-Fat, Dairy-Free, Artisanal Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Ice Cream Parlors Flavor Profile: Vanilla, Chocolate, Strawberry, Mint Chocolate Chip Consumer Age Group: Children, Teens, Adults, Seniors |
| Companies Covered | Unilever, Nestlé, Froneri International Limited, Wells Enterprises, Mars, Ferrero Group, Inspire Brands, The Magnum Ice Cream Company, General Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Cream Market Strategic Shifts & Innovations
Formulation science and distribution architecture are undergoing simultaneous transformation as regulatory scrutiny intensifies and consumer preference fragments across dietary requirements. These intersecting pressures are compressing traditional product development cycles.
Precision fermentation-derived dairy proteins are collapsing the functional gap between animal and plant-based frozen desserts. Premium manufacturers in the Netherlands and California are integrating these ingredients to replicate mouthfeel without lactose content. The technology is collapsing premium pricing power for conventional super-premium lines as parity perception spreads.
EFSA's 2023 updated guidance on novel food classifications is forcing reformulation roadmaps across European Union member states. Manufacturers must now submit comprehensive toxicological data for enzymatically modified starches and alternative protein hydrolysates. Reduced-sugar specialists face the steepest compliance burden as their core ingredient toolkits fall under intensified scrutiny.
Urban Indian consumers are bypassing traditional kirana stores for organized retail and quick-commerce platforms when purchasing impulse frozen desserts. Swiggy Instamart and Blinkit fulfillment networks now capture significant share in Mumbai, Delhi, and Bangalore metropolitan zones. This channel rotation is most pronounced among dual-income households under age forty seeking immediate gratification without pantry stocking.
Ice Cream Market Segmentation
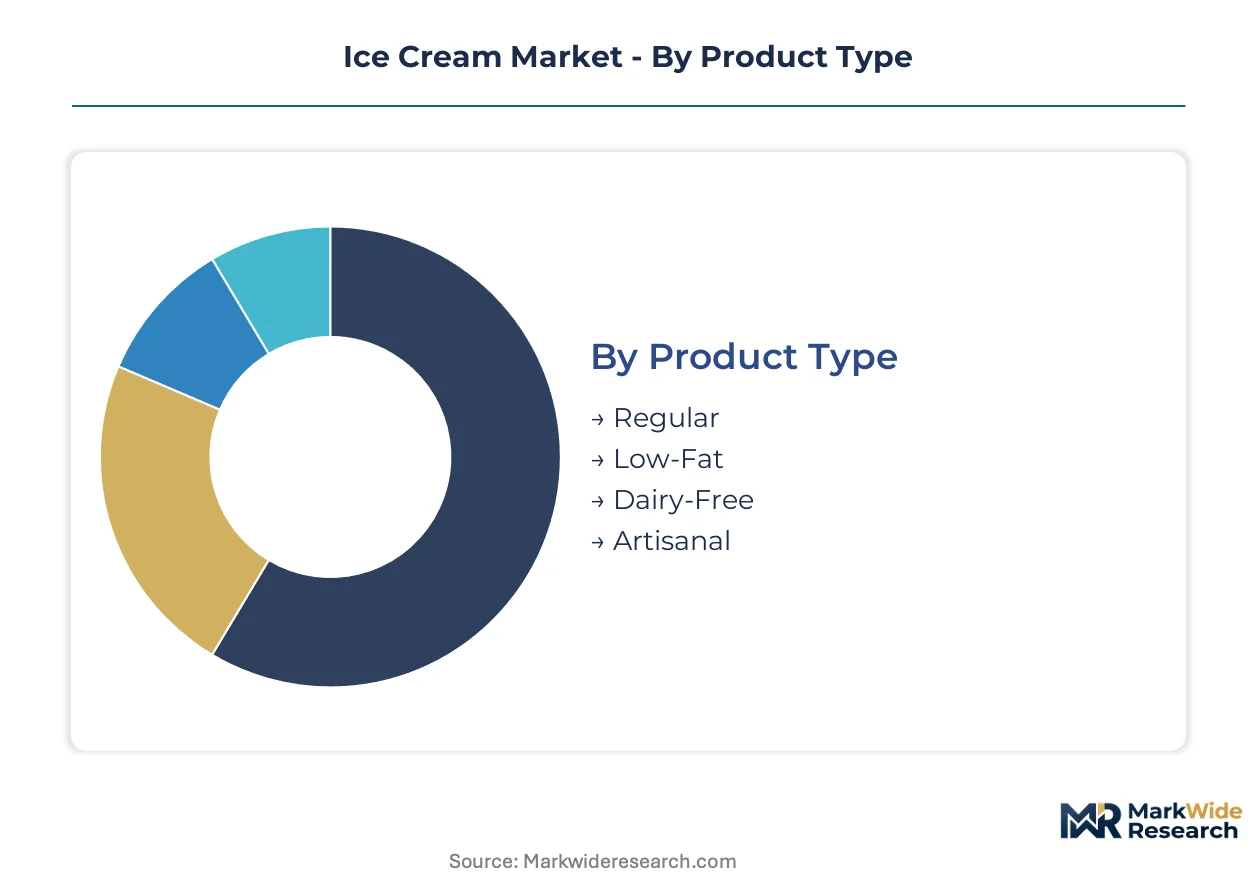
Segmentation in frozen desserts reveals divergent velocity profiles across product lifecycles. Artisanal and dairy-free variants turn inventory faster than legacy formats, while channel fragmentation demands distinct cold-chain investments.
Product Type:
Cycle times vary dramatically: regular ice cream rotates weekly in mass retail, while artisanal batches move through specialty channels with extended lead times and premium shelf positioning.
- Regular:Standard formulations containing minimum ten percent milkfat serve as the volume foundation across supermarket and convenience networks. Demand concentrates in Southeast Asian urban centers where middle-class household expansion drives repeat purchase frequency in organized retail.
- Dairy-Free:Oat and coconut base formulations are expanding most quickly as enzymatic processing eliminates prior texture defects. Lactose-intolerant and flexitarian consumers in German and Dutch markets sustain premium pricing for compliant clean-label variants.
- Low-Fat:Reduced-calorie positioning targets health-conscious adult demographics through reformulated emulsion stability.
- Artisanal:Small-batch production with localized flavor innovation captures disproportionate margin pools in Bangkok and Chiang Mai corridors.
Regular dominates installed base. Dairy-Free is where expansion concentrates.
Distribution Channel:
Cost tier stratification separates capital-intensive cold-chain infrastructure from asset-light digital fulfillment models.
- Supermarkets:Temperature-controlled display cases and centralized procurement dominate volume throughput in organized retail corridors. Indian metropolitan zones including Mumbai and Delhi concentrate demand as FSSAI certification legitimizes formal sector penetration.
- Online Retail:Quick-commerce platforms including Swiggy Instamart and Blinkit capture impulse purchases from dual-income households under age forty. Last-mile refrigeration investments in tier-two Indian cities remain the binding constraint on geographic expansion.
- Convenience Stores:Grab-and-go positioning targets immediate consumption occasions in high-foot-traffic urban locations.
- Ice Cream Parlors:Experience-driven formats in Thai foodservice channels enable artisanal premium positioning through gelateria and café concepts.
Supermarkets anchor volume throughput. Online Retail is where customer acquisition costs compress fastest.
Flavor Profile:
Application context drives formulation stability requirements: vanilla and chocolate demand industrial-scale consistency, while mint chocolate chip tolerates batch variation.
- Vanilla:The reference standard for dairy emulsion quality assessment serves as the benchmark for overrun and mouthfeel optimization across production facilities.
- Chocolate:Cocoa butter integration requires precise fat-phase crystallization control to prevent bloom defects in extended distribution.
- Strawberry:Fruit particulate suspension demands modified starch stabilization under EFSA's intensified novel food scrutiny.
- Mint Chocolate Chip:Inclusions and flavor oil encapsulation create manufacturing complexity that artisanal producers exploit for differentiation.
Vanilla and Chocolate dominate production volume. Mint Chocolate Chip is where flavor innovation investment concentrates.
Consumer Age Group:
Margin structure inverts across demographic tiers: children and teens drive volume through price-sensitive formats, while adults and seniors sustain premium pricing for functional and indulgent positioning.
- Adults:Dual-income professionals under forty prioritize immediate gratification through quick-commerce channels without pantry stocking behavior. Clean-label compliance and reduced-sugar formulations align with EFSA disclosure mandates in European procurement.
- Children:Impulse-driven purchase occasions in convenience and supermarket channels sustain high-frequency, low-margin turnover.
- Teens:Social consumption patterns favor experiential formats including ice cream parlor visits and shareable novelty products.
- Seniors:Digestibility concerns and portion control preferences drive demand for reduced-fat and functional ingredient integration.
Children anchor mass-market volume. Adults are where premium pricing power concentrates.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA dairy standards anchor North American formulation requirements while EFSA clean-label mandates reshape European competitive dynamics. India's FSSAI certification expansion accelerates formal sector penetration across South Asian frozen dessert corridors.
United States
Supermarket channel consolidation and quick-commerce platform expansion drive demand concentration in metropolitan zones. FDA standards of identity for frozen desserts enforce minimum milkfat disclosure and overrun specifications. California and Texas dairy processing clusters sustain premium artisanal production capacity through specialized cold-chain infrastructure.
Germany
Reduced-sugar formulation demand and oat-base technology maturation attract flexitarian consumer segments. EFSA additive authorization requirements and EU Green Deal carbon-footprint disclosure obligations tighten procurement criteria. Bavaria's precision fermentation startups and North Rhine-Westphalia's industrial dairy base anchor clean-label innovation pipelines.
India
Urban household formation and organized retail penetration in Mumbai, Delhi, and Bangalore metropolitan zones concentrate volume growth. FSSAI dairy certification protocols legitimize formal sector participation while squeezing unorganized channel share. Gujarat's dairy processing corridor and Maharashtra's quick-commerce fulfillment networks reshape distribution architecture for temperature-sensitive stock-keeping units.
Thailand
Foodservice channel underpenetration in Bangkok and Chiang Mai corridors creates white-space expansion for artisanal gelateria formats. National food safety modernization aligns with ASEAN harmonization protocols for dairy product standards. Central Thailand's urban consumption clusters and Southern tourist corridor destinations sustain premium positioning for experiential frozen dessert formats.
Brazil
Middle-class household expansion and convenience store channel growth drive impulse purchase frequency in São Paulo and Rio de Janeiro metropolitan zones. ANVISA dairy product regulations govern pathogen thresholds and nutritional labeling requirements. Minas Gerais dairy belt processing capacity and Southeast region cold-chain investments support formal sector distribution reach into tier-two urban centers.
Ice Cream Market Key Industry Players
Multinational conglomerates and specialized frozen dessert pure-plays split the market across volume and premium positioning vectors. Consolidation pressure intensifies as scale-dependent cold-chain investments and formulation R&D costs rise. Three archetypes dominate: diversified CPG giants with dairy heritage, dedicated frozen dessert specialists with super-premium licensing depth, and private-equity-backed roll-up platforms. Competitive moves concentrate on portfolio diversification into plant-based alternatives and geographic expansion through quick-commerce channel partnerships.
Within the diversified CPG tier, Unilever and Nestlé occupy positions spanning mass-market volume and premium indulgence segments. Froneri International Limited exemplifies the specialized frozen dessert archetype through concentrated expertise in gelato and super-premium licensing formats. These three entities anchor competitive dynamics across formulation innovation, distribution network density, and regulatory compliance infrastructure.
| Leading Market Players |
|---|
| Unilever |
| Nestlé |
| Froneri International Limited |
| Wells Enterprises |
| Mars |
| Ferrero Group |
| Inspire Brands |
| The Magnum Ice Cream Company |
| General Mills |
| Others |
Cost & Logistics Intelligence
Gujarat's dairy processing corridor concentrates butterfat refining capacity that directly shapes margin structures for premium formulations downstream. Cold-chain infrastructure density in this cluster creates pricing power asymmetries against regions dependent on fragmented procurement networks.
Pricing Analysis
Price spreads between Mumbai metropolitan quick-commerce channels and tier-two Indian kirana stores reflect delivery-cost differentials and FSSAI certification premiums. Three-tier pricing structure across premium artisanal, standard packaged, and economy bulk formats stratifies by overrun quality and clean-label compliance. Pricing pressure stems from oat-base technology maturation collapsing functional premiums for dairy alternatives. Dual-income households under forty exhibit lowest price sensitivity for immediate-gratification channels, while children-driven convenience purchases anchor volume at compressed margins.
Supply Chain Analysis
EFSA additive authorization regimes constrain stabilizer and emulsifier sourcing flexibility for European-bound production. Supply concentrates in New Zealand for premium butterfat, the Netherlands for precision fermentation inputs, and India for milk solids and quick-commerce fulfillment infrastructure. Raw material dependencies center on dairy commodity cycles, enzymatically modified starches, and specialized cold-chain equipment. Single-source vulnerability runs through New Zealand's pastoral production volatility. Distribution runs through temperature-controlled supermarket networks and quick-commerce dark stores in metropolitan India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as Southeast Asian middle-class household formation accelerates formal-sector frozen dessert penetration beyond traditional unorganized channels.
For Market Incumbents: Insulate premium positioning through captive sourcing from Gujarat's dairy corridor and accelerated FSSAI certification coverage. Defend against precision fermentation disruptors by locking exclusive licensing for enzymatically optimized oat bases. Deepen backward integration into cold-chain infrastructure to constrain new entrant distribution reach.
For New Entrants and Emerging Players: Bangkok's underpenetrated foodservice corridor offers white-space expansion through independent gelateria formats without legacy supermarket slotting constraints. Target artisanal positioning in Chiang Mai's tourist economy with localized flavor innovation. Deploy direct-to-consumer subscription models to bypass incumbent retail gatekeeping.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because cold-chain capital intensity and formulation R&D costs are compressing viable independent operator counts. Acquire specialized frozen dessert pure-plays with super-premium licensing depth and established EFSA compliance infrastructure. Monitor oat-base technology patent filings as inflection signal for dairy-alternative parity timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Bypasses retail slotting constraints while capturing recurring revenue from urban dual-income households. |
| Precision Fermentation Partnership | Secures functional dairy protein alternatives ahead of EFSA novel food classification enforcement. |
| Thailand Foodservice Channel Expansion | Captures artisanal premium positioning in Bangkok and Chiang Mai gelateria white space. |
| FSSAI Certification Acceleration | Legitimizes formal sector participation against unorganized competitors in Indian metropolitan zones. |
| Cold-Chain Infrastructure Buildout | Enables tier-two Indian city distribution reach beyond current quick-commerce constraints. |
Research Approach
Operator-level perspectives from dairy processing plant managers, quick-commerce category buyers, FSSAI compliance officers, and artisanal gelateria operators anchored the qualitative base. Secondary validation drew from FSSAI dairy certification records, EFSA additive authorization filings, Nielsen retail audit data, and customs trade statistics for butterfat and oat protein concentrates. Bottom-up demand modeling triangulated against top-down macroeconomic consumption elasticity frameworks.
Scenario-bracketing framed projections across the analysis window, with CAGRs derived from segmented demand elasticity and input cost trajectory assumptions. Segmentation dimensions spanned product type, distribution channel, flavor profile, and consumer age group, with regional regulatory cluster overlays. Forecast inputs incorporated cold-chain infrastructure investment pipelines, precision fermentation technology maturation curves, and FSSAI enforcement intensity gradients.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private-equity-backed roll-up platforms or precision fermentation specialists would shift outcomes. Material shifts in EFSA clean-label enforcement timelines or New Zealand dairy commodity volatility would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Packaged Bread Market
Bakery Products
Bread Slicer Blades Market
Bakery Products
US Frozen Bakery Market
Bakery Products
Europe Sourdough Market
Bakery Products
North America Par Baked Bread Market
Bakery Products
Low-Gluten Emmer and Einkorn Flour Blends Market
Bakery Products
Bakery Improvers Market
Bakery Products
Canada Frozen Bakery Market
Bakery Products
Bake Stable Pastry Fillings Market
Bakery Products
Frozen Bakery Additives Market
Bakery Products
Fondant Market
Bakery Products
Baking Molds and Trays Market
Bakery Products
Bakery Fats Market
Bakery Products
Europe Zwieback Market
Bakery Products
Aerating Cake Emulsifier Market
Bakery Products
Pie Shells Market