
 Muffins Market | 2026-2036
Muffins Market Size, Share, and Industry Trends Forecast 2026-2036
Muffins Market Analysis
The EU Green Deal's farm-to-fork sustainability targets is restructuring ingredient sourcing across European muffin manufacturing, compelling reformulation of conventional wheat-based recipes. Grupo Bimbo leverages its vertically integrated grain-milling network to secure cost-advantaged organic flour supplies across multiple continents. Flowers Foods sustains dominant in-store bakery penetration through direct-store-delivery infrastructure that controls retail shelf positioning. McKee Foods Corporation anchors its competitive stance through deep specialization in long-shelf-life wrapped snack cakes distributed via mass-market grocery channels.
A muffin is a chemically leavened quick bread baked in individual cup-shaped molds, typically containing wheat flour, sugar, fat, eggs, and milk with a moisture content of 35-45 percent that yields a tender crumb structure distinct from yeast-raised bakery products. Its primary commercial purpose centers on providing portion-controlled, ready-to-eat breakfast and snacking options for foodservice and retail channels. Blueberry and Chocolate Chip varieties occupy the core volume positions in mature North American markets where brand loyalty stabilizes repeat purchase rates. Gluten-Free and Organic ingredient segments are expanding fastest as celiac awareness and EU organic certification requirements reshape supermarket assortment planning. Online Retail distribution is capturing incremental growth through subscription-based breakfast box services that bypass traditional wholesale bakery intermediaries.
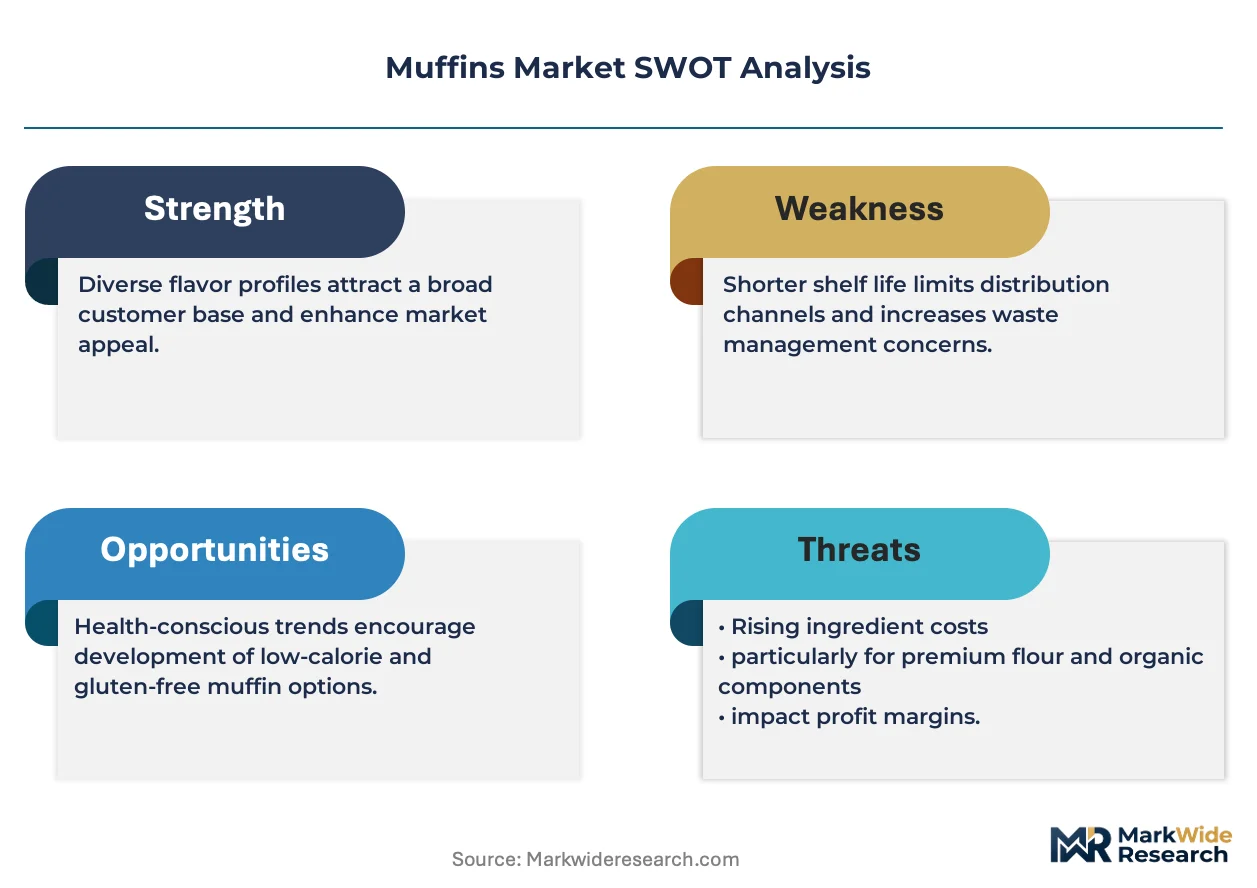
The FDA's updated Nutrition Facts labeling mandates and the EU's Nutri-Score front-of-pack scoring system are tightening compositional standards for sugar and saturated fat declarations across packaged muffin portfolios. Health Canada and the FSSAI in India are aligning sodium reduction guidelines with WHO recommendations, forcing multinational bakers to harmonize regional recipes against divergent regulatory baselines. Stakeholders must monitor evolving front-of-pack warning label regimes in Latin American markets and calibrate reformulation timelines against enforcement phase-ins.
Market Dynamics
Clean-label reformulation mandates from health regulators across multiple jurisdictions are forcing muffin manufacturers to restructure ingredient sourcing and accelerate functional substitution R&D, compressing legacy formulation cycles.
Growth Catalysts
- EU Green Deal farm-to-fork targets:Sustainability sourcing requirements are redirecting wheat procurement toward regenerative agriculture certification programs across European manufacturing networks.
- Grab-and-go foodservice channels:Urban convenience-seeking consumers are expanding purchases of individually wrapped portion formats for breakfast and snacking occasions.
- FSSAI sodium reduction alignment:Indian regulatory harmonization with WHO guidelines is opening reformulated product development for export-oriented bakeries targeting health-conscious segments.
Market Restraints
- Organic flour supply concentration:Certified organic wheat milling capacity clusters in North American and Western European grain belts, creating input bottlenecks for mid-tier manufacturers.
- Front-of-pack warning label friction:Latin American regulatory regimes are tightening compositional thresholds faster than reformulation timelines can accommodate.
- Alternative protein cost structure:Egg replacement ingredients derived from legume or algae sources trade at 40-60% premiums over conventional inputs.
Strategic Opportunities
- Subscription breakfast box services:Direct-to-consumer channels are bypassing wholesale bakery intermediaries and capturing recurring revenue from urban professional households.
- Gluten-free certification tailwind:Celiac awareness expansion and EU organic certification requirements are reshaping supermarket assortment planning for specialty segments.
- Long-shelf-life wrapped formats:Mass-market grocery channels favor ambient-stable products that reduce retail shrink and extend distribution reach.
Industry Challenges
- Reformulation technical complexity:Sugar reduction targets conflict with moisture retention requirements in chemically leavened quick bread systems.
- Cross-regional recipe harmonization:Divergent FDA, EFSA, and Health Canada labeling baselines force parallel product line maintenance.
- Clean-label ingredient stability:Natural preservative alternatives shorten finished goods shelf life and complicate inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Muffins Market |
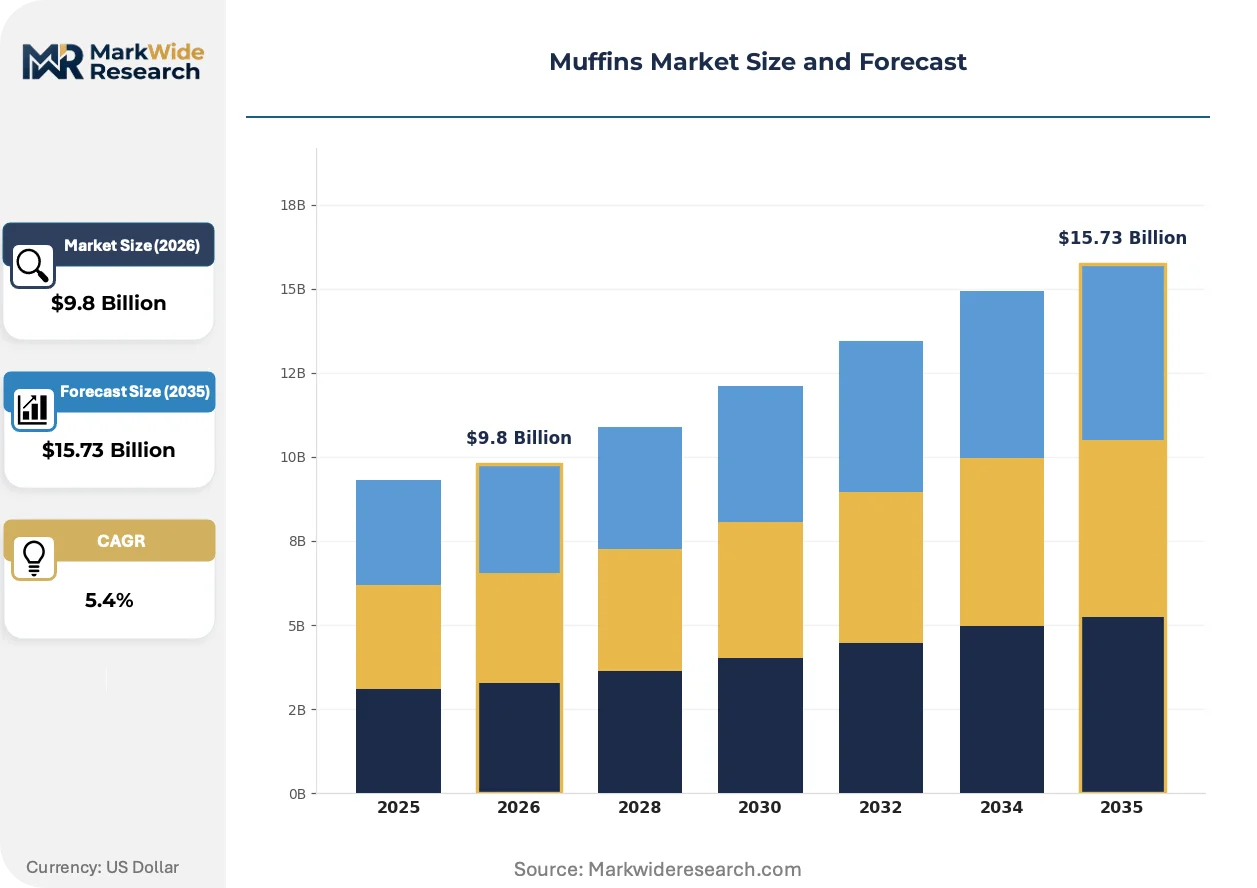
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blueberry, Chocolate Chip, Banana Nut, Lemon Poppy Seed Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Cafés Ingredient Type: Gluten-Free, Organic, Whole Wheat, Conventional Packaging Type: Box, Plastic Wrapper, Tray, Bulk |
| Companies Covered | McKee Foods Corporation, Flowers Foods, Grupo Bimbo, Britannia, Pladis (United Biscuits), Hostess Brands, Associated British Foods, George Weston Foods, ARYZTA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Muffins Market Emerging Trajectories
Functional ingredient substitution and distribution model disintermediation are converging to reshape competitive positioning, with technology adoption compressing traditional wholesale bakery intermediation.
Enzyme-based dough conditioning systems are consolidating control over crumb structure in reduced-sugar formulations. Mid-size commercial bakeries are adopting these systems to maintain texture profiles while meeting regulatory sugar thresholds. The technology is consolidating formulation expertise within ingredient supplier networks and reducing in-house R&D headcount at brand manufacturers.
EFSA's updated nutrition claim substantiation requirements are tightening health positioning evidence standards for functional muffin variants. Manufacturers must now commission clinical or robust observational studies to support digestive wellness or glycemic response claims. European premium positioning segments are responding by narrowing health claim portfolios to focus on verifiable fiber content declarations.
Urban foodservice buyers are consolidating procurement through centralized category management platforms that disaggregate volume across multiple bakery suppliers. Corporate cafeteria and convenience store chains are replacing direct supplier relationships with aggregated purchasing cooperatives. This pattern concentrates most visibly in North American metropolitan markets where retail consolidation has preceded foodservice procurement centralization.
Muffins Market Segmentation
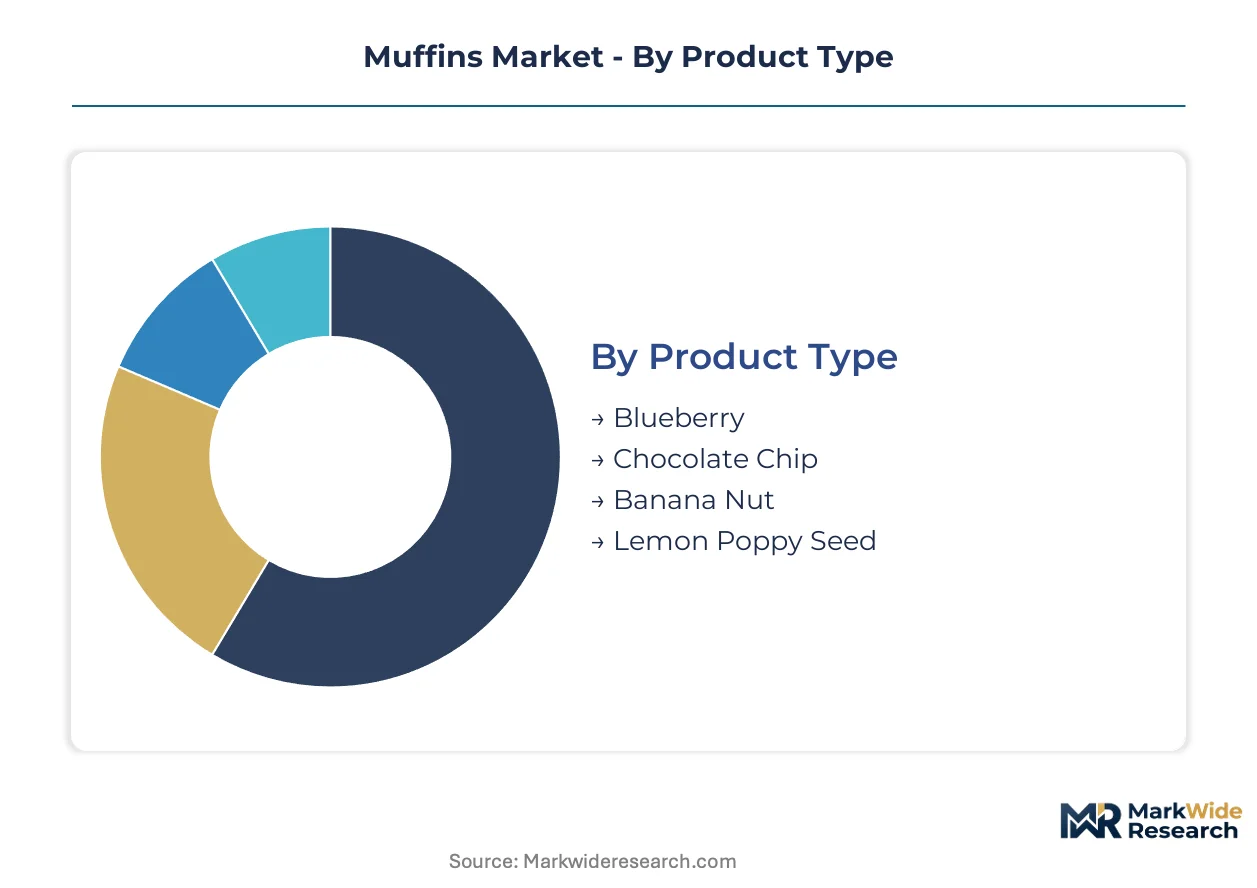
Muffin segmentation captures divergent purchase occasions across breakfast, snacking, and indulgence moments. Manufacturers must align formulation, packaging, and channel strategy to each segment's distinct margin structure and shelf-life requirements.
Product Type:
Flavor selection signals occasion targeting and price positioning within the bakery aisle.
- Blueberry:Classic fruit-inclusion formulation with dried or IQF wild blueberries distributed through mass-market retail. Dominant repeat-purchase rates in North American household breakfast routines anchor volume concentration.
- Chocolate Chip:Semi-sweet morsel distribution throughout the crumb creates indulgence positioning for afternoon snacking occasions. Premium pricing in cafés and specialty stores offsets higher cocoa input costs.
- Banana Nut:Moisture-dense formulation with walnut or pecan inclusions targeting health-permissible treat positioning.
- Lemon Poppy Seed:Citrus oil and seed textural contrast commands boutique bakery and seasonal limited-edition placement.
Volume sits with Blueberry; growth tilts toward Chocolate Chip.
Distribution Channel:
Channel choice determines packaging format, margin capture, and brand control intensity.
- Supermarkets:High-velocity in-store bakery and center-store packaged sections with weekly promotional cadence driving volume. Direct-store-delivery infrastructure controls shelf positioning and reduces out-of-stock rates.
- Specialty Stores:Premium artisan positioning with shorter ingredient decks and localized production claims. Urban professional households sustain price premiums for perceived freshness and provenance transparency.
- Online Retail:Subscription breakfast box services aggregate recurring demand and bypass wholesale bakery intermediaries.
- Cafés:Foodservice grab-and-go occasions favor individually wrapped portion formats with extended ambient stability.
Supermarkets capture absolute volume; Online Retail climbs the fastest.
Ingredient Type:
Certification tier dictates procurement cost structure and regulatory compliance burden.
- Gluten-Free:Rice flour, tapioca starch, and xanthan gum systems replace wheat protein matrices. Celiac awareness expansion and supermarket dedicated shelf-space allocation accelerate placement.
- Organic:Certified wheat and cane sugar sourcing with EU organic logo and USDA seal requirements. Regenerative agriculture certification programs redirect European procurement networks.
- Whole Wheat:Bran and germ inclusion increases fiber content declarations for front-of-pack scoring systems.
- Conventional:Standard refined wheat flour formulations with cost-optimized commodity input sourcing.
Conventional holds volume dominance; Gluten-Free gains share fastest.
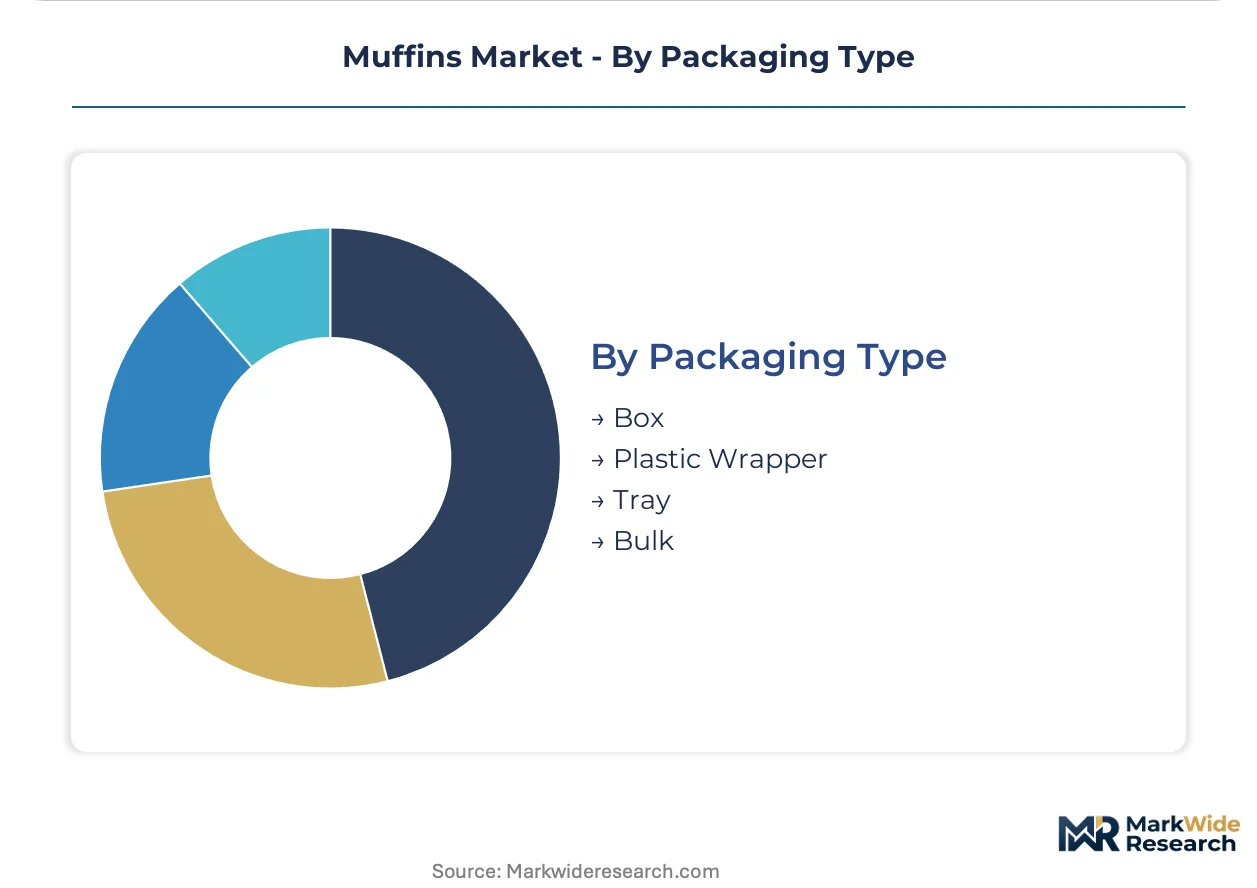
Packaging Type:
Packaging format balances shelf-life extension, portion control, and retail shrink reduction.
- Box:Multi-count paperboard enclosures for center-store retail with product visibility windows and reclose features. Family-size positioning supports breakfast occasion stock-up behavior.
- Plastic Wrapper:Individually sealed flow-wrap films with modified atmosphere properties for foodservice and convenience store channels. Extended ambient stability reduces retail shrink and enables broader distribution reach.
- Tray:Rigid PET or pulp-based containers for premium bakery display with product protection and stacking efficiency.
- Bulk:Unwrapped loose product for in-store bakery self-service with highest per-unit margin and shortest coded life.
Plastic Wrapper commands foodservice volume; Box maintains retail leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American muffin manufacturing through its centralized grain-milling corridor and foodservice distribution networks. The metropolitan area hosts major baking facilities serving convenience store and grocery channels across the Midwest. This concentration pattern repeats across four additional national markets where regulatory and demand conditions diverge.
United States
Urban professional households in New York and Los Angeles drive subscription breakfast box adoption through direct-to-consumer channels. The FDA's updated Nutrition Facts labeling mandates compress reformulation timelines for sugar and saturated fat declarations. Chicago-based baking clusters leverage direct-store-delivery infrastructure to control retail shelf positioning in mass-market grocery.
Germany
Regenerative agriculture certification programs redirect organic wheat procurement toward Bavarian and North Rhine-Westphalian grain cooperatives. The EU Green Deal's farm-to-fork sustainability targets compel reformulation of conventional wheat-based recipes across manufacturing networks. Munich and Hamburg anchor premium bakery positioning where clean-label assortments command dedicated shelf-space allocation.
India
FSSAI sodium reduction guidelines aligned with WHO recommendations open reformulated product development for export-oriented bakeries in Maharashtra and Karnataka. Health-conscious urban consumers in Mumbai and Bangalore expand purchases of individually wrapped portion formats. Domestic milling capacity concentrates in Gujarat and Telangana where commodity wheat sourcing meets cost-optimized production.
United Kingdom
Supermarket assortment planning for gluten-free segments accelerates through dedicated shelf-space mandates in London and Southeast England. The Nutri-Score front-of-pack scoring system tightens compositional standards for packaged muffin portfolios. Midlands-based manufacturing clusters specialize in long-shelf-life wrapped formats for convenience store distribution.
Brazil
Front-of-pack warning label regimes in São Paulo and Rio de Janeiro tighten compositional thresholds faster than reformulation timelines accommodate. Mass-market grocery channels favor ambient-stable products that reduce retail shrink in tropical distribution conditions. Minas Gerais hosts regional milling capacity serving cost-optimized conventional formulations.
Muffins Market Vendor Landscape
The competitive structure tilts toward vertically integrated grain processors with captive flour supply and direct-store-delivery networks. Mid-tier manufacturers face input bottlenecks as certified organic wheat milling capacity concentrates in specific grain belts. Three archetypes dominate: multinational bakery conglomerates with continental manufacturing footprints, regional specialists in long-shelf-life wrapped formats, and artisan-positioned premium players with localized production claims. Dominant competitive moves include backward integration into grain milling and strategic partnerships with regenerative agriculture certification programs.
Among North American baking conglomerates, McKee Foods Corporation and Flowers Foods exemplify scale-driven archetypes with mass-market grocery penetration. Grupo Bimbo represents the multinational vertically integrated model with grain-milling networks spanning multiple continents. These three entities anchor the competitive landscape through contrasting supply chain configurations—captive organic flour procurement, direct-store-delivery infrastructure, and deep specialization in ambient-stable wrapped distribution.
| Leading Market Players |
|---|
| McKee Foods Corporation |
| Flowers Foods |
| Grupo Bimbo |
| Britannia |
| Pladis (United Biscuits) |
| Hostess Brands |
| Associated British Foods |
| George Weston Foods |
| ARYZTA |
| Others |
Supply Flow & Price Mechanics
Grab-and-go foodservice procurement consolidation across North American metropolitan markets is compressing order batch sizes and accelerating delivery frequency requirements, forcing bakeries to absorb logistics premiums or cede shelf positioning to competitors with captive distribution networks.
Pricing Analysis
Value-based pricing anchors on clean-label certification tiers, with organic and gluten-free variants commanding sustained premiums over conventional formulations. Three-tier pricing structure across premium, standard, and economy levels separates artisan-positioned specialty stores from mass-market grocery and private-label economy tiers. Cost compression in mid-tier conventional segments is intensifying because organic flour supply bottlenecks concentrate procurement leverage among vertically integrated conglomerates. Foodservice buyers exhibit highest price sensitivity due to centralized category management platforms, while subscription direct-to-consumer households show lowest sensitivity.
Supply Chain Analysis
Organic wheat supply rests on certified milling capacity concentrated in the United States, Canada, and France, with regenerative agriculture certification programs redirecting European procurement networks. Key inputs include specialty grain flours, natural preservative systems, and modified atmosphere packaging films. Single-source vulnerability concentrates in xanthan gum supply for gluten-free formulations, which draws from Chinese fermentation capacity. Distribution runs through direct-store-delivery networks controlling retail shelf positioning, supplemented by wholesale bakery intermediaries serving foodservice channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as clean-label reformulation mandates and organic input bottlenecks force mid-tier manufacturers toward acquisition or exit.
For Market Incumbents: Deploy backward integration into grain milling to secure cost-advantaged organic flour supply across North American and European networks. Invest in enzyme-based dough conditioning systems to maintain texture profiles in reduced-sugar formulations, defending against specialty ingredient suppliers consolidating formulation expertise. Control foodservice channel access through direct-store-delivery infrastructure investments in Chicago and Midwest distribution corridors.
For New Entrants and Emerging Players: Begin with subscription breakfast box services targeting urban professional households in New York and Los Angeles, bypassing wholesale bakery intermediaries entirely. Penetrate the gluten-free certification segment where celiac awareness expansion and dedicated supermarket shelf-space mandates create placement tailwinds. Pursue white-label manufacturing partnerships with regenerative agriculture cooperatives in Bavaria and North Rhine-Westphalia for European market entry.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated grain processors with captive flour supply and established direct-store-delivery footprints. Long-term viability hinges on controlling organic wheat procurement and reformulation R&D capabilities against tightening regulatory baselines. Watch FSSAI enforcement phase-ins in India and Latin American front-of-pack warning label implementations as inflection indicators for regional recipe harmonization costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Milling | Captive organic flour supply secures cost advantages against input bottlenecks in North American grain belts. |
| Clean-Label Reformulation Investment | Enzyme-based systems maintain crumb structure while meeting FDA and EU Nutri-Score sugar thresholds. |
| Direct-to-Consumer Channel Launch | Subscription breakfast boxes bypass wholesale intermediaries and capture recurring revenue from urban households. |
| Regenerative Agriculture Certification Partnership | EU Green Deal compliance redirects European procurement toward Bavarian and North Rhine-Westphalian cooperatives. |
| Long-Shelf-Life Format Development | Ambient-stable wrapped products reduce retail shrink and extend distribution reach in tropical Brazilian conditions. |
Methodological Framework
Document review covered customs and trade data, FDA and EFSA regulatory filings, and Nielsen retail audit records, complemented by interviews with bakery R&D directors, grain procurement managers at milling operations, supermarket category buyers, and foodservice distribution executives. Primary fieldwork triangulated against secondary validation from SEC filings of publicly traded baking conglomerates, EU organic certification databases, and FSSAI guideline publications. Bottom-up volume modeling across product type, ingredient certification tier, packaging format, and distribution channel converged with top-down market sizing.
Cross-referencing historical volume trajectories against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include flavor category, clean-label certification grade, packaging shelf-life tier, and regional regulatory cluster. CAGRs derived from regression analysis of correlated demand drivers including urbanization rates, health regulatory enforcement intensity, and foodservice channel penetration. Industry-specific forecast inputs incorporated organic wheat supply capacity expansion timelines and enzyme technology adoption curves in commercial bakeries.
Regulatory enforcement delays, organic commodity price spikes, and alternative protein cost structure shifts are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about reformulation timeline feasibility and certification program scalability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
US Frozen Bakery Market
Bakery Products
Low-Gluten Emmer and Einkorn Flour Blends Market
Bakery Products
Bakery Conditioner Market
Bakery Products
Gulf Cooperation Council Frozen Bakery Products Market
Bakery Products
Lentil Bread Market
Bakery Products
Specula Market
Bakery Products
Teaseed Cake Market
Bakery Products
Specialty Bakery Market
Bakery Products
Cake Base Discs Market
Bakery Products
Bread Dough Improver Market
Bakery Products
Bread Slicer Blades Market
Bakery Products
Low Calorie Muffins Market
Bakery Products
Cakes and Pastries Market
Bakery Products
Gluten-Free Bakery Market
Bakery Products
Bread and Baked Food Market
Bakery Products
United States Cookies Market