
 Global Needle Free Diabetes Care Market | 2026-2036
Global Needle Free Diabetes Care Market Size, Share, and Industry Trends Forecast 2026-2036
Global Needle Free Diabetes Care Market Intelligence
The EU Green Deal is broadening the sustainability mandate for medical device manufacturing across European supply chains. Abbott Laboratories leverages its continuous glucose monitoring infrastructure to anchor wearable form factors in diabetes management. MannKind Corporation specializes in inhalable insulin delivery, occupying a distinct niche within needle-free therapeutic options. Dexcom, Inc. competes through sensor miniaturization and real-time data integration with insulin pump ecosystems.
Needle-free diabetes care encompasses drug delivery and glucose monitoring systems that eliminate percutaneous needle penetration, typically operating through transdermal, pulmonary, or microneedle array mechanisms with penetration depths below one millimeter. These technologies serve diabetic patients requiring frequent insulin administration or glucose surveillance without the tissue trauma, biohazard waste, and psychological barriers associated with conventional hypodermic injection. Wearable injectors and transdermal patches command the largest addressable base within delivery mode segments, while micro-needle platforms represent the fastest-expanding category due to their compatibility with biologic formulations and patient-administered use cases. Homecare settings generate disproportionate margin capture within end-user channels, reflecting the shift toward decentralized chronic disease management and remote patient monitoring reimbursement.
FDA premarket notification pathways, EU MDR conformity assessment requirements, and ISO 13485 quality management standards collectively govern device commercialization and post-market surveillance obligations for needle-free diabetes products. Japan's PMDA and Health Canada impose additional clinical evidence requirements that shape regional launch sequencing and registration investment priorities. Stakeholders must monitor evolving pharmacovigilance expectations for combination products and anticipate harmonization gaps between drug and device regulatory frameworks.
Market Dynamics
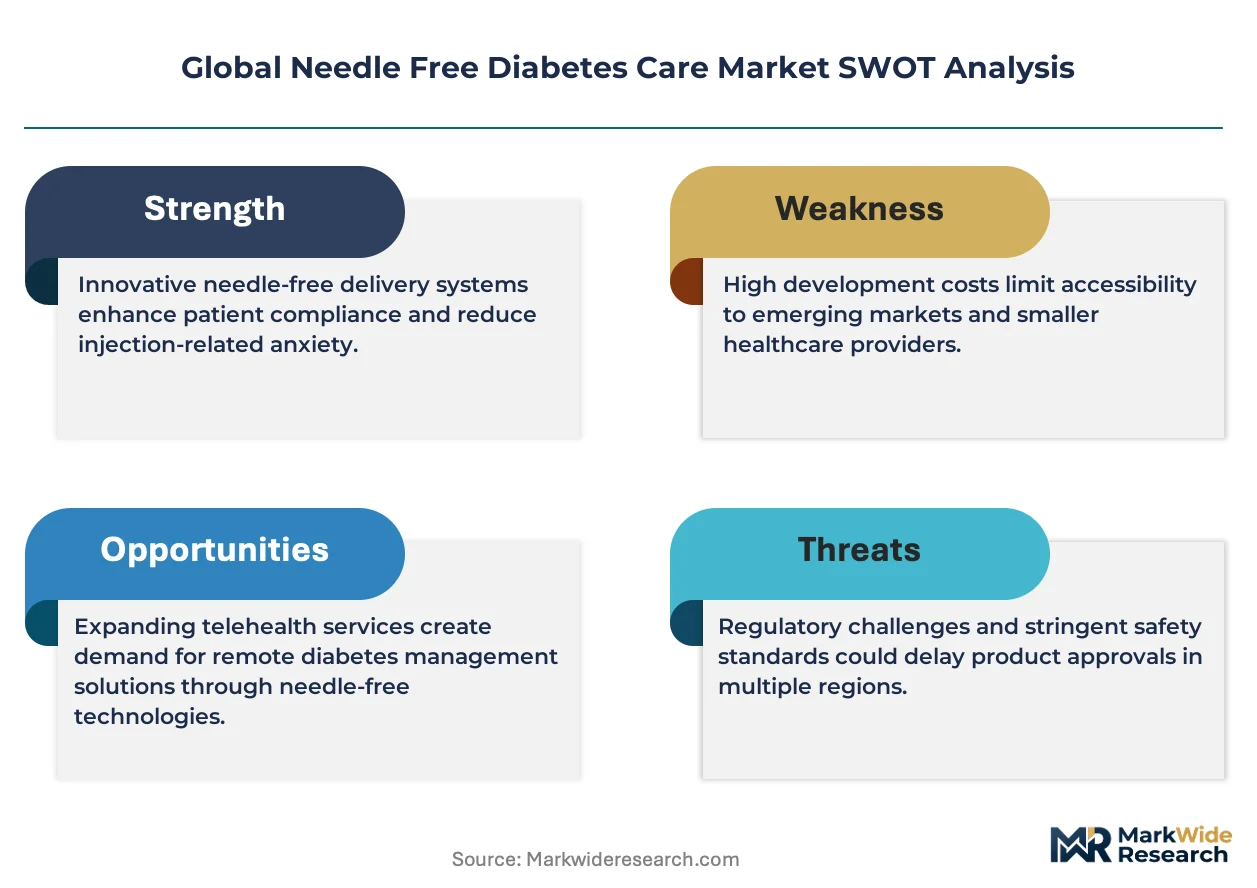
FDA 510(k) clearance compression for transdermal insulin delivery systems is collapsing time-to-market cycles from thirty-six to eighteen months, forcing incumbent device manufacturers to accelerate clinical validation pipelines or cede first-mover positioning to agile competitors.
Growth Catalysts
- EU MDR conformity acceleration:Streamlined technical documentation requirements for Class IIa wearable injectors are reducing notified body review timelines across German and French certification pathways.
- Homecare reimbursement expansion:United States CMS remote patient monitoring codes now cover non-invasive glucose surveillance for Type 2 populations, shifting site-of-care economics toward patient-administered delivery.
- Microneedle biologic compatibility:Polymeric dissolving arrays now accommodate peptide formulations previously restricted to subcutaneous injection, opening therapeutic categories beyond insulin.
Market Restraints
- Active pharmaceutical ingredient concentration:Inhalable insulin requires three to four times the bulk API versus subcutaneous equivalents, exposing manufacturers to insulin supply volatility from Danish and Indian fermentation facilities.
- PMDA clinical evidence thresholds:Japan's pharmaceutical and medical devices agency demands twelve-month local bridging studies for transdermal patches, extending registration investment timelines.
- Transdermal flux rate limitations:Current iontophoretic systems cannot achieve therapeutic delivery for patients requiring >50 units daily insulin, constraining addressable population.
Strategic Opportunities
- Pediatric indication white space:No needle-free delivery system holds approved labeling for patients under eighteen, creating exclusivity potential for first validated juvenile pharmacokinetic submissions.
- CSRD supply chain disclosure:European sustainability reporting mandates are privileging device manufacturers with carbon-transparent polymer sourcing and closed-loop patch recycling infrastructure.
- Continuous monitoring-pump convergence:API integration between real-time glucose sensors and closed-loop wearable injectors is absorbing patient adherence friction into automated dose-response algorithms.
Industry Challenges
- Biocompatibility toxicologist scarcity:FDA combination product submissions require specialized expertise in skin irritation protocols that outstrips available contract research organization capacity.
- Legacy electronic health record interoperability:Homecare glucose data streams face integration friction with hospital-based Epic and Cerner systems, fragmenting longitudinal patient records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Needle Free Diabetes Care Market |
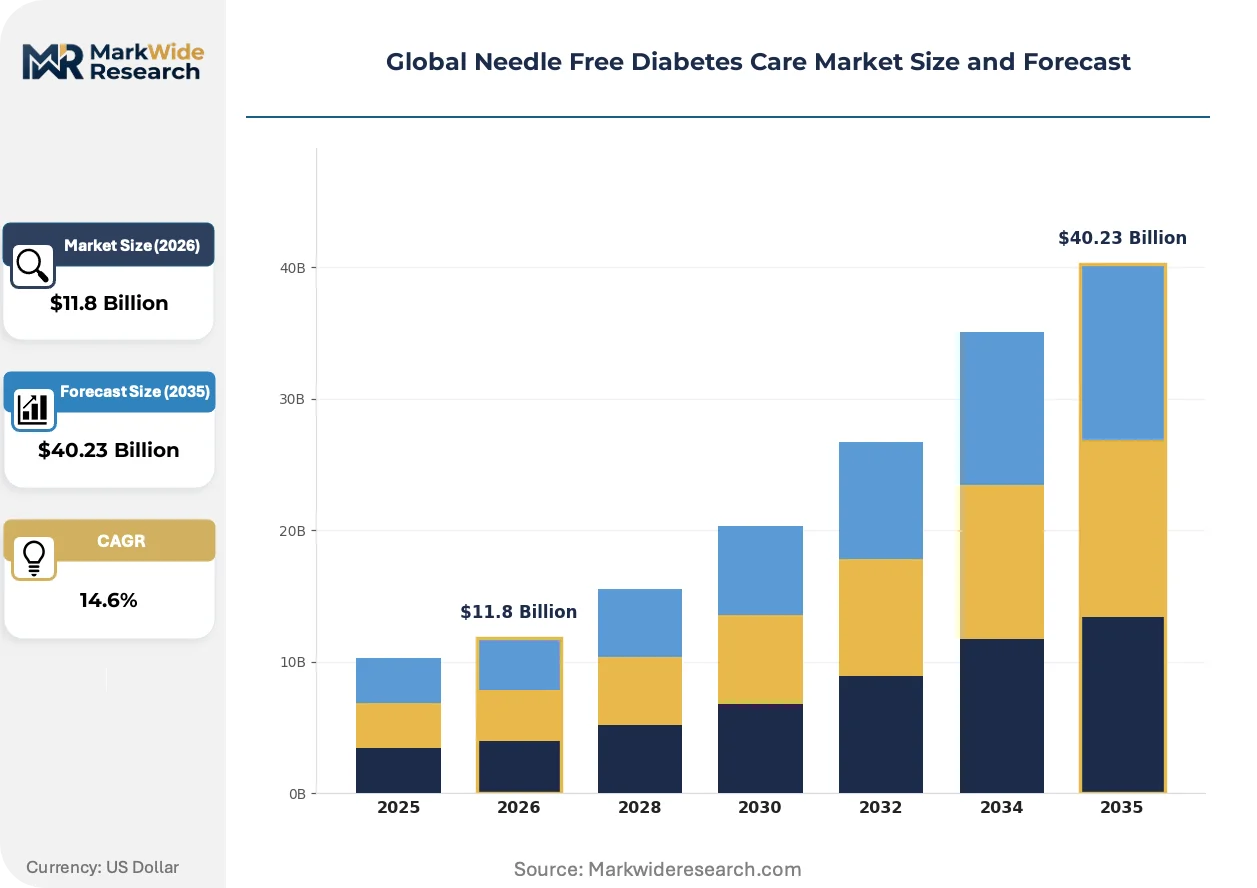
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $40.23 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
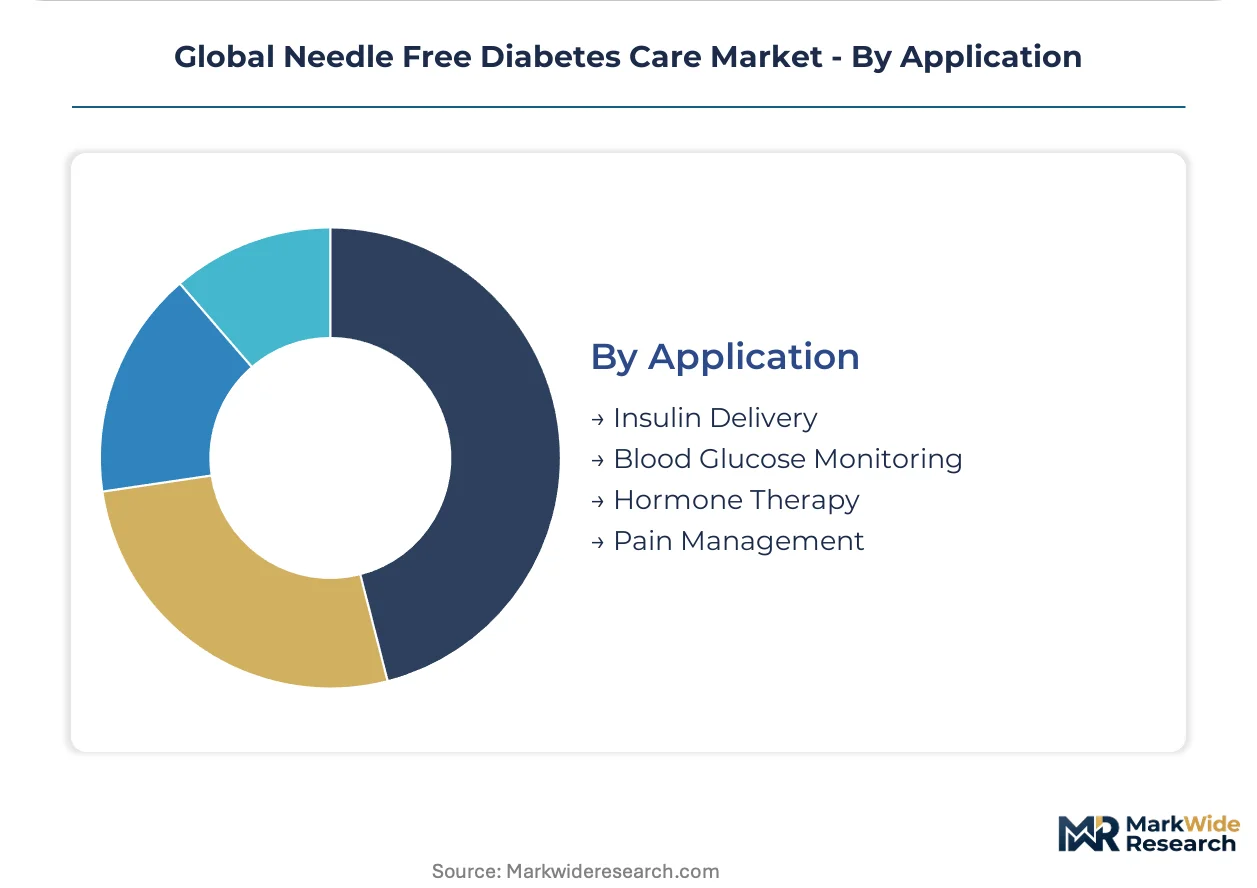
| Segmentation | Product Type: Devices, Systems, Solutions, Technologies Delivery Mode: Wearable Injectors, Spray Injections, Micro-needles, Transdermal Patches End User: Hospitals, Clinics, Homecare, Pharmacies Application: Insulin Delivery, Blood Glucose Monitoring, Hormone Therapy, Pain Management |
| Companies Covered | Antares Pharma, Inc., Bioject Medical Technologies, Inc., Abbott Laboratories, PharmaJet, Inc., INJEX Pharma AG, Insulet Corporation, MannKind Corporation, Becton, Dickinson and Company, Dexcom, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Needle Free Diabetes Care Market Strategic Shifts & Innovations
Transdermal delivery physics and real-time biosensor miniaturization are converging to collapse the distinction between glucose measurement and insulin administration into single-wearable platforms.
Microneedle arrays fabricated from hyaluronic acid and polyvinylpyrrolidone are absorbing the mechanical penetration function previously requiring metal hypodermics, enabling painless insulin deposition at 200-micron depths. Elderly Type 2 populations in Japanese homecare settings are adopting these dissolving platforms at rates exceeding patch pumps, compressing training burden and biohazard disposal costs for visiting nurse services. The technology is absorbing patient psychological resistance that previously drove fifteen to twenty percent annual discontinuation in conventional injection regimens.
EU MDR Article 117 requirements for drug-device combination products are mandating notified body involvement in quality system audits previously handled through self-certification, elevating documentation burden for transdermal patch manufacturers. This regulatory friction is compressing the European supplier base toward entities with established pharmaceutical quality management systems. Inhalable insulin delivery systems face heightened scrutiny under the EMA's revised guidance on pulmonary immunogenicity, extending development timelines for MannKind's competitive successors.
Diabetes purchasing committees within United States integrated delivery networks are consolidating supplier contracts around vendors offering combined glucose monitoring and insulin delivery platforms, displacing standalone device procurement. Hospital systems in Texas and Florida are bundling remote patient monitoring reimbursement with exclusive formulary placement for needle-free systems, forcing manufacturers to absorb service infrastructure costs previously borne by third-party distributors. This channel consolidation is most visible in Medicare Advantage populations where capitated payment models align device selection with total cost-of-care metrics.
Global Needle Free Diabetes Care Market Segmentation
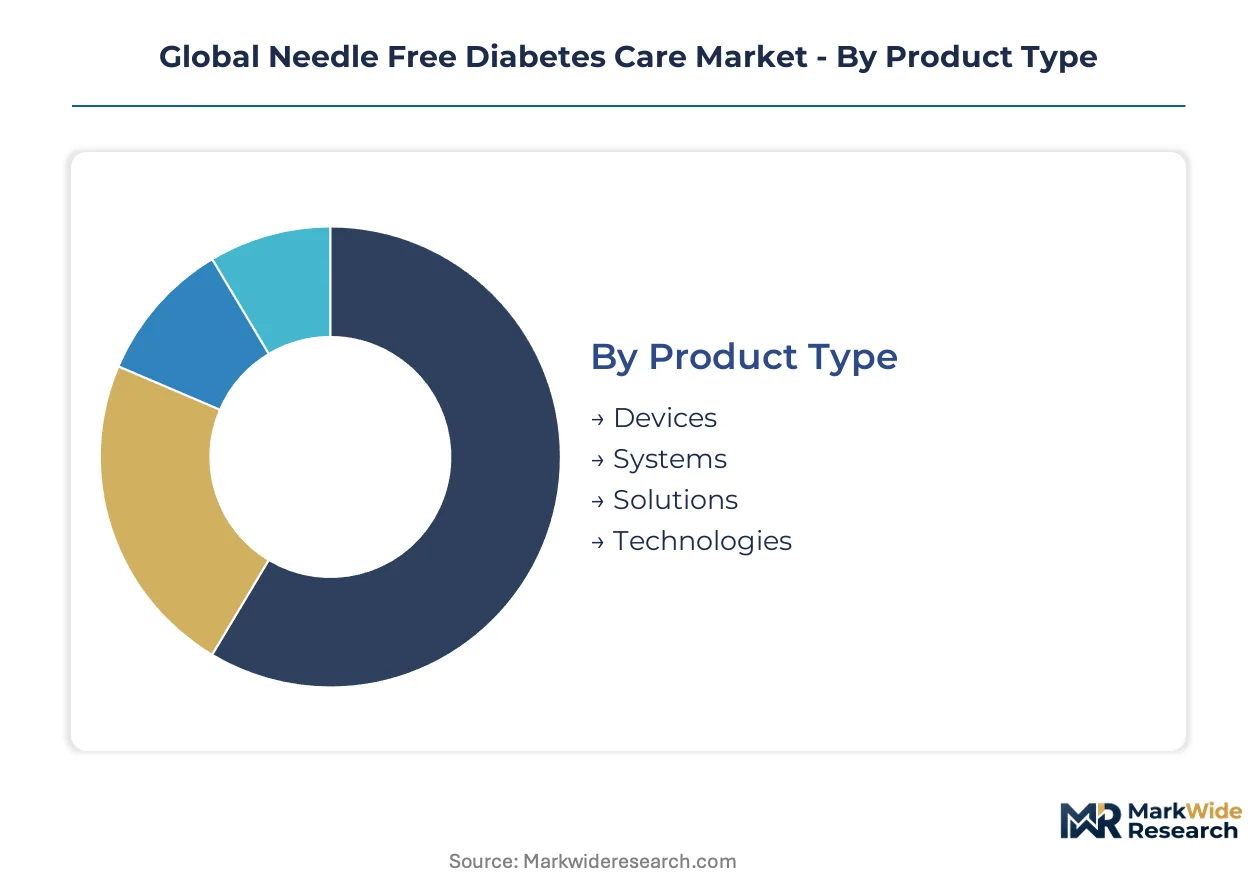
Needle-free diabetes care segments diverge sharply by reimbursement eligibility, patient self-administration capability, and regulatory pathway complexity. Manufacturers must align portfolio investments with where volume economics and margin capture concentrate across delivery modalities and care settings.
Product Type:
Procurement committees weight capital expenditure thresholds against disposable recurring revenue streams when evaluating product category fit.
- Devices:Standalone needle-free injectors and glucose monitors comprise the installed base foundation. United States hospital systems favor FDA 510(k)-cleared devices with established Epic EHR integration, locking out newer entrants lacking interoperability certification.
- Systems:Integrated platforms combining sensor arrays with automated dose-response algorithms command premium positioning. German integrated care networks are consolidating contracts around system vendors offering remote patient monitoring bundled reimbursement.
- Solutions:Service wraparounds including training, disposal logistics, and adherence analytics.
- Technologies:Licensing of transdermal delivery patents and microneedle fabrication IP.
Volume sits with Devices; growth tilts toward Systems.
Delivery Mode:
Patient pain tolerance and insulin pharmacokinetics determine modality selection across age and disease severity cohorts.
- Wearable Injectors:Patch-style pumps delivering basal insulin through piezoelectric or mechanical actuation without percutaneous needles. Japanese homecare agencies are deploying these for elderly Type 2 populations where caregiver training resources are constrained.
- Micro-needles:Dissolving polymeric arrays penetrating 200-500 microns to deposit insulin in epidermal layers. The technology is expanding fastest among pediatric candidates and needle-phobic adults previously discontinuing injection regimens.
- Spray Injections:Jet propulsion systems using high-pressure gas to force insulin through skin.
- Transdermal Patches:Passive or iontophoretic diffusion systems for basal insulin delivery.
Revenue concentrates in Wearable Injectors; Micro-needles are climbing the fastest.
End User:
Site-of-care economics and reimbursement code availability shape channel prioritization for commercial teams.
- Homecare:Patient-administered delivery settings where CMS remote monitoring codes now cover non-invasive glucose surveillance. Texas and Florida Medicare Advantage plans are bundling device costs into capitated payments, accelerating household penetration.
- Hospitals:Inpatient glycemic management and perioperative insulin protocols. German university hospitals are piloting closed-loop wearable systems for surgical recovery units, establishing efficacy data for broader formulary adoption.
- Clinics:Outpatient endocrinology practices and diabetes education centers.
- Pharmacies:Retail distribution points for over-the-counter glucose monitors and prescription delivery devices.
Margin capture favors Homecare; patient volume remains anchored in Hospitals.
Application:
Therapeutic indication breadth determines addressable market expansion beyond core insulin-dependent populations.
- Insulin Delivery:The foundational use case spanning Type 1 and advanced Type 2 diabetes. FDA combination product regulations treat insulin patches as drug-device hybrids, extending approval timelines versus standalone monitors.
- Blood Glucose Monitoring:Continuous and flash glucose surveillance without fingerstick calibration. Real-time data streams from Dexcom and Abbott sensors are integrating with insulin pump ecosystems, collapsing the distinction between measurement and delivery.
- Hormone Therapy:Glucagon-like peptide-1 agonist and other peptide delivery via microneedle arrays.
- Pain Management:Adjunct applications for diabetic neuropathy treatment delivery.
Insulin Delivery holds current revenue concentration; Blood Glucose Monitoring is gaining share fastest through sensor-pump convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing concentrates in German precision engineering clusters while patient adoption and reimbursement innovation centers on United States Medicare Advantage networks and Japanese homecare agencies. Consumption patterns diverge sharply between elderly Type 2 populations seeking caregiver-reduced solutions and Type 1 patients demanding closed-loop automation.
United States
CMS remote patient monitoring codes now reimburse non-invasive glucose surveillance for Type 2 populations, accelerating household penetration among Medicare Advantage enrollees in Texas and Florida capitated plans. FDA 510(k) clearance compression for transdermal insulin delivery systems is collapsing time-to-market cycles from thirty-six to eighteen months. Boston and Minneapolis medical device clusters host the dominant share of wearable injector engineering talent.
Germany
Integrated care networks in Bavaria and North Rhine-Westphalia are consolidating supplier contracts around vendors offering combined glucose monitoring and insulin delivery platforms with remote patient monitoring bundled reimbursement. EU MDR Article 117 mandates notified body involvement in quality system audits for drug-device combination products, elevating documentation burden for transdermal patch manufacturers. The EU Green Deal is broadening sustainability mandates across medical device supply chains headquartered in Baden-Württemberg.
Japan
Elderly Type 2 populations in homecare settings are adopting dissolving microneedle platforms at rates exceeding patch pumps, compressing training burden for visiting nurse services in Tokyo and Osaka metropolitan areas. PMDA demands twelve-month local bridging studies for transdermal patches, extending registration investment timelines beyond European and American pathways. METI industrial policy supports domestic manufacturing of polymeric microneedle arrays.
India
Domestic fermentation facilities supply active pharmaceutical ingredients for inhalable insulin formulations requiring three to four times the bulk API versus subcutaneous equivalents. CDSCO clinical trial regulations for combination products are harmonizing with ISO 13485 quality management standards, streamlining device commercialization for export-oriented manufacturers. Hyderabad and Bangalore pharmaceutical clusters are attracting contract research organizations specializing in skin irritation protocols.
Switzerland
Swissmedic maintains stringent post-market surveillance obligations for needle-free diabetes products that shape regional launch sequencing for manufacturers seeking European anchor markets. Geneva and Basel precision polymer suppliers serve microneedle fabrication demands from German and French device makers. The country's carbon-transparent polymer sourcing infrastructure positions it favorably under emerging CSRD supply chain disclosure requirements.
Global Needle Free Diabetes Care Market Key Industry Players
The competitive structure tilts toward diversified medical technology conglomerates with established continuous glucose monitoring infrastructure. Market concentration reflects significant barriers to entry including FDA combination product regulations, specialized biocompatibility toxicologist scarcity, and electronic health record interoperability certification requirements. Three archetypes dominate: sensor-pump integrators leveraging real-time data ecosystems, inhalable insulin specialists occupying pulmonary delivery niches, and microneedle platform developers targeting needle-phobic discontinuers. Dominant competitive moves include strategic partnerships between device manufacturers and insulin API suppliers, plus geographic expansion through notified body certification stacking across EU MDR, FDA, and PMDA pathways.
Among United States-based sensor-pump integrators, Dexcom, Inc. and Abbott Laboratories exemplify the data ecosystem archetype, while MannKind Corporation represents the inhalable insulin specialization tier. These entities anchor distinct competitive vectors without overlapping core technology positioning, enabling parallel market expansion rather than direct substitution competition.
| Leading Market Players |
|---|
| Antares Pharma, Inc. |
| Bioject Medical Technologies, Inc. |
| Abbott Laboratories |
| PharmaJet, Inc. |
| INJEX Pharma AG |
| Insulet Corporation |
| MannKind Corporation |
| Becton, Dickinson and Company |
| Dexcom, Inc. |
| Others |
Cost & Logistics Intelligence
Insulin API spot pricing from Danish and Indian fermentation facilities cascades through device manufacturing tiers, compressing margins on inhalable formulations while concentrating pricing power with vertically integrated patch pump suppliers serving Medicare Advantage networks.
Pricing Analysis
Value-based pricing anchored to HbA1c outcome guarantees now dominates United States integrated delivery network contracts, replacing per-unit device reimbursement. Three-tier pricing structure across premium closed-loop systems, standard wearable injectors, and economy microneedle arrays differentiates by FDA combination product certification status and Epic EHR interoperability tier. Pricing pressure stems from CMS remote patient monitoring code compression and capitated Medicare Advantage plan negotiations. Homecare elderly populations exhibit highest price sensitivity; pediatric indication holders command lowest elasticity due to exclusivity scarcity.
Supply Chain Analysis
Polymeric microneedle substrate supply rests on German precision polymer suppliers and Swiss carbon-transparent sourcing infrastructure serving EU MDR Article 117 compliance demands. Active pharmaceutical ingredient concentration for inhalable formulations draws from Danish Novo Nordisk fermentation capacity and Indian Biocon bulk insulin facilities. Single-source vulnerability concentrates in hyaluronic acid dissolving array feedstock from Tokyo and Osaka specialty chemical producers. Distribution runs through United States GPO contracts, German integrated care network tenders, and Japanese homecare agency procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR conformity acceleration and FDA 510(k) clearance compression are forcing subscale device manufacturers toward exit or acquisition, consolidating viable supplier bases around entities with pharmaceutical-grade quality management systems.
For Market Incumbents: Acquire pediatric pharmacokinetic data packages and juvenile bridging study archives to secure exclusivity in the under-eighteen needle-free delivery white space. Lock in long-term insulin API offtake agreements with Danish fermentation facilities before inhalable formulation demand spikes. Defend against microneedle platform entrants by accelerating sensor-pump convergence timelines and securing exclusive Epic EHR interoperability certification.
For New Entrants and Emerging Players: Visiting nurse service partnerships in Japanese metropolitan areas offer the most penetrable channel for dissolving microneedle platforms targeting elderly Type 2 populations. Target Texas and Florida Medicare Advantage capitated plans with remote patient monitoring bundled service proposals. Enter through private-label manufacturing contracts for European device firms lacking CSRD-compliant carbon-transparent polymer sourcing.
For Investors and Strategic Acquirers: Distressed-cycle entries favor microneedle platform developers with validated biologic compatibility but stranded without FDA combination product regulatory expertise. Five-to-ten year viability hinges on reimbursement code expansion for non-invasive glucose surveillance beyond Type 2 populations. Watch FDA premarket notification pathway compression rates as the inflection signal for first-mover valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Indication Development | FDA juvenile pharmacokinetic submissions unlock exclusive labeling in an untapped demographic segment. |
| CSRD Supply Chain Certification | Carbon-transparent polymer sourcing secures preferential positioning under EU Green Deal procurement mandates. |
| Sensor-Pump API Integration | Real-time glucose data streams into automated dose-response algorithms collapse patient adherence friction. |
| PMDA Bridging Study Investment | Twelve-month local clinical evidence satisfies Japan's pharmaceutical regulator for transdermal patch registration. |
| Epic EHR Interoperability Certification | Hospital system data integration locks out newer entrants lacking established electronic health record connectivity. |
Research Approach
Multi-period observation of FDA 510(k) clearance timelines, CMS remote patient monitoring code utilization, and EU MDR notified body queue lengths anchored the trend analysis, supplemented by interviews with biomedical engineers at German university hospitals, GPO contracts managers in Texas integrated delivery networks, and regulatory affairs leads at Japanese medical device subsidiaries. Secondary validation drew from FDA premarket notification databases, EMA drug-device combination product guidance documents, PMDA consultation minutes, and ISO 13485 audit disclosure filings. Bottom-up patient volume modeling across homecare, hospital, and clinic channels triangulated against top-down insulin delivery device procurement value estimates.
Segment-weighting applied delivery mode splits across wearable injectors, microneedles, transdermal patches, and spray injection systems, crossed with end-user channel economics and application-specific reimbursement eligibility. CAGRs derived from polynomial trend fitting of historical adoption curves adjusted for regulatory pathway acceleration effects. Forecast inputs incorporated PMDA bridging study timeline assumptions, EU MDR Article 117 documentation burden trajectories, and polymer substrate cost pass-through elasticity from German precision chemical suppliers.
Several conditions sit outside the modeled scope, including novel inhalable insulin immunogenicity events, sudden API supply disruptions from Indian fermentation facilities, and harmonization failures between FDA drug and device regulatory frameworks. Forecasts reflect documented assumptions about remote patient monitoring code stability and capitated plan penetration rates. A small set of named triggers warrants ongoing watch: FDA combination product review staffing levels, EU notified body capacity constraints, and Japanese METI industrial policy shifts on domestic microneedle manufacturing subsidies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Disposable Insulin-Delivery Device Market
Diabetes Care
South Korea Insulin Infusion Pump Market
Diabetes Care
China Continuous Glucose Monitoring Devices Market
Diabetes Care
Global Proliferative Diabetic Retinopathy Market
Diabetes Care
Diabetic Lancing Devices Market
Diabetes Care
Continuous Glucose Monitoring in Philippines Market
Diabetes Care
Asia Pacific Blood Glucose Test Strip Market
Diabetes Care
Digital Diabetes Care Market
Diabetes Care
Vietnam Diabetes Care Devices Market
Diabetes Care
Australia Insulin Infusion Pump Market
Diabetes Care
New Zealand Oral Anti-Diabetic Drug Market
Diabetes Care
Russia Diabetes Care Devices Market
Diabetes Care
Middle East and Africa Insulin Infusion Pumps Market
Diabetes Care
Insulin Pen Needles Market
Diabetes Care
SGLT2 Inhibitors Treatment Market
Diabetes Care
Malaysia Diabetes Care Devices Market