
 Anti-Neprilysin Market | 2026-2036
Anti-Neprilysin Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Neprilysin Market Insights
Combination therapy bundling is expanding as the dominant product-configuration pattern in anti-neprilysin commercial strategy. Novartis AG leverages its entrenched cardiovascular franchise to sustain leadership in fixed-dose combination formats. Cipla Ltd anchors its competitive position through manufacturing scale across emerging markets. Laurus Labs specializes in active pharmaceutical ingredient supply, differentiating through backward integration into key intermediates.
Anti-neprilysin compounds are enzyme inhibitors that block neprilysin, a neutral endopeptidase that degrades natriuretic peptides, thereby potentiating vasodilatory and anti-fibrotic signaling in cardiovascular and renal tissues. These agents functionally preserve endogenous vasoactive peptides, with primary commercial purpose centered on heart failure with reduced ejection fraction and resistant hypertension management. Among product type segments, combination therapy commands the largest margin pool due to patent-protected positioning and payer preference for single-pill adherence. Small molecule inhibitors represent the most mature category, while monoclonal antibodies emerge as the fastest-growing segment driven by biologic development pipelines targeting neprilysin-resistant pathways.
The FDA's cardiovascular drug approval standards and the EMA's centralized marketing authorization procedures collectively shape clinical trial design and label expansion for anti-neprilysin developers. REACH compliance in Europe and EPA manufacturing discharge requirements in the United States add cost layers to active pharmaceutical ingredient production, filtering market access for smaller manufacturers. Stakeholders must monitor how CMS national coverage determinations and parallel EMA health technology assessments converge on value-based pricing for combination formats.
Market Dynamics
Fixed-dose combination formats are consolidating prescribing patterns across cardiology departments, compressing demand for standalone neprilysin inhibitors while elevating adherence metrics as the decisive reimbursement lever.
Growth Catalysts
- CMS National Coverage Determinations:Medicare reimbursement protocols favor single-pill combination regimens, accelerating hospital formulary adoption of bundled cardiovascular therapies.
- Heart Failure with Reduced Ejection Fraction:Expanding diagnostic capture through biomarker-guided screening protocols is enlarging the addressable patient pool for neprilysin inhibition.
- Resistant Hypertension Pathways:Treatment-resistant hypertensive populations in tertiary care centers are driving off-label utilization beyond original heart failure indications.
Market Restraints
- Active Pharmaceutical Input Concentration:Backward-integrated manufacturers in India control critical sacubitril intermediates, creating single-source vulnerability for generic developers.
- REACH Compliance Burden:European chemical registration requirements add fixed cost layers to API synthesis, filtering market access for sub-scale producers.
- Biologic Substitution Trajectory:Monoclonal antibodies targeting neprilysin-resistant natriuretic peptide pathways threaten to displace small-molecule inhibitors in late-stage heart failure.
Strategic Opportunities
- Brazil's ANVISA Accelerated Pathway:Emerging market regulators are streamlining bioequivalence requirements for fixed-dose combinations, enabling faster generic entry.
- Chronic Kidney Disease Adjacency:Renal-protective signaling from neprilysin inhibition is expanding into diabetic nephropathy protocols, creating parallel indication development.
- Value-Based Contracting:Outcome-based reimbursement pilots in Medicare Advantage are rewarding adherence-improving single-pill formats with preferential tier placement.
Industry Challenges
- Cardiovascular Clinical Trial Talent Scarcity:Specialized principal investigators for heart failure outcomes studies command premium fees, extending recruitment timelines.
- Legacy EHR Integration Friction:Hospital systems struggle to embed combination therapy protocols into existing clinical decision support workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Neprilysin Market |
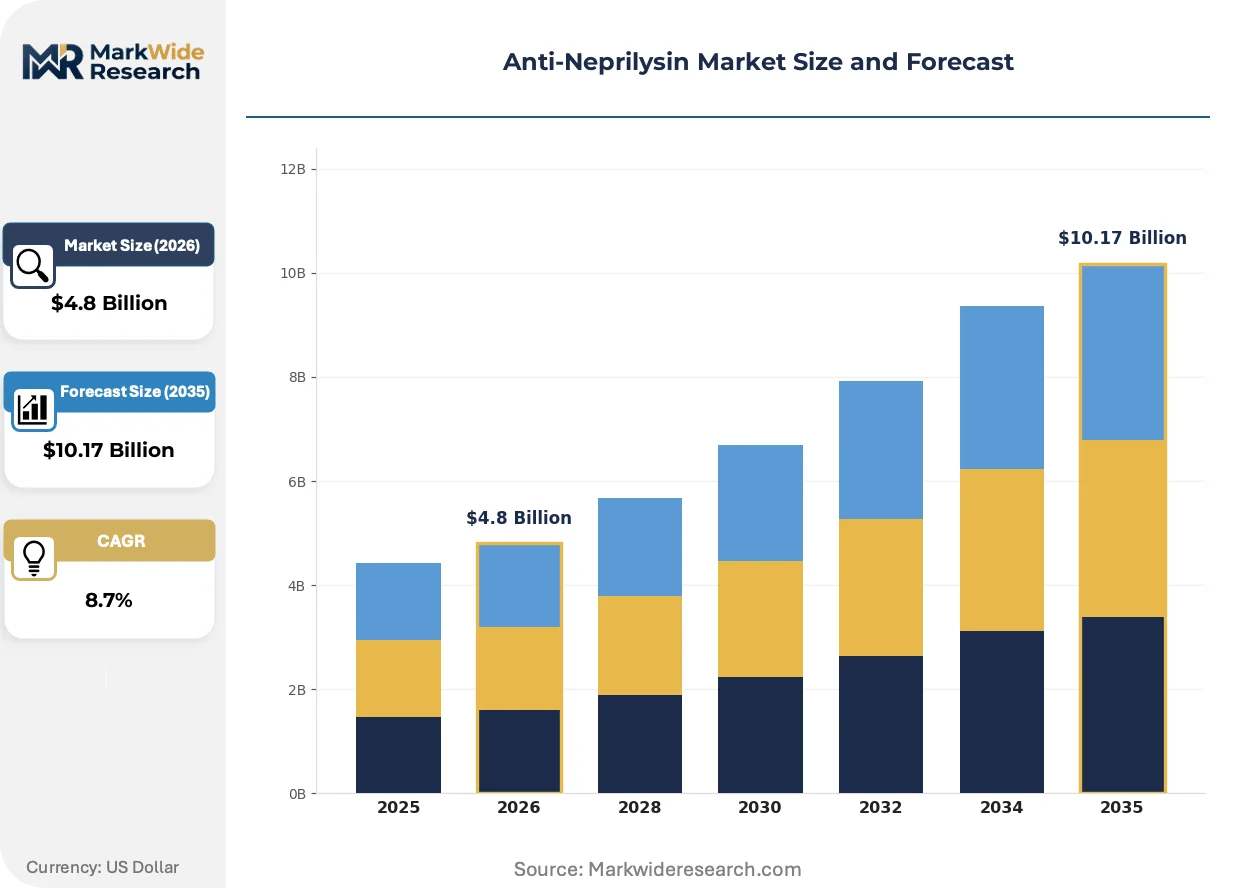
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecule Inhibitors, Monoclonal Antibodies, Combination Therapy, Tablets End User: Hospitals, Specialty Clinics, Homecare Settings, Research Institutions Application: Heart Failure, Hypertension, Atherosclerosis, Neurological Disorders Distribution Channel: Retail Pharmacies, Online Pharmacies, Hospital Pharmacies, Wholesalers |
| Companies Covered | Novartis AG, Bioprojet SCR, Pharmaleads SA, Theravance Biopharma, Cipla Ltd, Oceanic Pharmachem Pvt. Ltd, Regeneron Pharmaceuticals, Teva Pharmaceutical, Laurus Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Neprilysin Market Trends and Innovations
Biologic modalities are penetrating neprilysin-targeting pipelines, while regulatory convergence on real-world evidence standards compresses traditional randomized trial timelines.
Monoclonal antibodies engineered for neprilysin-resistant cleavage sites are expanding into late-stage heart failure populations previously non-responsive to small-molecule inhibition. Academic medical centers in Germany and Japan are piloting these agents in combination with SGLT2 inhibitors. This expansion is fragmenting the historical small-molecule dominance of the category.
EMA's centralized marketing authorization procedures now mandate cardiovascular outcome trials with composite endpoints including hospitalization reduction. Developers must integrate health technology assessment requirements from France's HAS and Germany's IQWiG into Phase III design. Fixed-dose combination sponsors face heightened evidentiary thresholds for incremental therapeutic benefit claims.
Hospital procurement committees are consolidating cardiovascular drug purchasing through integrated delivery networks, displacing individual physician preference in formulary decisions. GPOs in the United States now negotiate combination therapy bundles across entire health systems. This concentration is most visible in Medicare-dependent markets where adherence metrics directly impact quality bonus payments.
Anti-Neprilysin Market Segmentation
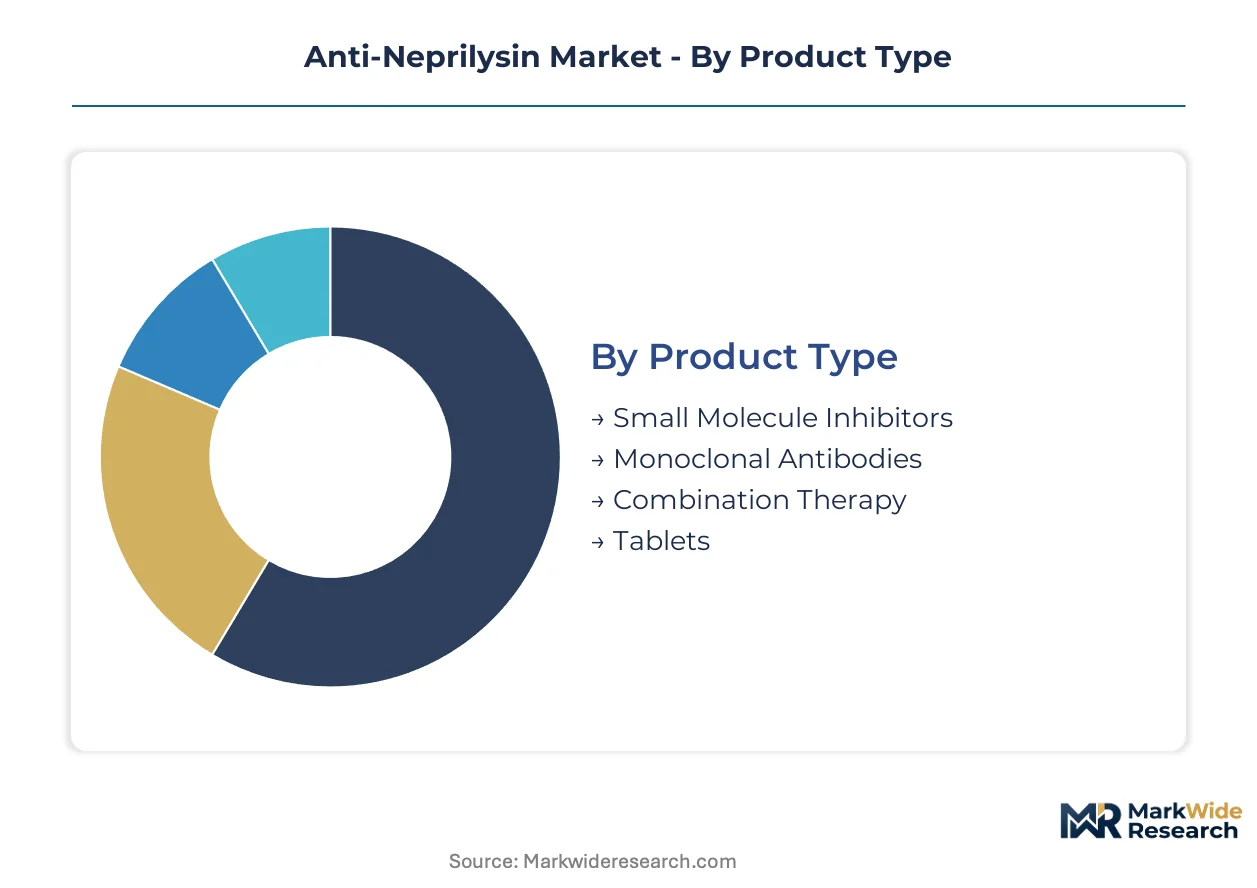
Anti-neprilysin developers structure their portfolios around distinct patient pathways, prescribing environments, and reimbursement mechanics. Segmentation choices directly determine which manufacturers capture formulary placement and which face commoditization pressure from generic substitution.
Product Type:
Upgrade cycles from standalone inhibitors to combination formats are compressing development timelines for single-mechanism candidates while extending patent protection for bundled regimens.
- Combination Therapy:Fixed-dose pairings of neprilysin inhibitors with angiotensin receptor blockers dominate hospital formularies through single-pill adherence advantages. Medicare Advantage quality bonus payments reward these formats in United States cardiology departments, entrenching incumbent manufacturers with established cardiovascular franchises.
- Small Molecule Inhibitors:Oral bioavailability and established manufacturing infrastructure make these the default for first-line heart failure protocols. Indian API producers control critical sacubitril intermediates, concentrating supply-side leverage among backward-integrated specialists.
- Monoclonal Antibodies:Engineered biologics targeting neprilysin-resistant cleavage sites are entering Phase II trials for late-stage populations. German and Japanese academic centers pilot these with SGLT2 inhibitors.
- Tablets:Immediate-release and extended-release oral solid dosage forms remain the standard for outpatient chronic disease management across retail and mail-order channels.
Volume placements concentrate in Combination Therapy; the faster expansion belongs to Monoclonal Antibodies.
End User:
Cost tier stratification separates acute intervention settings from maintenance therapy environments, with reimbursement intensity declining as care shifts toward lower-acuity venues.
- Hospitals:Integrated delivery networks and GPOs consolidate cardiovascular drug purchasing across entire health systems, displacing individual physician preference. CMS national coverage determinations favor evidence-based neprilysin inhibition regimens in inpatient and observation settings.
- Specialty Clinics:Tertiary care centers manage resistant hypertension populations through off-label utilization beyond original heart failure indications, generating higher per-patient revenue through complex case bundling.
- Homecare Settings:Post-discharge oral therapy administration is expanding with remote patient monitoring integration.
- Research Institutions:Academic medical centers conduct biomarker-guided screening protocol development and combination therapy pilot programs.
Revenue concentration sits with Hospitals; patient volume growth is shifting fastest toward Homecare Settings.
Application:
Diagnostic capture expansion is enlarging the addressable pool for neprilysin inhibition beyond its original regulatory indication into adjacent cardiovascular and renal pathways.
- Heart Failure:Reduced ejection fraction protocols represent the original commercial foundation, with biomarker-guided screening enlarging diagnostic capture. Cardiology departments are expanding combination therapy protocols for chronic management.
- Hypertension:Treatment-resistant populations in tertiary care centers drive off-label utilization, though payer scrutiny limits formal indication expansion.
- Atherosclerosis:Vascular anti-fibrotic signaling from natriuretic peptide potentiation is under investigation for plaque stabilization.
- Neurological Disorders:Preclinical exploration of neprilysin inhibition in amyloid clearance pathways remains early-stage with uncertain clinical translation.
Prescription volume clusters in Heart Failure; indication expansion is proceeding most rapidly in Hypertension.
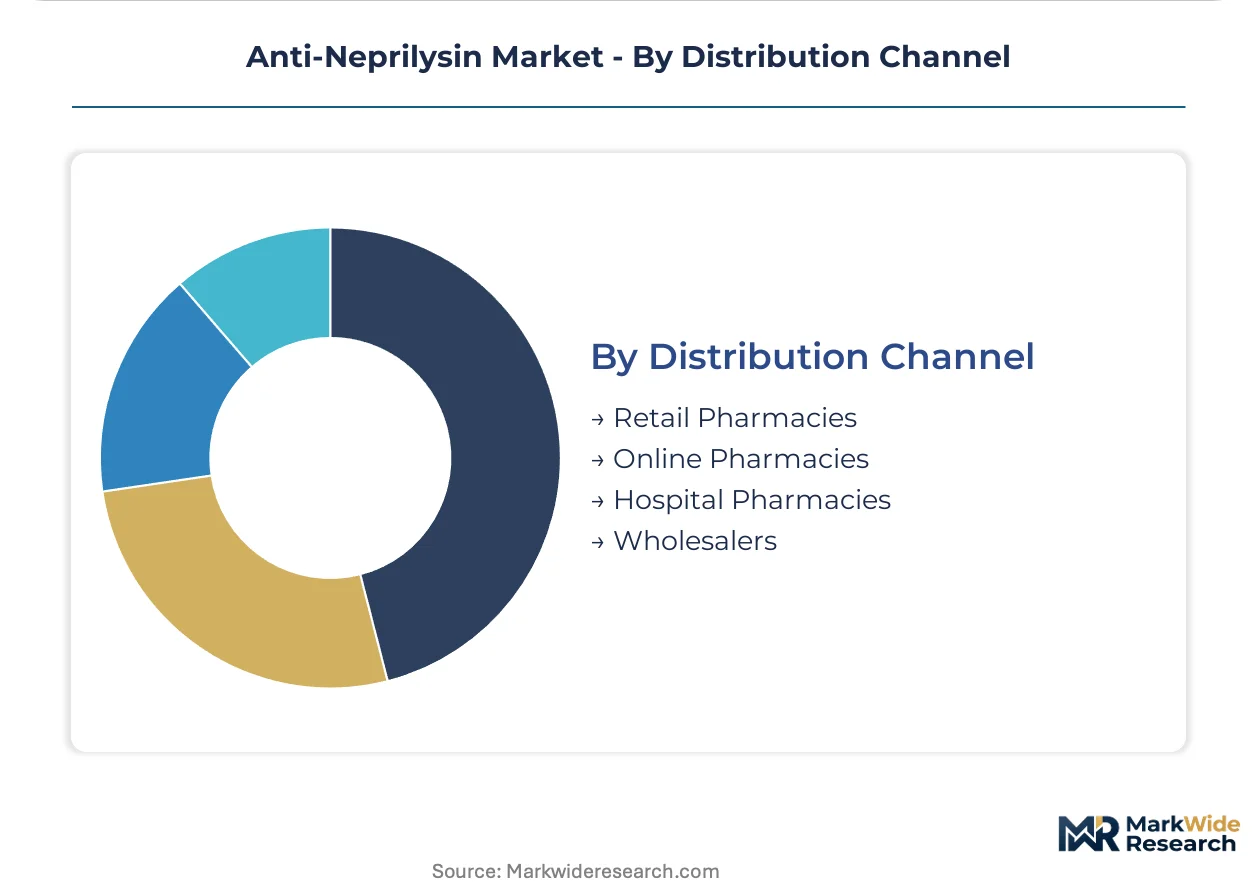
Distribution Channel:
Procurement consolidation through integrated networks is compressing margins for fragmented wholesale intermediaries while rewarding direct manufacturer contracting with large health systems.
- Hospital Pharmacies:Captive dispensing within integrated delivery networks ensures formulary compliance and adherence metric tracking for quality bonus payments. GPO-negotiated combination therapy bundles dominate procurement.
- Retail Pharmacies:Medicare Part D reimbursement structures and 90-day supply programs support maintenance therapy for stable outpatients.
- Online Pharmacies:Mail-order penetration is rising with remote patient monitoring and digital therapeutic integration for chronic disease management.
- Wholesalers:Three-tier distribution remains necessary for reaching fragmented independent pharmacies and rural access points.
Contracting power concentrates in Hospital Pharmacies; channel expansion is climbing fastest for Online Pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API synthesis concentrates in Indian chemical manufacturing corridors while consumption tilts toward United States cardiology departments and European hospital systems. Reimbursement policy divergence between Medicare Advantage quality bonuses and EMA health technology assessments shapes where value capture occurs.
United States
Medicare Advantage quality bonus payments reward single-pill adherence metrics, driving hospital formulary consolidation around fixed-dose combinations. FDA accelerated approval pathways compress cardiovascular trial timelines for developers targeting heart failure with reduced ejection fraction. The Cleveland Clinic and Mayo Clinic anchor biomarker-guided screening protocol development in the Midwest.
Germany
IQWiG evidentiary thresholds for incremental therapeutic benefit shape how combination therapy sponsors structure Phase III endpoints. EMA centralized marketing authorization procedures mandate composite outcome trials including hospitalization reduction. Academic medical centers in Berlin and Heidelberg pilot monoclonal antibody combinations with SGLT2 inhibitors.
India
Backward-integrated API manufacturers control critical sacubitril intermediates, concentrating supply-side leverage in Gujarat and Telangana. CDSCO bioequivalence requirements for generic fixed-dose combinations enable faster market entry for domestic producers. Laurus Labs anchors active pharmaceutical ingredient supply from its Hyderabad manufacturing base.
Japan
PMDA cardiovascular drug approval standards emphasize long-term outcome data for neprilysin inhibition regimens. METI industrial policy supports domestic biologic development pipelines targeting neprilysin-resistant pathways. Osaka-based research institutions collaborate with German centers on monoclonal antibody pilot programs.
Brazil
Treatment-resistant hypertensive populations in tertiary care centers drive off-label utilization beyond original heart failure indications. ANVISA accelerated pathways streamline bioequivalence requirements for fixed-dose combinations, enabling faster generic entry. São Paulo hospital networks consolidate cardiovascular drug purchasing through regional integrated delivery systems.
Anti-Neprilysin Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the anti-neprilysin market structure. Swiss and German pharmaceutical conglomerates leverage entrenched cardiovascular franchises to sustain leadership in patent-protected combination formats. Indian API specialists and generic manufacturers anchor the supply-side tier through manufacturing scale and backward integration. Competitive moves concentrate on portfolio diversification into adjacent renal indications and strategic partnerships for biologic co-development.
Within the diversified pharmaceutical tier, Novartis AG and Cipla Ltd occupy positions reflecting contrasting geographic and strategic emphases. Novartis exemplifies the patent-protected combination therapy archetype through its established cardiovascular franchise presence. Cipla represents the emerging market manufacturing scale model, with Laurus Labs anchoring the API supply specialization segment through its backward-integrated intermediate production.
| Leading Market Players |
|---|
| Novartis AG |
| Bioprojet SCR |
| Pharmaleads SA |
| Theravance Biopharma |
| Cipla Ltd |
| Oceanic Pharmachem Pvt. Ltd |
| Regeneron Pharmaceuticals |
| Teva Pharmaceutical |
| Laurus Labs |
| Others |
Pricing and Supply Chain Analysis
Backward integration into sacubitril intermediates anchors pricing power for Indian API manufacturers while compressing margins for non-integrated generic developers dependent on spot-market inputs. This structural asymmetry concentrates supply-side leverage in Gujarat and Telangana chemical corridors, where captive production of critical starting materials insulates incumbents from input volatility that fragments pricing coherence elsewhere.
Pricing Analysis
Cost-down pressure on small-molecule generics accelerates because REACH compliance burdens and EPA manufacturing discharge requirements add fixed cost layers that sub-scale producers cannot absorb. Pricing stratifies across patent-protected combination formats, bioequivalent fixed-dose bundles, and commodity standalone inhibitors, with Medicare Advantage quality bonus payments rewarding single-pill adherence in United States hospital systems. Brand premiums attach to FDA-approved fixed-dose combinations with demonstrated cardiovascular outcome benefits, while Indian generic manufacturers compete on manufacturing scale and backward-integrated cost structures. Hospital GPOs exhibit highest price sensitivity through consolidated procurement across integrated delivery networks, whereas specialty clinics managing resistant hypertension populations demonstrate lowest sensitivity due to complex case bundling revenue models.
Supply Chain Analysis
Freight cost volatility from Indian chemical manufacturing corridors to United States and European formulation sites compounds margin pressure for non-integrated developers lacking regional distribution hubs. Active pharmaceutical ingredient synthesis concentrates in India, China, and Switzerland, with sacubitril intermediates and valsartan starting materials drawing from specialized chemical manufacturing clusters. Single-source vulnerability pervades the intermediate tier where backward-integrated specialists control critical synthesis pathways, creating supply continuity exposure for generic developers without captive upstream capacity. Distribution runs through hospital pharmacy captive dispensing within integrated delivery networks, supplemented by three-tier wholesale channels reaching fragmented retail and mail-order access points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Monoclonal antibodies targeting neprilysin-resistant cleavage sites are displacing small-molecule inhibitors in late-stage heart failure populations, compressing the viable window for legacy therapeutic modalities and reshaping competitive positioning across the development pipeline.
For Market Incumbents: Extend patent protection through label expansion into chronic kidney disease adjacencies and diabetic nephropathy protocols, leveraging existing cardiovascular outcome data to satisfy EMA health technology assessment requirements. Fortify manufacturing scale in Indian API corridors through strategic partnerships with backward-integrated intermediate producers, insulating against single-source vulnerability that threatens generic substitution trajectories. Deepen formulary lock-in with United States hospital systems through adherence-metric guarantees that align with Medicare Advantage quality bonus payment structures. For New Entrants and Emerging Players: Hospital procurement committees represent the most penetrable channel archetype for biologic developers lacking established cardiovascular franchises, offering entry through outcome-based contracting pilots that reward adherence-improving formats. Brazil's ANVISA accelerated pathway and streamlined bioequivalence requirements enable faster generic fixed-dose combination entry for manufacturing-scale specialists. Academic medical center partnerships in Germany and Japan provide clinical validation platforms for monoclonal antibody combinations with SGLT2 inhibitors, establishing prescriber familiarity ahead of commercial scale-up. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified pharmaceutical conglomerates seeking cardiovascular pipeline diversification, with valuation premiums attaching to Phase II biologic assets demonstrating neprilysin-resistant mechanism differentiation. Long-term viability over the projection horizon hinges on successful navigation of EMA centralized marketing authorization procedures and FDA accelerated approval pathway execution for combination formats. Monitor CMS national coverage determination convergence with parallel EMA health technology assessments as the decisive inflection signal for reimbursement-supported volume expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | EMA-mandated composite endpoint trials with hospitalization reduction reshape Phase III design requirements. |
| Regulatory Approval Pathway | FDA accelerated approval compresses cardiovascular trial timelines for heart failure with reduced ejection fraction candidates. |
| Manufacturing Scale-Up | Backward integration into sacubitril intermediates concentrates supply-side leverage in Indian chemical corridors. |
| Pipeline Diversification | Chronic kidney disease adjacency expansion creates parallel indication development beyond original heart failure foundations. |
| Strategic Partnership | SGLT2 inhibitor co-development alliances with academic medical centers in Germany and Japan accelerate biologic validation. |
Research Methodology
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone for therapeutic pipeline mapping and regulatory pathway analysis. Primary interviews with drug development executives, formulary directors at United States hospital systems, payer access specialists, and regulatory affairs leads validated commercial assumptions and reimbursement dynamics. Bottom-up patient volume estimates across heart failure with reduced ejection fraction and resistant hypertension populations triangulated with top-down market size assessments derived from Medicare claims data and hospital procurement database analysis.
Bottom-up modeling anchored volume projections across product type segments including combination therapy, small molecule inhibitors, and monoclonal antibodies, while top-down cross-checks incorporated EMA health technology assessment convergence patterns and CMS national coverage determination timelines. CAGRs were derived from segmented growth rate analysis applied across the projection horizon, with treatment line stratification, dosage form differentiation, and regional regulatory clustering as core segmentation dimensions. Forecast inputs incorporated biomarker-guided screening protocol expansion rates and SGLT2 inhibitor combination pilot program enrollment trajectories from German and Japanese academic centers.
Caveats apply where EMA evidentiary threshold elevation, biologic substitution acceleration, or API supply disruption could materially shift the outlook for small-molecule inhibitor viability. Forecasts reflect assumptions about reimbursement policy stability and regulatory pathway execution timelines that carry inherent uncertainty given evolving health technology assessment standards. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Antibody Discovery Market
Biopharmaceuticals
Peptide Antibiotics Market
Biopharmaceuticals
Global Antibody Market
Biopharmaceuticals
North America Plasma Fractionation Market
Biopharmaceuticals
Levofloxacin Cyclized Ester Market
Biopharmaceuticals
Global Blood Product Market
Biopharmaceuticals
Global Argatroban Market
Biopharmaceuticals
Non-Receptor Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
Europe Insulin Pens Market
Biopharmaceuticals
Generic Injectables Market
Biopharmaceuticals
Peptide Drug Conjugates Market
Biopharmaceuticals
Combination Antibody Therapy Market
Biopharmaceuticals
Theranostics Market
Biopharmaceuticals
South Korea Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Seasonal Influenza Vaccine Market
Biopharmaceuticals
Insulin API Market