
 Asia-Pacific Plant-Based Biologics Market | 2026-2036
Asia-Pacific Plant-Based Biologics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Plant-Based Biologics Market Analytics
Oncology and immunology applications are restructuring the end-use profile of Asia-Pacific plant-based biologics, pulling capacity away from agricultural extension toward higher-margin therapeutics. Samsung BioLogics anchors contract manufacturing scale in South Korea, leveraging mammalian and plant-based hybrid platforms to serve multinational clients. Innovent Biologics specializes in antibody development for oncology, competing aggressively against imported reference products in Chinese hospitals. Biocon sustains cost leadership through in-house fermentation technology and backward integration into recombinant protein expression.
Asia-Pacific plant-based biologics comprise pharmaceutical proteins, including monoclonal antibodies, vaccines, and enzymes, produced through recombinant DNA technology in plant expression systems such as Nicotiana benthamiana or rice cell cultures. These products deliver therapeutic or diagnostic activity with reduced risk of mammalian pathogen contamination and lower upstream carbon intensity compared with traditional CHO-cell manufacturing. Antibodies command the largest revenue share among product types, reflecting oncology demand and the maturity of plant glycoengineering protocols that enable human-compatible glycosylation patterns. Vaccines represent the fastest-growing product category, driven by pandemic preparedness investments and the scalability of transient expression in leafy biomass. Fermentation technology dominates the technology landscape for stable cell-line production, while plant tissue culture retains niche applications for high-value metabolites and specialized research reagents.
China's NMPA and India's CDSCO enforce divergent approval pathways for plant-made pharmaceuticals, creating compliance complexity for sponsors pursuing multi-country trials in the region. South Korea's MFDS has streamlined biosimilar guidelines that indirectly accelerate plant-based platform validation for cost-sensitive antibody copies. The EU Green Deal's carbon-border adjustment mechanisms and REACH-derived substance standards are beginning to influence procurement criteria for export-oriented manufacturers in the Asia-Pacific zone. Stakeholders must monitor how regulator convergence on glycosylation comparability protocols reshapes platform selection decisions across the development pipeline.
Market Dynamics
Oncology and immunology applications are restructuring the end-use profile of Asia-Pacific plant-based biologics, pulling capacity away from agricultural extension toward higher-margin therapeutics. Samsung BioLogics anchors contract manufacturing scale in South Korea, leveraging mammalian and plant-based hybrid platforms to serve multinational clients.
Growth Catalysts
- India's PLI scheme:The production-linked incentive framework for biopharmaceutical manufacturing subsidizes fermentation-based plant expression systems, attracting greenfield investment into recombinant protein facilities.
- China's dual carbon goals:National decarbonization mandates favor low-carbon bioprocessing platforms, directing state-backed capital toward plant-based expression systems with reduced upstream energy intensity versus CHO-cell alternatives.
- Transient expression scalability:Leafy biomass platforms enable rapid vaccine surge capacity, addressing pandemic preparedness requirements across national health security frameworks.
Market Restraints
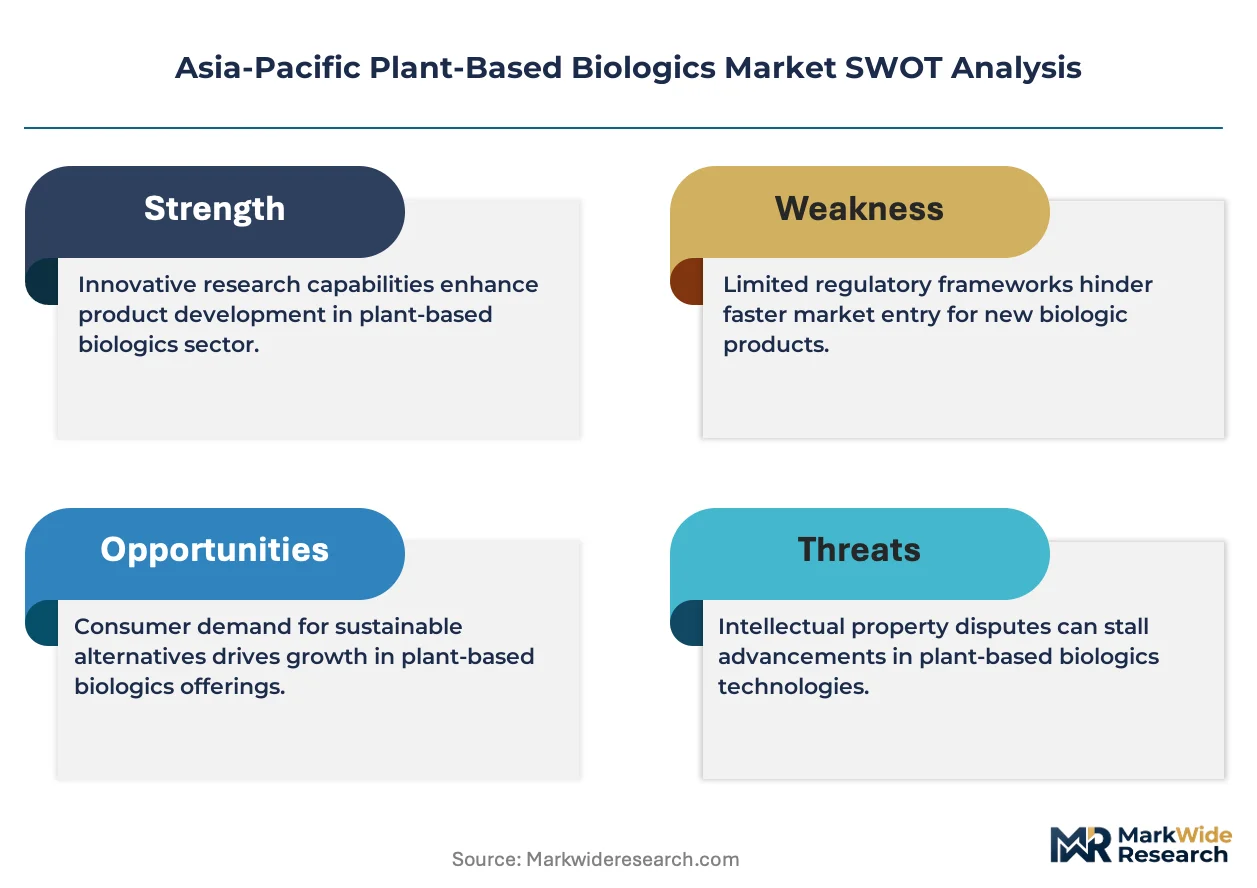
- Glycoengineering complexity:Plant-specific glycosylation patterns require extensive humanization protocols, extending development timelines and elevating technical risk for antibody candidates.
- Regulatory divergence:China's NMPA and India's CDSCO enforce non-harmonized approval pathways for plant-made pharmaceuticals, multiplying compliance burden for multi-country trial sponsors.
- Mammalian platform inertia:Established CHO-cell infrastructure at incumbent contract manufacturers creates switching costs that slow plant-based platform adoption for late-stage assets.
Strategic Opportunities
- Southeast Asia greenfield capacity:Vietnam and Indonesia present underdeveloped biologics manufacturing bases where plant-based platforms can bypass legacy mammalian infrastructure investments.
- EU carbon-border alignment:The EU Green Deal's carbon-border adjustment mechanisms create competitive advantage for Asia-Pacific exporters with verified low-carbon bioprocessing credentials.
- Glycoengineering-as-a-service:Specialized providers offering human-compatible glycosylation modification for Nicotiana benthamiana systems can capture value from platform-agnostic developers.
Industry Challenges
- Comparability protocol standardization:Regulator convergence on glycosylation comparability benchmarks remains incomplete, forcing sponsors to maintain multiple analytical packages for different agencies.
- Downstream processing bottlenecks:Extraction and purification of pharmaceutical proteins from plant biomass requires specialized equipment with limited vendor availability, constraining scale-up velocity.
- Platform talent scarcity:Cross-disciplinary expertise spanning plant molecular biology and GMP biomanufacturing concentrates at a handful of academic and industrial clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Plant-Based Biologics Market |
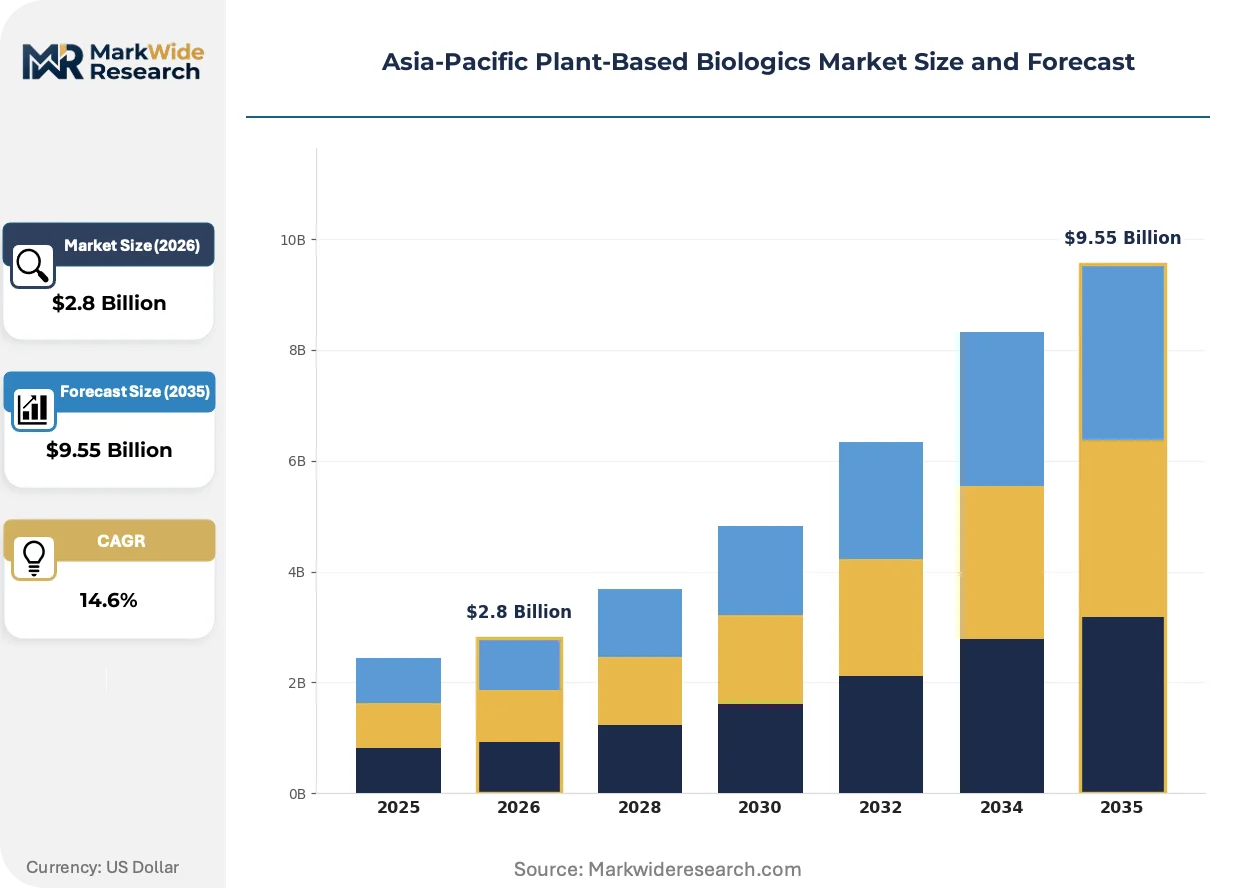
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibodies, Vaccines, enzymes, Hormones End User: Pharmaceutical Companies, Biopharmaceutical Firms, Research Institutions, Contract Manufacturers Application: Therapeutics, Diagnostics, Research, Agricultural Extension Technology: Recombinant DNA, Fermentation Technology, Extraction Techniques, Plant Tissue Culture |
| Companies Covered | Roche Holding AG, Amgen Inc, Johnson & Johnson, AbbVie Inc, Biocon, Samsung BioLogics, Innovent Biologics, Celltrion Healthcare, Bharat Biotech, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Plant-Based Biologics Market Evolving Landscape
Technology convergence between plant molecular farming and precision glycoengineering is compressing development timelines for complex biologics. Regulatory frameworks across the region are adapting to accommodate novel expression platforms while maintaining safety standards.
Transient expression systems using Nicotiana benthamiana are modularizing vaccine manufacturing workflows. National immunization programs in South Korea and Australia are adopting these platforms for rapid-response stockpiling. This modularization is collapsing the traditional 12-18 month vaccine production window into 6-8 week cycles, reshaping pandemic preparedness procurement.
South Korea's MFDS has streamlined biosimilar guidelines that indirectly accelerate plant-based platform validation for cost-sensitive antibody copies. The regulatory clarity reduces uncertainty for sponsors pursuing hybrid mammalian-plant manufacturing strategies. Contract manufacturers serving multinational clients are responding by qualifying plant-based capacity alongside traditional CHO-cell lines.
Hospital procurement in China is rotating toward domestically manufactured biologics with documented carbon intensity credentials. Innovent Biologics and similar developers are capturing share from imported reference products by combining cost position with sustainability disclosures. This preference shift is most visible in tier-one urban hospital networks where centralized purchasing incorporates environmental impact scoring.
Asia-Pacific Plant-Based Biologics Market Segmentation
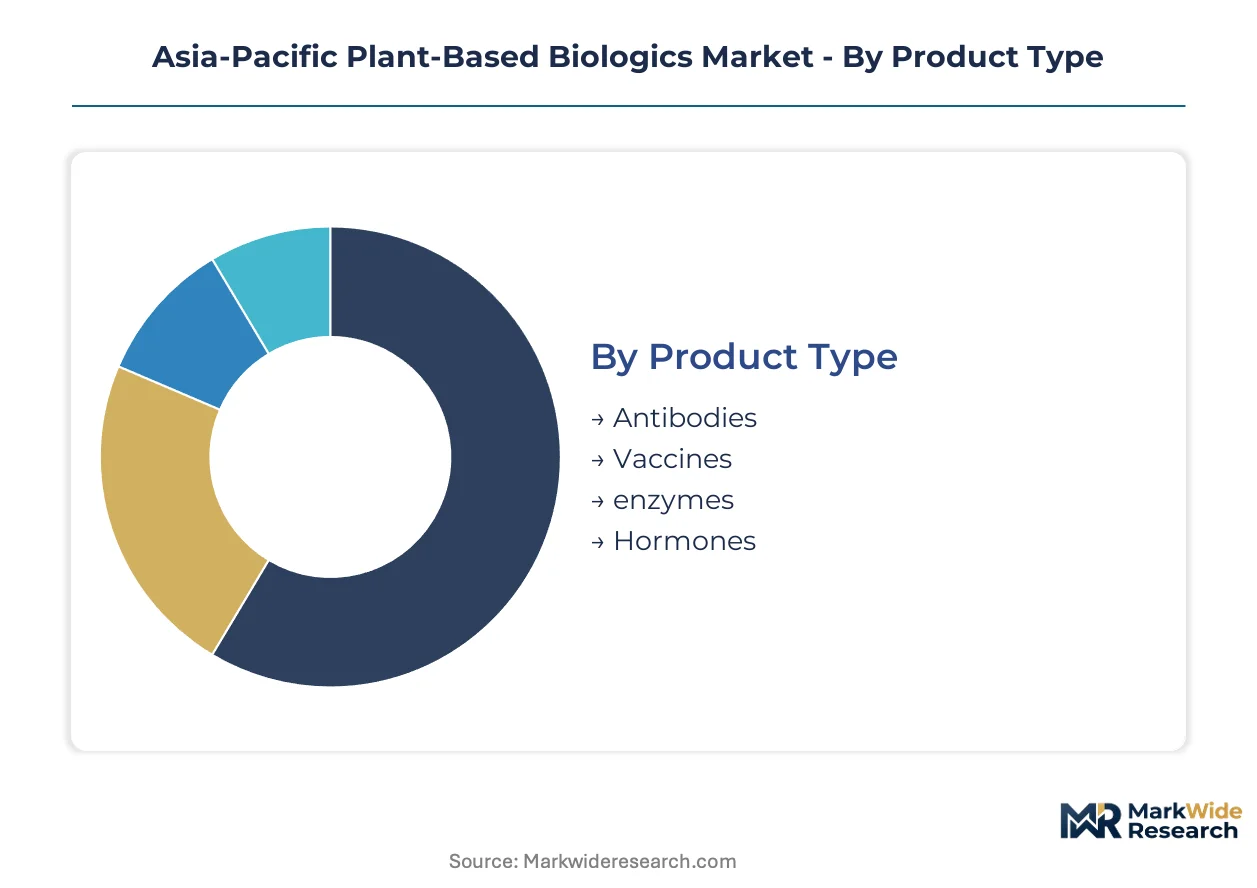
Segmentation reveals where capital deployment concentrates across Asia-Pacific plant-based biologics. Platform selection, end-user procurement patterns, and regulatory pathways diverge sharply by category, reshaping investment priorities for fermentation infrastructure and glycoengineering capabilities.
Product Type:
Antibodies demand the heaviest upstream investment in humanized glycosylation infrastructure, while vaccines require surge-capacity bioreactors for transient expression workflows.
- Antibodies:Monoclonal antibodies produced in Nicotiana benthamiana or rice cell cultures require extensive glycoengineering to eliminate plant-specific β-1,2-xylose and α-1,3-fucose residues. South Korean contract manufacturers anchor regional capacity for oncology and immunology applications, driven by MFDS biosimilar guidelines that validate plant-based platform comparability.
- Vaccines:Transient expression in leafy biomass enables rapid antigen production without stable cell-line development. Australia's national immunization programs and pandemic preparedness frameworks in South Korea are scaling procurement of plant-made vaccines, compressing traditional production timelines through modular manufacturing workflows.
- Enzymes:Industrial and therapeutic enzymes leverage lower glycosylation complexity, reducing purification burden for manufacturers targeting cost-sensitive diagnostic applications.
- Hormones:Recombinant protein hormones require precise folding environments, limiting commercial deployment to specialized fermentation facilities with advanced downstream processing capabilities.
Most installed capacity flows through Antibodies. Expansion is steepest in Vaccines.
End User:
Procurement scale and technical sophistication vary dramatically across customer types, with pharmaceutical companies commanding multi-ton fermentation runs while research institutions drive platform innovation.
- Pharmaceutical Companies:Multinational sponsors source plant-based biologics for pipeline assets requiring reduced mammalian pathogen risk, particularly for oncology antibodies entering Phase III trials across China and India.
- Biopharmaceutical Firms:Mid-sized developers in South Korea and Australia prioritize hybrid mammalian-plant manufacturing strategies to balance speed with regulatory familiarity, capturing share in cost-sensitive biosimilar segments.
- Research Institutions:Academic centers in Singapore and Japan advance glycoengineering protocols and transient expression optimization, transferring intellectual property to commercial partners through technology licensing arrangements.
- Contract Manufacturers:CDMOs with qualified plant-based capacity serve clients seeking carbon-intensity disclosures for EU export compliance, leveraging South Korea's established biologics infrastructure.
Contract Manufacturers aggregate the largest order volumes. Research Institutions are expanding procurement most quickly for platform development partnerships.
Application:
Therapeutic applications command premium pricing and stringent GMP compliance, while agricultural extension competes on volume with lower margin structures.
- Therapeutics:Oncology and immunology indications dominate revenue concentration, with plant-made antibodies displacing imported reference products in Chinese hospital procurement networks that weight carbon intensity scoring.
- Diagnostics:Enzyme and antibody reagents for immunoassays benefit from plant-based production's reduced batch-to-batch variability and absence of mammalian virus contamination risk.
- Research:High-value metabolites and specialized reagents sustain niche demand from pharmaceutical discovery programs requiring complex glycoproteins with defined glycoforms.
- Agricultural Extension:Veterinary vaccines and growth hormones face margin pressure from traditional microbial fermentation, limiting plant-based penetration outside pandemic surge scenarios.
Therapeutics captures the dominant revenue share. Diagnostics is climbing the fastest as quality-sensitive IVD manufacturers diversify supply sources.
Technology:
Fermentation infrastructure represents the largest capital commitment, while extraction techniques constrain scale-up velocity through specialized equipment scarcity.
- Recombinant DNA:Gene insertion and expression vector design underpin all commercial production, with India's PLI scheme subsidizing greenfield facility construction for stable transgenic lines.
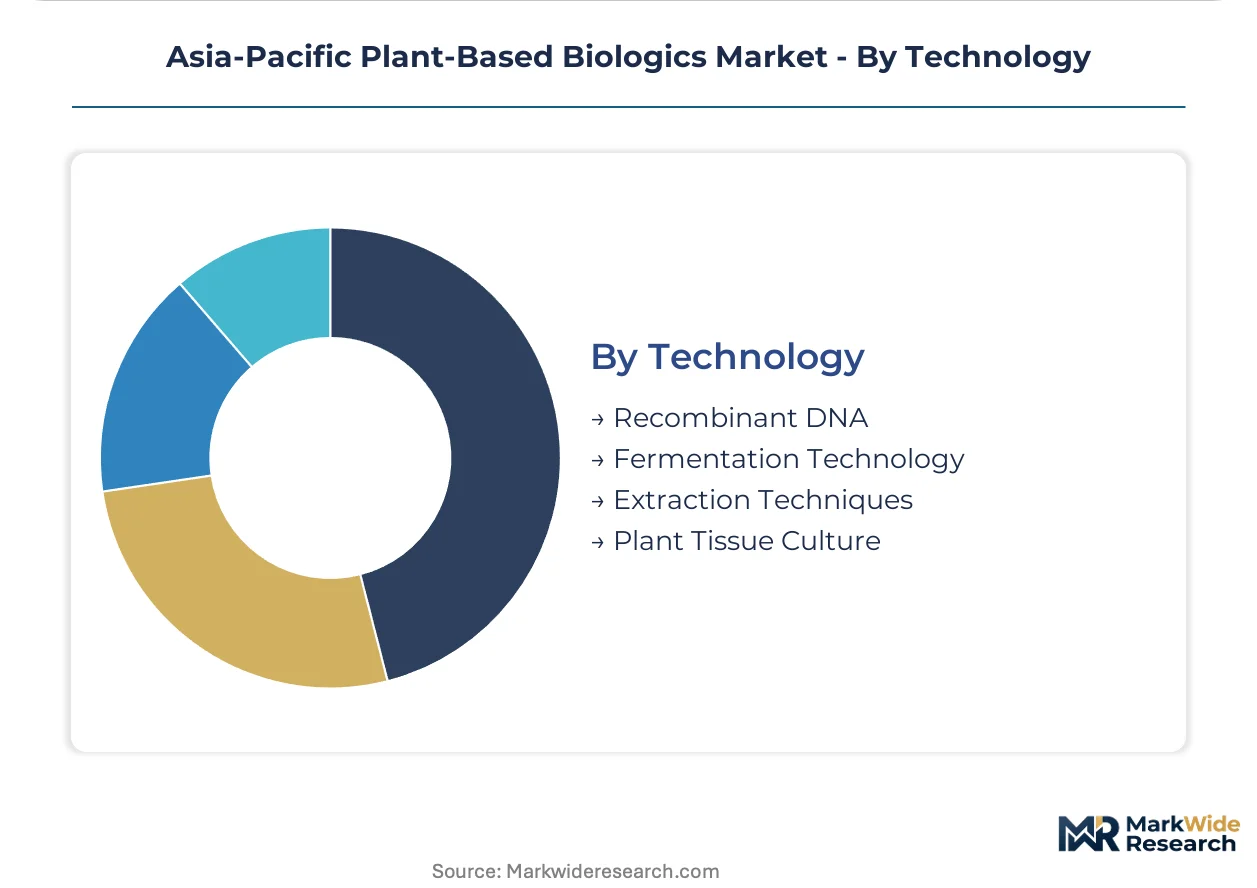
- Fermentation Technology:Bioreactor-based production of rice cell cultures and other plant suspension systems delivers consistent titers for antibodies requiring human-compatible glycosylation, anchoring capacity investment in South Korea and China.
- Extraction Techniques:Protein recovery from leafy biomass demands proprietary downstream processing equipment with limited vendor availability, creating bottlenecks for transient expression scale-up.
- Plant Tissue Culture:Specialized applications for high-value metabolites and research reagents retain niche positioning, concentrated in Japanese and Singaporean academic-industrial clusters.
Fermentation Technology hosts the majority of qualified GMP capacity. Extraction Techniques is gaining investment most rapidly as transient expression volumes expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting plant-based biologics investment toward jurisdictions where carbon-intensity compliance costs diverge sharply from traditional mammalian manufacturing. The Asia-Pacific region captures this migration through state-backed incentive schemes and streamlined biosimilar pathways.
China
Oncology antibody demand and hospital procurement carbon-scoring are accelerating plant-based platform validation. The NMPA's evolving technical guidelines for novel expression systems create compliance clarity for domestic sponsors. Yangtze River Delta bioclusters host the majority of qualified fermentation capacity for recombinant protein production.
India
Cost-sensitive biosimilar manufacturing and export-oriented CDMO growth are concentrating investment in fermentation infrastructure. The PLI scheme subsidizes greenfield recombinant protein facilities with reduced energy intensity versus CHO-cell alternatives. Karnataka and Telangana anchor the largest captive fermentation clusters for antibody production.
South Korea
Contract manufacturing scale and multinational client demand for carbon-disclosed supply chains dominate capacity expansion. The MFDS biosimilar guidelines validate plant-based platform comparability, reducing regulatory uncertainty for hybrid manufacturing strategies. Seoul Capital Area facilities qualify plant-based capacity alongside traditional mammalian lines.
Australia
National immunization programs and pandemic preparedness frameworks are scaling procurement of transient expression vaccines. The TGA's adaptive licensing pathways accommodate modular manufacturing workflows for rapid antigen production. Melbourne and Sydney academic-industrial clusters advance glycoengineering protocols for human-compatible glycosylation.
Singapore
Research institution partnerships and technology licensing activity concentrate platform innovation for commercial transfer. The national biomedical regulator enforces GMP standards that align with EU import requirements for carbon-border compliance. One-North and Tuas bioparks host specialized plant tissue culture facilities for high-value metabolite production.
Asia-Pacific Plant-Based Biologics Market Competitive Landscape
Capacity expansion dominates the current landscape as contract manufacturers qualify plant-based lines to capture carbon-disclosed procurement contracts. The market structures around three tiers: multinational biopharmaceuticals with hybrid platform portfolios, regional CDMOs scaling fermentation infrastructure, and domestic developers competing on biosimilar cost position. Strategic archetypes include platform-agnostic integrators, glycoengineering specialists, and state-backed national champions. Competitive intensity concentrates on manufacturing scale-up velocity and regulatory qualification speed rather than proprietary molecule ownership.
Among Asia-Pacific-based developers, Biocon exemplifies backward-integrated cost leadership through captive fermentation technology and recombinant protein expression capabilities. Samsung BioLogics anchors contract manufacturing scale with qualified capacity serving multinational clients seeking carbon-intensity disclosures. Innovent Biologics occupies a position within the domestic oncology antibody segment where hospital procurement preferences favor locally manufactured products with documented sustainability credentials.
| Leading Market Players |
|---|
| Roche Holding AG |
| Amgen Inc |
| Johnson & Johnson |
| AbbVie Inc |
| Biocon |
| Samsung BioLogics |
| Innovent Biologics |
| Celltrion Healthcare |
| Bharat Biotech |
| Others |
Value Network & Pricing Analysis
Cross-disciplinary GMP biomanufacturing talent clustering in South Korea's Seoul Capital Area widens labor-cost differentials against emerging Vietnamese greenfield sites, compressing pricing-tier spreads between premium mammalian-plant hybrid platforms and economy transient-expression vaccines.
Pricing Analysis
Direct-to-OEM contract manufacturing discounts dominate antibody procurement, while distributor markups persist for diagnostic enzyme reagents. Three-tier pricing structure across premium, standard, and economy levels separates MFDS-validated biosimilar platforms from research-grade materials and pandemic surge vaccine stockpiles. Pricing pressure stems from CDSCO and NMPA regulatory divergence multiplying compliance costs for multi-country sponsors. Hospital procurement networks in Chinese tier-one cities exhibit lowest price sensitivity due to carbon-intensity scoring preferences, while agricultural extension applications face acute cost compression from microbial fermentation substitutes.
Supply Chain Analysis
Specialized downstream extraction equipment supply rests on German and Japanese precision engineering producers, with fermentation bioreactor fabrication concentrated in South Korea and China. Nicotiana benthamiana seed stocks, recombinant protein chromatography resins, and GMP-grade culture media constitute critical input dependencies. Single-source vulnerability runs through proprietary glycoengineering enzyme suppliers for human-compatible glycosylation modification. Distribution runs through qualified CDMO networks serving multinational pharmaceutical sponsors with carbon-disclosure requirements for EU export compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific plant-based biologics market functions as a geographic-arbitrage play where India's PLI scheme subsidies and South Korea's MFDS regulatory clarity extract cost advantages against China's NMPA compliance burden and Australia's higher labor inputs.
For Market Incumbents: Deploy glycoengineering-as-a-service capabilities to capture value from platform-agnostic developers facing humanization protocol complexity. Anchor capacity expansion in Vietnam and Indonesia to bypass legacy mammalian infrastructure switching costs and preempt emerging entrant land-grabs. Secure dual NMPA-CDSCO regulatory qualification packages to defend against compliance fragmentation threatening multi-country trial economics. For New Entrants and Emerging Players: Transient expression modularization for pandemic preparedness vaccines offers the most penetrable wedge against established CHO-cell infrastructure. Target Australian national immunization program procurement and Southeast Asian greenfield hospital networks where carbon-intensity credentials outweigh brand legacy. Pursue technology licensing from Singaporean academic clusters to accelerate GMP qualification timelines without captive R&D investment. For Investors and Strategic Acquirers: Mid-cap biopharmaceuticals with hybrid mammalian-plant platform portfolios are the most active acquirer in this space, seeking carbon-disclosed manufacturing capacity for EU export positioning. Acquisition target archetypes include specialized glycoengineering service providers and qualified CDMOs with MFDS-validated plant-based lines. Watch NMPA technical guideline convergence with MFDS biosimilar protocols as the inflection indicator for regulatory arbitrage compression.| Strategic Initiative | Industry Significance |
|---|---|
| Glycoengineering-as-a-Service Launch | Captures value from developers lacking human-compatible glycosylation modification capabilities for Nicotiana benthamiana systems. |
| Southeast Asia Greenfield Capacity Buildout | Positions plant-based platforms to bypass legacy mammalian infrastructure investments in Vietnam and Indonesia bioclusters. |
| Dual NMPA-MFDS Regulatory Qualification | Reduces compliance burden for sponsors pursuing multi-country oncology antibody trials across China and South Korea. |
| Transient Expression Modularization | Collapses vaccine production timelines for Australian and South Korean pandemic preparedness procurement frameworks. |
| Carbon-Intensity Certification Program | Aligns manufacturing disclosures with EU Green Deal border adjustment mechanisms for export-oriented Asia-Pacific producers. |
Research Methodology
Multiple input streams — primary interviews with fermentation technology directors, regulatory affairs leads at CDMOs, and hospital procurement managers; secondary validation against MFDS biosimilar guidelines, NMPA technical standards, and CDSCO approval databases; plus customs records for bioprocessing equipment imports — were reconciled through bottom-up capacity modeling and top-down demand triangulation.
Data-stream reconciliation across the projection horizon applied treatment-line segmentation for oncology versus immunology applications, technology-tier differentiation between stable fermentation and transient expression platforms, and regional regulatory cluster grouping by NMPA, MFDS, and CDSCO jurisdiction. CAGRs were derived from installed capacity expansion trajectories and sponsor pipeline advancement rates, with carbon-intensity scoring adoption curves and pandemic preparedness procurement cycles as industry-specific forecast inputs.
The model holds under sustained PLI scheme subsidy continuity and MFDS guideline stability; deviation in NMPA technical standard acceleration or EU carbon-border enforcement intensity would shift capacity investment geography. Forecasts reflect these base-condition assumptions with acknowledged sensitivity to glycoengineering protocol standardization timelines and downstream extraction equipment vendor concentration. A small set of named triggers — regulator convergence benchmarks, CDMO qualification velocity, and carbon-border implementation scope — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Fenbendazole Market
Biopharmaceuticals
Antibiotics Market
Biopharmaceuticals
Levofloxacin Cyclized Ester Market
Biopharmaceuticals
North America Diabetes Drugs Market
Biopharmaceuticals
Global Kinase Inhibitors Market
Biopharmaceuticals
Mammalian Polyclonal Igg Antibody Market
Biopharmaceuticals
Triclabendazole Market
Biopharmaceuticals
Conjugated Estrogen Market
Biopharmaceuticals
Protein Kinase B Inhibitors Market
Biopharmaceuticals
Biologic Response Modifiers Market
Biopharmaceuticals
China Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Asia-Pacific Insulin Pens Market
Biopharmaceuticals
Global Upstream Bioprocessing Market
Biopharmaceuticals
Ocular Tuberculosis Therapeutics Market
Biopharmaceuticals
Bio-Active Peptides Market
Biopharmaceuticals
Oseltamivir Market