
 IT Monitoring Tools Market | 2026-2036
IT Monitoring Tools Market Size, Share, and Industry Trends Forecast 2026-2036
IT Monitoring Tools Market Outlook
The EU Digital Operational Resilience Act is repositioning how European financial institutions procure monitoring infrastructure, forcing real-time observability into core compliance budgets. Microsoft Corporation leverages its Azure-native monitoring stack to anchor enterprise deployments across regulated industries. Datadog Inc. specializes in cloud application performance management, competing aggressively for multi-cloud enterprise accounts. SolarWinds Worldwide sustains its installed base through deep on-premises network monitoring capabilities.
IT monitoring tools encompass software platforms that collect, analyze, and visualize telemetry from distributed computing infrastructure, typically processing metrics, logs, and traces at millisecond granularity to ensure service reliability. These systems serve the primary commercial purpose of minimizing mean time to detection and mean time to resolution for technology-dependent operations. Cloud-based deployment is capturing the fastest expansion as enterprises migrate from capital-intensive data center commitments to consumption-based observability pricing. Infrastructure monitoring within the feature dimension commands the largest existing spend, while AI-powered technology is displacing rule-based alerting as the primary growth vector for vendor R&D investment.
The European Banking Authority, the US Securities and Exchange Commission, and the UK Prudential Regulation Authority each enforce operational resilience reporting that mandates demonstrable technology monitoring coverage. These frameworks shape demand by specifying minimum recovery time objectives that only advanced observability platforms can consistently satisfy. Stakeholders must weigh vendor consolidation risk against the interoperability requirements emerging from cross-border regulatory divergence.
Market Dynamics
Observability platforms are compressing three historically separate software categories—metrics aggregation, log management, and distributed tracing—into unified telemetry fabrics. This convergence is forcing vendors to rebuild architecture around open standards or risk displacement by cloud-native alternatives.
Growth Catalysts
- EU Digital Operational Resilience Act:Frankfurt's banking cluster now mandates real-time infrastructure monitoring with demonstrable recovery time objectives, embedding observability spend into core compliance budgets.
- Cloud migration acceleration:Enterprises are abandoning capital-intensive data center commitments for consumption-based pricing models that scale telemetry ingestion dynamically.
- AI-powered anomaly detection:Machine learning models trained on historical incident data are displacing static threshold alerting, reducing mean time to detection for critical failures.
Market Restraints
- Data egress cost volatility:Cloud provider bandwidth pricing creates unpredictable cost spikes for high-volume telemetry pipelines, particularly for hybrid deployments.
- Vendor lock-in concentration:Proprietary query languages and storage formats from dominant cloud platforms create switching friction that constrains buyer negotiation leverage.
- Legacy instrumentation gaps:Mainframe and industrial control systems lack native OpenTelemetry support, creating coverage blind spots in heterogeneous environments.
Strategic Opportunities
- Edge computing observability:Manufacturing and energy sectors deploying distributed IoT sensors require lightweight agents capable of local preprocessing before cloud transmission.
- FinOps integration:Cloud cost optimization platforms are converging with monitoring tools to correlate infrastructure spend with application performance metrics.
- Sustainability telemetry:CSRD mandates in Europe are creating demand for carbon-aware monitoring that tracks workload energy consumption alongside traditional reliability signals.
Industry Challenges
- Site reliability engineering talent scarcity:Organizations struggle to hire engineers capable of operating complex observability stacks and interpreting distributed trace data.
- Multi-cloud instrumentation complexity:Each major cloud provider exposes proprietary APIs and metrics schemas, forcing buyers to maintain parallel integration codebases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IT Monitoring Tools Market |
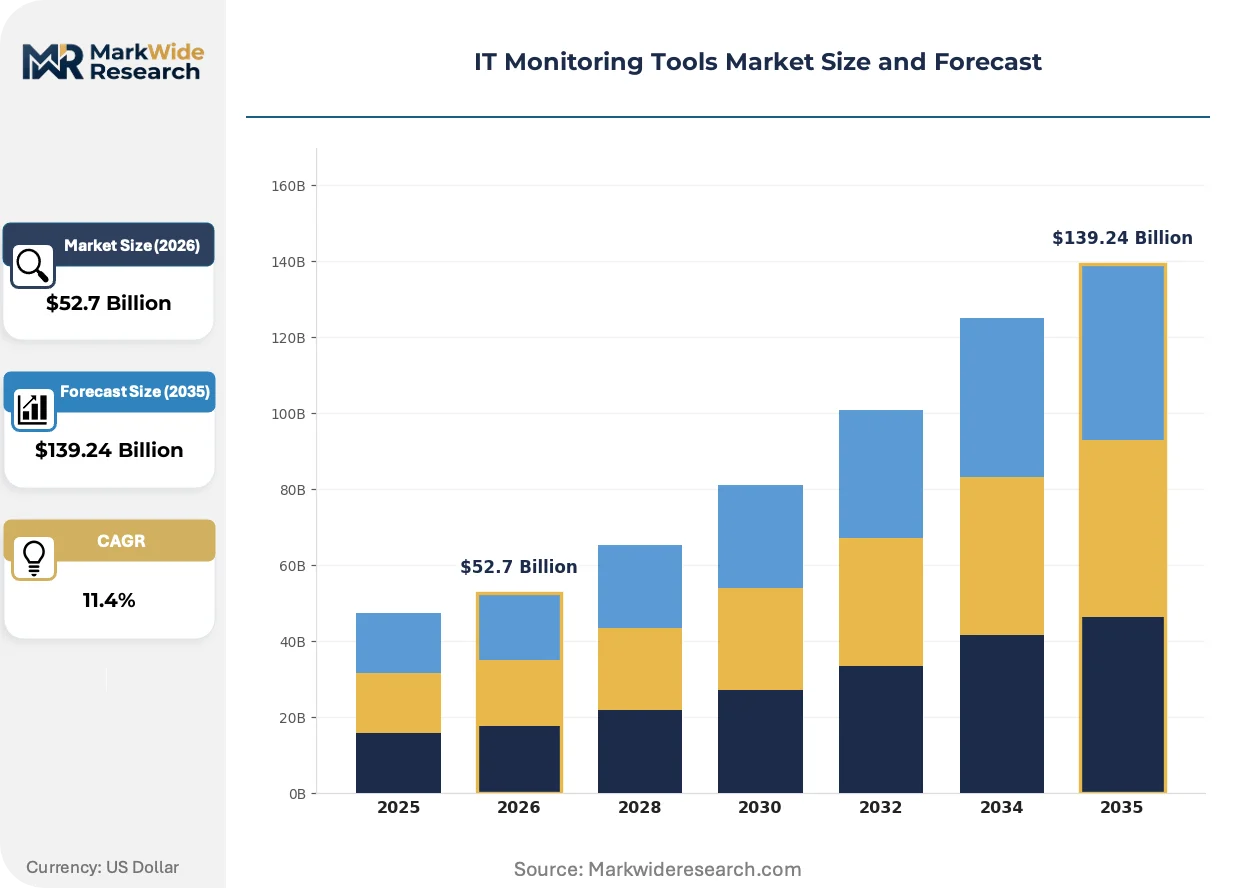
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $139.24 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: IT Departments, Managed Service Providers, Enterprises, Startups Feature: Network Monitoring, Application Performance, Log Management, Infrastructure Monitoring Technology: Open Source, Proprietary, AI-Powered, Hybrid Solutions |
| Companies Covered | Microsoft Corporation, Amazon Web Services, Inc., Cisco Systems, Inc., Dynatrace LLC, Datadog Inc., Splunk Inc., SolarWinds Worldwide, Google LLC, NetScout Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IT Monitoring Tools Market Strategic Shifts
OpenTelemetry is emerging as the dominant instrumentation standard, collapsing vendor-specific agent sprawl into a single telemetry pipeline. This standardization is redrawing competitive boundaries around data platform capabilities rather than collection mechanics.
Observability pipelines built on OpenTelemetry is consolidating telemetry collection across previously siloed monitoring, logging, and tracing systems. Financial services firms in Frankfurt and Singapore are deploying these unified pipelines at production scale. The technology is consolidating vendor market positions around backend query performance and storage economics rather than agent distribution.
The EU AI Act introduces risk classification requirements for automated decision systems that process infrastructure alerts. Deployments in regulated industries must now maintain explainability logs for anomaly detection models. Banking infrastructure teams are responding by demanding observability vendors provide model lineage documentation alongside traditional system telemetry.
Consumption-based pricing is displacing seat-based licensing as the dominant procurement model for enterprise observability. Platform engineering teams now negotiate contracts indexed to monthly active service instances rather than named user counts. This shift is most visible among technology companies with ephemeral container workloads that fluctuate dramatically in scale.
IT Monitoring Tools Market Segmentation
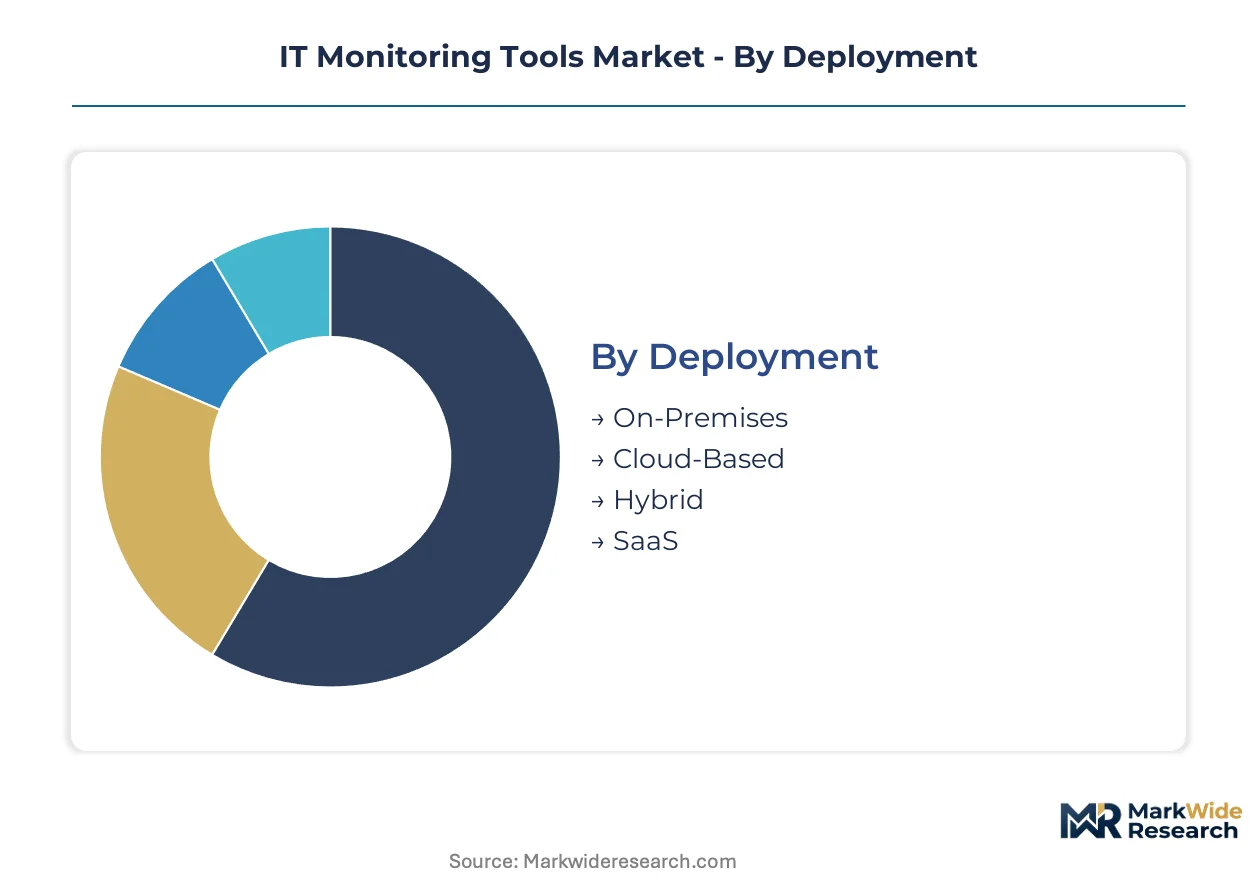
IT monitoring tools fragment across four critical dimensions that determine procurement patterns and vendor competitive positioning. Deployment models dictate capital structure and operational control. End-user profiles shape pricing tolerance and feature complexity requirements. Feature specialization and technology architecture determine integration depth with existing infrastructure stacks.
Deployment:
Integration depth varies sharply: cloud and SaaS segments embed monitoring into managed service fabrics, while on-premises deployments demand standalone operational investment.
- Cloud-Based:Consumption-priced telemetry platforms ingest metrics, logs, and traces through managed cloud infrastructure. Frankfurt's banking cluster under EU DORA mandates deploys these for real-time resilience reporting with demonstrable recovery time objectives.
- SaaS:Fully managed observability stacks eliminate infrastructure ownership, appealing to startups and mid-market enterprises without dedicated platform engineering teams. Procurement concentrates in technology companies with ephemeral container workloads requiring elastic scaling.
- On-Premises:Self-hosted monitoring infrastructure retains data sovereignty and latency control for regulated environments. Demand persists in German financial services and US defense-adjacent sectors with strict data residency requirements.
- Hybrid:Split deployments process sensitive telemetry on-premises while routing non-critical metrics to cloud backends. Manufacturing and energy sectors favor this architecture for distributed IoT sensor networks.
Infrastructure monitoring leads volumes today; SaaS is gaining share fastest.
End User:
Cost tier stratification separates enterprise buyers with compliance-driven budgets from price-sensitive startup procurement.
- Enterprises:Multi-divisional organizations procure unified observability platforms spanning global infrastructure footprints. EU banking groups under ECB supervisory expectations mandate enterprise-grade coverage with audit-ready telemetry retention.
- Managed Service Providers:Third-party IT operators resell monitoring capabilities as bundled service offerings. These buyers prioritize multi-tenant architecture and white-label dashboard capabilities.
- IT Departments:Internal technology teams operate tools for service reliability and incident response. Procurement concentrates in organizations with established site reliability engineering functions.
- Startups:Early-stage companies select lightweight, pay-as-you-grow solutions with minimal configuration overhead. These users drive consumption-based pricing adoption across the vendor landscape.
Enterprise procurement dominates absolute spend; MSP channel volume is climbing the fastest.
Feature:
Application context determines which capability layers sit embedded within DevOps pipelines versus standalone operational dashboards.
- Infrastructure Monitoring:Server, storage, and network hardware telemetry forms the foundational observability layer. This capability commands the largest existing spend across regulated industries with uptime mandates.
- Application Performance:Distributed tracing and code-level instrumentation target microservices architectures. Financial services firms in Singapore and Frankfurt deploy these at production scale for latency-sensitive transaction systems.
- Network Monitoring:Traffic flow analysis and device health tracking sustain deep on-premises capabilities. Demand concentrates in telecommunications and critical infrastructure operators.
- Log Management:Centralized log aggregation and search enable security forensics and operational debugging. This segment expands with CSRD-mandated audit trail requirements in European jurisdictions.
Infrastructure monitoring anchors current budgets; application performance is expanding most quickly.
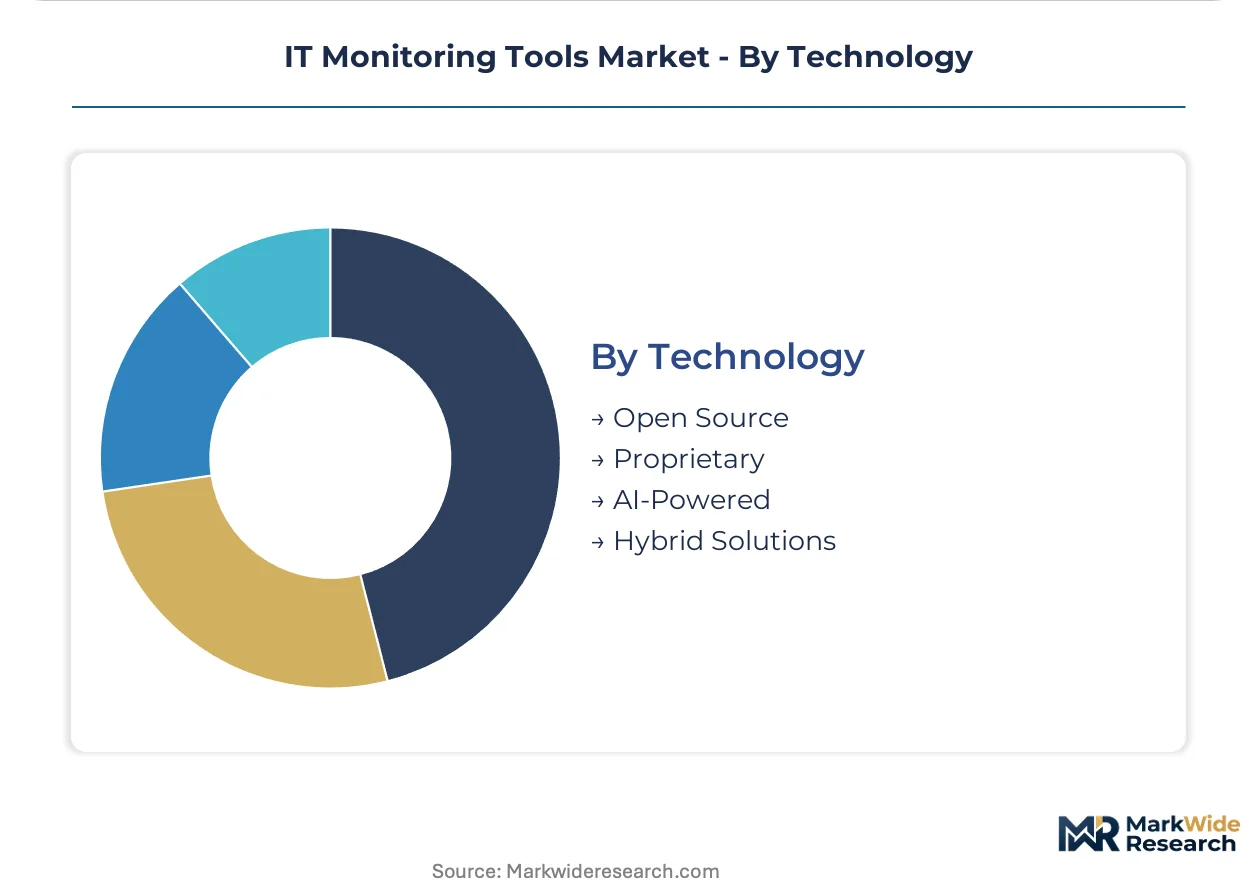
Technology:
Maturity curves separate established proprietary stacks from emerging AI-augmented architectures.
- AI-Powered:Machine learning models trained on historical incident data displace static threshold alerting. EU AI Act risk classification requirements now demand explainability logs for automated anomaly detection in regulated deployments.
- Open Source:OpenTelemetry-based instrumentation collapses vendor-specific agent sprawl into unified telemetry pipelines. This architecture is consolidating vendor competition around backend query performance rather than collection mechanics.
- Proprietary:Vendor-locked agents and query languages sustain switching friction and margin protection. Dominant cloud platforms leverage proprietary formats to constrain buyer negotiation leverage.
- Hybrid Solutions:Mixed architectures combine open-source collection with proprietary analytics backends. These deployments address interoperability requirements emerging from cross-border regulatory divergence.
Proprietary technology retains volume leadership; AI-powered solutions show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The IT monitoring tools industry traces its commercial origins to Silicon Valley's enterprise software expansion during the late 1990s, with foundational telemetry architectures emerging from US-based network equipment vendors before migrating to cloud-native platforms.
United States
Financial services firms in New York and technology companies in Seattle drive enterprise observability procurement. The SEC mandates operational resilience reporting with demonstrable recovery time objectives for registered broker-dealers. San Francisco's cloud-native software cluster deploys consumption-based monitoring at scale for ephemeral container workloads.
Germany
Frankfurt's banking concentration enforces strict uptime requirements under ECB supervisory expectations. The EU Digital Operational Resilience Act embeds real-time infrastructure monitoring into core compliance budgets for financial institutions. Munich's industrial technology corridor applies observability platforms to manufacturing IoT sensor networks.
United Kingdom
London's fintech ecosystem and institutional asset managers expand observability spending to meet UK Prudential Regulation Authority mandates. The Financial Conduct Authority requires operational resilience reporting with specified maximum tolerable downtime. The Thames Valley technology cluster concentrates SaaS monitoring procurement among mid-market enterprises.
Singapore
Latency-sensitive trading systems and sovereign wealth fund technology operations demand millisecond-granularity application performance monitoring. The Monetary Authority of Singapore enforces technology risk management guidelines requiring comprehensive infrastructure coverage. The Marina Bay financial district deploys distributed tracing for high-frequency transaction platforms.
Japan
Tokyo's banking consortiums and automotive manufacturers invest in hybrid observability architectures for legacy mainframe integration. METI operational resilience guidelines shape procurement requirements for critical infrastructure operators. The Osaka-Kobe manufacturing belt applies edge computing monitoring to distributed industrial control systems.
IT Monitoring Tools Market Competitive Environment
Premium-margin players sit above commodity-margin players across deployment model sophistication, with cloud-native platforms commanding higher pricing power than on-premises toolkits. The vendor landscape consolidates around three strategic tiers: hyperscale cloud providers bundling monitoring into infrastructure services, independent observability specialists competing on multi-cloud neutrality, and legacy network monitoring vendors defending installed bases through deep on-premises capabilities. Dominant competitive moves include vertical integration into managed security operations and strategic partnerships with FinOps platforms to correlate infrastructure spend with performance metrics.
Within the hyperscale tier, Microsoft Corporation and Amazon Web Services, Inc. anchor enterprise deployments through native integration with cloud infrastructure fabrics. Datadog Inc. exemplifies the independent specialist archetype competing for multi-cloud accounts requiring vendor-neutral telemetry pipelines. These three entities represent the primary competitive anchors shaping procurement negotiations and pricing benchmarks across regulated industries.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Amazon Web Services, Inc. |
| Cisco Systems, Inc. |
| Dynatrace LLC |
| Datadog Inc. |
| Splunk Inc. |
| SolarWinds Worldwide |
| Google LLC |
| NetScout Systems |
| Others |
Value Chain & Pricing Dynamics
OpenTelemetry standardization is collapsing vendor-specific agent architectures into unified telemetry pipelines, simultaneously compressing collection costs and concentrating backend platform competition around query performance and storage economics rather than distribution mechanics.
Pricing Analysis
Consumption-based pricing indexed to monthly active service instances dominates enterprise procurement, displacing seat-based licensing across technology companies with ephemeral container workloads. Price differentiation hinges on data retention tiers and AI-powered anomaly detection capabilities. Cost compression in mid-market SaaS tiers intensifies as open-source alternatives erode switching friction. Startups exhibit highest price sensitivity; regulated financial services firms show lowest.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscale providers concentrated in the United States, Ireland, and Singapore. Critical inputs include GPU compute for ML inference, object storage for telemetry retention, and edge networking hardware for distributed sensor preprocessing. Single-source vulnerability runs through proprietary query language ecosystems that constrain buyer migration. Distribution feeds through direct enterprise sales and managed service provider channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
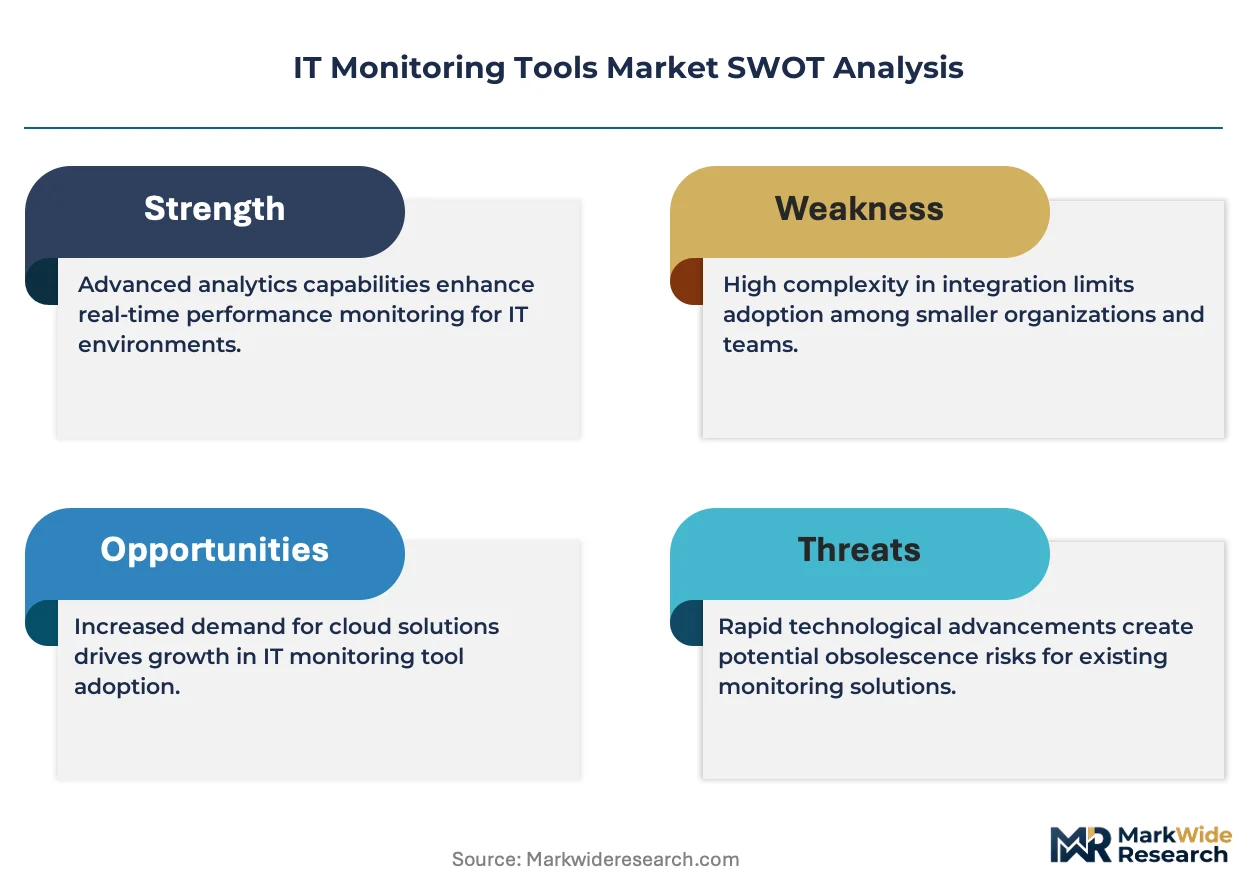
The IT monitoring tools market compounds steadily as regulatory mandates across financial services permanently embed observability spend into compliance budgets rather than discretionary technology cycles.
For Market Incumbents: Anchor multi-cloud neutrality as the core defensive position against hyperscale bundling. Invest in OpenTelemetry-native architectures to neutralize proprietary format lock-in. Deepen vertical integration into FinOps platforms to capture cloud cost optimization convergence. Prioritize explainability documentation for EU AI Act compliance in regulated deployments. For New Entrants and Emerging Players: AI-powered edge observability for manufacturing IoT networks offers the most penetrable white space. Target German industrial corridors and Japanese automotive belts with lightweight agent architectures. Pursue sustainability telemetry as the go-to-market angle, leveraging CSRD carbon reporting mandates to displace legacy infrastructure monitoring incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among independent observability specialists with proven multi-cloud deployments but subscale enterprise sales infrastructure. Long-term viability favors platforms with demonstrated recovery time objective compliance for EU banking mandates. Watch OpenTelemetry backend performance benchmarks as the inflection signal for platform consolidation winners.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | OpenTelemetry-native pipelines collapse vendor lock-in and redraw competitive boundaries around storage economics. |
| Strategic Partnership | FinOps convergence partnerships capture cloud cost optimization budgets alongside traditional reliability spend. |
| Acquisition of Specialist Firm | Edge computing observability targets expand coverage into manufacturing IoT and distributed industrial control systems. |
| Geographic Expansion | Frankfurt banking cluster deployments satisfy EU DORA mandates and anchor European compliance-driven procurement. |
| Product Launch | Explainable AI anomaly detection addresses EU AI Act risk classification requirements for automated infrastructure alerts. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs, platform engineering directors, IT procurement officers, and channel integration specialists with secondary validation through SEC filings, hyperscaler capex disclosures, EU regulatory impact assessments, and OpenTelemetry community documentation. Bottom-up telemetry volume estimates and top-down enterprise spend surveys were triangulated against vendor-reported deployment metrics.
Segment-weighted modeling applied deployment mode, organization size, vertical industry, and regional regulatory cluster as primary stratification dimensions across the projection horizon. CAGRs derived from historical telemetry ingestion growth curves, cloud migration velocity indices, and compliance mandate implementation timelines. AI-powered technology adoption curves and OpenTelemetry standardization penetration served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to hyperscale pricing aggression, regulatory enforcement variance across EU member states, and site reliability engineering talent scarcity constraints. Material deviation in OpenTelemetry backend performance benchmarks or EU AI Act enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital Certificates Market
Digital Solutions
Service Virtualization Market
Digital Solutions
Foot Traffic and Customer Location Intelligence Solution Market
Digital Solutions
Lecture Capture Systems Market
Digital Solutions
Epedigree Software Market
Digital Solutions
Global Asset Reliability Software Market
Digital Solutions
Global Continuous Delivery Market
Digital Solutions
Location As a Service Market
Digital Solutions
Global Asset Tracking and Inventory Management Solutions Market
Digital Solutions
Work From Home Setup Market
Digital Solutions
Global Automatic Content Recognition (ACR) Market
Digital Solutions
Australia Digital Marketing Software Market
Digital Solutions
Saudi Arabia ICT Market
Digital Solutions
File Sharing Market
Digital Solutions
E-Ink E-Reader Market
Digital Solutions
Warehouse Management System (WMS) Market