
 Business Process Management As a Service Market | 2026-2036
Business Process Management As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Business Process Management As a Service Market Insights
The EU AI Act is recalibrating procurement criteria for automated workflow platforms across European enterprises. IBM Corporation leverages its hybrid cloud infrastructure to sustain compliance-ready deployments for regulated industries. Oracle Corporation anchors its position through deep integration with enterprise resource planning ecosystems. Accenture plc differentiates via vertical-specific process templates that reduce implementation timelines for financial services clients.
Business Process Management As a Service denotes the cloud-hosted delivery of process design, execution, monitoring, and optimization capabilities through subscription or usage-based licensing, typically leveraging containerized microservices architectures with API-first integration protocols. Its primary commercial purpose is to replace on-premises workflow engines with elastic, multi-tenant platforms that reduce capital expenditure while enabling real-time process analytics. Process Automation commands the largest service type revenue pool as enterprises eliminate manual handoffs in claims processing and invoice reconciliation. Hybrid Cloud deployments are expanding fastest among end users managing personally identifiable information across jurisdictional boundaries. Analytics Services represents the highest-margin segment, where predictive process mining commands premium pricing against descriptive dashboards alone.
The Securities and Exchange Commission mandates audit trail retention for financial process automation, elevating demand for tamper-evident logging within BPM platforms. The EU General Data Protection Regulation imposes data residency constraints that favor private cloud or hybrid configurations over pure public cloud deployments for European healthcare and government verticals. Stakeholders must evaluate whether their current vendor partnerships provide jurisdictional data sovereignty guarantees before committing to long-term platform contracts.
Market Dynamics
Cloud-native process orchestration is rewriting how enterprises provision workflow automation, collapsing deployment cycles from quarters to weeks while embedding compliance-by-design into financial services infrastructure.
Growth Catalysts
- EU AI Act certification mandates:Automated decision-making systems in European banking now require algorithmic audit trails, forcing platform upgrades that favor established BPM-as-a-Service vendors with pre-built compliance modules.
- Containerized microservices adoption:Financial services firms deploy API-first process engines to eliminate manual handoffs in claims processing and invoice reconciliation, reducing operational latency.
- United States hybrid cloud concentration:Enterprises managing personally identifiable information across state jurisdictions prioritize private cloud extensions for sensitive operational data, accelerating platform contracts with sovereignty guarantees.
Market Restraints
- Data residency compliance costs:EU General Data Protection Regulation constraints favor hybrid configurations over pure public cloud, inflating total cost of ownership for European healthcare deployments.
- Specialized talent scarcity:Process mining engineers and compliance architects command premium compensation, constraining implementation velocity for mid-market buyers.
- Legacy system integration friction:Mainframe-connected workflows in established financial institutions resist API abstraction, prolonging migration timelines.
Strategic Opportunities
- Process mining convergence with predictive analytics:Real-time anomaly detection layered atop historical workflow data commands premium pricing against descriptive dashboards alone.
- Healthcare vertical expansion:HIPAA-compliant orchestration platforms remain underpenetrated in US hospital systems managing patient intake across multi-state networks.
- Securities and Exchange Commission audit mandates:Tamper-evident logging requirements for financial process automation create vendor stickiness through embedded compliance infrastructure.
Industry Challenges
- Cross-functional implementation coordination:Business analysts, IT security teams, and compliance officers maintain conflicting success metrics, stalling platform rollouts.
- Algorithmic bias certification delays:EU AI Act conformity assessments for automated credit decisioning extend procurement cycles by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Process Management As a Service Market |
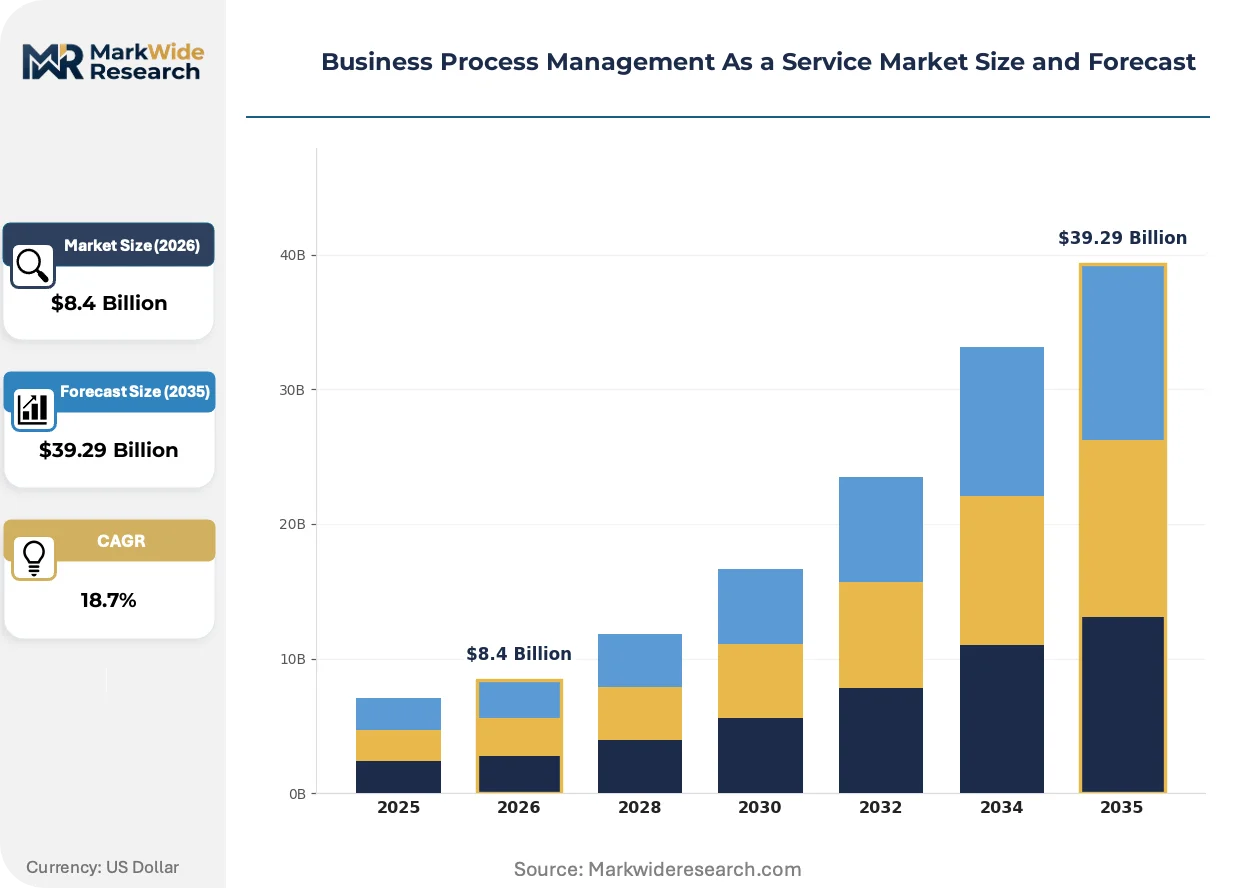
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Process Automation, Workflow Management, Document Management, Analytics Services Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Healthcare, Financial Services, Retail, Telecommunications Industry Vertical: Manufacturing, Education, Government, Utilities |
| Companies Covered | IBM Corporation, Appian, Oracle Corporation, Software AG, Pegasystems Inc., TIBCO Software Inc., Accenture plc, SAP SE, Open Text Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Process Management As a Service Market Trends and Innovations
Generative AI integration is compressing process design cycles while embedding natural language interfaces into workflow configuration tools. Platform vendors race to embed predictive capabilities without triggering regulatory scrutiny.
Large language models are rewriting how business analysts construct workflow logic, enabling natural language process specification that bypasses traditional drag-and-drop interfaces. Mid-market financial services firms adopt these tools fastest, cutting process design from weeks to days. The structural consequence is deskilling of configuration work and margin compression for implementation services.
The EU AI Act's risk-based classification system is forcing platform vendors to pre-certify high-risk automation modules before European deployment. Banking and insurance buyers now mandate algorithmic explainability documentation as standard procurement criteria. German and French enterprises lead this compliance-driven vendor consolidation.
Usage-based licensing models are displacing flat-rate subscriptions as buyers demand cost alignment with actual transaction volumes. Cloud marketplaces and API aggregators capture growing share of platform distribution. This shift is most visible in United States fintech segments where transaction volatility makes committed spend models untenable.
Business Process Management As a Service Market Segmentation
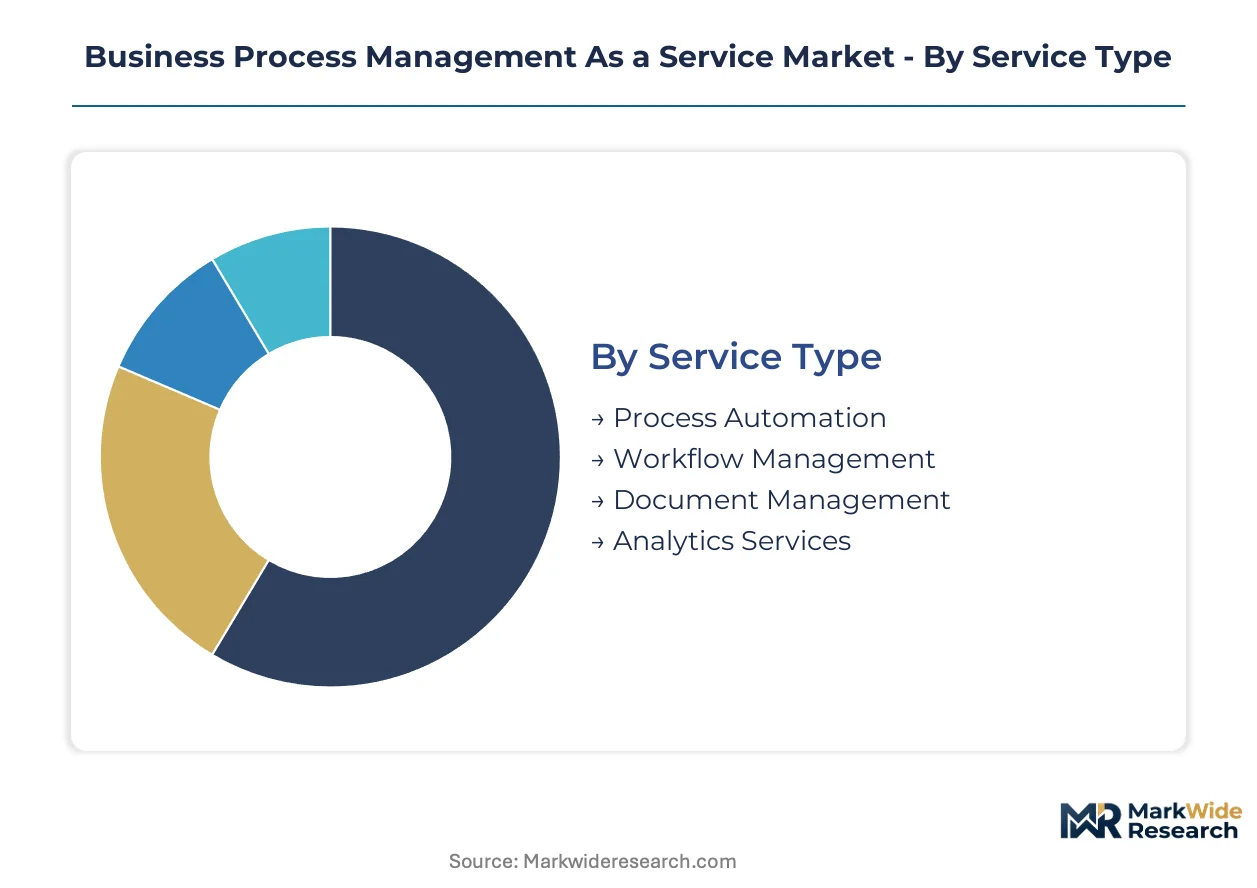
BPM-as-a-Service segmentation reveals how cloud delivery models, service layers, and vertical requirements create distinct commercial battlegrounds. Vendors must calibrate infrastructure investments against compliance mandates and data sovereignty demands that vary sharply across deployment configurations and end-use industries.
Service Type:
Process Automation commands volume leadership while Analytics Services captures premium margins through predictive capabilities.
- Process Automation:Containerized microservices orchestrate claims processing, invoice reconciliation, and compliance workflows through API-first integration protocols. Financial services firms in the United States deploy these engines to eliminate manual handoffs and embed SEC-mandated audit trails directly into transaction flows.
- Analytics Services:Predictive process mining layered atop historical workflow data enables real-time anomaly detection and commands pricing premiums against descriptive dashboards alone. Healthcare networks managing patient intake across multi-state jurisdictions leverage these tools for capacity optimization.
- Workflow Management:Cloud-native orchestration platforms collapse deployment cycles from quarters to weeks through subscription licensing.
- Document Management:Tamper-evident logging architectures support regulatory retention requirements in banking and insurance sectors.
Today's leader: Process Automation. Tomorrow's challenger: Analytics Services.
Deployment Model:
Cost tier stratification separates sovereign-ready private infrastructure from elastic public consumption.
- Hybrid Cloud:Private cloud extensions for sensitive operational data combined with public burst capacity address GDPR data residency constraints and HIPAA jurisdictional requirements. United States enterprises managing personally identifiable information across state boundaries prioritize these configurations for healthcare and financial workloads.
- Private Cloud:Single-tenant dedicated infrastructure delivers compliance certifications required by EU AI Act high-risk automation modules. German and French banking regulators mandate these deployments for automated credit decisioning systems.
- Public Cloud:Multi-tenant elastic provisioning serves mid-market buyers with standardized process templates and lower operational overhead.
- On-Premises:Legacy mainframe-connected workflows in established financial institutions resist API abstraction, prolonging migration timelines.
Hybrid Cloud is climbing the fastest as sovereignty guarantees become non-negotiable in procurement criteria.
End User:
Application intensity varies by regulatory exposure and transaction velocity requirements.
- Financial Services:Algorithmic audit trails for automated decision-making systems under EU AI Act mandates drive platform upgrades. SEC tamper-evident logging requirements create vendor stickiness through embedded compliance infrastructure.
- Healthcare:HIPAA-compliant orchestration platforms managing patient intake across multi-state networks remain underpenetrated in US hospital systems.
- Retail:Usage-based licensing aligns costs with seasonal transaction volatility in e-commerce fulfillment chains.
- Telecommunications:Real-time provisioning workflows support network service activation and customer onboarding at scale.
Financial Services anchors current deployment value. Healthcare represents the steepest expansion trajectory as compliance-ready platforms penetrate hospital networks.
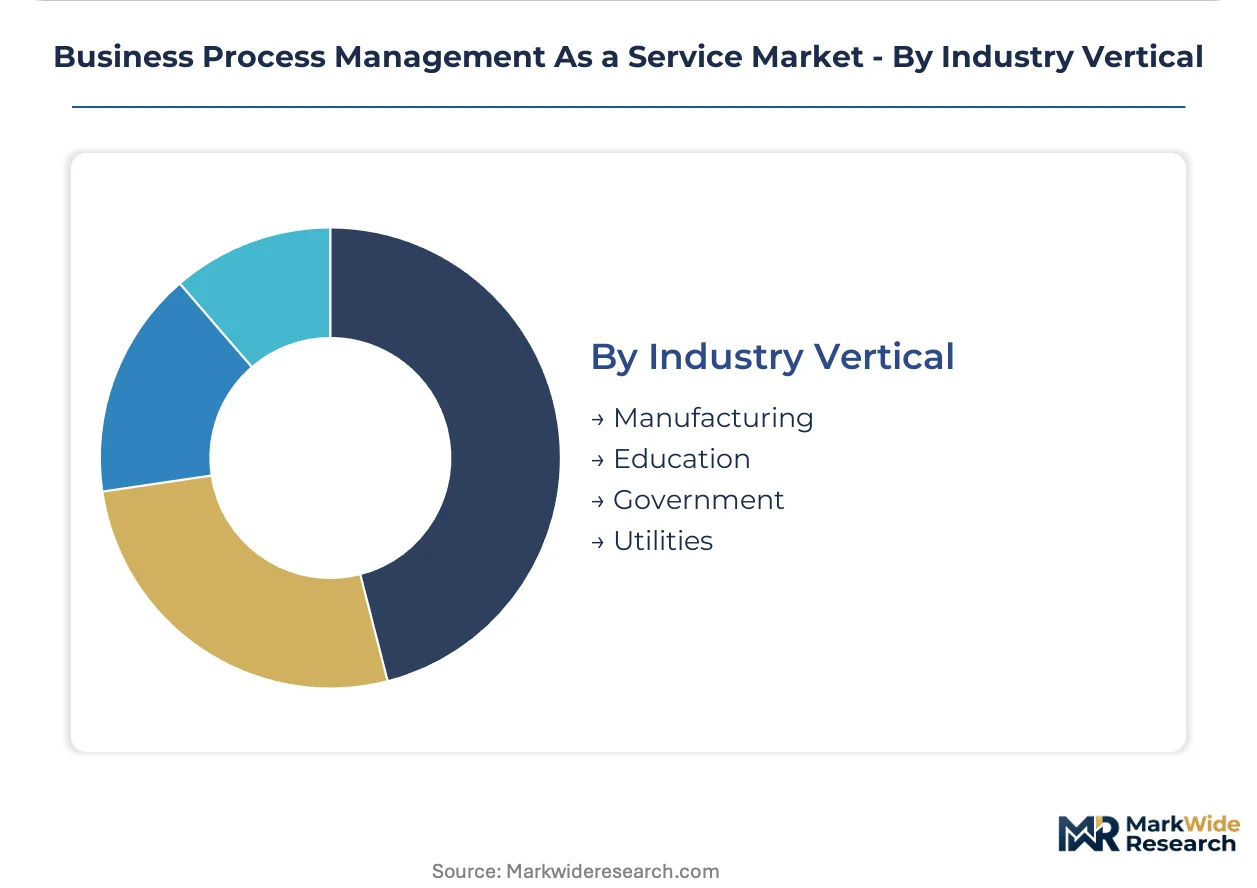
Industry Vertical:
Maturity gaps separate digitally transformed sectors from compliance-constrained laggards.
- Manufacturing:Supply chain orchestration and quality management workflows integrate with ERP ecosystems through pre-built connectors.
- Government:Data residency requirements and procurement security certifications favor established vendors with federal authorization pathways.
- Education:Student lifecycle management and research administration workflows adopt cloud-native platforms for operational cost reduction.
- Utilities:Field service dispatch and asset maintenance scheduling leverage mobile-enabled process automation for distributed workforces.
Manufacturing leads vertical adoption. Government contracts deliver the longest revenue visibility despite extended sales cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud-based workflow automation originated in United States technology corridors before spreading to European financial centers and Asia-Pacific enterprise hubs. The current geographic footprint reflects divergent regulatory regimes and data sovereignty requirements.
United States
Financial services firms in New York and Chicago drive hybrid cloud adoption for SEC-mandated audit trail retention. HIPAA compliance requirements push healthcare networks toward private cloud extensions. The Dallas-Fort Worth metroplex hosts expanding data center capacity for multi-state patient intake orchestration.
Germany
Automated credit decisioning systems in Frankfurt's banking district require EU AI Act high-risk module certification. The country's national data protection regulator enforces GDPR data residency constraints strictly. Munich's industrial software cluster concentrates manufacturing workflow integration expertise.
United Kingdom
London's insurance sector demands algorithmic explainability documentation for automated claims processing. The Financial Conduct Authority scrutinizes algorithmic decision-making in consumer lending. Edinburgh's fintech corridor incubates usage-based licensing models for transaction-volatile workloads.
Japan
Tokyo's banking consortiums deploy containerized microservices for legacy mainframe modernization. METI guidelines shape procurement criteria for cloud-native process engines. Osaka's manufacturing belt integrates supply chain orchestration with enterprise resource planning ecosystems.
India
Bengaluru's IT services hubs deliver process mining engineering talent at scale. RBI guidelines on data localization influence hybrid cloud architecture decisions. Mumbai's financial district anchors back-office automation for global banking clients.
Business Process Management As a Service Market Competitive Landscape
Premium-margin players sit above commodity-margin players across compliance certification depth and vertical specialization intensity. The vendor base clusters around three strategic tiers: hyperscale cloud platforms with embedded workflow engines, pure-play process automation specialists, and systems integrators with pre-built industry templates. Consolidation pressure favors vendors with pre-certified EU AI Act modules and established federal authorization pathways. Dominant competitive moves include strategic partnerships with cloud marketplaces and portfolio diversification into predictive analytics layers.
Among United States-based technology conglomerates, IBM Corporation and Oracle Corporation occupy positions at the infrastructure-integrated tier where hybrid cloud sovereignty guarantees anchor long-term contracts. Appian exemplifies the pure-play archetype with its low-code process design heritage. Accenture plc sits within the advisory-led systems integration segment where vertical-specific implementation velocity commands premium pricing against generic platform deployments.
| Leading Market Players |
|---|
| IBM Corporation |
| Appian |
| Oracle Corporation |
| Software AG |
| Pegasystems Inc. |
| TIBCO Software Inc. |
| Accenture plc |
| SAP SE |
| Open Text Corporation |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure spot pricing indices cascade through BPM-as-a-Service vendor cost structures, compressing margins for pure-play automation specialists while hyperscale platforms absorb volatility through captive server farms and long-term compute commitments.
Pricing Analysis
Subscription-based tiering across enterprise, professional, and developer levels anchors vendor revenue models, with EU AI Act certification grade and transaction volume scale serving as the primary price differentiation levers. Cost compression in the mid-market tier intensifies as usage-based licensing displaces flat-rate subscriptions, forcing vendors to align pricing with actual workflow execution counts. Financial services buyers exhibit the lowest price sensitivity due to embedded compliance requirements, while retail and education segments drive hardest bargain for standardized process templates.
Supply Chain Analysis
Container orchestration software supply rests on hyperscale cloud providers in the United States, specialized microservices engineering talent in India, and compliance certification bodies in Germany and France. Critical inputs span Kubernetes distributions, API gateway middleware, and algorithmic audit logging architectures. Single-source vulnerability concentrates around hyperscale infrastructure dependencies, with tariff exposure on cross-border data transfer services emerging as a secondary risk. Distribution runs through direct enterprise sales teams, cloud marketplaces, and systems integrators with vertical-specific implementation expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BPM-as-a-Service functions as a stable compounder, with regulatory compliance mandates generating recurring platform upgrade cycles that lock in enterprise customers across multi-year contracts.
For Market Incumbents: Anticipate margin pressure from generative AI-enabled process design tools that deskill configuration work and compress implementation services revenue. Defend position by deepening backward integration into predictive analytics layers and securing pre-certified EU AI Act modules before procurement cycles extend. Prioritize hybrid cloud sovereignty guarantees in United States and German banking verticals where data residency constraints favor established vendors. For New Entrants and Emerging Players: Enter via HIPAA-compliant orchestration platforms in United States hospital systems, where compliance-ready solutions remain underpenetrated relative to financial services saturation. Target mid-market healthcare networks managing patient intake across multi-state jurisdictions with usage-based licensing that aligns costs with seasonal volume volatility. Lead with natural language process specification tools that collapse design cycles from weeks to days. For Investors and Strategic Acquirers: Consolidation pressure builds where EU AI Act certification requirements favor vendors with pre-built compliance modules and established federal authorization pathways. The market supports long-term compounder positioning for platforms with embedded regulatory infrastructure that generates switching costs. Monitor algorithmic bias certification delays as an inflection signal—extended procurement cycles in European banking indicate vendor consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Module Pre-Certification | Frankfurt and Paris banking regulators mandate algorithmic explainability documentation for automated credit decisioning systems. |
| Predictive Analytics Layer Acquisition | Premium-margin process mining capabilities command pricing power against descriptive dashboards in healthcare capacity optimization. |
| Hybrid Cloud Sovereignty Expansion | Dallas-Fort Worth data center capacity addresses multi-state HIPAA jurisdictional requirements for patient intake orchestration. |
| Natural Language Process Design Launch | Mid-market financial services firms adopt generative AI configuration tools fastest, cutting deployment timelines dramatically. |
| Healthcare Vertical Partnership | Hospital system GPO contracts deliver longest revenue visibility despite extended sales cycles and compliance validation requirements. |
Research Methodology
Direct dialogue with cloud platform architects, compliance officers at financial institutions, healthcare IT procurement leads, and process mining engineers grounded the qualitative foundation, cross-referenced against SEC 10-K infrastructure disclosures, EU regulatory filing databases, hyperscaler capex reports, and hospital system RFP documentation. Bottom-up and top-down triangulation validated segment-level assumptions.
Bottom-up modeling of containerized deployment volumes and subscription renewal rates across service type, deployment model, and vertical segmentation combined with top-down macroeconomic elasticity checks across the projection horizon. CAGRs were derived from trend extrapolation of cloud-native adoption curves and regulatory mandate implementation timelines, with algorithmic audit trail requirements and data residency constraints serving as industry-specific demand drivers.
Inputs from cloud marketplace transaction data and healthcare procurement databases were available through the study window; gaps in private cloud infrastructure pricing transparency introduce uncertainty bands around hybrid deployment forecasts. A small set of named triggers—EU AI Act enforcement escalation, SEC audit mandate expansion, and generative AI capability commoditization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Japan E-Invoicing Market
Digital Solutions
Event Apps Market
Digital Solutions
Cloud Backup and Recovery Market
Digital Solutions
Brazil Digital Twin Market
Digital Solutions
US Customer Communication Management (CCM) Market
Digital Solutions
Global Client Virtualization Market
Digital Solutions
Dating Services Market
Digital Solutions
Integrated Systems Market
Digital Solutions
Webrtc Market
Digital Solutions
Load Balancer Market
Digital Solutions
Search Engine Optimization Services Market
Digital Solutions
Asia-Pacific Intelligent Document Processing Market
Digital Solutions
Data Classification Tool Market
Digital Solutions
Global Intelligent Document Processing Market
Digital Solutions
US Digital Signage Market
Digital Solutions
Digital Signage Services Market