
 Global Digital Experience Management Market | 2026-2036
Global Digital Experience Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Experience Management Market Foresight
Modular platform bundling is recalibrating how enterprises evaluate digital experience management vendors. Adobe leverages its creative cloud integration to anchor comprehensive content-to-experience workflows. Salesforce sustains competitive positioning through its CRM-native personalization layer. SAP differentiates by embedding experience management directly into ERP-driven operational data streams.
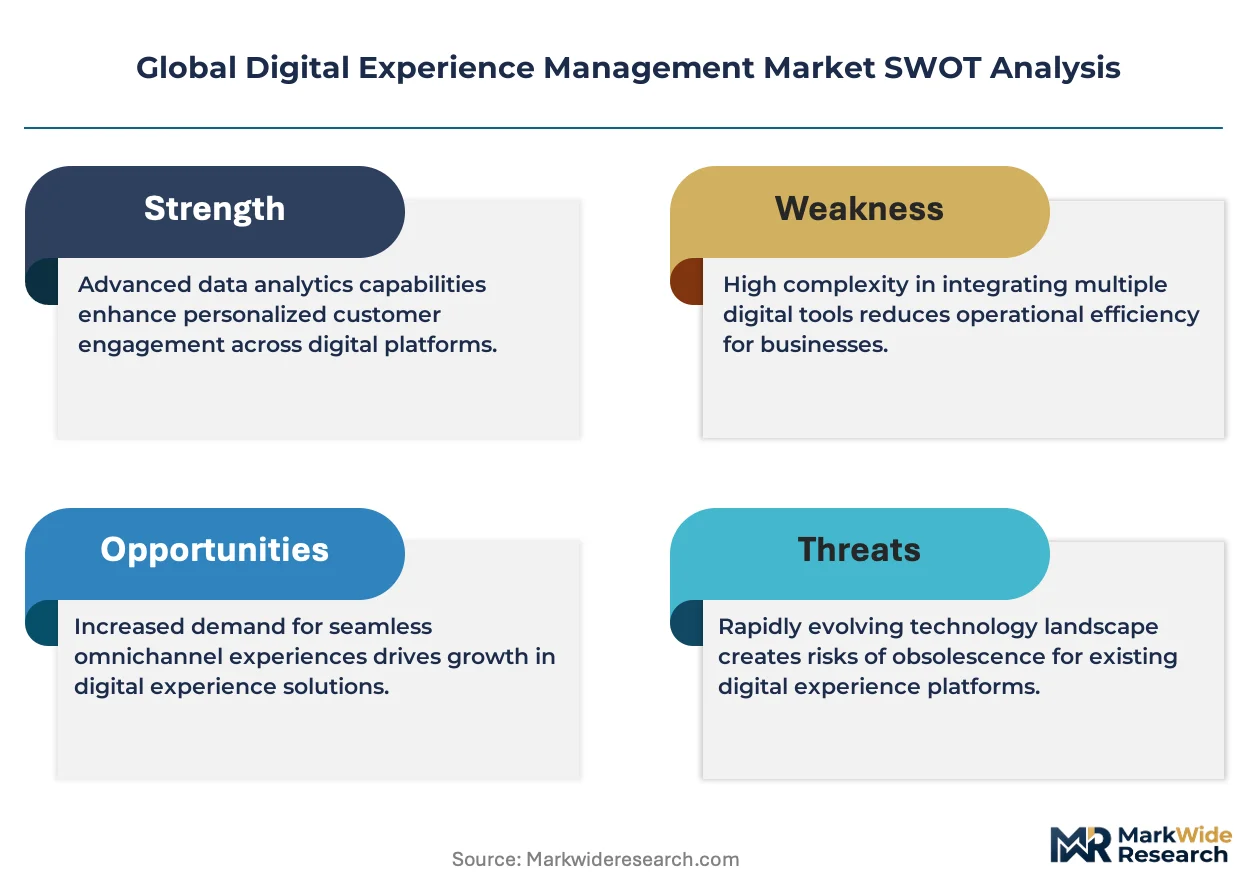
Digital experience management encompasses the orchestration of content, analytics, and interaction technologies to deliver consistent, measurable engagement across customer touchpoints, typically integrating real-time data pipelines with rule-based personalization engines. The primary commercial purpose centers on reducing customer acquisition costs while extending lifetime value through behavior-triggered engagement. Cloud-based deployment leads solution delivery due to elastic scaling requirements for seasonal traffic spikes, while personalization engines capture disproportionate R&D investment as enterprises prioritize one-to-one messaging at scale. Customer journey mapping within the use case taxonomy is maturing fastest as a standalone purchase category, though omnichannel engagement retains the broadest cross-industry applicability.
The EU AI Act and GDPR shape product roadmaps for any vendor serving European enterprises, mandating explainable algorithms and granular consent management within personalization systems. The US FDA and SEC impose sector-specific data governance requirements on healthcare and financial services deployments respectively, fragmenting compliance architectures. Japan's METI guidelines on digital platform transparency add a third jurisdictional layer that multinational vendors must navigate. Stakeholders should monitor regulatory divergence between privacy-first jurisdictions and innovation-permissive markets as the primary strategic variable affecting platform architecture decisions.
Market Dynamics
Real-time personalization engines are compressing decision cycles across enterprise marketing stacks, forcing vendors to embed sub-100-millisecond latency into customer data platforms or lose competitive relevance.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises must deploy explainable personalization algorithms with granular consent audit trails, accelerating replacement cycles for opaque legacy systems.
- BFSI sector expansion:Financial services firms in the United States and India are integrating customer analytics platforms with core banking infrastructure to reduce acquisition costs.
- Edge computing architectures:Distributed processing nodes enable real-time experience orchestration without centralized data gravity, unlocking latency-sensitive use cases in retail and telecommunications.
Market Restraints
- Cloud infrastructure concentration:Hyperscaler dependency in the United States creates single-point-of-failure exposure for global deployment footprints.
- GDPR territorial friction:Data localization requirements fragment architecture decisions, forcing redundant infrastructure investments for European operations.
- Identity resolution cost inflation:Third-party cookie deprecation drives up proprietary data collection infrastructure spend by 40-60% for mid-market buyers.
Strategic Opportunities
- India's digital public infrastructure:The Account Aggregator framework and UPI payment rails enable consent-based financial data sharing, creating native personalization channels for banking and insurance use cases.
- Healthcare experience orchestration:HIPAA-compliant patient journey mapping remains underpenetrated relative to retail and financial services, with FDA guidance on digital therapeutics creating regulatory clarity.
- Generative AI content pipelines:Convergence of large language models with brand governance tools enables dynamic creative production at scale, compressing campaign launch cycles from weeks to hours.
Industry Challenges
- Cross-functional talent scarcity:Enterprises struggle to hire practitioners who bridge data engineering, privacy law, and creative operations simultaneously.
- Legacy CRM integration complexity:Decades-old customer databases in German manufacturing and Japanese automotive sectors resist real-time API connectivity without expensive middleware layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Experience Management Market |
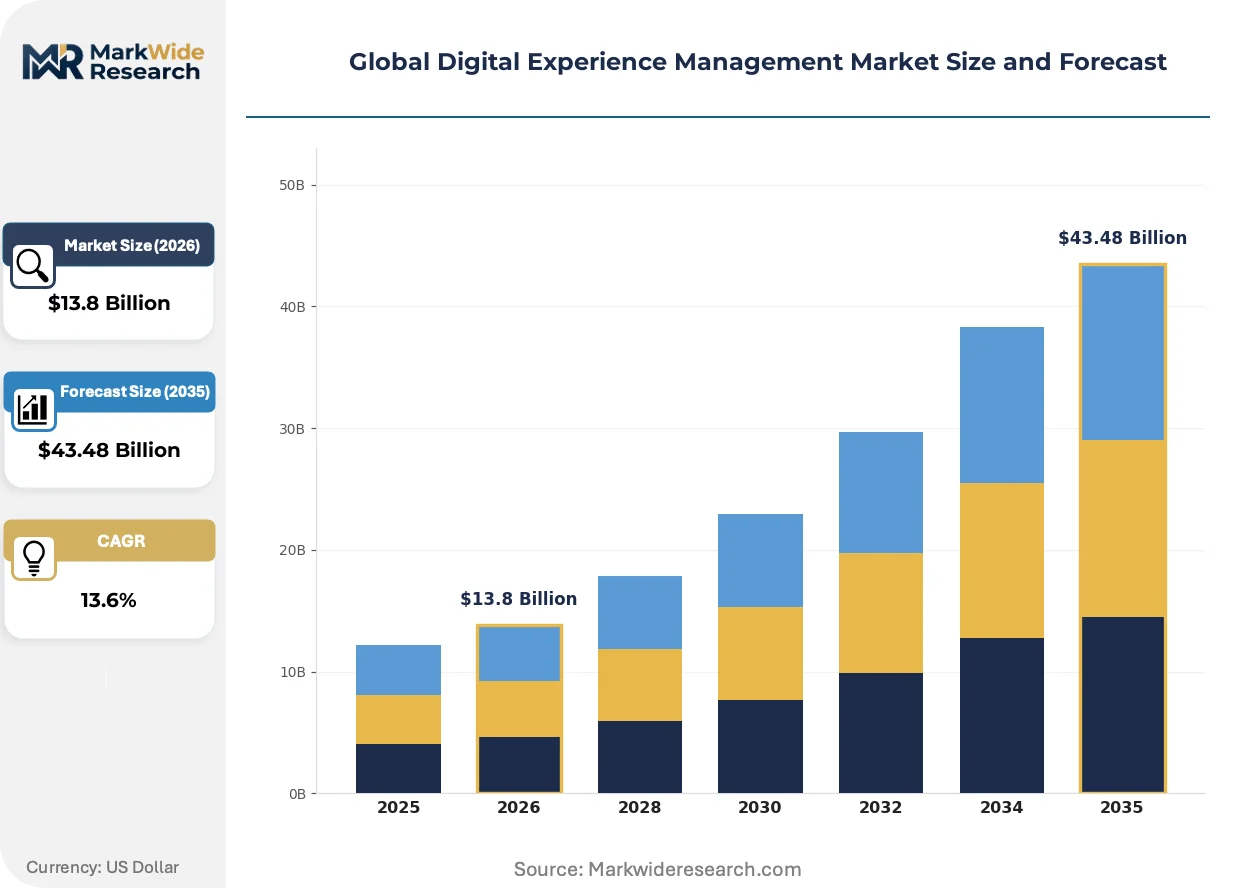
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $43.48 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Solution Type: Content Management, Customer Analytics, Personalization Engines, Campaign Management, Social Media Management, Feedback Management Use Case: Customer Journey Mapping, Omnichannel Engagement, User Behavior Tracking, Conversion Rate Optimization, Digital Asset Management End User Industry: BFSI, Telecommunications, Education, Government, Travel & Hospitality |
| Companies Covered | Adobe, Salesforce, Oracle, SAP, Microsoft, IBM, Sitecore, Acquia, Liferay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Experience Management Market Shifts & Advancements
Composable architecture principles are dismantling monolithic experience platforms, enabling enterprises to swap individual components without forklift upgrades. This shift rewards vendors with open APIs and punishes closed ecosystems.
Customer data platforms are converging with identity resolution services to unify anonymous and authenticated touchpoints. Retailers in Germany and the United States are deploying these stacks fastest, compressing the path from first visit to personalized engagement from days to milliseconds. The structural consequence is collapsing vendor margins for point-solution providers lacking adjacent capabilities.
The EU AI Act's risk-based classification system is forcing algorithmic transparency into product roadmaps. High-risk personalization systems must maintain human oversight logs and bias audit documentation, adding 15-25% to compliance overhead. Healthcare and financial services deployments in France and the Netherlands are most affected, with vendors accelerating investment in explainable AI modules.
Enterprise buyers are unbundling omnichannel suites to purchase journey orchestration as standalone software. Procurement teams in India and the United States now evaluate point solutions against best-of-breed criteria rather than single-vendor coverage. This pattern is most visible in telecommunications and energy utilities, where legacy vendor relationships carry lower switching friction.
Global Digital Experience Management Market Segmentation
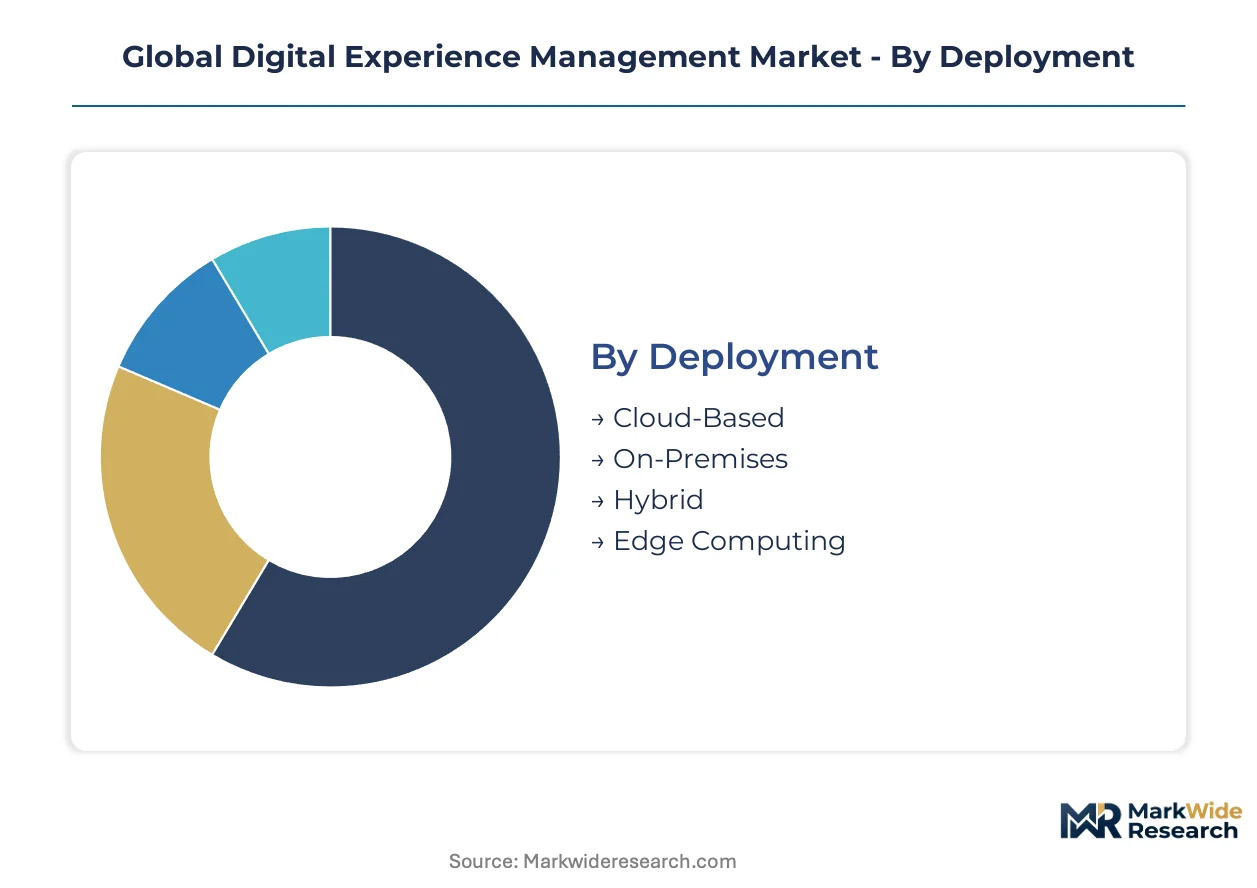
Deployment architecture determines latency thresholds and data sovereignty compliance for digital experience platforms. Solution type selection reflects enterprise maturity in personalization sophistication. Use case prioritization varies by industry regulatory exposure and customer touchpoint density.
Deployment:
Elastic infrastructure requirements shape how enterprises balance operational control against scalability.
- Cloud-Based:Multi-tenant architectures enable elastic scaling for seasonal traffic spikes in retail and travel sectors. Financial services firms in India and the United States deploy cloud-native stacks to compress time-to-value for personalization initiatives.
- On-Premises:Dedicated hardware installations maintain air-gapped data environments for classified government workloads and HIPAA-sensitive healthcare deployments. German automotive manufacturers retain on-premises customer data platforms to satisfy works council data governance requirements.
- Hybrid:Split architectures process anonymized behavioral data in cloud pipelines while keeping authenticated PII in controlled on-premises vaults. Japanese telecommunications operators favor hybrid models to navigate METI platform transparency guidelines.
- Edge Computing:Distributed processing nodes reduce round-trip latency for real-time personalization in physical retail and connected vehicle interfaces.
Cloud-Based leads on scale; Edge Computing leads on momentum.
Solution Type:
Functional module selection tracks enterprise investment priority in content operations versus customer intelligence.
- Personalization Engines:Real-time decisioning systems apply machine learning models to select optimal content variants for individual users. EU AI Act compliance mandates are accelerating replacement of opaque legacy recommendation systems in France and the Netherlands.
- Customer Analytics:Unified data pipelines consolidate behavioral signals across touchpoints to calculate propensity scores and churn risk. BFSI sector buyers in the United States and India prioritize analytics modules that integrate directly with core banking APIs.
- Content Management:Headless architectures decouple content repositories from presentation layers to enable omnichannel delivery.
- Campaign Management:Orchestration tools coordinate message timing and channel selection across paid, owned, and earned media.
- Social Media Management:Listening and response platforms monitor brand sentiment and manage community engagement at scale.
- Feedback Management:Survey and voice-of-customer systems close the loop between experience measurement and operational improvement.
Personalization Engines command the steepest expansion trajectory; Customer Analytics maintains the broadest cross-industry penetration.
Use Case:
Application prioritization reflects whether enterprises optimize for acquisition efficiency or retention depth.
- Customer Journey Mapping:Visualization tools model touchpoint sequences to identify friction points and drop-off stages. Procurement teams in telecommunications and energy utilities now evaluate journey orchestration as standalone software rather than bundled suite components.
- Omnichannel Engagement:Unified interaction layers synchronize messaging across web, mobile, contact center, and physical channels. Retailers in Germany and the United States deploy these capabilities fastest to compress path-to-purchase cycles.
- User Behavior Tracking:Event streaming infrastructure captures granular interaction data to feed machine learning pipelines.
- Conversion Rate Optimization:A/B testing and multivariate experimentation frameworks validate experience hypotheses with statistical rigor.
- Digital Asset Management:Centralized repositories govern brand asset versioning and rights management for distributed creative production.
Omnichannel Engagement leads on scale; Customer Journey Mapping leads on momentum.
End User Industry:
Sector-specific regulatory exposure and customer lifetime value economics shape platform requirements.
- BFSI:Banking and insurance deployments integrate experience platforms with core transactional systems to reduce acquisition costs. The Account Aggregator framework and UPI rails in India enable consent-based financial data sharing that powers native personalization channels.
- Telecommunications:Subscriber lifecycle management demands real-time experience orchestration across billing, support, and upgrade touchpoints. Legacy vendor relationships in this sector carry lower switching friction than in manufacturing.
- Education:Student engagement platforms must balance personalization against FERPA compliance and institutional data governance policies.
- Government:Citizen service portals prioritize accessibility standards and multilingual support over behavioral targeting sophistication.
- Travel & Hospitality:Booking engines and loyalty programs require real-time inventory integration with experience personalization.
BFSI leads on scale; Telecommunications leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Digital experience management platforms first achieved enterprise scale in the United States through early cloud computing adoption and venture capital concentration in Silicon Valley. The industry's geographic footprint now spans regulatory jurisdictions with divergent data governance frameworks.
United States
Financial services firms in New York and San Francisco deploy personalization engines to compress customer acquisition timelines. The SEC imposes sector-specific data governance requirements on investment management deployments. Healthcare systems in Boston integrate HIPAA-compliant patient journey mapping with electronic health record infrastructure.
Germany
Automotive manufacturers in Bavaria retain on-premises customer data platforms to satisfy works council data governance requirements. The GDPR mandates granular consent audit trails for behavioral targeting systems. Industrial clusters in Baden-Württemberg embed experience management into ERP-driven operational workflows.
India
Banking and insurance enterprises in Mumbai and Bangalore leverage the Account Aggregator framework for consent-based financial data sharing. RBI guidelines shape data localization requirements for core banking integrations. The UPI payment rails enable real-time personalization at transaction touchpoints.
France
Retail conglomerates in Paris deploy omnichannel engagement stacks to compress path-to-purchase cycles. The CNIL enforces algorithmic transparency mandates under EU AI Act risk classifications. Luxury goods houses in Lyon integrate customer analytics with heritage brand governance protocols.
Japan
Telecommunications operators in Tokyo favor hybrid deployment models to navigate METI platform transparency guidelines. The PMDA imposes documentation requirements on healthcare experience orchestration. Automotive suppliers in Nagoya struggle with legacy CRM integration complexity for real-time API connectivity.
Global Digital Experience Management Market Competitive Landscape
Premium-margin players sit above commodity-margin players across integration depth and compliance certification vectors. The vendor base organizes into three tiers: creative cloud-anchored suites, CRM-native personalization layers, and ERP-embedded operational data streams. Competitive intensity concentrates on M&A activity targeting customer data platform capabilities and strategic partnerships with hyperscale cloud providers.
Within the creative-to-experience workflow tier, Adobe and Sitecore occupy positions defined by content operations heritage. Salesforce exemplifies the CRM-native archetype through its personalization layer integration. SAP anchors the ERP-embedded segment by embedding experience management directly into operational data streams.
| Leading Market Players |
|---|
| Adobe |
| Salesforce |
| Oracle |
| SAP |
| Microsoft |
| IBM |
| Sitecore |
| Acquia |
| Liferay |
| Others |
Supply & Pricing Matrix
Platform certification tiers separate enterprise-grade compliance bundles from mid-market SaaS offerings, with that bifurcation manifesting in both annual contract values and the geographic concentration of implementation partners. Premium deployments command higher fees by embedding GDPR audit trails and EU AI Act explainability modules, while supply chains for these advanced configurations cluster around hyperscaler regions with dedicated compliance engineering capacity.
Pricing Analysis
Subscription tiers anchored to data volume and integration depth dominate vendor pricing architectures. Price differentiation separates cloud-native personalization engines from on-premises legacy migrations, with customization levels and after-sales implementation support as secondary drivers. Pricing pressure stems from composable architecture unbundling as procurement teams evaluate point solutions against bundled suites. Mid-market buyers exhibit highest price sensitivity due to identity resolution cost inflation from third-party cookie deprecation.
Supply Chain Analysis
Cloud infrastructure supply rests on United States hyperscaler concentration, with India and Germany emerging as secondary data sovereignty hubs for localized deployments. Compute instances, API middleware, and identity resolution services constitute critical input dependencies. Single-source vulnerability concentrates in United States cloud regions, creating exposure for global deployment footprints. Distribution runs through direct enterprise sales teams and certified implementation partners with vertical specialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in compliance-certified premium tiers as enterprises absorb 15-25% overhead increases for EU AI Act adherence. Cost compression in cloud infrastructure provisioning enables vendors to maintain pricing power while expanding implementation capacity.
For Market Incumbents: Acquire customer data platform capabilities to anchor composable architecture positioning against unbundling threats. Deepen vertical integration into edge computing infrastructure to reduce hyperscaler dependency exposure. Invest in explainable AI modules to capture GDPR-mandated replacement cycles in France and the Netherlands. For New Entrants and Emerging Players: Healthcare system partnerships offer the most penetrable channel for HIPAA-compliant patient journey mapping, where FDA guidance on digital therapeutics has created regulatory clarity. Target India's Account Aggregator-enabled financial services segment for consent-based data sharing integrations. Pursue API-first positioning to bypass legacy CRM integration complexity in German manufacturing and Japanese automotive sectors. For Investors and Strategic Acquirers: Asymmetric upside sits with customer data platform specialists possessing adjacent identity resolution capabilities. Long-term viability over the next decade hinges on regulatory divergence navigation between privacy-first jurisdictions and innovation-permissive markets. Watch for EU AI Act enforcement patterns as the primary inflection signal for compliance technology demand.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Customer data platform capabilities compress time-to-value for personalization deployments in BFSI sectors. |
| Platform Integration | ERP-native experience management embeds SAP and Oracle workflows into operational data streams for manufacturing. |
| Geographic Expansion | India's digital public infrastructure enables consent-based financial data sharing through Account Aggregator frameworks. |
| Product Launch | Explainable AI modules address EU AI Act risk classifications for high-risk personalization systems in healthcare. |
| Strategic Partnership | Hyperscaler alliances unlock elastic scaling capacity for seasonal retail traffic spikes without infrastructure ownership. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs, IT procurement officers, platform engineers, and integration specialists with secondary validation against SEC filings, hyperscaler capex disclosures, and regulatory submission databases. Bottom-up deployment estimates and top-down market sizing triangulated across cloud infrastructure spend patterns and enterprise software procurement records.
Comparable-period anchoring linked projection models to historical adoption curves across deployment architecture, solution type, and end-user industry dimensions. Segmentation modeling incorporated deployment model, organization size, vertical regulatory exposure, integration complexity, and regional adoption patterns. CAGRs derived from elasticity-adjusted spend trajectories and technology replacement cycle analysis, with inputs from GDPR compliance investment patterns and EU AI Act implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory enforcement divergence and hyperscaler concentration policy shifts. Forecasts reflect documented assumptions on enterprise digitization timelines and cloud migration velocity. A small set of triggers—including EU AI Act precedent cases and third-party cookie deprecation acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital Evidence Management System Market
Digital Solutions
Crop Management Software Market
Digital Solutions
Digital Certificates Market
Digital Solutions
Digital Notepad Market
Digital Solutions
Change and Configuration Management Market
Digital Solutions
Healthcare Computerized Maintenance Management System Market
Digital Solutions
Global Document Scanning Services Market
Digital Solutions
Global Content Recommendation Engine Market
Digital Solutions
Business As a Service Market
Digital Solutions
Europe Content Moderation Services Market
Digital Solutions
Advanced Drill Data Management Solutions Market
Digital Solutions
Asia-Pacific Multichannel Order Management Market
Digital Solutions
Coin Sorter Machines Market
Digital Solutions
Returnless Refund Fraud Detection Market
Digital Solutions
Cloud Video Conferencing Market
Digital Solutions
Water Level and Storage Monitoring Software Market