
 Global Bug Tracking Software Market | 2026-2036
Global Bug Tracking Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bug Tracking Software Market Foresight
Mid-market SaaS vendors are redrawing demand patterns as they displace legacy on-premise installations across software development teams. Atlassian leverages its Jira ecosystem to anchor workflows across agile development pipelines. IBM competes through enterprise-grade governance features that satisfy heavily regulated industries. Sentry differentiates via real-time error monitoring that integrates directly into continuous deployment toolchains.
Bug tracking software comprises systems that log, prioritize, assign, and trace resolution of software defects through structured workflows with audit trails and SLA enforcement. These platforms serve as the operational backbone for quality assurance, enabling teams to correlate code commits with incident reports and measure mean-time-to-resolution metrics. Cloud-based deployment leads solution type adoption as organizations abandon server maintenance overhead, while issue tracking functionality remains the core module though test management integration is expanding fastest among DevOps-mature teams. Enterprise customer types generate the dominant revenue share, yet IT consultancies represent the fastest-growing segment as outsourced quality assurance expands.
The EU AI Act, GDPR data residency provisions, and India's CERT-In cybersecurity directives collectively shape product architecture decisions across vendors. FDA software validation requirements for medical device code and ISO 9001 quality management standards further constrain how bug tracking systems record and report defect remediation in regulated environments. Stakeholders must monitor evolving cross-border data flow restrictions and their compounding effect on cloud deployment choices.
Market Dynamics
DevOps toolchain consolidation is compressing standalone bug tracking into integrated platform suites, forcing vendors to embed defect management within broader CI/CD orchestration layers or face displacement by native capabilities from cloud providers.
Growth Catalysts
- EU AI Act compliance mandates:Software quality documentation requirements for high-risk AI systems are expanding audit trail depth in defect tracking workflows across European enterprises.
- India's CERT-In cybersecurity directives:Incident reporting timelines for critical software vulnerabilities are tightening SLA enforcement mechanisms in bug tracking deployments.
- Medical device software validation:FDA 21 CFR Part 820 quality system regulations are elevating traceability requirements from code commit through defect resolution in regulated healthcare technology development.
Market Restraints
- Cloud data residency friction:India's data localization rules and China's cybersecurity law are fragmenting deployment architectures and inflating infrastructure redundancy costs for multinational vendors.
- Open-source substitution pressure:GitHub Issues and GitLab's native tracking modules are capturing price-sensitive development teams, compressing commercial software addressable market at the low end.
- Integration tax accumulation:Enterprise buyers face mounting connector licensing costs to bridge bug tracking systems with specialized test automation and security scanning tools.
Strategic Opportunities
- German automotive software quality surge:ISO 26262 functional safety requirements for autonomous vehicle code are creating specialized defect classification and verification workflow demand.
- IT consultancy channel expansion:Outsourced quality assurance providers in India and Poland are white-labeling bug tracking infrastructure for mid-market clients lacking internal DevOps maturity.
- AI-assisted triage convergence:Natural language processing integration with static analysis tools is enabling automated severity scoring and duplicate detection in high-volume defect queues.
Industry Challenges
- Legacy mainframe integration complexity:Financial services institutions in the United States and Japan struggle to bridge COBOL-era change management protocols with modern agile defect workflows.
- Multi-cloud credential synchronization:Engineering teams managing defects across AWS, Azure, and Google Cloud environments face identity federation failures that fragment audit trails.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bug Tracking Software Market |
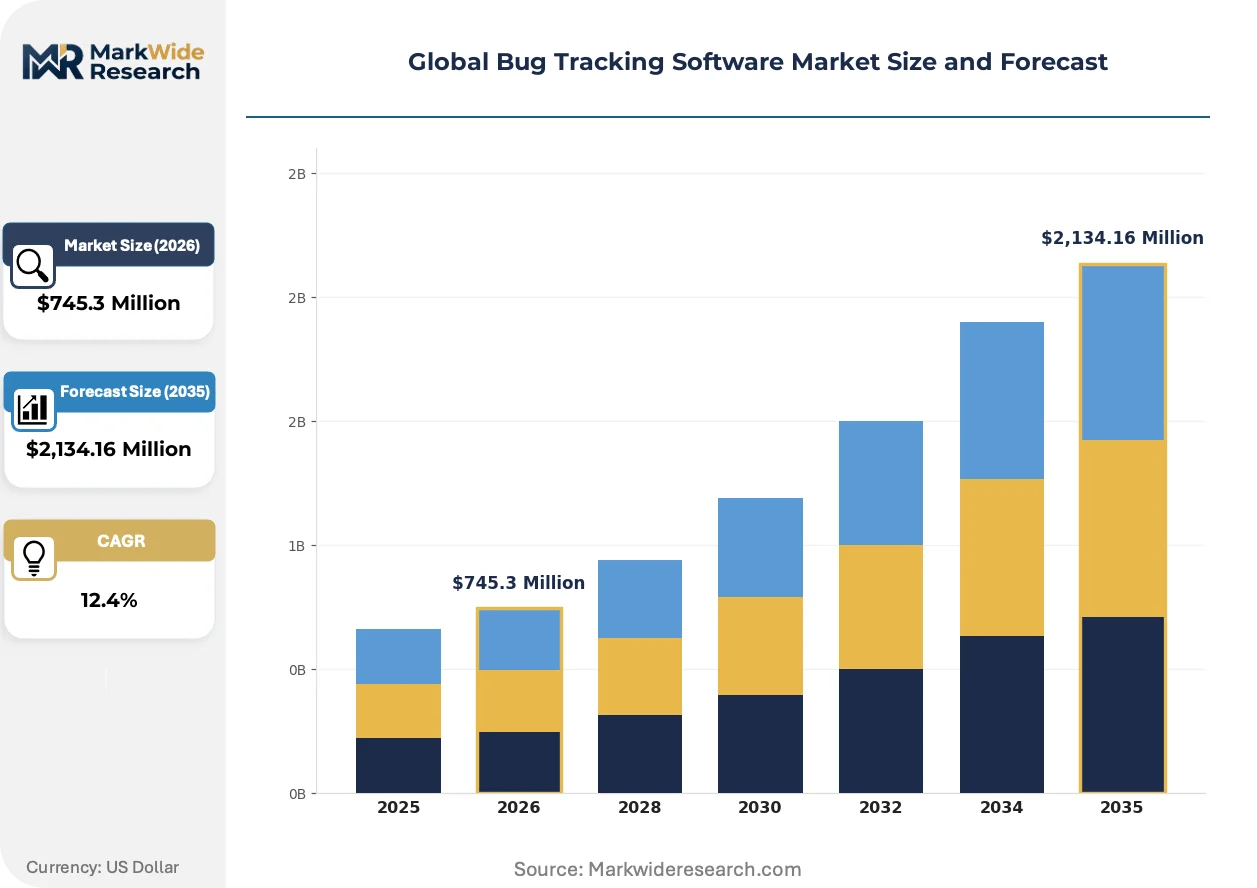
| Market Size in 2026 | $745.3 Million |
| Market Size in 2035 | $2,134.16 Million |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Private Cloud, Public Cloud Solution Type: Issue Tracking, Project Management, Test Management, Release Management, Change Management Use Case: Software Development, Quality Assurance, Customer Support, Operations Management, Product Management Customer Type: Enterprises, Small and Medium Businesses, Independant Developers, IT Consultancies |
| Companies Covered | Atlassian, IBM, Zoho Corporation, JetBrains, Inflectra Corporation, Axosoft, Bugsnag, Raygun, Sentry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bug Tracking Software Market Shifts & Advancements
Real-time observability pipelines are merging with defect management systems, collapsing the latency between production error detection and ticket creation. This convergence is redefining vendor competitive moats around data ingestion scale and automated root-cause correlation.
Edge-deployed error capture agents are miniaturizing data collection footprints for IoT firmware diagnostics. Industrial manufacturers in Germany and Japan are adopting these lightweight SDKs to monitor embedded software health without cloud round-trip delays. The technology is miniaturizing acceptable telemetry overhead thresholds, enabling defect tracking penetration into resource-constrained device categories previously excluded from systematic monitoring.
CSRD sustainability reporting requirements in Europe are extending software carbon footprint disclosure to development operations. Defect resolution energy consumption metrics and CI/CD pipeline emissions are entering procurement evaluation criteria for enterprise buyers in the Netherlands and France. Quality assurance teams must now correlate bug fix velocity with infrastructure utilization efficiency to satisfy emerging ESG data requests.
Subscription fatigue among mid-market software teams is reviving interest in usage-based pricing for defect tracking capacity. Buyers in the United States and United Kingdom are negotiating event-volume tiers rather than seat-based licenses, aligning costs with actual development activity fluctuations. This model shift pressures vendors to instrument granular consumption metering and threatens traditional per-user revenue predictability.
Global Bug Tracking Software Market Segmentation
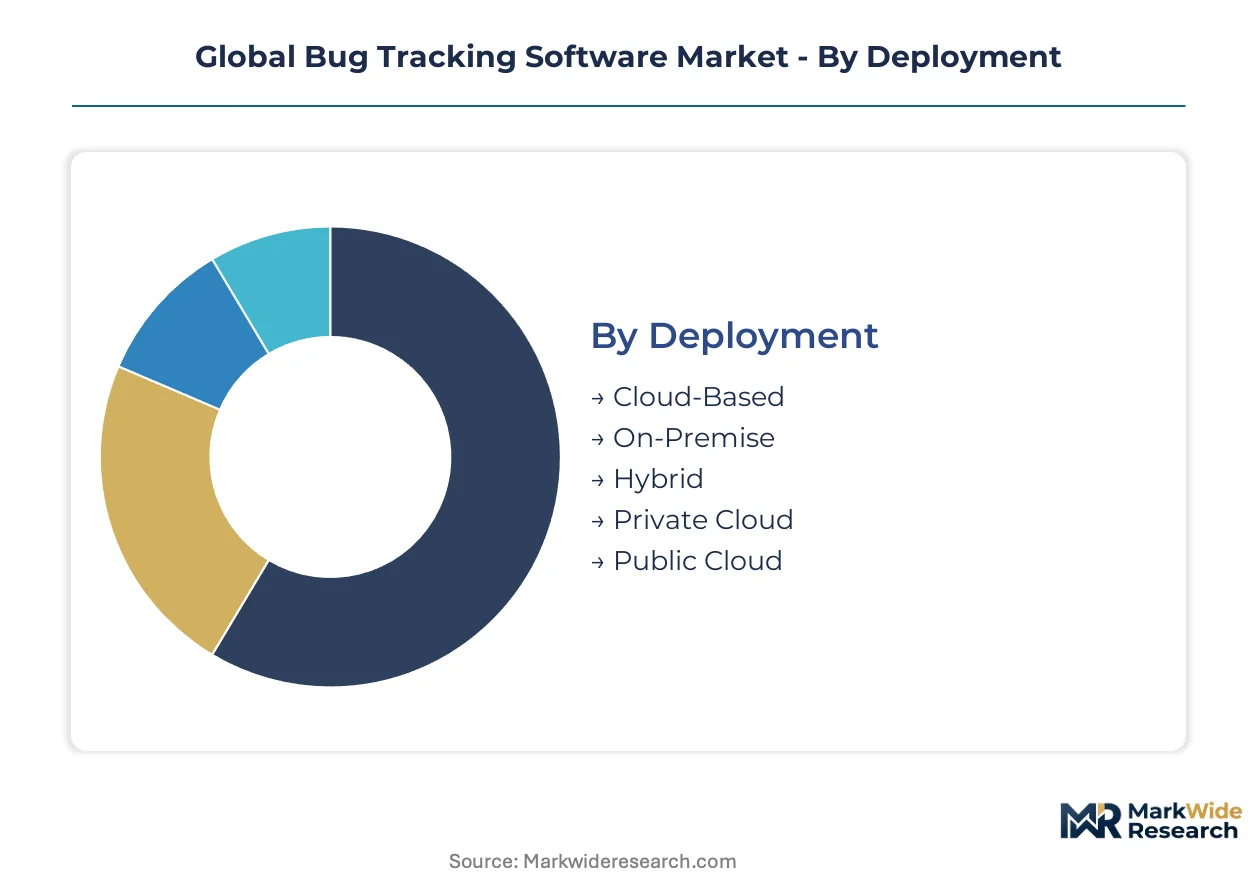
Bug tracking software vendors structure their go-to-market strategies around deployment flexibility and buyer sophistication tiers. Channel economics vary sharply between self-serve cloud adoption and enterprise procurement cycles requiring compliance documentation.
Deployment:
Cloud-based delivery dominates direct sales channels, while on-premise and hybrid configurations flow through systems integrators and value-added resellers serving regulated industries.
- Cloud-Based:Multi-tenant SaaS architecture eliminates infrastructure overhead for development teams. United States-based agile software houses favor this model for rapid scaling without capital expenditure commitments.
- On-Premise:Self-hosted installations within customer data centers satisfy air-gapped security requirements. German automotive suppliers and Japanese financial institutions mandate this deployment for firmware development workflows under strict data sovereignty protocols.
- Hybrid:Split architectures keep sensitive defect data on-premise while leveraging cloud analytics layers. Indian IT consultancies deploy hybrid configurations to serve clients with mixed compliance obligations across jurisdictions.
- Private Cloud:Dedicated single-tenant environments hosted in third-party facilities. Healthcare technology developers in the United States select this model to satisfy HIPAA technical safeguards while avoiding capital-intensive data center ownership.
- Public Cloud:Shared infrastructure across AWS, Azure, and Google Cloud marketplaces. Mid-market software startups in the United Kingdom and Netherlands consume public cloud bug tracking through marketplace procurement to consolidate vendor management.
By volume, Cloud-Based leads. By growth pace, Hybrid is climbing the fastest as multinational enterprises navigate fragmented data residency requirements.
Solution Type:
Cost tier differentiation separates commodity issue logging from premium orchestration suites commanding higher per-seat economics.
- Issue Tracking:Core defect logging, prioritization, and assignment workflows with audit trails. This foundational module captures the largest user base across all customer segments but faces margin pressure from open-source alternatives.
- Project Management:Sprint planning, resource allocation, and burndown charting integrated with defect queues. DevOps-mature teams in Germany and the United States pay premium pricing for unified work management rather than maintaining separate tools.
- Test Management:Test case design, execution tracking, and coverage analysis linked to defect discovery. Quality assurance departments in medical device companies require this integration to satisfy FDA software validation documentation requirements.
- Release Management:Deployment orchestration, rollback procedures, and release note generation tied to resolved defects. CI/CD pipeline vendors embed native capabilities here, compressing standalone solution addressable market.
- Change Management:Configuration control, impact assessment, and approval workflows for production code modifications. Financial services institutions in the United States and Japan deploy this module to bridge COBOL-era governance with modern agile practices.
By installed base, Issue Tracking holds the largest footprint. By expansion trajectory, Test Management is gaining share fastest as quality engineering integrates upstream into development pipelines.
Use Case:
Application maturity determines feature depth requirements, with customer support and operations management representing emerging adjacencies beyond traditional development-centric adoption.
- Software Development:Defect detection, triage, and resolution workflows embedded within IDE and version control environments. Engineering teams in India and Poland constitute the densest concentration of this core use case.
- Quality Assurance:Systematic test execution, regression validation, and defect verification protocols. ISO 9001-certified manufacturers in Germany extend QA bug tracking to embedded software in industrial automation equipment.
- Customer Support:Ticket-to-defect linking that converts user-reported issues into engineering backlog items. SaaS vendors in the United States deploy this integration to reduce mean-time-to-resolution for production incidents.
- Operations Management:Infrastructure monitoring alerts feeding directly into defect tracking systems. Site reliability engineering teams in cloud-native enterprises treat service degradation as software defects requiring code-level remediation.
- Product Management:Roadmap prioritization informed by defect severity and customer impact scoring. B2B software companies in the United Kingdom use this linkage to align engineering capacity with revenue-at-risk calculations.
By deployment scale, Software Development remains dominant. By adoption velocity, Customer Support is expanding most quickly as support organizations seek tighter engineering collaboration.
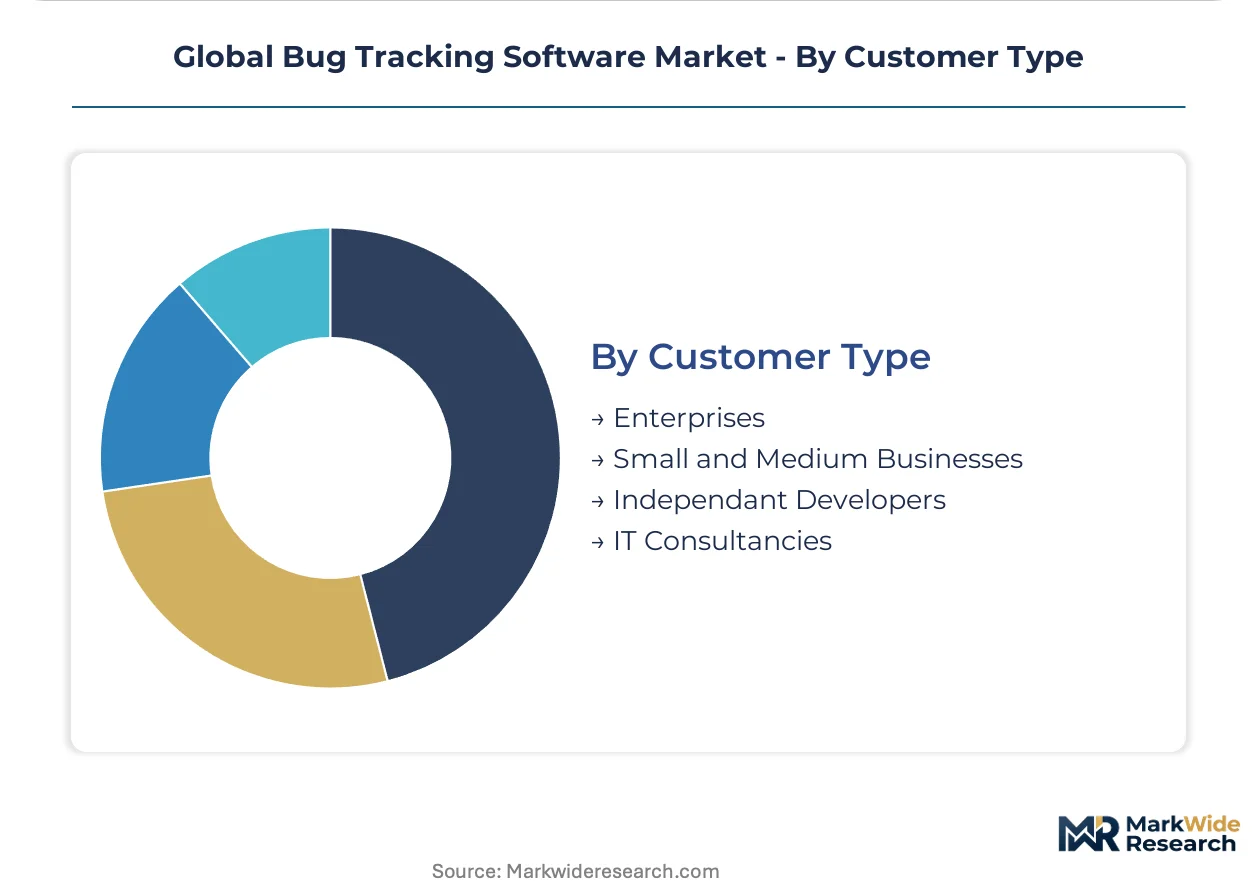
Customer Type:
Volume concentration and margin profiles diverge sharply between procurement-savvy enterprises and price-sensitive independent practitioners.
- Enterprises:Multi-department deployments with custom integration requirements and SLA guarantees. Fortune 500 technology divisions in the United States negotiate three-year contracts with dedicated customer success management.
- Small and Medium Businesses:Department-level adoption with standardized configurations and credit-card procurement. Software agencies in the Netherlands and France select mid-tier SaaS tiers balancing functionality against subscription cost discipline.
- Independent Developers:Solo practitioners and micro-teams consuming freemium tiers or open-source alternatives. This segment exhibits highest price elasticity and lowest switching costs in the market structure.
- IT Consultancies:Outsourced quality assurance providers white-labeling or reselling bug tracking infrastructure. Polish and Indian service providers represent the steepest expansion trajectory as nearshore delivery models mature.
By revenue contribution, Enterprises generate the largest share. By growth pace, IT Consultancies are pulling ahead as outsourced testing penetrates mid-market accounts lacking internal DevOps capability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor infrastructure concentrates most densely in the United States, Germany, and India, where software development and quality assurance operations cluster around major technology hubs and regulatory frameworks mandate systematic defect documentation.
United States
Enterprise IT departments and SaaS vendors drive procurement volume across agile development pipelines. FDA software validation requirements for medical device code elevate traceability standards in healthcare technology clusters around Boston and San Francisco. The FDA's 21 CFR Part 820 quality system regulations compel defect resolution audit trails from code commit through production release.
Germany
Automotive software quality demands surge under ISO 26262 functional safety requirements for autonomous vehicle code. The EU AI Act compliance mandates expand audit trail depth in defect tracking workflows across Stuttgart and Munich engineering centers. German automotive suppliers mandate on-premise deployments for firmware development under strict data sovereignty protocols.
India
IT consultancies and outsourced quality assurance providers represent the fastest-expanding customer segment in Bangalore and Hyderabad. CERT-In cybersecurity directives tighten incident reporting timelines for critical software vulnerabilities. Indian service providers deploy hybrid configurations to serve multinational clients with mixed compliance obligations across jurisdictions.
United Kingdom
B2B software companies and mid-market SaaS vendors concentrate procurement evaluation in London and Manchester. CSRD sustainability reporting requirements extend software carbon footprint disclosure to development operations. Quality assurance teams correlate bug fix velocity with infrastructure utilization efficiency to satisfy emerging ESG data requests.
Japan
Financial services institutions struggle to bridge COBOL-era change management protocols with modern agile defect workflows in Tokyo and Osaka. METI industrial standards shape procurement criteria for manufacturing software quality systems. Japanese industrial automation equipment manufacturers extend QA bug tracking to embedded software under ISO 9001 certification requirements.
Global Bug Tracking Software Market Competitive Landscape
Concentration sits with platform ecosystems and specialized monitoring vendors that anchor distinct workflow layers. The vendor base spans consolidated platform players with broad DevOps integration and focused error-monitoring specialists with deep telemetry capabilities. Three archetypes dominate: ecosystem-anchored suites, enterprise governance platforms, and real-time observability tools. Competitive moves center on CI/CD pipeline embedding and multi-cloud credential federation partnerships.
Within the ecosystem-anchored tier, Atlassian exemplifies platform consolidation through workflow integration across agile pipelines. IBM occupies a position serving heavily regulated industries with governance-centric architectures. Sentry represents the real-time observability vector, embedding error capture directly into continuous deployment toolchains. These three anchors illustrate how competitive positioning diverges between breadth-first platform strategies and depth-first monitoring specialization.
| Leading Market Players |
|---|
| Atlassian |
| IBM |
| Zoho Corporation |
| JetBrains |
| Inflectra Corporation |
| Axosoft |
| Bugsnag |
| Raygun |
| Sentry |
| Others |
Supply & Pricing Matrix
Multi-tenant cloud infrastructure scale economies in the United States and India compress marginal delivery costs below on-premise alternatives, concentrating vendor pricing power among hyperscaler-aligned platforms while forcing regional resellers into thin-margin implementation services.
Pricing Analysis
Volume-discount tiering structures separate enterprise deployments with custom SLA guarantees from mid-market SaaS tiers and freemium entry points for independent developers. Pricing stratifies across premium governance modules, standard agile workflows, and economy issue-logging tiers, with FDA validation certification and EU AI Act compliance documentation commanding substantial premiums in regulated verticals. Cost compression in the mid-market tier intensifies because GitHub Issues and GitLab native modules capture price-sensitive teams with zero marginal pricing. Independent developers exhibit highest price sensitivity, while Fortune 500 technology divisions demonstrate lowest elasticity due to switching cost entrenchment and audit trail requirements.
Supply Chain Analysis
The United States anchors hyperscaler cloud infrastructure and platform engineering talent pools, while India supplies outsourced quality assurance labor and white-label implementation services, and Germany hosts specialized automotive compliance tooling development. Core inputs draw from open-source telemetry libraries, third-party identity federation services, and static analysis engine APIs. Single-source vulnerability concentrates in AWS Marketplace distribution chokepoints for mid-market procurement. Distribution runs through direct SaaS self-serve portals, systems integrator channels for regulated industries, and IT consultancy resellers serving DevOps-immature clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in switching cost entrenchment: once engineering teams embed defect workflows across CI/CD pipelines and correlate historical resolution data with code repositories, migration costs exceed rational reevaluation thresholds.
For Market Incumbents: Compound platform stickiness through deeper IDE embedding and native security scanning integration to neutralize GitLab and GitHub native module substitution. Prioritize vertical integration into test automation tooling to capture quality engineering budget consolidation. Defend against Sentry's real-time observability encroachment by matching millisecond-latency error ingestion capabilities.
For New Entrants and Emerging Players: Differentiate on AI-assisted triage automation for high-volume defect queues where incumbent rule-based systems create resolution latency. Target IT consultancies in Poland and India as the most penetrable channel, exploiting their need for white-label infrastructure without internal platform development capacity. Pursue usage-based pricing models to exploit subscription fatigue among United Kingdom and United States mid-market buyers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized observability vendors with deep telemetry pipelines over horizontal platform suites facing consolidation pressure. Long-term viability rests on data ingestion scale moats and automated root-cause correlation algorithms that compound with deployment footprint. Monitor CERT-In directive enforcement intensity in India as an inflection indicator for compliance-documentation premium expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding defect management within CI/CD orchestration layers neutralizes displacement risk from cloud provider native capabilities. |
| Acquisition of Specialist Firm | Consolidating test automation or static analysis vendors captures quality engineering budget upstream of traditional bug tracking procurement. |
| Geographic Expansion | Establishing data residency-compliant infrastructure in Germany and India satisfies EU AI Act and CERT-In mandates for multinational clients. |
| Strategic Partnership | Aligning with hyperscaler marketplaces accelerates mid-market procurement through consolidated vendor management and pre-negotiated enterprise terms. |
| Product Launch | Introducing edge-deployed error capture SDKs penetrates IoT firmware diagnostics markets in German and Japanese industrial automation sectors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and EU regulatory documentation to construct demand-side validation. Primary interviews engaged CTOs at SaaS vendors, IT procurement officers at Fortune 500 enterprises, platform engineers at DevOps-mature organizations, and channel partners serving regulated industries. Bottom-up deployment estimates triangulate against top-down IT spend allocation models across cloud infrastructure and quality assurance budget categories.
Segmentation dimensions modeled span deployment architecture, organization size tier, vertical industry, integration complexity level, and regional regulatory cluster across the projection horizon. CAGRs derive from fitted growth curves calibrated to historical adoption velocity in comparable software tooling categories, with specific inputs including CI/CD pipeline penetration rates and outsourced quality assurance expansion trajectories in India and Poland.
Decision-makers should treat outputs as directional under assumptions of sustained cloud migration momentum and stable cross-border data flow regimes; material deviation in trade policy or cybersecurity directive enforcement would warrant model refresh. Recalibration cycles align with material shifts in EU AI Act implementation guidance and CERT-In incident reporting timeline adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Sales Compensation Software Market
Software & Services
Lead-To-Account Matching and Routing Software Market
Software & Services
Mindfulness Meditation Application Market
Software & Services
Global Application Platform Market
Software & Services
Data Visualization Software Market
Software & Services
Productivity Management Software Market
Software & Services
Workflow Automation and Optimization Software Market
Software & Services
Expense Management Software Market
Software & Services
Global Gym Software Market
Software & Services
Over-The-Air Software Update Market
Software & Services
Global Cloud-Based Call Center Software Market
Software & Services
Global Self-Service BI Market
Software & Services
Global Business Card Software Market
Software & Services
Labeling Software Market
Software & Services
Europe Digital Signage Software Market
Software & Services
Landing Page Creation Software Market