
 HACCP Software Market | 2026-2036
HACCP Software Market Size, Share, and Industry Trends Forecast 2026-2036
HACCP Software Market Insights
Restaurant chains and institutional foodservice operators is pivoting toward automated hazard controls, replacing paper-based logs with digital workflows. SafetyChain Software leverages cloud infrastructure to anchor North American mid-market penetration. FoodDocs competes through template-driven compliance engines tailored for multi-location operators. Intelex Technologies extends its position by integrating HACCP modules into broader EHS platforms.
HACCP software comprises digital platforms that automate hazard analysis, critical control point monitoring, and corrective action documentation for food safety management systems. These platforms typically incorporate temperature logging, supplier verification, and audit trail generation to prevent biological, chemical, and physical contamination across food production and service operations. Cloud-based deployment leads the software type category by reducing IT overhead for small and mid-sized processors, while mobile applications represent the fastest-expanding segment as field inspectors and kitchen managers demand real-time data entry. The feature set dimension shows compliance management modules capturing the deepest margin pools due to recurring subscription structures tied to regulatory update cycles.
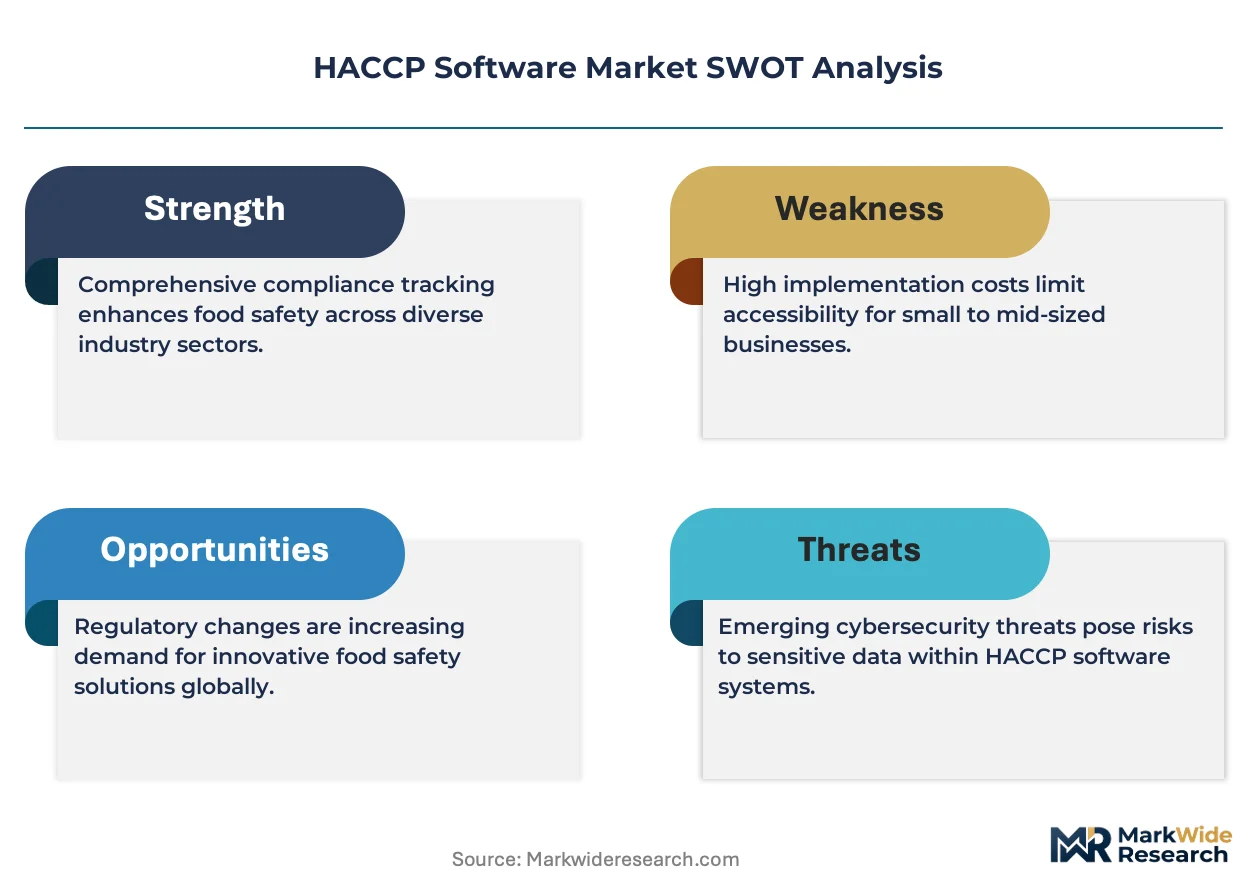
The FDA enforces Hazard Analysis and Risk-based Preventive Controls under FSMA, compelling covered facilities to maintain verifiable digital records accessible during inspections. The EU's Hygiene Package and EFSA guidance on food contact materials shape product standards for exporters serving European retail channels. China's SAMR and NMPA-aligned food safety standards are tightening import documentation requirements. Stakeholders must monitor how regulatory divergence between jurisdictions affects software localization costs and validation protocols.
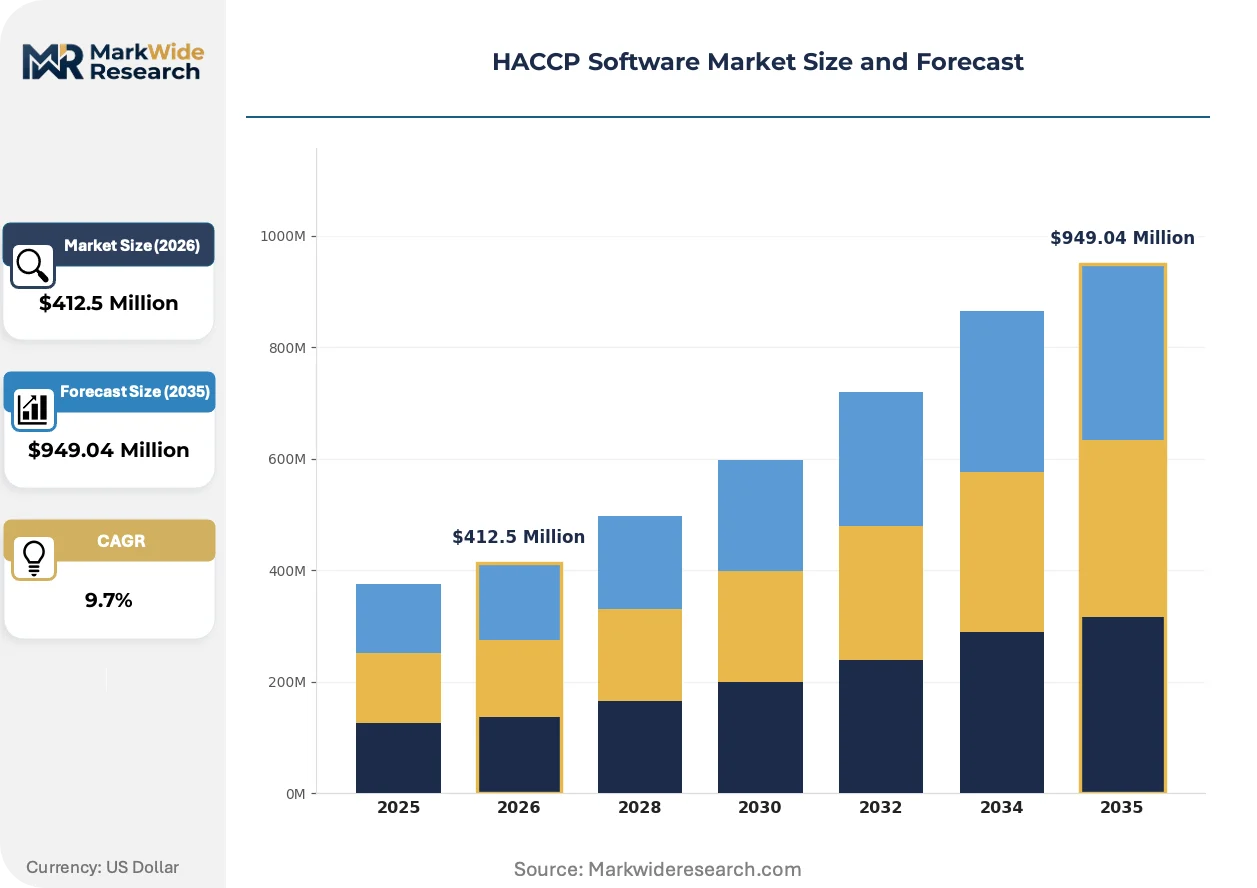
Market Dynamics
Cloud migration is compressing deployment timelines for hazard analysis platforms as food processors abandon on-premise infrastructure. This structural shift is redistributing vendor power toward subscription-native software providers and away from legacy license-model incumbents.
Growth Catalysts
- FSMA Rule 204:The FDA's enhanced traceability requirements mandate electronic record-keeping for high-risk foods, compelling domestic processors to digitize HACCP workflows ahead of enforcement deadlines.
- Cold-chain expansion:Frozen food logistics operators in Germany and China are deploying temperature-monitoring modules to satisfy import documentation standards for retail channel access.
- IoT sensor proliferation:Wireless temperature probes and pH meters are dropping below $15 per unit, enabling real-time CCP monitoring in mid-scale bakeries and meat processing plants previously priced out of automation.
Market Restraints
- Implementation cost barriers:Multi-site foodservice operators face $50,000-$150,000 first-year outlays for enterprise HACCP suites, excluding hardware and retraining, freezing out independent restaurant groups.
- Data localization mandates:China's SAMR requires domestic hosting of food safety records, forcing foreign vendors to establish local cloud infrastructure or cede market position to domestic competitors.
- Interoperability gaps:Proprietary data formats from incumbent ERP systems resist seamless HACCP module integration, extending deployment timelines and inflating customization costs.
Strategic Opportunities
- Smallholder integration:Template-driven mobile applications can capture India's fragmented dairy and spice processing sectors currently operating on paper-based hazard logs.
- Blockchain audit trails:Distributed ledger technology is unifying supplier verification with retail traceability requirements, creating premium positioning for vendors serving export-oriented seafood processors.
- EU Green Deal alignment:Carbon footprint tracking modules appended to HACCP platforms can access sustainability-linked procurement budgets from European retail chains.
Industry Challenges
- Food safety technologist scarcity:Qualified professionals who bridge microbiology expertise with software configuration are concentrated in the United States and Western Europe, slowing rollout in emerging markets.
- Validation protocol complexity:Software-as-a-medical-device frameworks from FDA and EMA are bleeding into food safety platform certification, extending time-to-market for predictive analytics features.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HACCP Software Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $949.04 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Software Type: Cloud-based, On-premise, Mobile Applications, Desktop Applications End User: Food Manufacturers, Restaurants, Catering Services, Retail Deployment Model: Single Tenant, Multi-tenant, Hybrid, Private Cloud Feature Set: Real-time Monitoring, Reporting Tools, Compliance Management, Risk Assessment |
| Companies Covered | Zip HACCP, FoodDocs, SafetyChain Software, Momentum, EtQ, FoodLogiQ, Safefood 360, IONI, Intelex Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HACCP Software Market Trends and Innovations
Artificial intelligence is penetrating hazard prediction workflows, shifting competitive advantage from documentation tools toward anticipatory risk platforms. Vendors are racing to embed machine learning models that flag contamination probabilities before critical control points breach thresholds.
Sensor-to-cloud architecture is unifying previously siloed temperature, humidity, and allergen testing data into single-pane dashboards. Quick-service restaurant chains with 500-plus locations are adopting these integrated stacks fastest, compressing incident response times from hours to minutes and reducing insurance premiums through demonstrable risk reduction.
EFSA's updated guidance on food contact materials is tightening documentation requirements for packaging migrants and chemical hazards. Export-oriented processors serving European retail channels are reconfiguring supplier questionnaires and testing protocols to satisfy these standards, with software vendors embedding EFSA-aligned templates as default configurations for EU-bound customers.
Subscription pricing is displacing perpetual licenses across mid-market buyers, with annual contracts tied to regulatory update cycles replacing upfront capital expenditure. Food manufacturers with volatile production schedules prefer this operational expenditure model, particularly in seasonal agricultural processing verticals where capacity fluctuates dramatically.
HACCP Software Market Segmentation
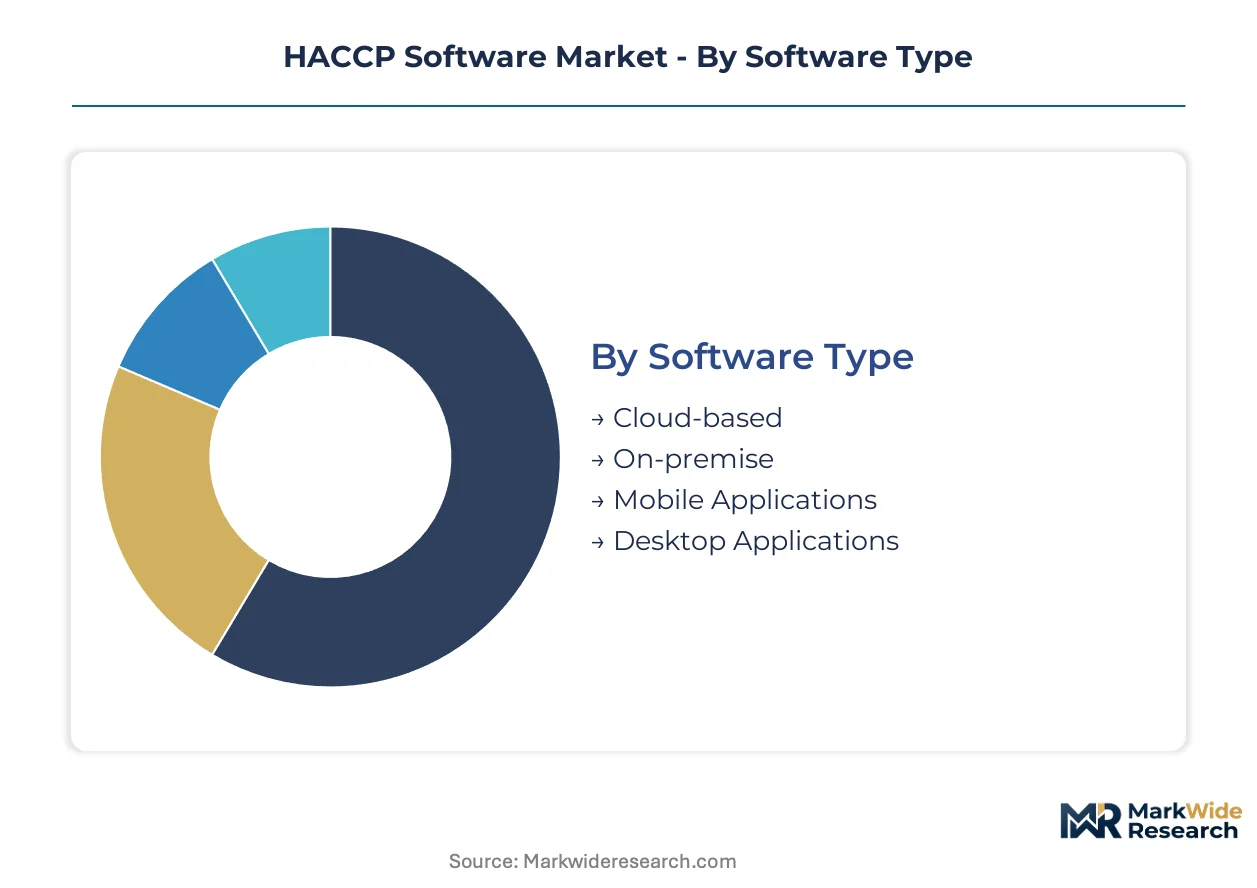
Segmentation in HACCP software reveals how regulatory complexity and operational scale drive purchasing decisions. Food processors select platforms based on deployment constraints, audit frequency, and integration requirements with existing quality management infrastructure.
Software Type:
Cloud-based deployments require ISO 27001 certification and SOC 2 attestation for enterprise buyers, while mobile applications face additional FDA 21 CFR Part 11 validation for electronic records in US facilities.
- Cloud-based:Browser-accessible platforms with centralized data storage eliminate server maintenance for mid-sized processors. Demand concentrates in Germany and the United States where multi-site operators need unified dashboards across production facilities. FSMA's electronic record accessibility mandates accelerate replacement of paper-based systems.
- Mobile Applications:Native iOS and Android tools enable real-time CCP data entry by floor supervisors and field inspectors. Quick-service restaurant chains with 500-plus locations adopt these fastest for instant corrective action alerts. Battery optimization and offline synchronization remain technical hurdles in cold-storage environments.
- On-premise:Locally installed software persists in defense and aerospace foodservice contractors with air-gapped security requirements.
- Desktop Applications:Single-workstation licenses serve small bakeries and butcher shops with limited connectivity and minimal IT support.
Cloud-based sits at the top of the volume ranking, with mobile applications climbing the fastest.
End User:
Cost tiering separates enterprise suites from entry-level subscriptions, with per-location pricing creating distinct bands for multinational manufacturers versus independent operators.
- Food Manufacturers:High-volume processors of meat, dairy, and ready-to-eat meals require batch-level traceability and supplier verification modules. China's SAMR documentation standards for imported ingredients drive platform upgrades among export-oriented seafood and spice processors. Integration with MES and ERP systems dominates procurement criteria.
- Restaurants:Full-service and quick-service chains deploy temperature logging and allergen tracking to reduce liability exposure. Regional franchise operators in the United States favor template-driven configurations that accelerate multi-unit rollout without dedicated food safety technologists.
- Catering Services:Event-based and institutional caterers prioritize mobile-first tools for off-site preparation and transport monitoring.
- Retail:Supermarket delis and in-store bakery operations seek lightweight solutions connected to corporate quality portals.
Food Manufacturers command the largest subscription base, with Restaurants expanding most quickly as franchise systems standardize digital hazard controls.
Deployment Model:
Application criticality determines infrastructure investment, with preventive controls for high-risk foods demanding isolated environments while routine documentation tolerates shared resources.
- Multi-tenant:Shared infrastructure with logical data separation delivers lowest per-seat cost for restaurant groups and small processors. Automatic updates align with evolving FDA guidance documents without IT intervention.
- Private Cloud:Dedicated virtual environments serve European retailers with GDPR-mandated data residency and encryption standards. German discount grocery chains specify Frankfurt-region hosting for supplier audit records.
- Single Tenant:Isolated instances support defense contractors and nuclear facility foodservice with customized security baselines.
- Hybrid:Split architectures process sensitive formulation data on-premise while pushing non-critical temperature logs to public cloud for analytics.
Multi-tenant captures the deepest market penetration, with Private Cloud gaining share fastest among EU-facing exporters.
Feature Set:
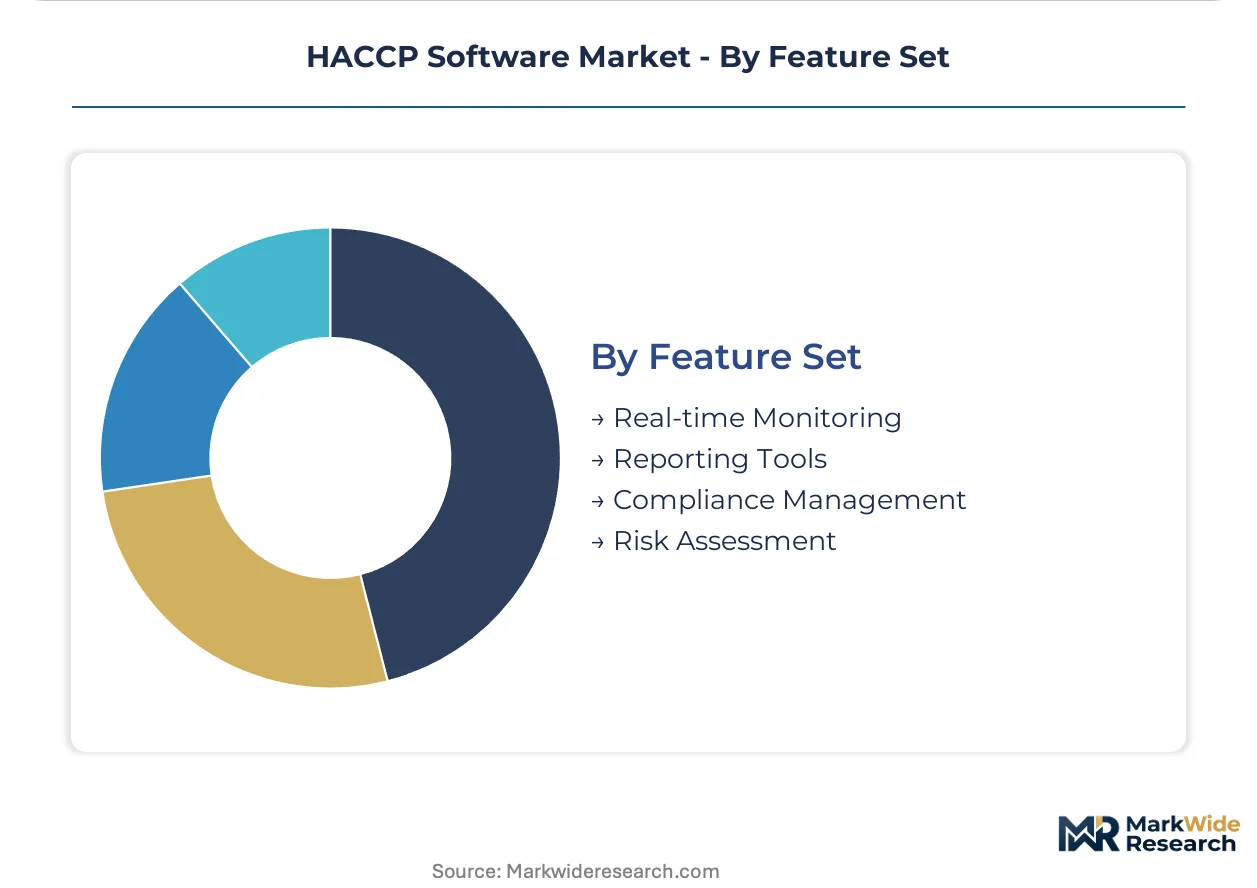
Margin concentration follows regulatory update cycles, with compliance modules commanding premium subscriptions tied to evolving FDA, EFSA, and SAMR guidance.
- Compliance Management:Automated template updates for FSMA, EU Hygiene Package, and GB standards reduce audit preparation labor. Recurring revenue models attach to regulatory change notifications, creating sticky relationships with export-dependent processors in China and Vietnam.
- Real-time Monitoring:IoT sensor integration for temperature, humidity, and pH enables immediate corrective action before product deviation. Cold-chain logistics operators in Germany deploy these modules to satisfy retail channel documentation requirements.
- Reporting Tools:Customizable dashboards and automated regulatory submissions streamline inspector interactions for mid-market manufacturers.
- Risk Assessment:Predictive algorithms flag contamination probabilities based on historical CCP data and supplier performance scores.
Compliance Management leads feature prioritization, with Real-time Monitoring showing the steepest expansion trajectory as sensor costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping HACCP software procurement as food exporters relocate production to jurisdictions with harmonized compliance costs. The United States, Germany, and China enforce the strictest digital documentation mandates, while emerging processors in Vietnam and Mexico face pressure to upgrade systems for market access.
United States
Multi-site restaurant chains and frozen food processors drive cloud-based HACCP adoption. FDA's FSMA Rule 204 mandates electronic traceability records for high-risk foods by enforcement deadlines. Chicago-area meatpacking facilities and California central valley produce processors are replacing paper logs with automated temperature monitoring to satisfy inspector accessibility requirements.
Germany
Discount grocery chains and cold-chain logistics operators anchor European demand for real-time monitoring modules. EU Hygiene Package directives and EFSA guidance on food contact materials shape software specifications for exporters. Frankfurt-region hosting clusters serve private cloud deployments for retailers requiring GDPR-compliant supplier audit trails.
China
Export-oriented seafood and spice processors upgrade platforms to satisfy SAMR documentation standards for imported ingredients. NMPA-aligned food safety standards and data localization mandates force foreign vendors to establish domestic cloud infrastructure. Qingdao and Dalian port-zone processors deploy temperature-logging systems to access European and North American retail channels.
Vietnam
Fragmented coffee and aquaculture sectors present template-driven mobile application opportunities as operators transition from paper-based hazard logs. FSSAI-equivalent national standards are tightening for EU-bound exporters. Ho Chi Minh City-based aggregators are piloting subscription compliance tools for smallholder integration into certified supply chains.
Mexico
Produce exporters serving US retail channels face pressure to digitize HACCP workflows for FDA inspection readiness. NOM-251 sanitation standards are converging with FSMA preventive controls frameworks. Guanajuato and Sinaloa agricultural clusters are adopting cloud platforms to maintain berry and tomato export certifications.
HACCP Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with subscription-native vendors capturing mid-market foodservice while legacy license incumbents defend enterprise manufacturing accounts. Market structure tilts toward consolidation in compliance management modules where recurring regulatory update cycles create sticky relationships. Three archetypes dominate: cloud-first SaaS providers with rapid deployment capabilities, EHS platform extenders integrating HACCP into broader quality systems, and template-driven mobile specialists targeting multi-location restaurant chains. M&A activity concentrates on sensor-to-cloud capability acquisition, while geographic expansion through local hosting partnerships addresses data sovereignty requirements.
Within the cloud-native tier, SafetyChain Software and FoodDocs exemplify divergent positioning strategies. SafetyChain Software anchors North American mid-market penetration through browser-accessible platforms with centralized dashboards. FoodDocs occupies a template-specialist position targeting rapid multi-unit rollout for franchise operators lacking dedicated food safety technologists. Intelex Technologies sits within the platform-extender archetype, representing EHS integration plays that embed HACCP modules into broader environmental and quality management suites.
| Leading Market Players |
|---|
| Zip HACCP |
| FoodDocs |
| SafetyChain Software |
| Momentum |
| EtQ |
| FoodLogiQ |
| Safefood 360 |
| IONI |
| Intelex Technologies |
| Others |
Pricing and Supply Chain Analysis
Cloud-native deployment architectures are compressing both customer acquisition costs and vendor infrastructure spend, redistributing margin capture toward subscription-native providers with multi-tenant efficiency and away from legacy license incumbents burdened by on-premise support obligations.
Pricing Analysis
Direct-to-OEM discounts dominate enterprise manufacturing procurement, while distributor margins of 15-25% persist for mid-market restaurant chains purchasing through foodservice technology resellers. SaaS-tiered pricing stratifies across compliance tier, integration complexity, and sensor count, with premium modules for real-time monitoring commanding 40-60% markups over baseline documentation tools. Cost compression in the independent restaurant tier is intensifying because template-driven mobile entrants are undercutting incumbent per-location fees by half. Quick-service franchise operators show highest price sensitivity due to thin per-unit margins, while export-oriented seafood processors in China and Vietnam demonstrate lowest sensitivity given certification-dependent market access.
Supply Chain Analysis
China's data localization mandates and India's emerging domestic-content preferences for government-catered institutional foodservice are reshaping vendor cloud infrastructure sourcing toward in-country hosting partnerships. Software development concentrates in the United States, Germany, and Estonia, with IoT sensor hardware manufacturing anchored in China, Taiwan, and South Korea. Critical dependencies include wireless temperature probes, pH meter components, and SOC 2-certified hosting capacity. Single-source vulnerability runs through Taiwan-based semiconductor foundries supplying sensor microcontrollers. Distribution runs through foodservice equipment distributors, EHS platform channel partners, and direct inside-sales teams for enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where audit-grade documentation and inspector-accessible records have become non-negotiable procurement criteria, shifting demand toward platforms with validated 21 CFR Part 11 compliance and away from lightweight logging tools.
For Market Incumbents: Deploy sensor-to-cloud integration capabilities to defend against point-solution disaggregation, while consolidating compliance template libraries to raise switching costs for export-dependent processors facing multi-jurisdiction regulatory refresh cycles. Acquire mobile-first specialists to fill quick-service restaurant white space before template-driven entrants capture franchise standardization decisions. For New Entrants and Emerging Players: Launch via aggregator partnerships targeting India's fragmented dairy cooperatives and Vietnam's smallholder aquaculture clusters, where paper-to-digital transition creates first-mover positioning without direct sales infrastructure. Penetrate the catering services vertical through event-management software integrations that embed HACCP modules into existing workflow tools. For Investors and Strategic Acquirers: Roll-up economics work for vertical SaaS consolidators because recurring regulatory update cycles create 90%-plus net revenue retention and predictable expansion revenue from sensor add-ons. Target cloud-native platforms with established FDA validation protocols and EU GDPR-compliant hosting architectures. Watch for inflection when SAMR publishes finalized data-localization enforcement timelines that force foreign vendors into domestic partnership structures.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-to-Cloud Platform Integration | Unifies temperature, humidity, and pH data into single-pane dashboards for 500-plus location chains. |
| Regulatory Template Library Expansion | Captures sticky relationships with export processors facing FSMA, EU Hygiene Package, and SAMR refresh cycles. |
| Domestic Hosting Partnership | Satisfies China's data localization mandates without full infrastructure buildout by foreign vendors. |
| Mobile-First Product Launch | Targets independent restaurant groups priced out of enterprise suite implementations. |
| Blockchain Audit Trail Development | Creates premium positioning for seafood processors serving European retail traceability requirements. |
Research Methodology
Multiple input streams — structured interviews with food safety technologists and quality assurance directors, procurement discussions with multi-site restaurant operators, and regulatory affairs consultations with export-oriented processors — were reconciled against secondary validation from FDA guidance documents, EFSA scientific opinions, SAMR circulars, and EU Hygiene Package directives. Bottom-up sizing of vendor subscription bases and top-down triangulation against food manufacturer IT spend benchmarks anchored volume estimates. Primary fieldwork included conversations with cloud infrastructure providers, IoT sensor OEMs, and foodservice technology distributors.
Historical growth trajectories were cross-referenced against expert panel assessments of enforcement timeline impacts across the projection horizon. Segmentation modeling spanned deployment model, organization size tier, vertical application, integration complexity with existing ERP/MES systems, and regional regulatory cluster. CAGRs were derived from fitted adoption curves reflecting FSMA Rule 204 compliance deadlines and sensor cost decline trajectories. Industry-specific forecast inputs included cold-chain logistics expansion rates and franchise system standardization timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated SAMR enforcement or prolonged FSMA deadline extensions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Social Collaboration Software Market
Software & Services
Global Reference Check Software Market
Software & Services
Mobile Device Management (MDM) Market
Software & Services
E-Invoicing Software Market
Software & Services
Trading Software Market
Software & Services
Library Management Software Market
Software & Services
Global Job Evaluation Software Market
Software & Services
Enterprise Mobility Software Market
Software & Services
Gym Motion Tracking Software Market
Software & Services
Debt Collection Software Market
Software & Services
Europe HR Payroll Software Market
Software & Services
Graphical User Interface (GUI) Design Software Market
Software & Services
Global Document Management Software Market
Software & Services
Global Employee Engagement and Feedback Software Market
Software & Services
Tenant Billing System Market
Software & Services
Europe Integration Platform As a Service Market