
 Customs Declaration Software Market | 2026-2036
Customs Declaration Software Market Size, Share, and Industry Trends Forecast 2026-2036
Customs Declaration Software Market Insights
ISO 27001 certification is redrawing competitive boundaries in customs technology procurement. Descartes Systems Group leverages its long-standing network footprint to anchor multi-modal declaration platforms across North American ports. E2open sustains deep ERP integration capabilities that differentiate its offering for enterprise shippers with complex supplier matrices. CargoWise competes aggressively on geographic dominance, controlling substantial market presence in Asia-Pacific trade lanes through unified forwarding and customs modules.
Customs declaration software comprises digital platforms that automate the preparation, validation, and electronic submission of customs documentation required for cross-border goods movement. These systems integrate tariff classification engines, duty calculation algorithms, and real-time regulatory update feeds to ensure compliance with national customs authorities while minimizing clearance delays. Cloud-based solutions currently lead product type adoption as freight forwarders prioritize remote accessibility and API-driven connectivity with carrier systems. SaaS deployment models are capturing the fastest expansion within the deployment model dimension, particularly among mid-market logistics providers seeking to avoid capital-intensive infrastructure commitments. Integration services command the most substantial margin pools within service type categories, given the complexity of connecting declaration platforms to existing WMS, TMS, and ERP architectures.
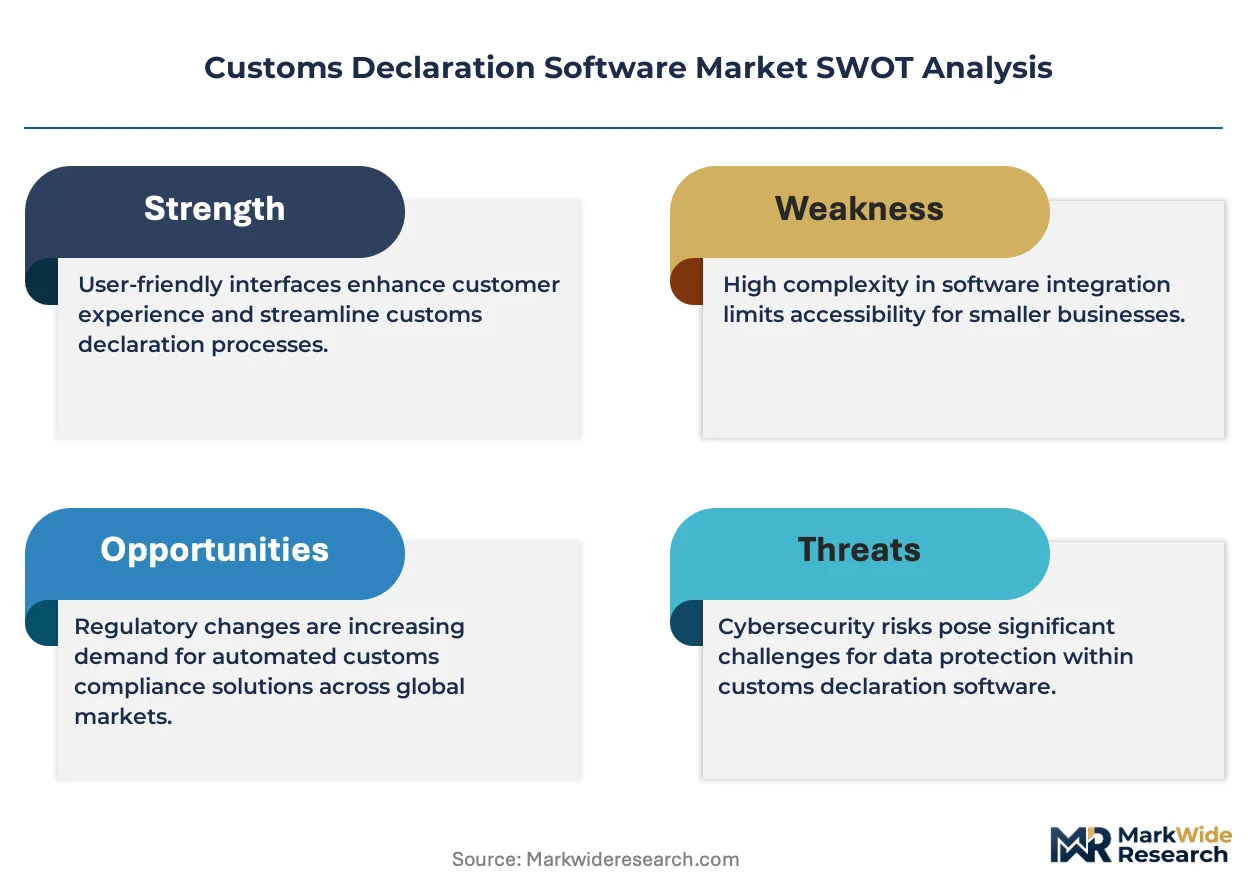
FDA import entry requirements, EU ICS2 mandates, and REACH documentation protocols collectively shape product development priorities and customer onboarding complexity in this market. These frameworks demand granular data fields, audit trails, and real-time validation that only advanced software architectures can deliver. Stakeholders must monitor how customs authorities in key trade corridors accelerate digital-first clearance models and whether their technology stacks can adapt to machine-readable declaration standards without disruptive re-platforming costs.
Market Dynamics
EU ICS2 mandates are forcing wholesale platform upgrades across European customs corridors, compressing vendor selection cycles and elevating ISO 27001 certification from preference to procurement prerequisite.
Growth Catalysts
- E-commerce parcel volumes:Cross-border direct-to-consumer shipments are generating declaration complexity that manual processes cannot handle. Freight forwarders in Germany and the Netherlands are automating workflows fastest.
- ICS2 compliance deadlines:The EU's phased rollout through 2025 is compelling customs brokers to replace legacy entry systems. Pre-arrival security filing requirements demand real-time data integration.
- API-first architectures:Cloud-native platforms with open connectivity standards are displacing on-premise installations. Mid-market logistics providers prioritize subscription models over capital expenditure.
Market Restraints
- Integration cost concentration:Connecting declaration engines to existing WMS and ERP architectures consumes 40-60% of total implementation budgets. This capex burden falls heaviest on smaller customs brokers.
- Regulatory fragmentation:Divergent national filing formats across EU member states, the UK, and Switzerland force vendors to maintain parallel validation engines. This complexity slows product standardization.
- Talent scarcity in tariff classification:Automated systems still require human oversight for HS code determination. Experienced classifiers command premium compensation that erodes SaaS margin structures.
Strategic Opportunities
- India's digitization push:DGFT's phased migration to paperless customs creates whitespace for declaration platforms with localized compliance engines. The country's expanding manufacturing exports amplify addressable volume.
- Machine-readable standards:WTO Trade Facilitation Agreement implementation is accelerating single-window adoption across Southeast Asian ports. Vendors with UN/EDIFACT expertise capture first-mover positioning.
- Carbon border adjustment mechanics:The EU CBAM's reporting requirements for embedded emissions are creating new data fields that incumbent platforms lack. Specialized modules for emissions documentation represent unclaimed margin pools.
Industry Challenges
- Legacy system entrenchment:Customs brokers in established trade corridors operate decades-old AS/400 installations. Migration timelines stretch 18-36 months, delaying revenue recognition for platform vendors.
- Certification audit backlogs:ISO 27001 and SOC 2 attestation queues at accredited bodies extend 6-9 months. This bottleneck stalls enterprise procurement cycles and competitive positioning.
- Real-time regulatory feed maintenance:National customs authorities update tariff schedules and restricted party lists with minimal notice. Platform operators must sustain 24/7 monitoring operations across 150+ jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Customs Declaration Software Market |
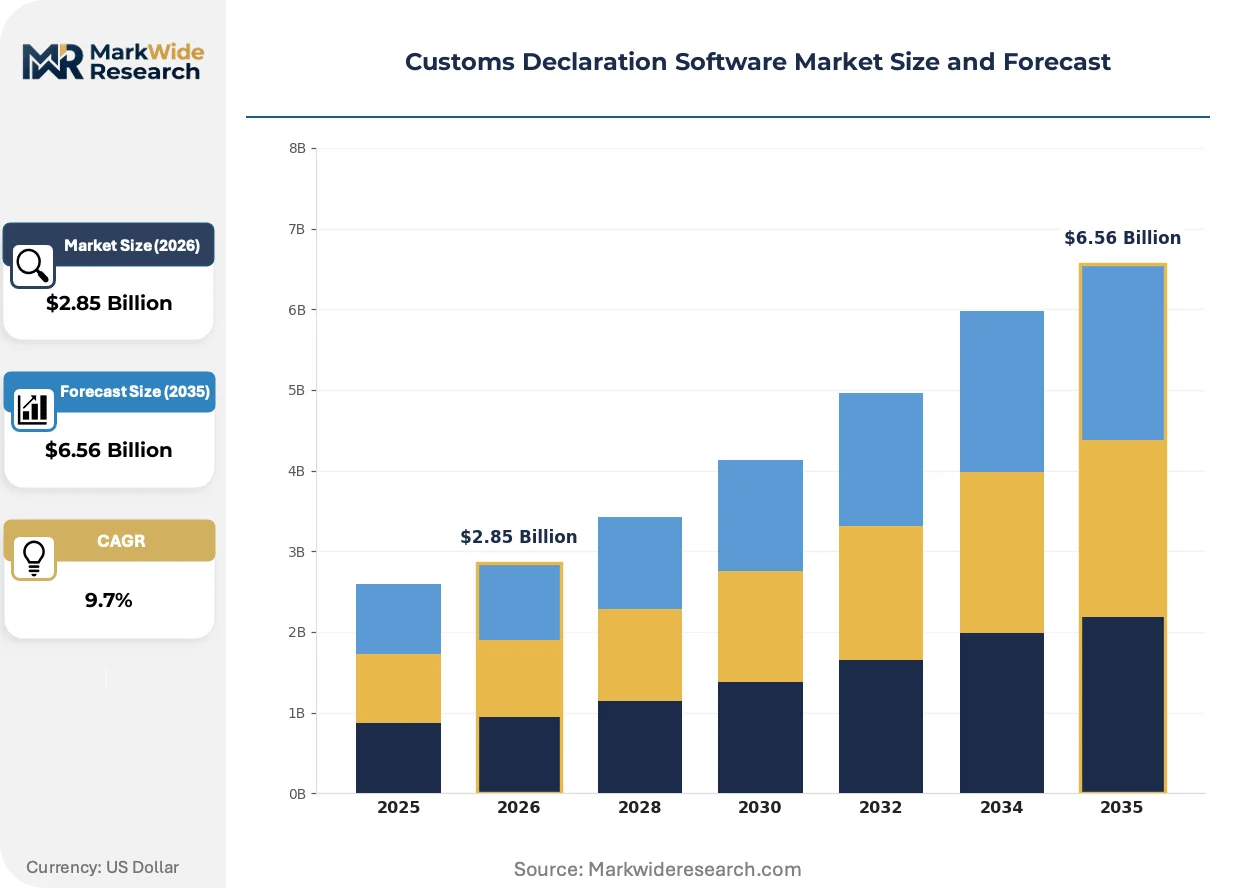
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $6.56 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Solutions, On-Premises Solutions, Hybrid Solutions, Mobile Applications Deployment Model: Private Cloud, Public Cloud, Community Cloud, SaaS Service Type: Integration Services, Training Services, Maintenance Services, Consulting Services Industry Vertical: Logistics, E-Commerce, Manufacturing, Retail |
| Companies Covered | MIC, Sphere, Descartes Systems Group, Zeus Logics, Altana, CargoWise, Flexport, Vivansa, E2open, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Customs Declaration Software Market Trends and Innovations
Declaration technology is splitting between commodity cloud tools and specialized compliance engines, with buyer sophistication determining which architecture prevails in each segment.
Natural language processing for trade document extraction is bifurcating vendor capabilities. Large forwarders with captive development teams are building in-house classification engines, while mid-tier buyers depend on vendor-provided AI modules. This capability gap is compressing margins for undifferentiated SaaS offerings and rewarding platforms with proprietary training datasets.
REACH documentation protocols are reshaping data field requirements for chemical shipments entering EU customs territory. The ECHA's expanded substance database integration demands granular composition disclosure that legacy platforms cannot capture. Pharmaceutical and specialty chemical shippers are prioritizing vendors with pre-built REACH validation workflows.
Subscription contracting is displacing perpetual license sales across the mid-market segment. Buyers in the Netherlands and Belgium now expect consumption-based pricing tied to declaration volume rather than fixed seat arrangements. This shift pressures vendors to restructure revenue recognition and customer success investments.
Customs Declaration Software Market Segmentation
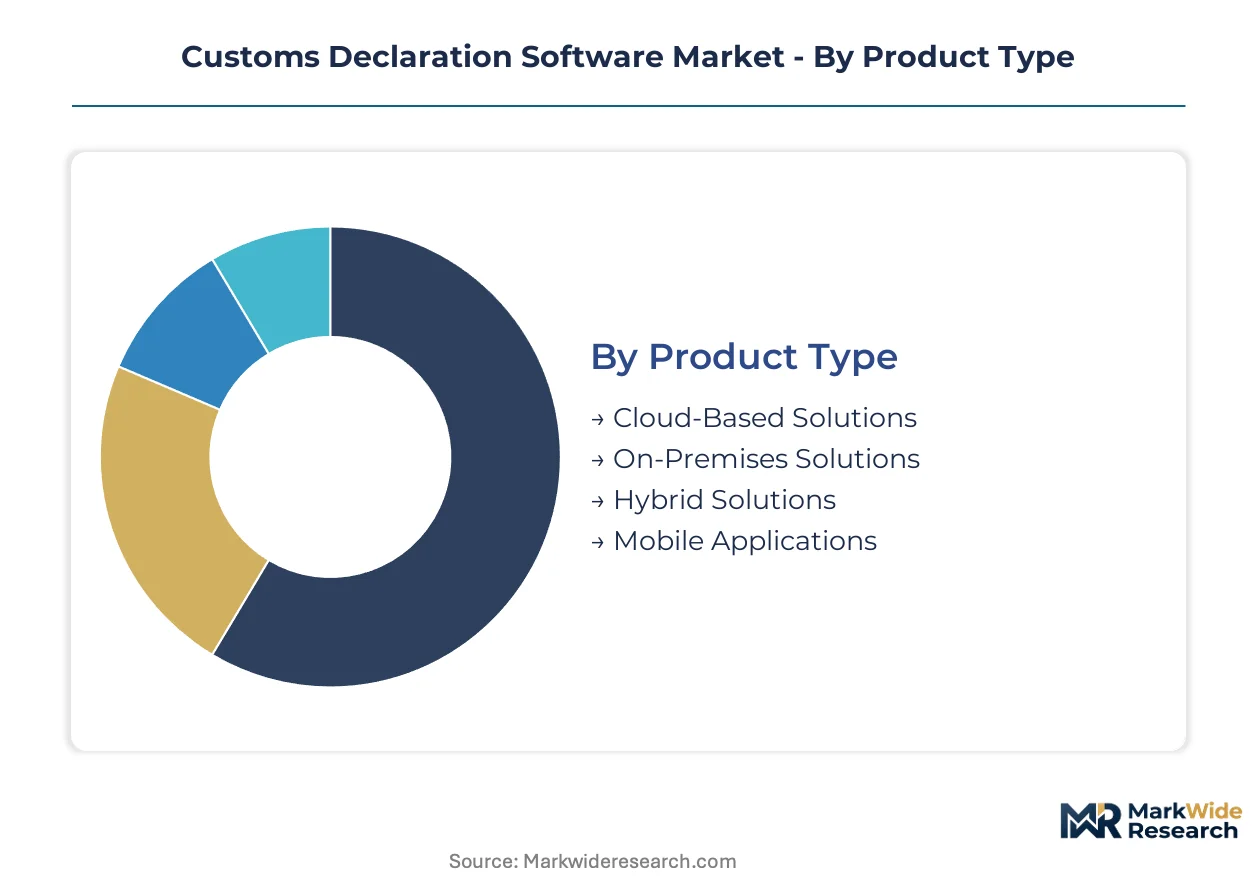
Customs declaration software procurement decisions hinge on trade lane complexity, regulatory jurisdiction, and existing IT infrastructure. Vendors must architect solutions that span cloud-native flexibility for mid-market forwarders and hardened on-premise deployments for customs authorities with sovereign data requirements.
Product Type:
Cloud-based solutions face substitution pressure from hybrid architectures as large customs brokers demand air-gapped backup systems for critical declaration workflows.
- Cloud-Based Solutions:Multi-tenant SaaS platforms with API-driven connectivity to carrier systems and real-time regulatory feed integration. Freight forwarders in Germany and the Netherlands prioritize these for remote workforce accessibility and ICS2 pre-arrival filing compliance.
- On-Premises Solutions:Single-tenant installations hosted within customer data centers with full control over security certificates and audit trails. National customs authorities and defense contractors mandate these for sovereign data requirements and offline contingency operations.
- Hybrid Solutions:Split architectures processing routine declarations in cloud environments while retaining sensitive tariff rulings on local infrastructure. Large customs brokers in Rotterdam-adjacent clusters adopt these to balance accessibility with risk mitigation.
- Mobile Applications:Native iOS and Android clients for field inspectors and truck drivers requiring barcode scanning and photographic evidence capture at port gates.
Cloud-based solutions anchor the volume base while hybrid solutions gain share at the steepest rate.
Deployment Model:
Cost tier stratification separates enterprise buyers with dedicated infrastructure budgets from mid-market logistics providers seeking consumption-based economics.
- Private Cloud:Dedicated virtualized environments with single-tenant isolation and custom security policy enforcement. Large pharmaceutical shippers deploy these for FDA import entry workflows requiring validated system configurations.
- Public Cloud:Shared infrastructure with automatic scaling and geographic redundancy across AWS, Azure, or Google Cloud regions. Mid-tier forwarders in Belgium favor these for pay-per-declaration pricing without capital commitment.
- Community Cloud:Collaborative platforms serving customs broker associations or port authorities with standardized filing formats and pooled regulatory update subscriptions.
- SaaS:Fully managed software subscriptions with vendor-controlled infrastructure, automatic feature releases, and embedded customer success functions.
SaaS deployment anchors the volume base while private cloud gains share at the steepest rate.
Service Type:
Margin concentration favors integration specialists over commoditized training vendors as ERP connectivity complexity escalates.
- Integration Services:Custom middleware development connecting declaration engines to WMS, TMS, and ERP architectures. These engagements consume 40-60% of total implementation budgets and generate recurring maintenance revenue.
- Training Services:Instructor-led certification programs for tariff classification specialists and customs compliance officers. REACH documentation protocols and ECHA database navigation command premium pricing.
- Maintenance Services:24/7 monitoring operations for regulatory feed accuracy, restricted party list updates, and tariff schedule revisions across 150+ jurisdictions.
- Consulting Services:Advisory engagements for ICS2 migration planning, carbon border adjustment preparation, and single-window system design.
Integration services anchor the volume base while consulting services gain share at the steepest rate.
Industry Vertical:
Application intensity varies by shipment complexity, with chemical and pharmaceutical shippers demanding granular data fields that generalist platforms cannot satisfy.
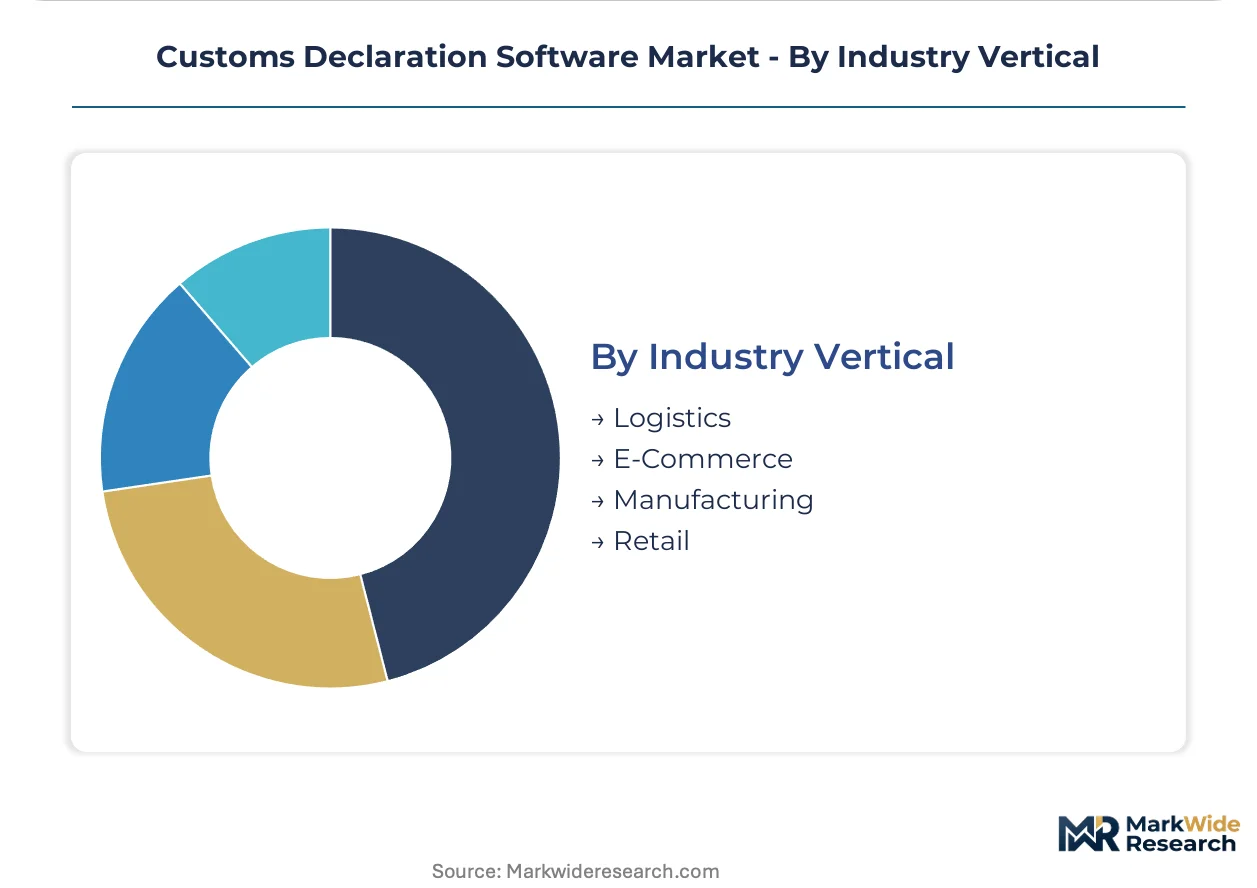
- Logistics:Third-party freight forwarders and customs brokers managing multi-client declaration portfolios with divergent compliance requirements. Hamburg-based operators lead digitization investment.
- E-Commerce:Direct-to-consumer platforms processing high-volume, low-value parcel declarations with automated HS code determination and duty calculation. Cross-border volume surges strain manual processing capacity.
- Manufacturing:Industrial exporters with complex bills of materials requiring component-level origin documentation and preferential tariff claims under trade agreements.
- Retail:Omnichannel merchants consolidating supplier declarations across private label and branded merchandise with seasonal volume spikes.
Logistics anchors the volume base while e-commerce gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Customs brokers and freight forwarders in Germany and the Netherlands are digitizing declaration workflows faster than peers elsewhere, driven by EU ICS2 deadlines and port congestion pressures. Buyer archetypes cluster around mid-sized logistics providers seeking SaaS alternatives to legacy AS/400 installations.
Germany
Hamburg-based customs brokers and Rotterdam-adjacent operators are automating declaration workflows to meet ICS2 pre-arrival filing requirements. The country's national customs authority enforces strict data quality standards for security filings. Industrial clusters in the Rhine-Ruhr corridor are upgrading ERP-integrated declaration platforms to handle manufacturing export complexity.
Netherlands
Amsterdam and Rotterdam freight forwarders process the highest per-capita declaration volumes in Europe, driving demand for API-first cloud platforms. The Dutch customs administration operates one of the EU's most advanced single-window systems. Mid-market logistics providers in the Randstad region are abandoning perpetual licenses for consumption-based SaaS pricing.
United States
Los Angeles and Long Beach port customs brokers face FDA import entry requirements for pharmaceutical and food shipments that demand validated system configurations. The FDA's import operations division maintains strict audit trail standards for electronic filings. Third-party logistics providers in the Southeast are expanding declaration automation to handle e-commerce parcel surges from Asian manufacturing hubs.
India
DGFT's phased migration to paperless customs is creating whitespace for declaration platforms with localized compliance engines. The country's central board of indirect taxes and customs mandates ICEGATE integration for all electronic filings. Manufacturing exporters in Gujarat and Maharashtra are digitizing component-level origin documentation to claim preferential tariff benefits.
United Kingdom
Post-Brexit customs declarations have quadrupled declaration volumes for UK-EU trade, straining broker capacity in Dover and Felixstowe. HM Revenue & Customs operates the Customs Declaration Service with distinct filing formats from EU systems. Logistics providers in the Midlands are investing in dual-validation platforms that handle both UK and EU regulatory requirements simultaneously.
Customs Declaration Software Market Competitive Landscape
Player mix skews toward specialized compliance software vendors with established regulatory feed infrastructure rather than generalist enterprise software providers. Market structure exhibits moderate consolidation around vendors with multi-modal network footprints and deep ERP integration capabilities. Two strategic archetypes dominate: platform operators with unified forwarding-customs modules, and pure-play compliance engines with granular tariff classification tools. Competitive intensity centers on geographic expansion into India's digitizing customs corridor and M&A activity targeting mid-tier SaaS providers with ICS2-ready architectures.
Within the established platform tier, Descartes Systems Group and E2open occupy positions anchored by long-standing network infrastructure and enterprise integration depth. CargoWise exemplifies the unified forwarding-customs archetype with substantial Asia-Pacific trade lane presence. These three vendors represent the competitive standard against which mid-market SaaS challengers benchmark feature completeness and regulatory coverage breadth.
| Leading Market Players |
|---|
| MIC |
| Sphere |
| Descartes Systems Group |
| Zeus Logics |
| Altana |
| CargoWise |
| Flexport |
| Vivansa |
| E2open |
| Others |
Pricing and Supply Chain Analysis
Ninety-day implementation cycles for ICS2-compliant platforms concentrate pricing power with vendors holding pre-certified architectures, while buyers in Germany and the Netherlands absorb premium rates to avoid operational disruption. This lead-time compression rewards established players with existing regulatory feed infrastructure and squeezes mid-tier brokers into longer deployment queues.
Pricing Analysis
Cost-plus contracts with annual indexation to ISO 27001 audit costs dominate enterprise procurement, while SaaS subscriptions with consumption-based pricing capture mid-market logistics providers in Belgium and the Netherlands. Three-tier pricing structure across premium, standard, and economy levels separates vendors with pre-built REACH validation from commodity cloud tools. Price differentiation hinges on certification grade and integration complexity, with pharmaceutical shippers paying premiums for FDA-validated configurations. Cost compression in the standard tier is intensifying because API-first entrants are commoditizing basic declaration automation. Mid-market freight forwarders exhibit highest price sensitivity, while defense contractors and national customs authorities show minimal elasticity due to sovereign data requirements.
Supply Chain Analysis
ISO 27001 certification queues at accredited bodies constitute the primary chokepoint, extending vendor onboarding timelines and concentrating delivery capacity with pre-certified platform operators. Software development centers in Germany, the Netherlands, and India anchor supply, with regulatory content feeds drawing from customs authorities across 150+ jurisdictions. Cloud infrastructure dependencies rest on hyperscaler regions in Frankfurt, Amsterdam, and Mumbai. Single-source vulnerability emerges from concentrated tariff classification talent pools in Hamburg and Rotterdam. Distribution runs through direct enterprise sales for large customs brokers and channel partners serving mid-market logistics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform vendors face acute scarcity in machine-readable declaration expertise and real-time regulatory feed maintenance capabilities, creating asymmetric returns for those who secure specialized talent pools before ICS2 deadlines harden.
For Market Incumbents: Fortify defensive moats by accelerating ISO 27001 certification for mid-tier acquisition targets before audit backlogs extend further, and deepen upstream control over tariff classification training pipelines to capture scarce human capital. Emerging API-first challengers with consumption-based pricing threaten margin structures in the Benelux corridor. Vertical integration into regulatory content aggregation—direct licensing from national customs authorities—anchors differentiation against commodity SaaS entrants. For New Entrants and Emerging Players: White-space in carbon border adjustment modules for EU CBAM compliance offers immediate penetration opportunity, as incumbent platforms lack embedded emissions documentation fields. India's DGFT digitization push presents the most penetrable geography, with localized ICEGATE integration capabilities commanding premium positioning. A compliance-specialist go-to-market angle—pre-built REACH and FDA validation workflows—circumvents direct confrontation with unified forwarding platforms. For Investors and Strategic Acquirers: Carve-out targets emerge from logistics holding companies with captive customs software divisions that lack standalone scale. Long-term viability favors vendors with multi-modal network footprints spanning at least three trade corridors and pre-certified ICS2 architectures. The signal to watch is acceleration in single-window system adoption across Southeast Asian ports, which would validate UN/EDIFACT expertise as a durable competitive asset.| Strategic Initiative | Industry Significance |
|---|---|
| ICS2-Ready Platform Certification | Pre-arrival filing mandates in EU customs corridors compress vendor selection cycles and elevate procurement prerequisites. |
| Regulatory Feed Infrastructure Acquisition | Direct licensing agreements with national customs authorities secure real-time tariff schedule updates across 150+ jurisdictions. |
| Carbon Border Adjustment Module Development | EU CBAM reporting requirements for embedded emissions create unclaimed margin pools in specialized compliance engines. |
| India Localization Investment | DGFT paperless customs migration and ICEGATE integration demands create whitespace for declaration platforms with localized engines. |
| Tariff Classification AI Training | Proprietary NLP datasets for HS code determination compress margins for undifferentiated SaaS offerings and reward specialized platforms. |
Research Methodology
Initial hypotheses were tested against primary input from customs brokerage operations directors, freight forwarder CTOs, regulatory compliance officers at pharmaceutical shippers, and integration specialists at ERP vendors, then refined through secondary validation. Customs authority filing databases, EU ICS2 implementation guidance documents, SEC filings from listed logistics technology providers, and trade volume statistics from Hamburg and Rotterdam port authorities supplied quantitative anchors. Bottom-up demand estimates from declaration volume trends were triangulated against top-down market sizing from software vendor revenue disclosures.
Variance decomposition across deployment models, organization size tiers, vertical applications, integration complexity levels, and regional adoption patterns structured the analytical framework. CAGRs were derived from segment-level growth rate assumptions weighted by addressable base sizes. Forecast inputs included e-commerce parcel volume trajectories, ICS2 compliance deadline phasing, and customs authority digital-first clearance roadmaps across the analysis window.
Material uncertainties—regulatory deadline extensions, customs authority API standard changes, and hyperscaler infrastructure cost volatility—sit outside the modeled envelope. Forecasts reflect documented assumptions about technology adoption curves and compliance cost pass-through rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Disclosure Management Software Market
Software & Services
Global Retail Management Systems Software Market
Software & Services
Driver and Staff Management Software Market
Software & Services
United States Human Resource (HR) Technology Market
Software & Services
India Software Services Export Market
Software & Services
Global Business Software Market
Software & Services
Embedded Software and Tools Market
Software & Services
SRM Software Market
Software & Services
Global Electronic Lab Notebook (ELN) Market
Software & Services
Application Platform As a Service Market
Software & Services
Android Emulator Market
Software & Services
Software License Management (SLM) Market
Software & Services
Bridge Analysis Software Market
Software & Services
Global Auction Software Market
Software & Services
Global Application Performance Monitoring (APM) Market
Software & Services
Global User Research and User Testing Software Market