
 HVAC Solution Software Market | 2026-2036
HVAC Solution Software Market Size, Share, and Industry Trends Forecast 2026-2036
HVAC Solution Software Market Insights
Subscription-based predictive maintenance layers is broadening what facility managers purchase alongside core HVAC hardware. Johnson Controls leverages its building automation ecosystem to bundle software analytics with equipment service contracts. Schneider Electric anchors its competitive stance through edge-to-cloud integration that reduces latency for real-time equipment diagnostics. Daikin Industries specializes in refrigerant leak detection algorithms that differentiate its software modules from generic building management platforms.
HVAC solution software encompasses digital platforms that command, monitor, and optimize heating, ventilation, and air conditioning systems through protocols such as BACnet and Modbus, with functional parameters spanning setpoint calibration, fault detection diagnostics, and energy consumption baselining. These systems serve the primary commercial purpose of reducing operational expenditure while maintaining indoor environmental quality across distributed building portfolios. Cloud-based Solutions lead deployment preferences among multi-site operators seeking centralized visibility, while Edge Computing represents the fastest-expanding technology segment as latency-sensitive applications such as demand response and occupant-centric climate zoning gain traction. Management Software occupies the largest product category share, though Optimization Tools command premium pricing due to their integration of machine learning-driven load forecasting.
The US Department of Energy enforces building performance standards that mandate granular energy tracking, while the EU Green Deal and F-Gas Regulation impose refrigerant management and emissions disclosure requirements that software platforms must encode. India's BIS energy labeling norms and China's GB standards for building efficiency create parallel compliance pathways that shape product localization strategies. Stakeholders must monitor how fragmented national certification requirements affect development roadmaps and partner channel investments.
Market Dynamics
Building performance mandates from the US Department of Energy and the EU Green Deal are compressing compliance timelines for energy management platforms, forcing software vendors to embed real-time emissions tracking and refrigerant leak detection into core product architectures.
Growth Catalysts
- KfW Building Modernization Funding:Germany's federal development bank subsidizes retrofit software procurement, accelerating demand for predictive maintenance modules among commercial portfolio operators.
- Edge-to-Cloud Protocol Convergence:BACnet and Modbus integration with 5G-enabled edge nodes reduces diagnostic latency, enabling demand response participation that unlocks new revenue streams for facility managers.
- Commercial Real Estate ESG Disclosure:Institutional investors now mandate granular HVAC energy baselining for loan covenants, converting software analytics from operational tool to financial compliance instrument.
Market Restraints
- Semiconductor Supply Concentration:Edge computing hardware dependencies on Taiwan-based chip fabrication create procurement bottlenecks for latency-sensitive control systems.
- Legacy System Interoperability Costs:Proprietary building automation protocols from the 1990s require expensive middleware gateways, inflating total cost of ownership for retrofit deployments.
- Cyber Insurance Premium Escalation:Ransomware attacks on operational technology networks have doubled premiums for cloud-connected HVAC platforms, squeezing vendor margins.
Strategic Opportunities
- India BIS Energy Labeling Expansion:Mandatory efficiency disclosure for commercial buildings above 100 kW connected load creates first-mover advantage for localized software platforms.
- Refrigerant Management as Service:EU F-Gas Regulation phase-down schedules position refrigerant tracking algorithms as standalone subscription products separate from hardware sales.
- Digital Twin Convergence:Integration of BIM models with live sensor streams enables simulation-based commissioning, reducing energy waste during building handover.
Industry Challenges
- Controls Engineering Talent Scarcity:Shortage of technicians proficient in both HVAC physics and Python-based machine learning pipelines delays deployment timelines for optimization tools.
- Multi-Standard Certification Burden:Fragmented national requirements across GB standards, BIS norms, and ASHRAE guidelines force redundant testing cycles that extend product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVAC Solution Software Market |
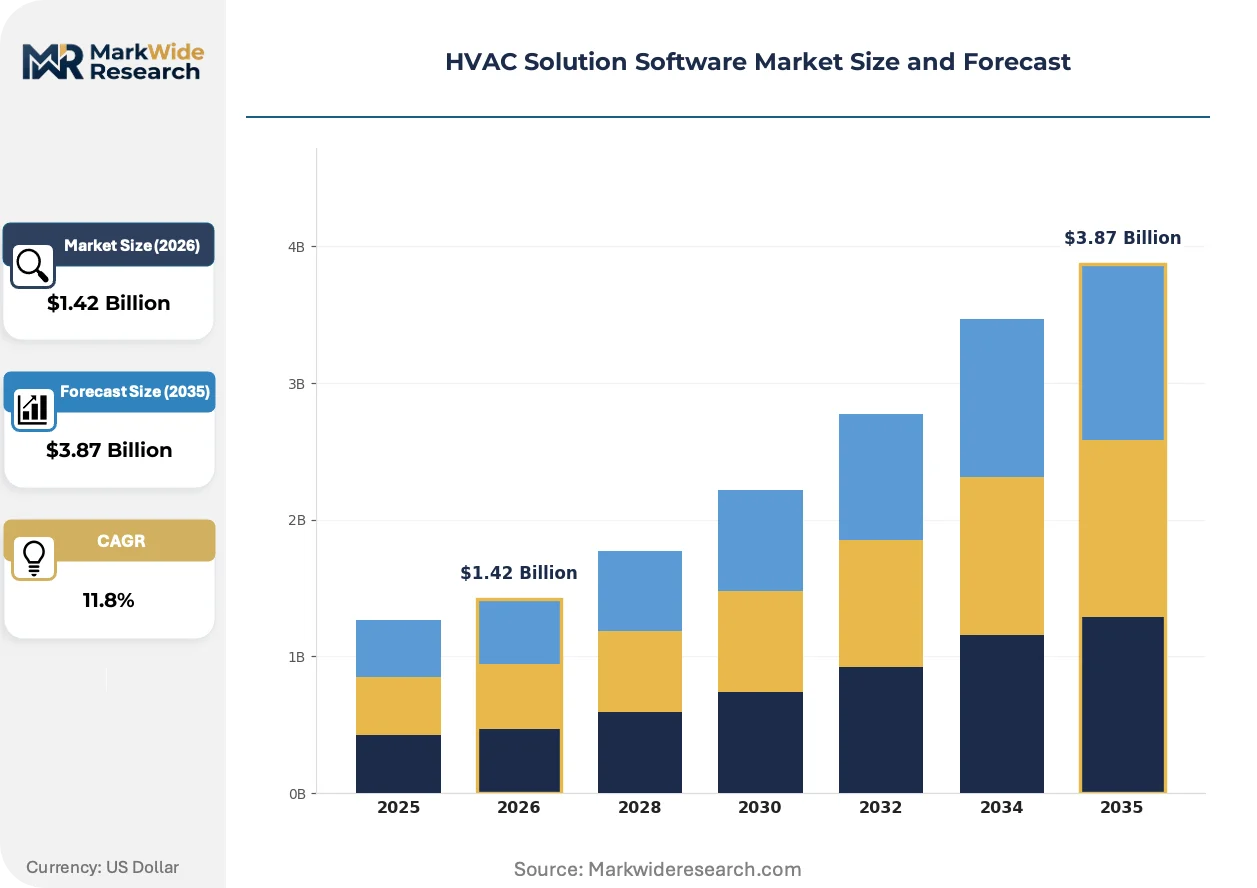
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.87 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Management Software, Control Systems, Monitoring Solutions, Optimization Tools Technology: Cloud-based Solutions, On-premise Systems, Edge Computing, Mobile Applications End User: Commercial Buildings, Residential Properties, Industrial Facilities, Educational Institutions Deployment: Hybrid Deployment, SaaS, On-site Deployment, Remote Access |
| Companies Covered | Johnson Controls, Trane Technologies, Carrier Global Corporation, Honeywell International, Schneider Electric, Rheem Manufacturing, Daikin Industries, Lennox International, Emerson Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVAC Solution Software Market Trends and Innovations
Software architectures are migrating from monolithic building management systems toward modular API-first platforms that interoperate with third-party energy marketplaces and occupant experience applications.
Digital twin technology is unifying static BIM assets with dynamic operational data streams, creating persistent simulation environments for predictive load forecasting. Large commercial developers in Germany and the Netherlands are deploying these unified models during design-build-operate contracts to guarantee energy performance outcomes. The technology is compressing commissioning timelines and shifting liability for efficiency shortfalls from building owners to software-integrated construction consortia.
The EU F-Gas Regulation's refrigerant phase-down mandates are forcing platform vendors to embed automated leak detection and inventory tracking into core management software. Industrial consequence includes mandatory API connections to national emissions registries in France, Germany, and Italy. Cold storage and supermarket operators face the steepest compliance burden, driving premium pricing for specialized refrigerant analytics modules.
Facility management procurement is consolidating vendor relationships around integrated service contracts that bundle software subscriptions with equipment maintenance and energy supply. This displaces the traditional model of separate CAPEX hardware purchases and siloed software licenses. The shift is most visible in US healthcare and university campus portfolios, where multi-site operators seek single-accountability partners for carbon neutrality commitments.
HVAC Solution Software Market Segmentation
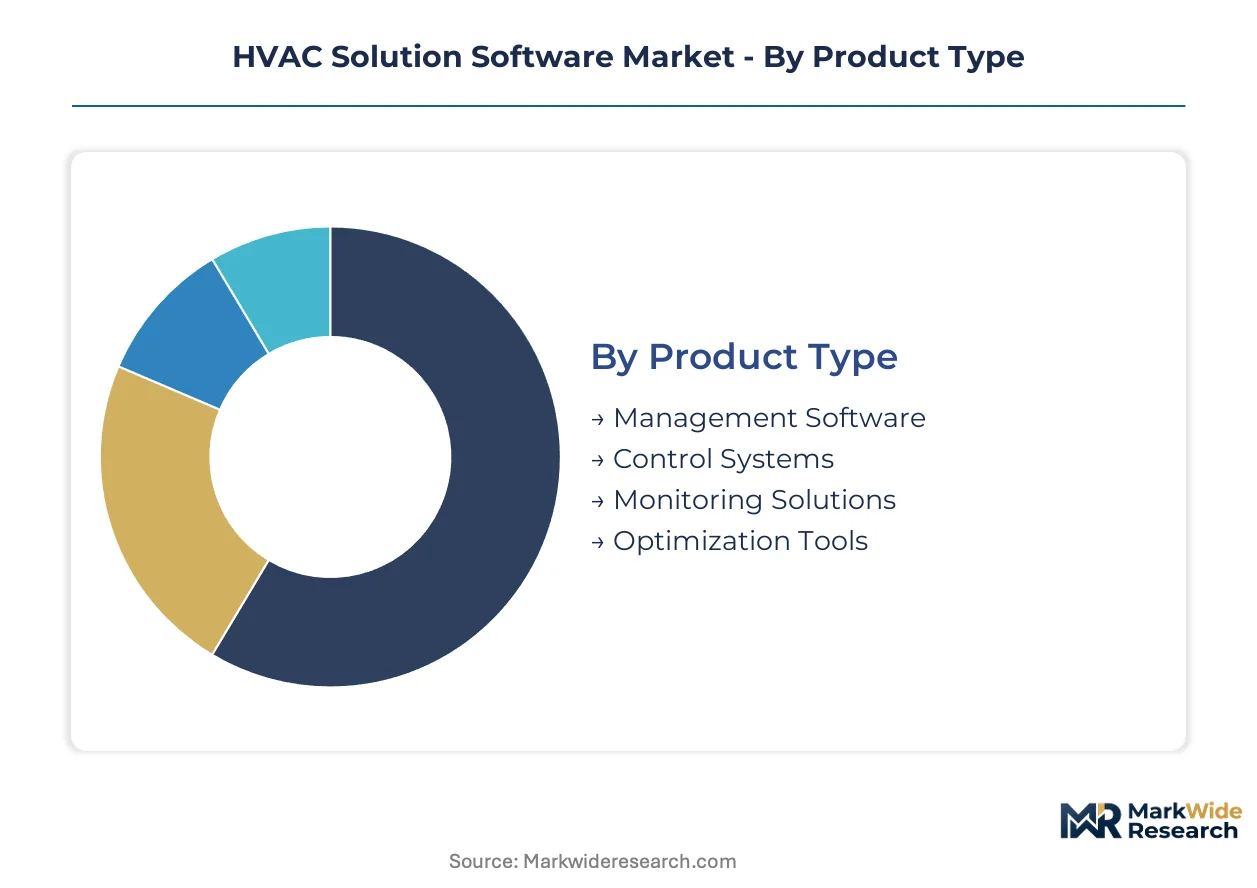
Segmentation in HVAC solution software reveals how procurement decisions bifurcate between capital-intensive on-premise installations and recurring-revenue cloud subscriptions. Facility operators select architectures based on portfolio scale, latency requirements, and regulatory disclosure obligations.
Product Type:
Standardization dominates at the infrastructure layer while customization concentrates in analytics modules that embed machine learning for specific building typologies.
- Management Software:Core platforms orchestrating setpoint calibration, scheduling, and alarm management across distributed equipment fleets. Demand concentrates in US healthcare and university campuses where Johnson Controls bundles these systems with long-term service contracts under single-accountability carbon neutrality commitments.
- Optimization Tools:Machine learning-driven modules for load forecasting and energy consumption baselining that command premium pricing. German commercial portfolio operators under KfW retrofit funding mandates represent the fastest-expanding customer base for these analytics layers.
- Control Systems:Protocol gateways translating BACnet and Modbus signals for equipment command.
- Monitoring Solutions:Sensor aggregation platforms for fault detection diagnostics and indoor environmental quality tracking.
Leading the category by volume: Management Software. Expanding most quickly: Optimization Tools.
Technology:
Deployment location determines latency sensitivity and data sovereignty compliance, with edge architectures gaining traction where real-time demand response participation requires sub-second reaction times.
- Cloud-based Solutions:Centralized platforms enabling multi-site visibility and API integrations with third-party energy marketplaces. Multi-site operators in commercial real estate ESG disclosure regimes favor these architectures for granular HVAC energy baselining required by institutional investor loan covenants.
- Edge Computing:Localized processing nodes reducing diagnostic latency for occupant-centric climate zoning and demand response. 5G-enabled edge deployments are climbing the fastest as EU electricity market operators open ancillary service revenue streams to building-level flexibility.
- On-premise Systems:Air-gapped installations serving cybersecurity-sensitive industrial facilities and defense infrastructure.
- Mobile Applications:Technician-facing interfaces for remote alarm acknowledgment and setpoint adjustment.
Dominant by deployment share: Cloud-based Solutions. Steepest expansion trajectory: Edge Computing.
End User:
Building typology dictates software complexity, with industrial facilities requiring refrigerant management compliance while commercial portfolios prioritize carbon disclosure automation.
- Commercial Buildings:Office towers, retail centers, and hospitality properties seeking operational expenditure reduction across distributed portfolios. US healthcare systems and Dutch commercial developers deploying design-build-operate contracts with guaranteed energy performance outcomes anchor demand for integrated software-hardware procurement.
- Industrial Facilities:Manufacturing plants and cold storage operations with intensive HVAC loads and stringent refrigerant tracking obligations. EU F-Gas Regulation phase-down schedules position this segment for specialized refrigerant analytics modules with mandatory API connections to national emissions registries in France, Germany, and Italy.
- Residential Properties:Multi-family housing and single-family home automation integrations.
- Educational Institutions:K-12 and university campuses with deferred maintenance backlogs and public procurement constraints.
Highest revenue concentration: Commercial Buildings. Gaining share fastest: Industrial Facilities.
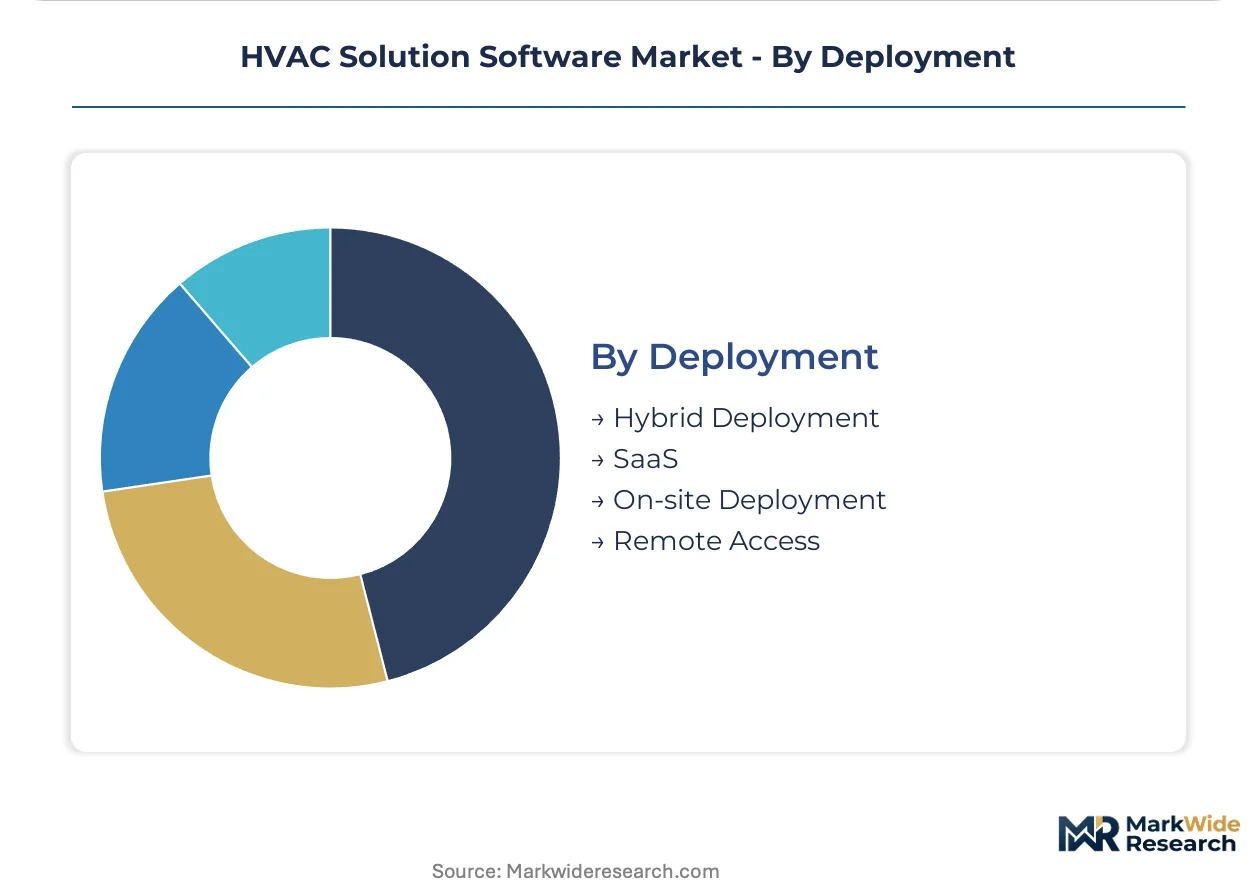
Deployment:
Procurement models diverge between capital expenditure ownership and operational expenditure subscriptions, with hybrid architectures emerging to balance latency requirements against centralized analytics.
- SaaS:Subscription licensing with continuous feature updates and cloud hosting. US university campuses consolidating vendor relationships around integrated service contracts that bundle software with equipment maintenance represent the primary expansion vector for this model.
- Hybrid Deployment:Architectures combining on-site edge processing for latency-sensitive control loops with cloud aggregation for portfolio-level analytics. German building modernization projects under KfW funding increasingly specify these configurations to satisfy both real-time efficiency optimization and centralized compliance reporting.
- On-site Deployment:Perpetual license installations with local data retention.
- Remote Access:VPN and zero-trust connectivity layers for distributed technician support.
Primary procurement model by contract value: SaaS. Fastest-growing configuration: Hybrid Deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European HVAC software procurement as Germany's KfW funding program channels retrofit capital toward predictive maintenance platforms. Commercial portfolio operators across the metropolitan region bundle software subscriptions with equipment modernization contracts to satisfy federal efficiency mandates.
United States
Healthcare systems and university campuses drive SaaS procurement through integrated service contracts bundling analytics with long-term maintenance. The US Department of Energy's building performance standards mandate granular energy tracking that software platforms must encode. Boston's commercial real estate cluster concentrates ESG disclosure automation as institutional investors impose HVAC energy baselining for loan covenants.
Germany
Commercial portfolio operators under KfW building modernization funding represent the fastest-expanding customer base for optimization tools with machine learning-driven load forecasting. The EU Green Deal and F-Gas Regulation impose refrigerant management requirements that vendors embed into core architectures. Frankfurt's financial district leads hybrid deployment adoption, combining edge processing for real-time efficiency with cloud aggregation for centralized compliance reporting.
China
GB standards for building efficiency create localized certification pathways that shape product development roadmaps for domestic software platforms. The country's national building efficiency regulator enforces disclosure requirements for commercial structures above specified energy thresholds. Shanghai's Yangtze River Delta corridor concentrates demand for cloud-based solutions among multi-site operators seeking centralized visibility across distributed portfolios.
India
Mandatory BIS energy labeling for commercial buildings above 100 kW connected load creates first-mover advantage for localized software platforms. The Bureau of Indian Standards efficiency disclosure norms compress procurement timelines for energy management systems. Mumbai's Maharashtra industrial corridor anchors initial deployment clusters as facility managers seek operational expenditure reduction across retail and hospitality properties.
Netherlands
Commercial developers deploying design-build-operate contracts guarantee energy performance outcomes through software-integrated construction consortia. The EU Green Deal's efficiency mandates tighten compliance timelines for emissions tracking platforms. Amsterdam's metropolitan region leads digital twin convergence, unifying BIM models with live sensor streams to compress commissioning timelines and shift liability for efficiency shortfalls.
HVAC Solution Software Market Competitive Landscape
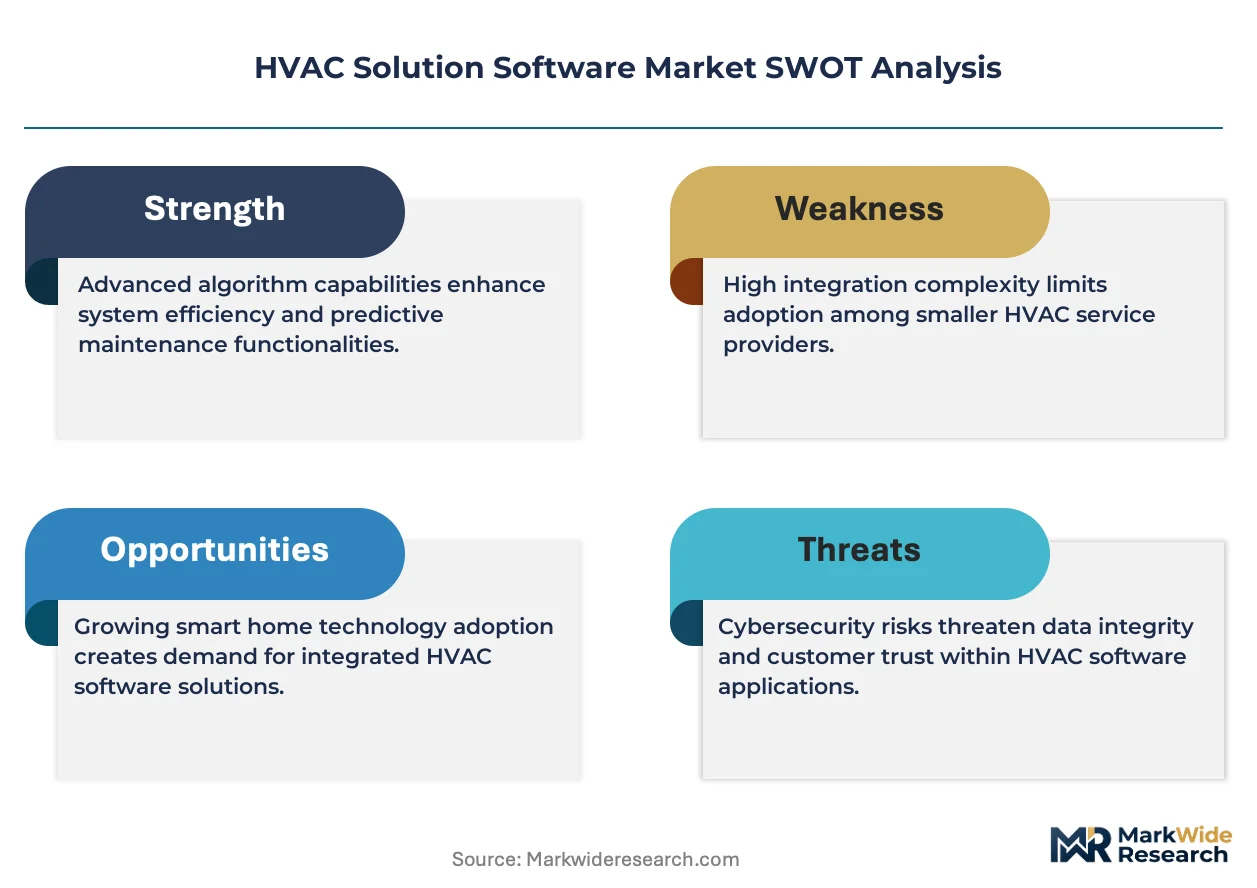
Capital-heavy producers compete with asset-light designers across a market structure consolidating around integrated service contracts that displace separate hardware and software procurement. The vendor base clusters into three strategic archetypes: building automation incumbents bundling analytics with equipment service contracts, industrial conglomerates anchoring competitive stance through edge-to-cloud integration, and specialized refrigerant management vendors differentiating through leak detection algorithms. Dominant competitive moves include portfolio diversification into predictive maintenance subscriptions and strategic partnerships with 5G infrastructure providers to reduce diagnostic latency.
Within the building automation tier, Johnson Controls and Carrier Global Corporation exemplify the integrated service contract model that US healthcare and university campuses increasingly favor. Schneider Electric occupies a position representing edge-to-cloud protocol convergence for latency-sensitive demand response applications. Daikin Industries sits within the specialized refrigerant analytics segment, anchoring differentiation through automated leak detection modules that address EU F-Gas Regulation compliance burdens.
| Leading Market Players |
|---|
| Johnson Controls |
| Trane Technologies |
| Carrier Global Corporation |
| Honeywell International |
| Schneider Electric |
| Rheem Manufacturing |
| Daikin Industries |
| Lennox International |
| Emerson Electric |
| Others |
Pricing and Supply Chain Analysis
The EU F-Gas Regulation refrigerant phase-down mandates gate qualified supply and premium-tier pricing access for HVAC solution software vendors, as compliance-certified platforms command subscription premiums while non-compliant providers face exclusion from EU procurement channels serving cold storage and supermarket operators.
Pricing Analysis
Outcome-based pricing tied to guaranteed energy savings anchors premium-tier subscriptions for optimization tools with machine learning-driven load forecasting. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade predictive maintenance bundles from basic management software licenses. Cost compression in the standard tier is intensifying because cloud infrastructure commoditization erodes margins for undifferentiated monitoring platforms. Small commercial portfolio operators in India exhibit highest price sensitivity, while German KfW-funded retrofit projects demonstrate lowest sensitivity due to subsidized procurement timelines.
Supply Chain Analysis
Certification against EU Green Deal efficiency mandates and US Department of Energy building performance standards gates vendor participation in the highest-value procurement channels. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States, creating dependencies for edge computing hardware essential to latency-sensitive demand response applications. Supply chain risk centers on single-source vulnerability for advanced AI accelerators used in refrigerant leak detection algorithms. Distribution runs through building automation OEMs and specialized energy service companies serving multi-site commercial portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HVAC solution software market functions as a cost-of-compliance story where the EU F-Gas Regulation creates a barrier-to-entry moat for vendors with certified refrigerant tracking architectures, systematically excluding non-compliant competitors from the fastest-expanding customer segments.
For Market Incumbents: Cement defensive positioning by embedding automated emissions registry API connections into core product architectures before the EU mandates expand to additional member states. Deepen backward integration into edge hardware design to reduce Taiwan semiconductor exposure that threatens fulfillment timelines for latency-sensitive control systems. Prioritize certification investment against India's BIS energy labeling norms to capture first-mover advantage as the 100 kW disclosure threshold expands. For New Entrants and Emerging Players: The pricing gap between premium predictive maintenance bundles and economy-tier monitoring licenses creates entry opportunity for mid-market SaaS providers specializing in hybrid deployment architectures. Target India's Maharashtra industrial corridor where localized software platforms face limited incumbent penetration and compressed procurement timelines under BIS mandates. Pursue white-label partnerships with European construction consortia seeking refrigerant compliance modules for design-build-operate contracts. For Investors and Strategic Acquirers: KfW funding program expansions beyond Germany's current retrofit allocations are the leading indicator that optimization tool demand will accelerate across broader EU building modernization initiatives. Long-term viability favors vendors with integrated service contract capabilities spanning software subscriptions, equipment maintenance, and energy supply. Target acquisition profiles should emphasize refrigerant analytics specialists with mandatory API connections to French, German, and Italian emissions registries.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-to-Cloud Protocol Integration | Reduces diagnostic latency for EU electricity market ancillary service participation. |
| Refrigerant Management-as-Service Launch | Positions leak detection algorithms as standalone F-Gas Regulation compliance products. |
| Digital Twin Platform Development | Compresses commissioning timelines for Dutch design-build-operate energy performance contracts. |
| Hybrid Deployment Architecture Rollout | Satisfies German KfW-funded projects requiring real-time optimization plus centralized reporting. |
| 5G Infrastructure Partnership | Unlocks demand response revenue streams through sub-second latency control loops. |
Research Methodology
Independent corroboration across facility management executives, building automation system integrators, energy service company technical directors, and commercial real estate portfolio managers underwrites the qualitative findings. Secondary validation draws from US Department of Energy building performance standard filings, EU Green Deal implementation progress reports, KfW funding disbursement records, and India BIS energy labeling registration databases. Bottom-up sizing of software subscription volumes triangulates against top-down estimates of commercial building HVAC modernization expenditure across the analysis window.
Rate-of-change decomposition separates volume effects from pricing effects across deployment model, building typology, integration complexity, and regional regulatory cluster dimensions. CAGRs derive from segment-level growth trajectories modeled against policy mandate implementation schedules and funding program renewal cycles. Forecast inputs incorporate edge computing hardware cost curves and cloud infrastructure pricing trends specific to building management system workloads.
Underlying measurement precision varies by segment; cloud-based solutions and SaaS deployment models carry tighter precision than on-premise installations where vendor reporting opacity persists. Forecasts reflect assumptions regarding KfW program continuity, EU F-Gas Regulation enforcement intensity, and semiconductor supply normalization. A model refresh is warranted upon material change in US Department of Energy building performance standard adoption timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
APAC Workforce Management Software Market
Software & Services
Global Lead Capture Software Market
Software & Services
Global Human Capital Management Software Market
Software & Services
Apache Spark Market
Software & Services
Cloud Business Process Management (BPM) Software Market
Software & Services
Quick Service Restaurants (QSR) IT Market
Software & Services
Torque Software Market
Software & Services
Global Video Streaming Software Market
Software & Services
Plant Design Software Market
Software & Services
Application Development and Deployment Software Market
Software & Services
Sales Dialer Software Market
Software & Services
BFSI Software Market
Software & Services
Automation Test Software Market
Software & Services
Global Maintenance Management Software Market
Software & Services
Gym Management Software Market
Software & Services
Recruitment Software Market